
 Brazil Cold Chain Logistics Market | 2026-2036
Brazil Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Cold Chain Logistics Market Outlook
ANVISA's updated Good Distribution Practices for temperature-sensitive pharmaceuticals is recalibrating compliance investments across Brazil's cold chain sector. Brado Logistics SA leverages its integrated port-to-warehouse network to dominate refrigerated cargo flows through Santos. Emergent Cold LatAm anchors its growth strategy on purpose-built freezer facilities in São Paulo and Minas Gerais. Friozem Armazens Frigorificos Ltda specializes in multi-temperature warehousing for regional food processors.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—maintaining ranges from deep-frozen minus 25 degrees Celsius to controlled ambient 25 degrees Celsius—required to preserve product integrity across storage, handling, and distribution. The primary purpose centers on preventing thermal degradation of pharmaceuticals, perishables, and frozen goods from manufacture through final delivery. Warehousing commands the largest share of service type revenue, driven by scarcity of certified refrigerated space in Brazil's interior states. Pharmaceuticals within product type segments attract premium margins due to ANVISA validation requirements and biologics proliferation. Monitoring Systems technology is expanding fastest as real-time traceability becomes mandatory for vaccine and insulin distribution.
ANVISA governs pharmaceutical cold chain standards through Good Distribution Practice audits, while MAPA enforces sanitary protocols for meat and dairy logistics. Brazil's Plano Nacional de Logística Sustentável incentivizes energy-efficient refrigeration retrofits, redirecting capital toward greenfield facilities with lower carbon footprints. Stakeholders must weigh compliance cost trajectories against consolidation opportunities as family-owned cold stores face capital constraints for dual-carbon and regulatory upgrades.

Market Dynamics
ANVISA's updated Good Distribution Practices mandate is forcing wholesale capital reallocation across Brazil's cold chain sector, as legacy refrigerated warehouses face compliance-driven obsolescence and certified capacity concentrates in São Paulo's logistics corridor.
Growth Catalysts
- Temperature-sensitive biologics proliferation:Pharmaceutical manufacturers are expanding refrigerated distribution networks to handle insulin, vaccines, and cell therapies requiring strict cold chain integrity from production through patient delivery.
- Plano Nacional de Logística Sustentável:Brazil's national sustainable logistics plan incentivizes energy-efficient refrigeration retrofits, redirecting investment toward greenfield facilities with lower carbon footprints and modern monitoring infrastructure.
- Port of Santos expansion:Brazil's largest container port is deepening refrigerated cargo handling capacity, drawing integrated logistics providers to cluster cold storage facilities within the southeastern corridor.
Market Restraints
- Certified warehouse scarcity:Brazil's interior states suffer from acute shortages of ANVISA-validated refrigerated space, forcing pharmaceutical distributors to absorb higher last-mile costs from coastal hubs.
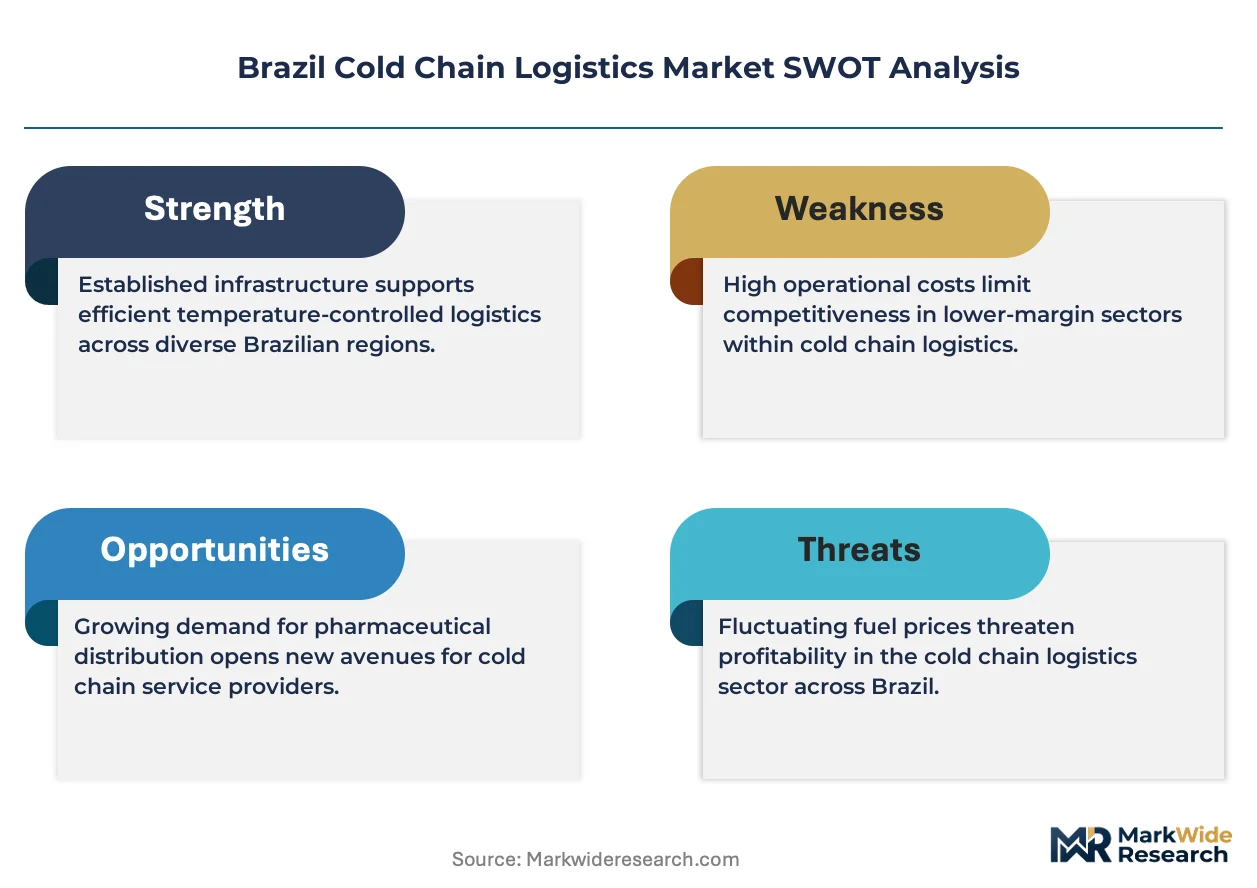
- Energy cost volatility:Diesel and electricity price fluctuations compress margins for refrigerated transport operators running continuous-cooling reefers across Brazil's vast territory.
- Dual-carbon compliance burden:Family-owned cold stores face capital constraints for simultaneous regulatory upgrades and energy-efficiency retrofits, accelerating sector consolidation.
Strategic Opportunities
- Minas Gerais penetration:Purpose-built freezer facilities in Brazil's third-largest state capture agricultural processing demand underserved by São Paulo-centric capacity.
- Real-time traceability convergence:Integration of IoT sensors with blockchain verification creates premium service tiers for vaccine and insulin distribution requiring immutable temperature records.
- Viracopos air cargo corridor:Brazil's second-busiest cargo airport offers underutilized cold chain infrastructure for temperature-sensitive pharmaceutical exports to Latin American markets.
Industry Challenges
- ANVISA validation timelines:Pharmaceutical warehouse certification cycles stretch operational planning horizons, delaying facility commissioning and revenue recognition.
- Refrigeration technician scarcity:Specialized labor pools for ammonia and CO2 refrigeration systems remain concentrated in southeastern Brazil, constraining interior expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Cold Chain Logistics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Technical Support Product Type: Pharmaceuticals, Perishables, Frozen Goods, Chemicals End User: Retailers, Distributors, Manufacturers, Hospitals Technology: Monitoring Systems, Refrigeration Units, Data Loggers, Insulated Containers |
| Companies Covered | Brado Logistics SA, Brasfrigo SA, Emergent Cold LatAm, Kuehne + Nagel, DHL Supply Chain, Friozem Armazens Frigorificos Ltda, SuperFrio Armazens Gerais Ltda, Nippon Express, Comfrio Logística, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Cold Chain Logistics Market Strategic Shifts
Digital traceability infrastructure is displacing paper-based temperature logging across Brazil's pharmaceutical cold chain, while regulatory mandates accelerate equipment modernization and energy transition investments.
IoT-enabled temperature monitoring systems are rewriting compliance economics for Brazilian pharmaceutical distributors. These platforms transmit continuous cold chain data to ANVISA audit portals, eliminating manual record-keeping labor. Large hospital networks and government vaccine programs are mandating sensor-equipped shipments, compressing adoption timelines from years to months. Real-time alerts are rewriting risk allocation between logistics providers and pharmaceutical manufacturers, shifting liability toward technology-verified performance guarantees.
ANVISA's updated Good Distribution Practices framework tightens temperature excursion documentation requirements for all pharmaceutical warehouses. The regulation mandates redundant cooling systems and automated alert protocols for facilities handling biologics. São Paulo state's concentration of certified capacity places the heaviest compliance burden on operators serving Brazil's northern and northeastern markets through extended distribution chains.
Hospital procurement departments are consolidating cold chain vendor relationships around integrated service providers offering warehousing, transport, and regulatory documentation. Single-source contracts displace fragmented arrangements with separate storage and trucking operators. This consolidation is most visible in São Paulo and Rio de Janeiro metropolitan regions, where large health systems optimize total cost of ownership across temperature-sensitive pharmaceutical spend.
Brazil Cold Chain Logistics Market Segmentation
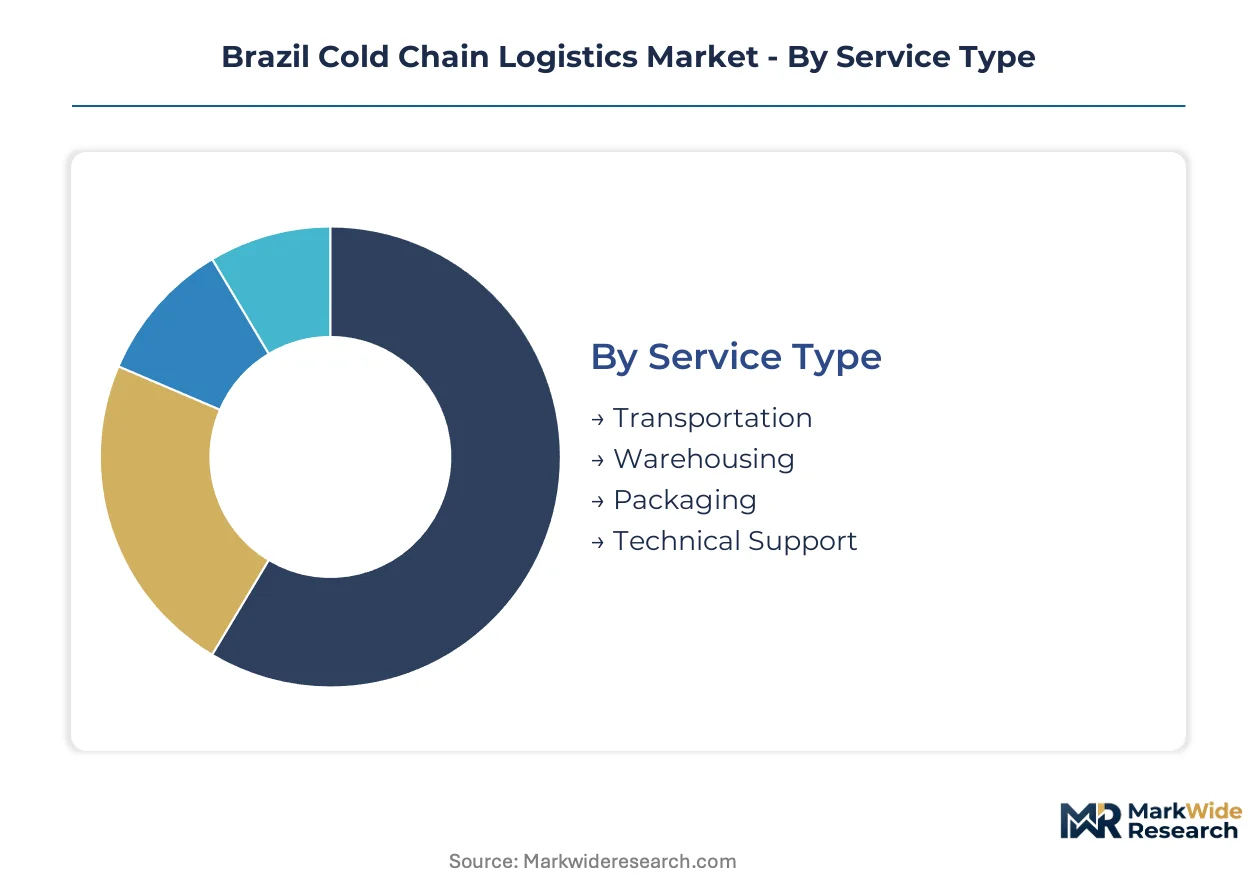
Segmentation in Brazil's cold chain logistics market reveals how regulatory certification requirements fragment service capabilities across temperature ranges and product sensitivity tiers. ANVISA validation mandates create distinct competitive moats between pharmaceutical-grade and food-grade operators.
Service Type:
ANVISA certification requirements vary sharply across service types, with pharmaceutical warehousing demanding redundant cooling systems while transportation faces diesel cost volatility.
- Warehousing:Temperature-controlled storage facilities maintain ranges from deep-frozen minus 25 degrees Celsius to controlled ambient 25 degrees Celsius. São Paulo state's southeastern logistics corridor concentrates certified refrigerated capacity near the Port of Santos and Viracopos International Airport, though interior states suffer acute ANVISA-validated space shortages that force pharmaceutical distributors to absorb higher last-mile costs from coastal hubs.
- Transportation:Continuous-cooling reefers traverse Brazil's vast territory with real-time temperature monitoring. Diesel and electricity price fluctuations compress margins for refrigerated transport operators running long-haul distribution chains from southeastern manufacturing centers to northern and northeastern consumption markets.
- Packaging:Insulated shippers and phase-change materials protect temperature-sensitive payloads during transit gaps. Food processors and regional distributors rely on multi-temperature packaging solutions for last-mile delivery where mechanical refrigeration proves uneconomical.
- Technical Support:Specialized labor pools for ammonia and CO2 refrigeration systems remain concentrated in southeastern Brazil, constraining interior expansion and maintenance response times for remote facilities.
Warehousing sits at the top of the volume ranking, with technical support climbing the fastest as ANVISA mandates deepen compliance complexity.
Product Type:
Margin structures diverge dramatically across product types, with biologics commanding premium pricing against commodity frozen goods.
- Pharmaceuticals:Temperature-sensitive biologics including insulin, vaccines, and cell therapies require strict cold chain integrity from production through patient delivery. ANVISA's updated Good Distribution Practices mandate redundant cooling systems and automated alert protocols, tightening compliance requirements nationwide and accelerating consolidation among family-owned cold stores facing capital constraints.
- Perishables:Fresh meat, dairy, and produce categories fall under MAPA sanitary protocol enforcement with shorter temperature excursion windows. Brazil's agricultural processing belt in Minas Gerais generates concentrated demand for rapid chilling and controlled atmosphere storage.
- Frozen Goods:Deep-frozen commodities at minus 25 degrees Celsius serve retail and foodservice channels with lower certification barriers. Purpose-built freezer facilities in São Paulo and Minas Gerais capture volume from protein exporters and import distributors.
- Chemicals:Industrial temperature-sensitive inputs require specialized handling protocols distinct from food and pharmaceutical standards. Chemical manufacturers integrate captive cold storage with production facilities to maintain batch integrity.
Pharmaceuticals capture the steepest expansion trajectory as biologics proliferation reshapes distribution network requirements.
End User:
Procurement centralization patterns vary by end user scale, with large hospital networks consolidating vendor relationships around integrated service providers.
- Hospitals:Large health systems in São Paulo and Rio de Janeiro metropolitan regions are mandating sensor-equipped shipments and consolidating cold chain vendor relationships around single-source contracts offering warehousing, transport, and regulatory documentation.
- Retailers:Supermarket chains and e-commerce grocery platforms demand multi-temperature last-mile capabilities with real-time visibility.
- Distributors:Pharmaceutical and food wholesale intermediaries bridge manufacturer production schedules with fragmented retail and institutional demand.
- Manufacturers:Biologics producers and processed food companies operate captive cold storage at production sites with third-party overflow arrangements.
Manufacturers anchor current volume, while hospitals are gaining share fastest through procurement consolidation mandates.
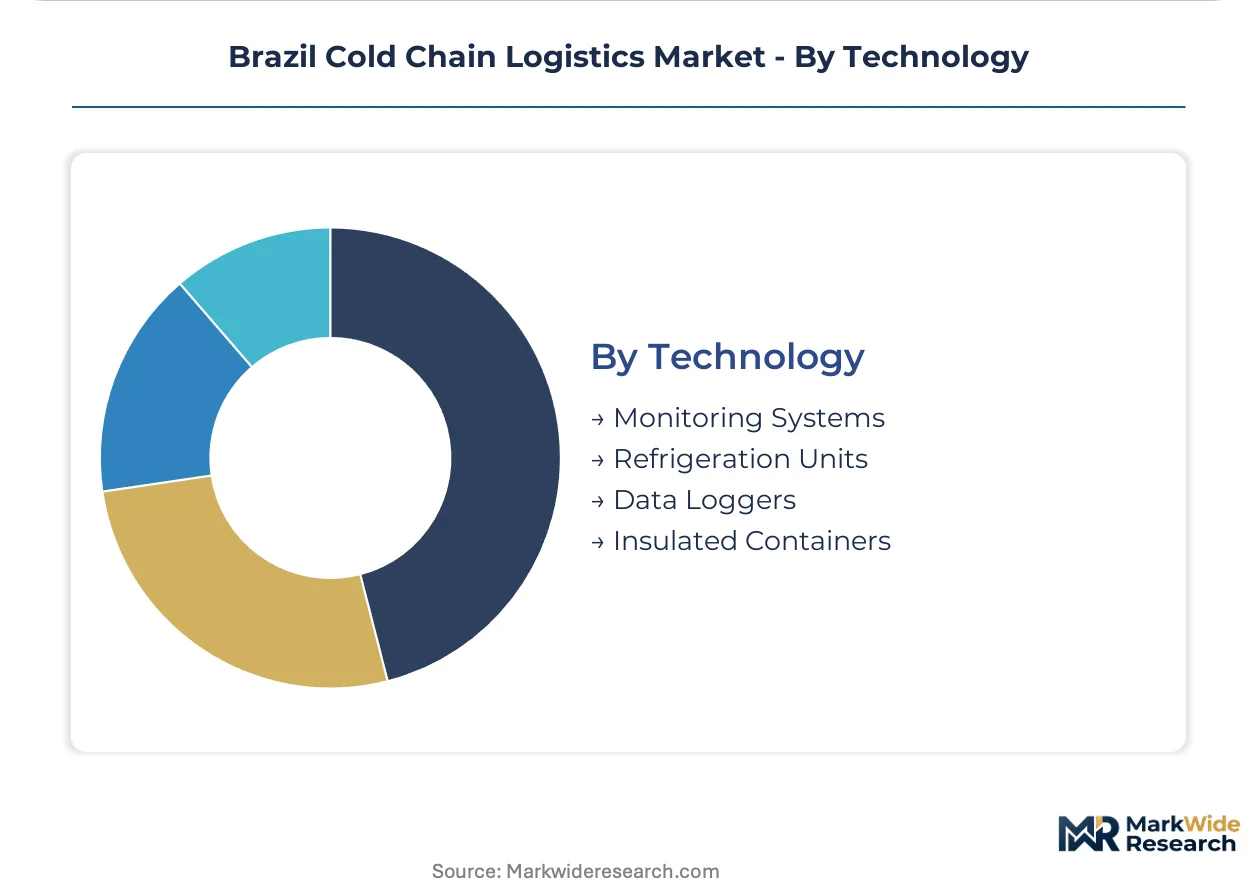
Technology:
Capital allocation across technology segments reflects regulatory pressure for immutable temperature records and energy transition requirements.
- Monitoring Systems:IoT-enabled platforms transmit continuous cold chain data to ANVISA audit portals, eliminating manual record-keeping labor. Government vaccine programs and large hospital networks are compressing adoption timelines from years to months through mandatory sensor-equipped shipment requirements.
- Refrigeration Units:Energy-efficient ammonia and CO2 systems dominate new greenfield construction under Brazil's Plano Nacional de Logística Sustentável incentives for lower carbon footprints.
- Data Loggers:Portable temperature recording devices provide backup verification for regulatory documentation during transport segments.
- Insulated Containers:Passive thermal protection systems serve short-duration shipments and last-mile delivery where active refrigeration proves impractical.
Refrigeration units maintain volume leadership, with monitoring systems expanding most quickly as real-time traceability becomes mandatory for vaccine and insulin distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's cold chain logistics industry traces its modern origins to São Paulo state's agricultural export boom of the 1960s, when refrigerated warehousing first clustered around the Port of Santos to handle coffee and meat shipments. This southeastern corridor remains the operational core, though regulatory mandates and biologics demand are redrawing investment maps toward interior states and secondary hubs.
São Paulo
Pharmaceutical distribution and protein exports drive capacity concentration in Brazil's wealthiest state. ANVISA's updated Good Distribution Practices mandate accelerates warehouse certification cycles, forcing legacy operators toward redundant cooling retrofits. The Santos-Viracopos logistics belt hosts the densest cluster of validated refrigerated space, serving as the national gateway for temperature-sensitive imports and exports.
Minas Gerais
Dairy processing and meatpacking generate concentrated demand for rapid chilling and deep-frozen storage in Brazil's third-largest state. MAPA sanitary protocol enforcement tightens temperature excursion windows for agricultural commodities. Purpose-built freezer facilities in Belo Horizonte's industrial periphery capture overflow demand underserved by São Paulo-centric capacity.
Rio Grande do Sul
Poultry and pork exports from Brazil's southernmost state require continuous-cooling reefer corridors to Porto Alegre and Itajaí ports. The Plano Nacional de Logística Sustentável incentivizes energy-efficient ammonia refrigeration retrofits in aging facilities. Rio Grande do Sul's meatpacking belt is consolidating cold storage ownership as family-owned operators face dual-carbon and compliance capital constraints.
Paraná
Soybean logistics and frozen food distribution anchor refrigerated demand in this agricultural powerhouse. ANVISA validation timelines stretch operational planning horizons for pharmaceutical distributors serving Curitiba's health system procurement networks. The state's central location positions it as a transshipment node between São Paulo capacity and southern production zones.
Bahia
Fruit exports and regional pharmaceutical distribution create fragmented cold chain requirements in Brazil's northeastern economic hub. Certified warehouse scarcity forces distributors to absorb higher last-mile costs from southeastern coastal hubs. Salvador's port modernization is drawing speculative cold storage investment targeting African export corridors.
Brazil Cold Chain Logistics Market Competitive Environment
Premium-margin players sit above commodity-margin players across ANVISA certification tiers, with validated pharmaceutical-grade operators commanding pricing power over standard food-grade facilities. The market structure reflects moderate consolidation at the top tier alongside persistent fragmentation among regional cold store operators. Three archetypes dominate: integrated port-to-warehouse networks, specialized pharmaceutical validators, and multi-temperature food logistics providers. Competitive dynamics center on M&A-driven consolidation of family-owned assets and greenfield capacity expansion in underserved interior states.
Among Brazil-based operators, Brado Logistics SA occupies a position within the integrated infrastructure archetype, leveraging port-adjacent assets. Emergent Cold LatAm exemplifies the purpose-built freezer facility model with southeastern concentration. Friozem Armazens Frigorificos Ltda represents the regional multi-temperature specialist serving food processors. Global forwarders Kuehne + Nagel and DHL Supply Chain anchor the international pharmaceutical validation tier, while Brasfrigo SA and SuperFrio Armazens Gerais Ltda sit within the domestic consolidation target pool.
| Leading Market Players |
|---|
| Brado Logistics SA |
| Brasfrigo SA |
| Emergent Cold LatAm |
| Kuehne + Nagel |
| DHL Supply Chain |
| Friozem Armazens Frigorificos Ltda |
| SuperFrio Armazens Gerais Ltda |
| Nippon Express |
| Comfrio Logística |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across port-to-warehouse networks anchors pricing power for Brazil's cold chain operators, as ANVISA certification requirements and coastal capacity concentration create dual barriers that protect validated facilities from price erosion while exposing interior distributors to cost absorption.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-validated pharmaceutical warehouses from MAPA-compliant food-grade facilities and uncertified ambient storage. Price differentiation rests on certification grade and geographic delivery cost, with São Paulo corridor operators commanding substantial premiums over interior states. Cost compression in economy-tier frozen goods is intensifying because diesel volatility and electricity spikes compress reefer margins. Food processors and regional distributors exhibit highest price sensitivity, while large hospital networks in metropolitan São Paulo and Rio de Janeiro show lowest sensitivity due to procurement consolidation mandates.
Supply Chain Analysis
Regional distribution centers in São Paulo state's southeastern logistics corridor anchor Brazil's cold chain map, with satellite facilities in Minas Gerais and Paraná forming secondary hubs. Supply draws from ammonia and CO2 refrigeration equipment manufacturers in southeastern Brazil, diesel and electricity providers across the national grid, and specialized technician labor pools concentrated near Santos and Viracopos. Single-source vulnerability runs through certified warehouse scarcity in interior states, forcing extended distribution chains from coastal hubs. Distribution runs through hub-and-spoke patterns radiating from São Paulo toward northern and northeastern consumption markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's cold chain logistics market reads as a late-cycle quality story, with temperature-sensitive biologics proliferation shifting procurement specifications toward premium ANVISA-validated capacity and real-time traceability infrastructure.
For Market Incumbents: Hedge against regulatory obsolescence by accelerating redundant cooling retrofits in legacy facilities before ANVISA validation timelines extend further. Consolidate family-owned cold store assets in Minas Gerais and Paraná to capture agricultural processing demand underserved by São Paulo-centric capacity. Certification investment represents the priority defensive lever against margin compression from energy cost volatility.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium pharmaceutical-grade and economy frozen-goods facilities offers white-space entry for multi-temperature specialists targeting regional food processors in Brazil's interior states. Viracopos air cargo corridor infrastructure remains underutilized for temperature-sensitive pharmaceutical exports to Latin American markets. A go-to-market angle anchored on IoT-enabled monitoring systems with blockchain verification addresses hospital procurement mandates for immutable temperature records.
For Investors and Strategic Acquirers: Roll-up economics work for platform consolidation of family-owned cold stores because dual-carbon compliance and ANVISA upgrade capital constraints force distressed exits across Brazil's interior states. Long-term viability favors operators with integrated port-to-warehouse networks and validated pharmaceutical capacity. The signal to watch is ANVISA audit portal adoption timelines compressing from years to months, indicating technology-verified performance guarantees displacing manual compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Redundant cooling retrofits and automated alert protocols protect pharmaceutical-grade pricing power against regulatory obsolescence. |
| Greenfield Facility Expansion | Plano Nacional de Logística Sustentável incentives redirect capital toward energy-efficient ammonia and CO2 systems in Minas Gerais. |
| IoT Monitoring Platform Integration | Real-time traceability convergence with blockchain verification creates premium service tiers for vaccine and insulin distribution mandates. |
| Regional Cold Store Acquisition | Consolidation of family-owned assets in Paraná and Bahia captures transshipment demand between São Paulo capacity and interior markets. |
| Viracopos Air Cargo Corridor Development | Underutilized cold chain infrastructure offers export positioning for temperature-sensitive biologics to Latin American markets. |
Study Parameters
Direct dialogue with cold chain operations directors, pharmaceutical distribution executives, ANVISA compliance officers, hospital procurement managers, and refrigerated transport fleet operators grounded qualitative findings. Secondary validation drew from ANVISA audit portal disclosures, MAPA sanitary protocol enforcement records, Plano Nacional de Logística Sustentável policy documents, and customs trade data for refrigerated cargo flows. Bottom-up facility capacity assessments and top-down pharmaceutical spend analysis provided triangulation across the analysis window.
Bottom-up modeling segmented revenue by service type, product temperature sensitivity tier, end-user procurement scale, and monitoring technology adoption stage. Top-down validation cross-referenced pharmaceutical biologics pipeline expansion against certified warehouse stock across São Paulo, Minas Gerais, Rio Grande do Sul, Paraná, and Bahia. CAGRs derived from facility commissioning timelines, ANVISA validation cycle durations, and energy transition investment curves. Forecast inputs incorporated diesel-electricity price correlation patterns and IoT sensor penetration rates in government vaccine programs.
The model assumes a particular technology adoption path; alternative pathways for blockchain-verified temperature logging would alter the outlook if regulatory mandates accelerate faster than infrastructure deployment. Forecasts reflect stated assumptions around ANVISA audit portal integration timelines and Plano Nacional de Logística Sustentável incentive continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Refrigerated Trailer Market