
 Spain Road Freight Transport Market | 2026-2036
Spain Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Road Freight Transport Market Analytics
The capability gap between asset-heavy fleet operators and digital-first intermediaries is bifurcating competitive dynamics across Spanish road freight. DSV A/S leverages its integrated European network to control cross-border flows into Iberia. Marcotran Transportes Internacionales S L anchors its position through specialized heavy-haulage capacity across the peninsula. Grupo Sese competes via temperature-controlled expertise linking Almería's agricultural output to Northern European retail channels.
Spain road freight transport encompasses the movement of goods by motorized vehicles over the national road network, utilizing heavy-duty trucks with gross vehicle weights exceeding 16 tonnes for long-haul routes and lighter configurations for urban distribution. The sector functions as the dominant mode for domestic cargo movement, handling manufactured goods, perishables, and construction materials across a radial infrastructure pattern centered on Madrid. Full truckload services dominate volume flows along the Mediterranean and Atlantic corridors, while less-than-truckload networks capture margin pools through consolidated urban deliveries to manufacturing and retail endpoints. Refrigerated trucks represent the fastest-expanding vehicle category, driven by pharmaceutical cold-chain requirements and fresh produce exports from Andalusia and Murcia.
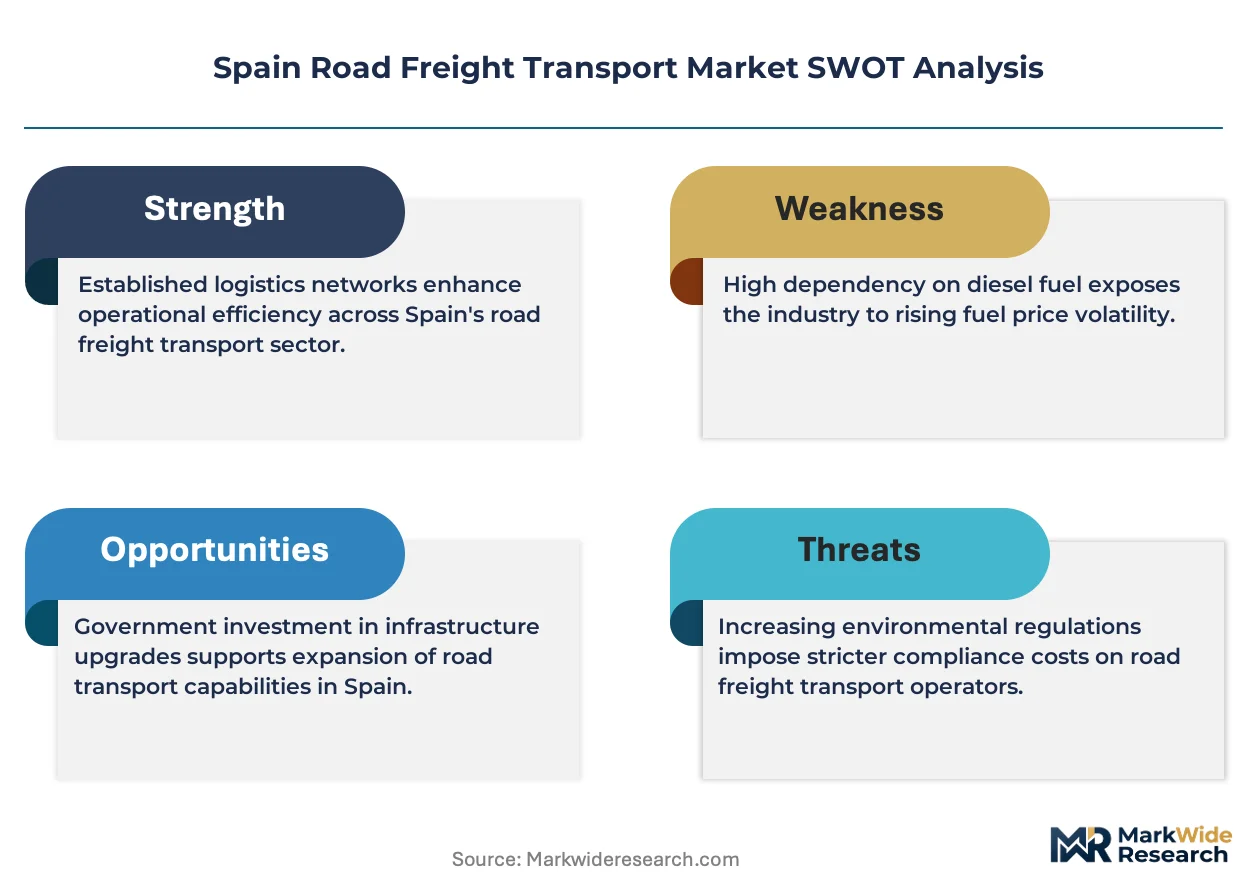
Spain's Directorate-General for Traffic enforces EU-mandated driving hours and tachograph compliance, while the Spanish Ministry of Transport and Sustainable Mobility implements the national alternative fuels infrastructure plan aligned with EU Green Deal targets. These frameworks elevate operating costs for diesel-dependent fleets while creating market access advantages for operators investing in liquefied natural gas and electric vehicle trials. Stakeholders must weigh fleet renewal timelines against the uncertain pace of charging and refueling infrastructure deployment along major freight corridors.
Market Dynamics
The EU Green Deal's Fit for 55 framework is compressing fleet renewal timelines while alternative fuel infrastructure deployment lags across Spanish freight corridors, forcing operators to balance compliance costs against uncertain asset utilization.
Growth Catalysts
- EU Green Deal emission mandates:The Fit for 55 package tightens CO2 standards for heavy-duty vehicles, creating regulated demand pull for LNG and electric truck adoption across Iberian distribution networks.
- E-commerce fulfillment density:Last-mile delivery volumes from Madrid and Barcelona metropolitan zones are expanding consolidated urban distribution requirements for temperature-sensitive and time-definite cargo.
- Andalusian agricultural exports:Almería's greenhouse production clusters generate year-round refrigerated truck demand linking Spanish produce to Northern European retail channels through dedicated cold-chain capacity.
Market Restraints
- Diesel price volatility:Fuel cost swings compress operating margins for asset-heavy operators running Euro VI diesel fleets across long-haul peninsula routes.
- Charging infrastructure gaps:Sparse electric truck charging deployment along the A-1 and AP-7 corridors limits viable range for battery-electric heavy-duty vehicles.
- Driver availability constraints:Spain's Directorate-General for Traffic enforces strict tachograph compliance and rest-period regulations that tighten qualified driver supply.
Strategic Opportunities
- Port-centric intermodal integration:Valencia and Barcelona container terminals offer rail-road transshipment potential for reducing carbon-intensive long-haul trucking segments.
- Pharmaceutical cold-chain specialization:Temperature-controlled transport for biologics and vaccines commands premium pricing through validated GDP compliance.
- Digital freight matching platforms:Real-time load-board algorithms reduce empty backhaul kilometers for small and mid-sized fleet operators.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly retrofitting to interface with EU-mandated smart tachograph Generation 2 devices.
- Alternative fuel technician scarcity:LNG and hydrogen propulsion maintenance demands specialized training programs that Spanish vocational institutions have yet to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Road Freight Transport Market |
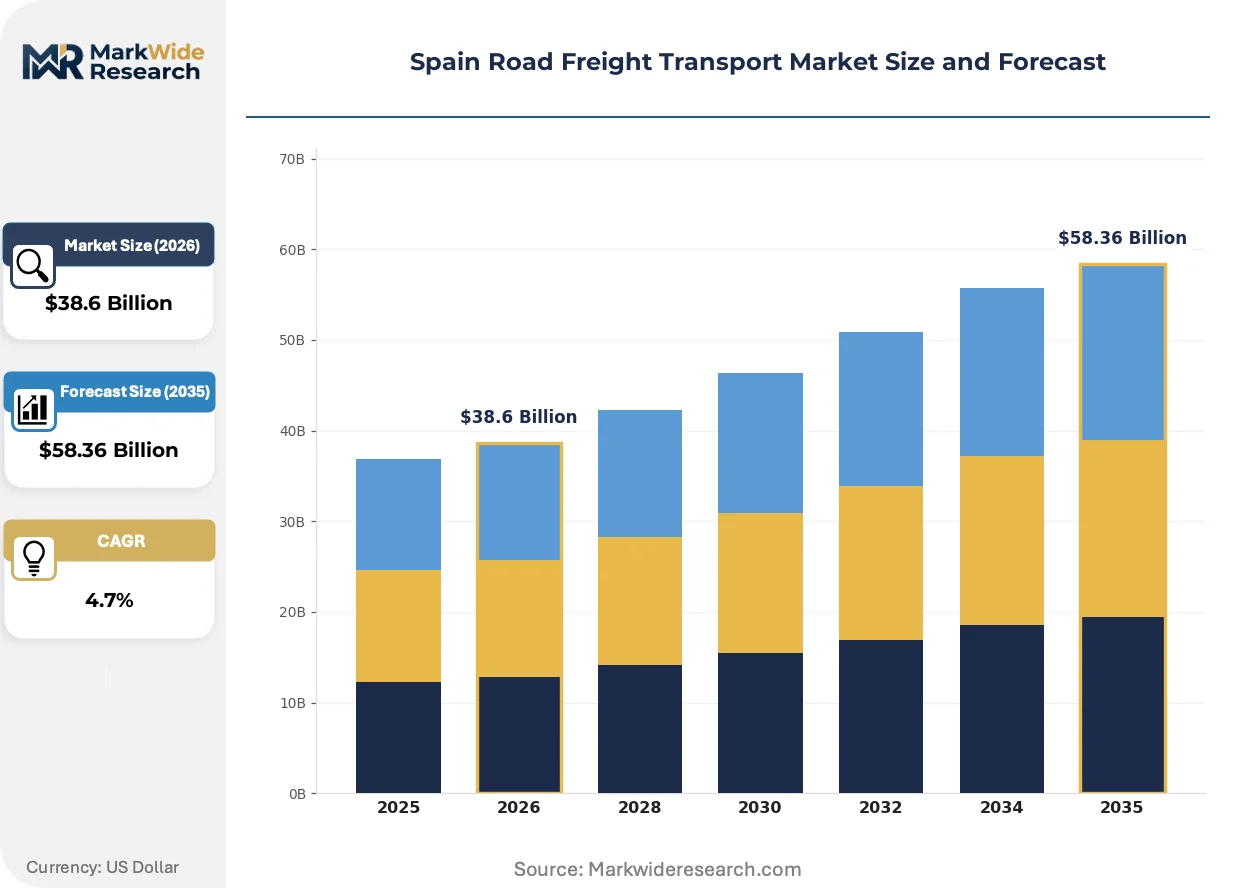
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Intermodal, Dedicated Vehicle Type: Heavy Duty Trucks, Light Duty Trucks, Refrigerated Trucks, Flatbed Trucks End User: Retail, Manufacturing, Construction, E-Commerce Delivery Model: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Regular Freight |
| Companies Covered | DSV A/S, Trans Sese SL, XPO Inc, Primafrio, Grupo Sese, DB Schenker, Dachser, Marcotran Transportes Internacionales S L, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Road Freight Transport Market Evolving Landscape
Telematics and predictive routing algorithms are compressing traditional dispatch hierarchies while the EU Green Deal accelerates powertrain diversification beyond diesel dependency.
Platooning and cooperative adaptive cruise control systems are bifurcating fleet investment strategies. Large operators with dedicated lane density are piloting truck convoy automation on the Madrid-Barcelona corridor. This technology is bifurcating competitive positioning between capital-intensive early adopters and smaller fleets locked into conventional asset models.
The EU Green Deal's Fit for 55 framework mandates 45% CO2 reduction for heavy-duty vehicles by 2030. Spain's Ministry of Transport and Sustainable Mobility aligns national alternative fuels infrastructure deployment with these binding targets. Refrigerated transport operators face disproportionate compliance pressure due to auxiliary power unit energy demands.
Shippers are consolidating vendor relationships toward integrated logistics providers offering carbon-accounted freight services. Traditional spot-market brokerage loses share to contracted emission-reporting partnerships. This concentration is most visible among German retail chains sourcing fresh produce through Almería corridor operators.
Spain Road Freight Transport Market Segmentation
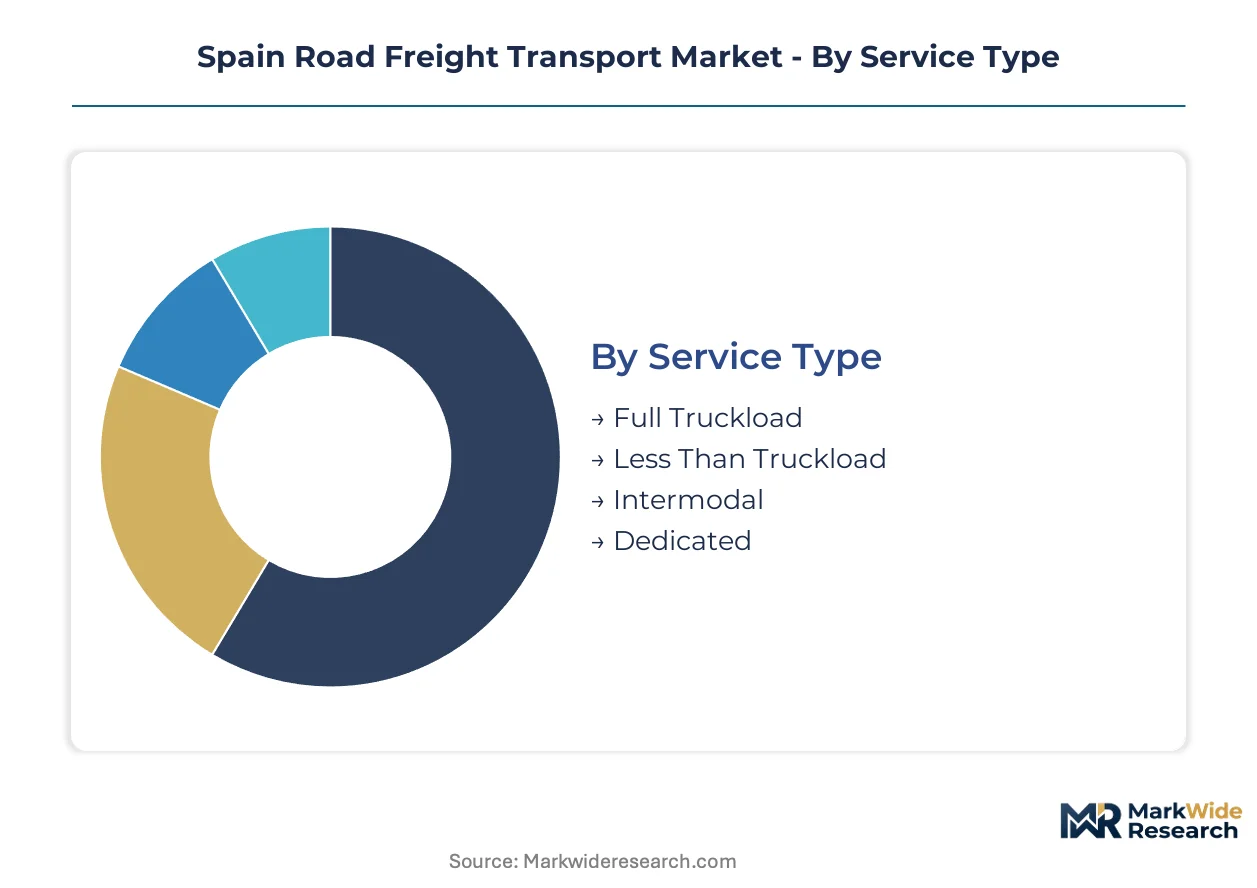
Service configurations in Spanish road freight reflect the radial infrastructure pattern centered on Madrid, with corridor density and cargo characteristics determining which operational models capture margin. Segment boundaries blur as integrated operators bundle multiple service tiers under single contracts.
Service Type:
Domestic peninsula flows favor asset-heavy dedicated contracts, while export corridors into France and Portugal drive demand for flexible less-than-truckload consolidation.
- Full Truckload:Single-shipper cargo fills entire tractor-trailer units, typically 24-tonne payloads moving direct from manufacturing clusters in Catalonia and the Basque Country to distribution centers. Madrid-Barcelona corridor density supports highest utilization rates for automotive parts and consumer goods.
- Less Than Truckload:Consolidated shipments from multiple shippers share trailer capacity through hub-and-spoke terminal networks. Barcelona and Valencia consolidation centers capture cross-border flows into Southern France where freight forwarding margins concentrate.
- Intermodal:Rail-road transshipment at Valencia and Barcelona container terminals reduces carbon-intensive long-haul segments for maritime import distribution.
- Dedicated:Exclusive fleet allocation for single-shipper operations, common among retail chains requiring store replenishment rhythm control.
Full Truckload holds the largest share; momentum sits with Less Than Truckload as e-commerce fragmentation increases shipment frequency.
Vehicle Type:
Cost tiers separate diesel-dependent long-haul assets from specialized temperature-controlled units commanding premium per-kilometer rates.
- Refrigerated Trucks:Insulated van bodies with integrated refrigeration units maintain controlled temperatures for pharmaceutical cold-chain and fresh produce exports from Almería's greenhouse clusters to Northern European retail channels.
- Heavy Duty Trucks:Tractor units exceeding 16 tonnes gross vehicle weight haul standard dry freight across the A-1 and AP-7 corridors, facing EU Green Deal compliance pressure for fleet renewal.
- Light Duty Trucks:Urban delivery vehicles under 7.5 tonnes navigate Madrid and Barcelona metropolitan restrictions on heavy vehicle access.
- Flatbed Trucks:Open-deck configurations transport construction materials and oversized machinery across peninsula infrastructure projects.
Heavy Duty Trucks dominate fleet composition; Refrigerated Trucks are expanding most quickly on agricultural export demand.
End User:
Customer concentration varies by margin structure, with manufacturing and retail anchoring contracted volume while construction and e-commerce drive spot-market volatility.
- Retail:Scheduled replenishment of store networks requires reliable lead-time performance, favoring dedicated contract relationships over transactional spot markets.
- Manufacturing:Just-in-time component delivery from supplier parks to assembly plants demands precise arrival windows, common in automotive supply chains around Martorell and Vitoria-Gasteiz.
- E-Commerce:Fragmented last-mile delivery requirements from Madrid and Barcelona fulfillment centers generate high-frequency small-lot movements.
- Construction:Project-based bulk material transport exhibits seasonal demand swings tied to infrastructure spending cycles.
Manufacturing holds the largest share; E-Commerce is climbing the fastest on fulfillment center expansion.
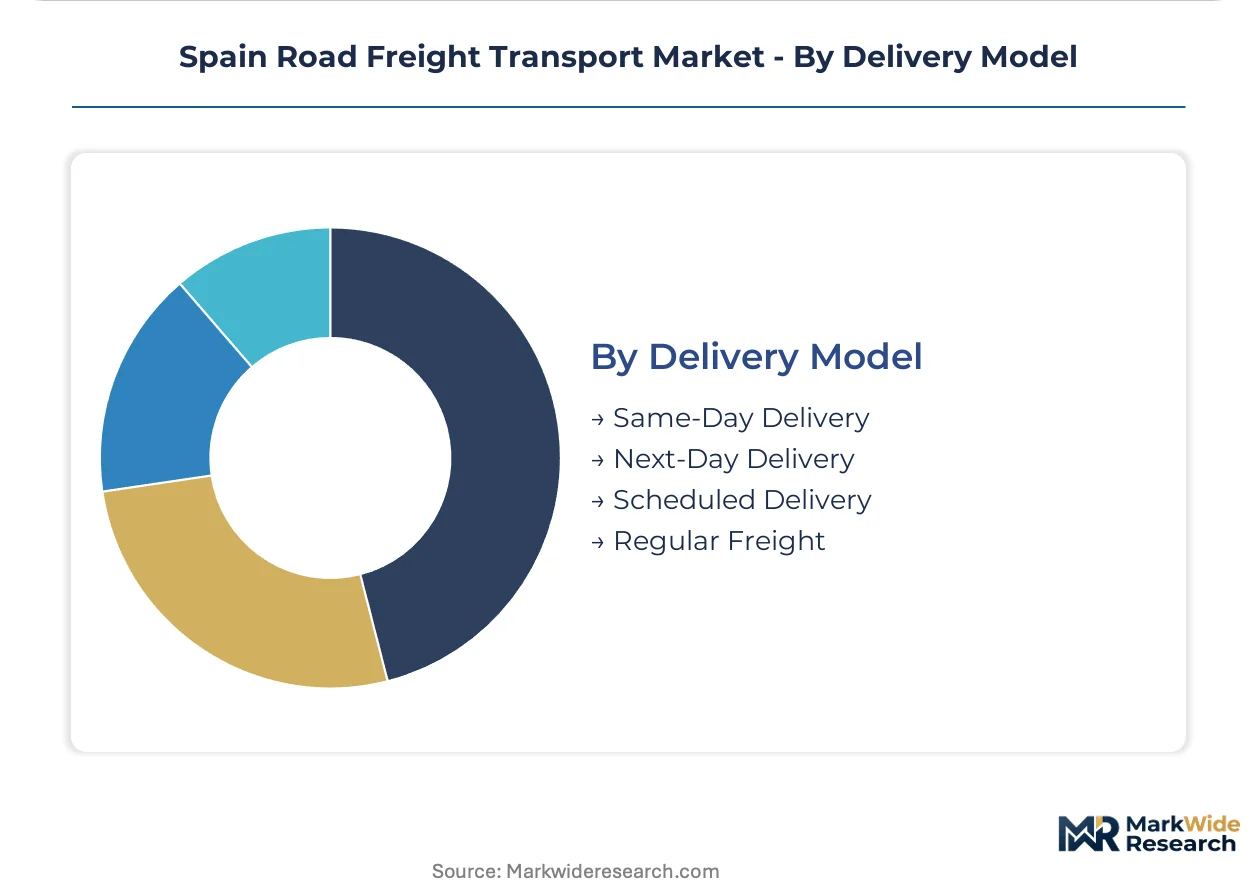
Delivery Model:
Speed premiums stratify pricing, with same-day and next-day services capturing urban density while scheduled delivery optimizes rural route efficiency.
- Scheduled Delivery:Pre-planned routes with fixed delivery windows maximize vehicle utilization for B2B manufacturing and retail replenishment flows.
- Next-Day Delivery:Time-definite service guarantees within 24 hours command premium pricing for consumer electronics and fashion distribution from Barcelona logistics zones.
- Same-Day Delivery:Urgent urban courier services limited to Madrid and Barcelona metropolitan radii where warehouse density supports rapid fulfillment.
- Regular Freight:Non-expedited standard transit times offer lowest cost per kilogram for non-time-sensitive cargo.
Scheduled Delivery holds the largest share; Next-Day Delivery shows the steepest expansion trajectory on omnichannel retail requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Madrid-Barcelona corridor commands premium freight rates that outpace Andalusian agricultural lanes by double-digit margins, while Basque manufacturing clusters generate the densest dedicated contract coverage in Iberia.
Madrid
The capital's radial highway network funnels automotive parts from supplier parks to assembly plants across Castile. Spain's Ministry of Transport and Sustainable Mobility channels alternative fuels infrastructure investment through the MOVES III program. The Corredor del Henares logistics belt east of Madrid concentrates e-commerce fulfillment centers driving last-mile density.
Catalonia
Barcelona's port connectivity and French border proximity generate cross-border LTL consolidation demand for consumer goods. The EU Green Deal's Fit for 55 framework pressures fleet operators serving the AP-7 corridor toward LNG adoption. The Zona Franca industrial estate anchors temperature-controlled exports to Northern European retail channels.
Basque Country
Automotive component flows from Vitoria-Gasteiz and Bilbao manufacturing clusters sustain the highest full-truckload utilization rates in Spain. The country's Directorate-General for Traffic enforces strict tachograph compliance on routes linking Gipuzkoa supplier parks. The Port of Bilbao offers rail-road transshipment for reducing carbon-intensive long-haul segments.
Andalusia
Almería's greenhouse agriculture generates year-round refrigerated truck demand for fresh produce exports. Spain's national alternative fuels infrastructure plan lags in southern corridors, extending diesel fleet dependence. The Campo de Dalías concentration of horticultural operations commands dedicated cold-chain capacity to Northern European markets.
Valencia
The Mediterranean port city's container terminal traffic drives intermodal rail-road integration for maritime import distribution. EU emissions standards for heavy-duty vehicles accelerate fleet renewal timelines for operators serving the Levante corridor. The Parc Logístic de Valencia consolidates retail replenishment flows for national distribution networks.
Spain Road Freight Transport Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Spanish road freight. Integrated European logistics networks compete against peninsula-specialized fleet operators for cross-border flows. Three archetypes dominate: asset-heavy dedicated contract carriers, digital-first freight intermediaries, and temperature-controlled specialists. Consolidation pressure favors M&A activity among mid-sized operators, while strategic partnerships with port authorities unlock intermodal positioning.
Among integrated European networks, DSV A/S and DHL Group exemplify cross-border consolidation archetypes. Marcotran Transportes Internacionales S L occupies a position within specialized heavy-haulage capacity. Grupo Sese anchors temperature-controlled expertise linking agricultural output to retail channels.
| Leading Market Players |
|---|
| DSV A/S |
| Trans Sese SL |
| XPO Inc |
| Primafrio |
| Grupo Sese |
| DB Schenker |
| Dachser |
| Marcotran Transportes Internacionales S L |
| DHL Group |
| Others |
Value Network & Pricing Analysis
Asset utilization rates above eighty percent on the Madrid-Barcelona corridor compress per-kilometer cost floors while concentrating pricing power among operators with dedicated lane density. Spain's Ministry of Transport and Sustainable Mobility channels MOVES III subsidies toward alternative fuel adoption, yet diesel-dependent mid-sized fleets face margin compression from fuel price volatility and EU Green Deal compliance timelines.
Pricing Analysis
The customization-premium spread separates dedicated contract rates from spot-market transactions by fifteen to twenty-five percent. Three-tier pricing structure across premium, standard, and economy levels reflects service reliability guarantees, temperature-control certification, and cross-border customs handling. Pricing pressure stems from German retail chains consolidating vendor relationships toward carbon-accounted freight partnerships. Small and mid-sized fleet operators exhibit highest price sensitivity due to empty backhaul exposure, while pharmaceutical shippers accept premium rates for GDP-validated cold-chain compliance.
Supply Chain Analysis
Port congestion at Valencia and Barcelona container terminals underwrites intermodal rail-road transshipment economics for maritime import distribution. Vehicle manufacturing draws from Germany, France, and Czech Republic component supplier parks. Diesel engine production rests on German and Italian powertrain engineering. Supply chain risk centers on single-source vulnerability for LNG refueling infrastructure deployment along southern corridors. Distribution runs through Madrid's radial highway network with spoke terminals in Zaragoza and Burgos consolidating northern peninsula flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and French retail chains that demand emission-accounted freight services, fragmenting spot-market brokerage relationships. This consolidation pressures mid-sized Spanish operators toward contracted partnerships or acquisition exits.
For Market Incumbents: Compound fleet renewal timelines with LNG pilot programs on the AP-7 corridor to preempt EU Green Deal compliance penalties. Deepen backward integration into Almería cold-chain warehousing to capture margin from agricultural export growth. Defensive positioning requires telematics retrofitting for Generation 2 tachograph mandates before enforcement tightens.
For New Entrants and Emerging Players: GDP certification fast-track for pharmaceutical cold-chain compliance unlocks premium pricing in a segment where incumbents carry legacy diesel fleet overhead. White-space targets include same-day delivery consolidation for Madrid e-commerce fulfillment centers and electric last-mile pilot partnerships with municipal authorities. Go-to-market positioning should emphasize carbon-accounted freight reporting aligned with German retail procurement standards.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors temperature-controlled specialists with established Northern European retail relationships over asset-heavy general freight operators. Long-term viability over a five-to-ten year window hinges on alternative fuel infrastructure deployment pace and driver availability constraints. Acquisition target archetype: refrigerated transport operators with validated cold-chain compliance and contracted produce export volumes. The signal to watch is LNG refueling station commissioning rates along the A-1 and AP-7 corridors as inflection indicator for fleet renewal economics.
| Strategic Initiative | Industry Significance |
|---|---|
| LNG Fleet Pilot Program | EU Green Deal compliance positioning on the AP-7 corridor ahead of 2030 CO2 mandates. |
| Almería Cold-Chain Warehouse Integration | Captive supply of temperature-controlled capacity for year-round agricultural export demand. |
| Digital Freight Matching Platform Launch | Real-time load-board algorithms reduce empty backhaul kilometers for mid-sized fleet operators. |
| Generation 2 Tachograph Telematics Retrofit | Spanish Directorate-General for Traffic mandates smart device compliance for cross-border operations. |
| Port-Centric Intermodal Partnership | Valencia and Barcelona rail-road transshipment reduces carbon-intensive long-haul trucking segments. |
Research Methodology
A standing panel of fleet operations directors, logistics procurement managers at German retail chains, port authority planning officers, and cold-chain compliance specialists provided ongoing calibration across the study period. Primary interviews combined with secondary validation from Spanish Ministry of Transport infrastructure deployment filings, EU Green Deal regulatory texts, and DGT tachograph enforcement statistics. Bottom-up fleet operator surveys triangulated against top-down customs trade flow data.
Consistency checks validated volume and value outputs against external benchmarks including EU transport statistics and Iberian logistics association membership data. Segmentation modeling incorporated service type, vehicle configuration, end-user industry, and corridor density dimensions across the projection horizon. CAGRs derived from logistic curve fitting to technology adoption patterns and regulatory compliance timelines. Forecast inputs included alternative fuel infrastructure deployment schedules and e-commerce fulfillment center construction pipelines.
Decision-makers should treat outputs as directional under stable EU emissions enforcement and diesel price assumptions; material deviation would warrant model refresh. Forecasts reflect base-case assumptions around driver availability and charging infrastructure rollout. Practitioners should keep alternative scenarios live as LNG refueling network density and German retail procurement standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Intermodal Freight Transportation Market