
 Fleet Management Solution Market | 2026-2036
Fleet Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Fleet Management Solution Market Analysis
Buyer concentration among mid-to-large logistics operators is expanding as fleet owners consolidate vendor relationships around unified platforms. Geotab Inc. leverages its open-platform architecture to anchor enterprise accounts across North America. Verizon Connect sustains channel dominance through bundled connectivity and telematics offerings. Samsara Inc. differentiates via AI-enabled video safety and equipment monitoring integrations.
A fleet management solution encompasses hardware, software, and communication systems that collect vehicle location, engine diagnostics, driver behavior, and asset status data through GPS receivers, OBD-II ports, and cellular or satellite modems, then processes this information via cloud or on-premises servers to optimize routing, maintenance, compliance, and fuel consumption. Cloud-based deployment now leads adoption due to lower upfront infrastructure costs and faster scaling across distributed operations. Route optimization and fuel management solutions capture disproportionate margin pools as diesel price volatility and emissions compliance intensify operational pressure. Telematics and IoT technologies are displacing standalone GPS tracking as fleets demand predictive maintenance and real-time cargo condition monitoring.
The EPA's Phase 3 greenhouse gas standards and the DOT's electronic logging device mandate shape product requirements and market access for solution providers serving US commercial fleets. The FCC governs spectrum allocation for cellular and satellite communication modules embedded in telematics hardware, directly affecting device certification timelines. Stakeholders must monitor evolving state-level zero-emission vehicle mandates and weigh in-house platform development against partnerships with established telematics infrastructure providers.
Market Dynamics
Logistics operators are consolidating fragmented point solutions into unified cloud-based telematics platforms as diesel price volatility and EPA Phase 3 emissions standards intensify pressure on fuel efficiency and route optimization.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Heavy-duty fleet operators across the United States are accelerating deployment of fuel management systems to meet stringent emissions thresholds and avoid regulatory penalties.
- Telematics-IoT convergence:Predictive maintenance capabilities powered by real-time engine diagnostics and cargo condition monitoring are pulling fleet owners away from standalone GPS tracking.
- Cloud migration:Lower upfront infrastructure costs and faster scaling across distributed operations are driving mid-to-large logistics operators toward SaaS-based fleet architectures.
Market Restraints
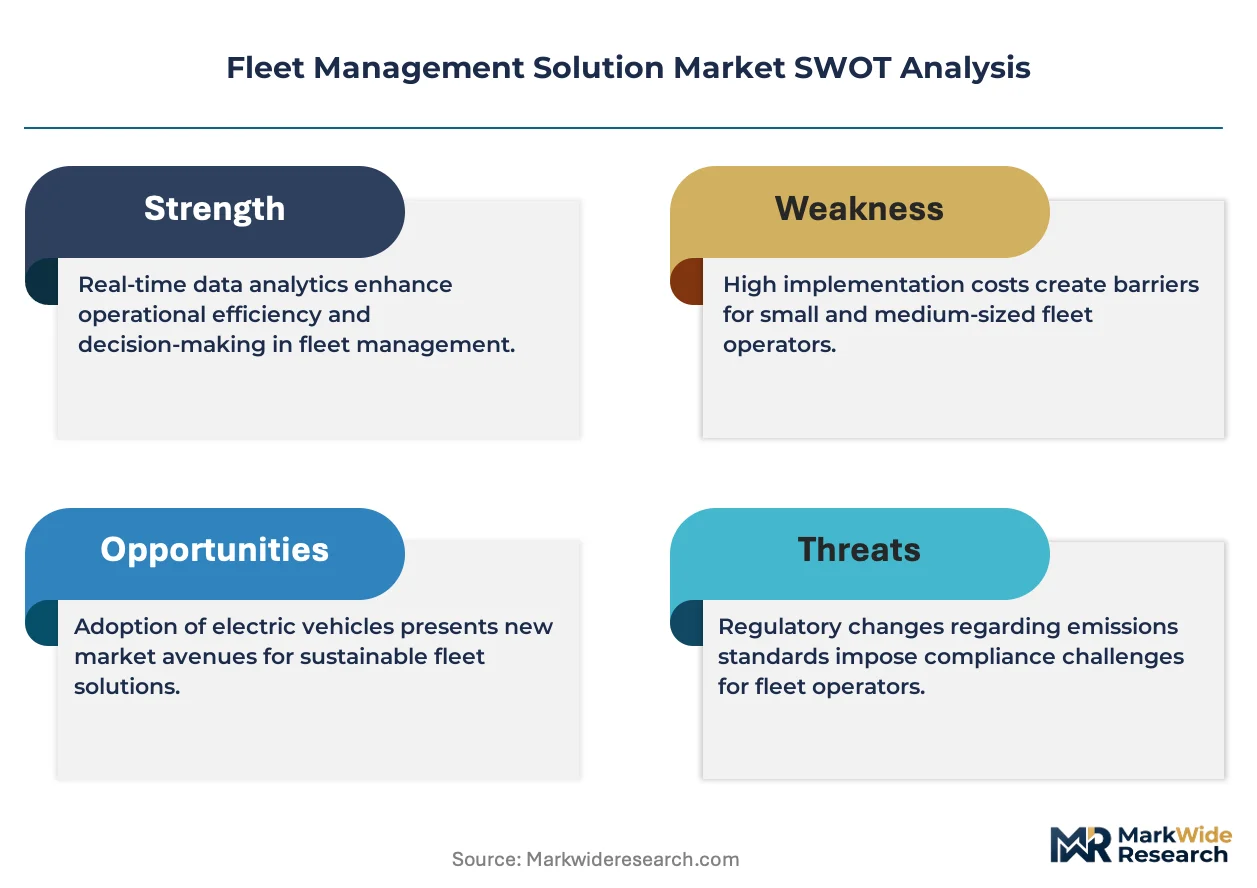
- Cellular module supply concentration:FCC certification timelines for telematics hardware create bottlenecks when semiconductor foundry capacity tightens in East Asian manufacturing hubs.
- Legacy system integration friction:Fleet operators running decades-old dispatch software face prohibitive data migration costs when adopting unified platforms.
- Diesel-electric total cost parity gaps:Battery-electric commercial vehicles remain uneconomical for long-haul routes, limiting the addressable market for EV-optimized fleet solutions.
Strategic Opportunities
- State-level zero-emission mandates:California's Advanced Clean Trucks regulation and similar state programs are creating regulated demand for electric fleet transition planning tools.
- AI-enabled video safety:Computer vision integration with driver behavior analytics represents an underpenetrated upsell path within existing telematics accounts.
- Equipment monitoring convergence:Construction and agricultural machinery fleets present adjacent revenue pools for providers with proven heavy-asset tracking capabilities.
Industry Challenges
- Telematics data science talent scarcity:Fleet operators struggle to hire analysts capable of extracting actionable insights from high-velocity vehicle sensor streams.
- Multi-vendor integration complexity:Unified platforms must reconcile incompatible data formats from disparate ELD, fuel card, and maintenance systems already deployed across customer fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fleet Management Solution Market |
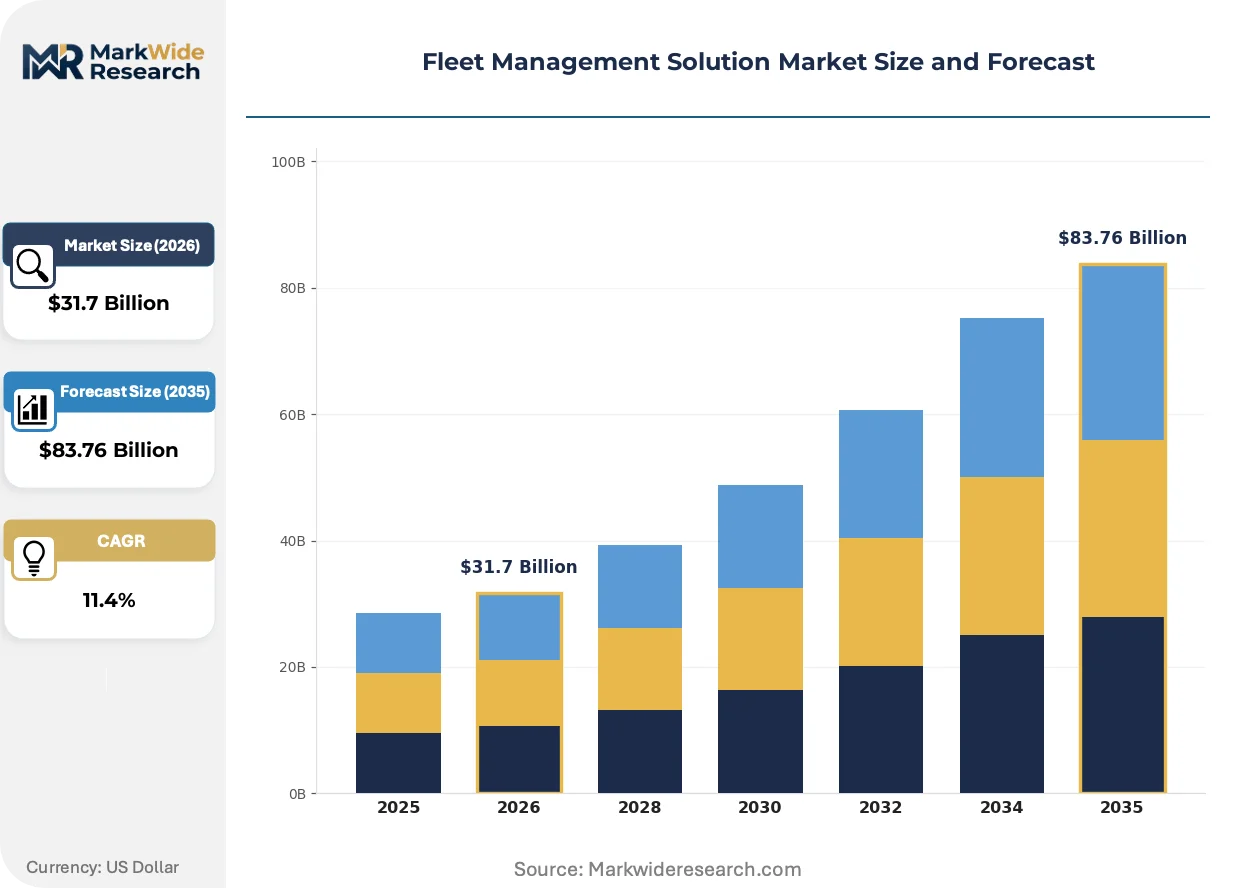
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $83.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solution: Route Optimization, Asset Tracking, Fuel Management, Maintenance Scheduling End User: Transportation, Logistics, Construction, Emergency Services Technology: Telemetry, GPS Tracking, Telematics, IoT Solutions |
| Companies Covered | Geotab Inc., Verizon Connect, Samsara Inc., Trimble Inc., Omnitracs LLC, PowerFleet Inc., MiX Telematics Ltd., Teletrac Navman, Fleet Complete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fleet Management Solution Market Emerging Trajectories
Artificial intelligence and edge computing are reshaping how fleet data is processed, with real-time decision-making moving from cloud servers to vehicle-mounted hardware. Regulatory pressure on emissions and safety is simultaneously accelerating hardware refresh cycles.
Edge AI inference engines mounted directly on commercial vehicles are converging with 5G connectivity modules to enable millisecond-latency hazard detection and autonomous emergency braking. Large for-hire trucking fleets are piloting these systems on high-frequency routes between distribution centers. The technology is converging with traditional telematics to compress insurance premium differentiation and reshape vendor competitive positioning around safety outcomes rather than mere tracking accuracy.
The DOT's electronic logging device mandate has hardened compliance requirements around hours-of-service documentation, forcing smaller carriers to upgrade from paper logbooks or basic AOBRDs. This regulatory friction is compressing the long tail of non-compliant operators and accelerating platform consolidation. Regional LTL carriers operating across multiple states face the steepest adaptation costs as they reconcile varying intrastate enforcement intensities.
Subscription-based fleet software procurement is displacing perpetual license purchases as logistics CFOs prioritize operational expenditure predictability over capital deployment. Third-party logistics providers and dedicated contract carriage operators are leading this shift, demanding usage-based pricing tied to active vehicle counts. The pattern is most visible among mid-sized fleets with 50-500 power units seeking to align technology costs with revenue volatility.
Fleet Management Solution Market Segmentation
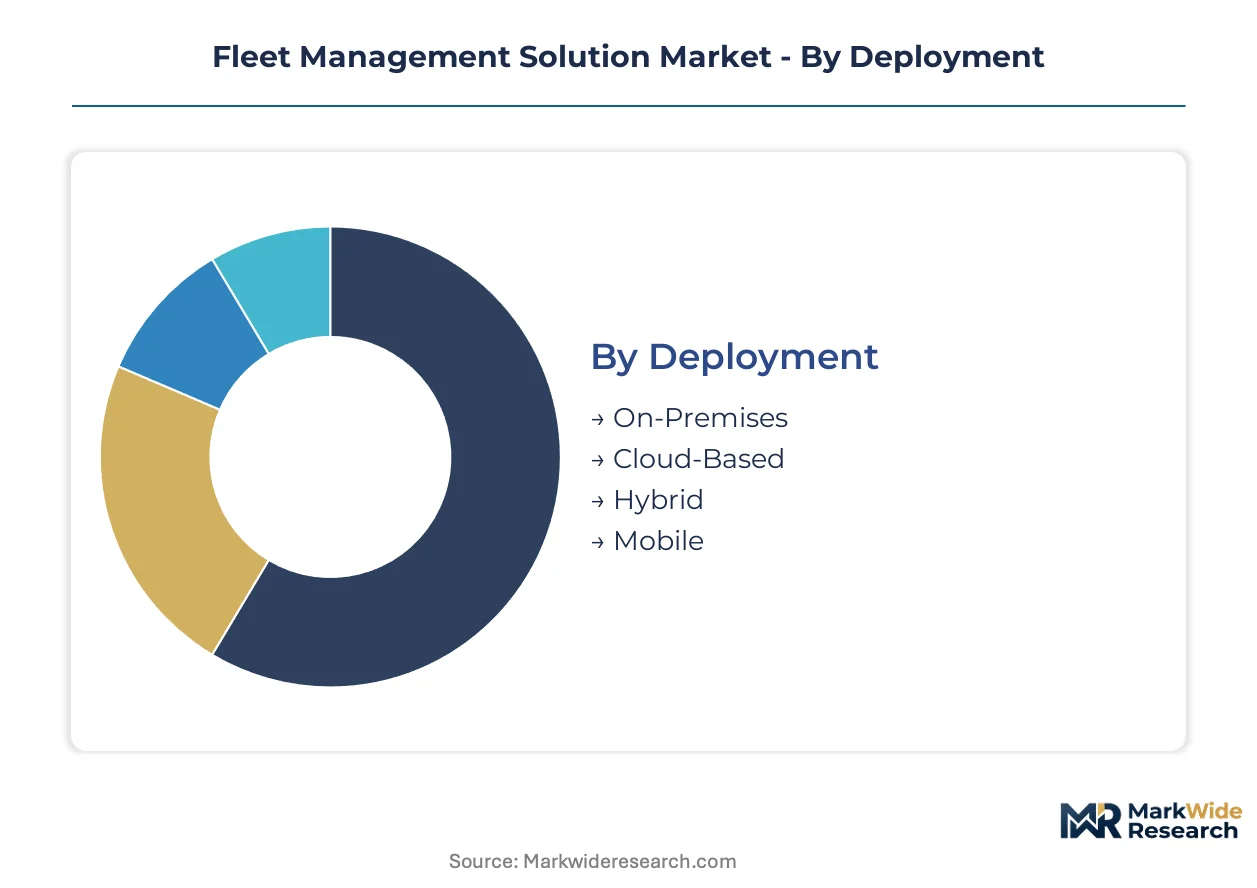
Fleet operators select solution architectures based on fleet size, IT infrastructure maturity, and regulatory exposure. Segmentation reveals where vendor consolidation concentrates and which technology layers command premium pricing.
Deployment:
Standardization versus customization tension runs deepest in deployment architecture, with enterprise security requirements colliding against speed-to-value pressures from mid-market buyers.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance burdens and compress implementation timelines from months to weeks. Mid-sized logistics operators in the United States with 50-500 power units favor this model for aligning technology costs with revenue volatility.
- On-Premises:Dedicated hardware installations behind customer firewalls satisfy defense contractors and hazardous materials carriers with stringent data sovereignty requirements. High upfront capital deployment and internal IT staffing obligations constrain adoption to heavily regulated niches.
- Hybrid:Edge computing nodes process safety-critical data locally while non-sensitive analytics sync to cloud repositories. Construction fleets operating across remote job sites with intermittent connectivity deploy this architecture to maintain operational continuity.
- Mobile:Smartphone-dependent solutions leveraging driver-owned devices minimize hardware procurement. Owner-operator trucking segments and small last-mile delivery contractors adopt this lowest-barrier entry point despite limited sensor integration depth.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as edge AI capabilities mature.
Solution:
Margin capture concentrates in applications that directly reduce fuel expenditure and liability exposure rather than pure operational visibility.
- Route Optimization:Algorithmic dispatch systems ingest real-time traffic, weather, and delivery window constraints to minimize miles driven and idle time. EPA Phase 3 compliance pressure on heavy-duty fleets accelerates procurement of these fuel-saving engines.
- Fuel Management:Integrated fuel card telemetry and engine diagnostic monitoring expose theft, inefficient driving behaviors, and maintenance issues degrading combustion efficiency. Long-haul trucking operators facing diesel price volatility treat this as non-discretionary spend.
- Asset Tracking:GPS and cellular-enabled hardware locates trailers, containers, and non-powered equipment across distributed yards and customer sites. Intermodal operators and dedicated contract carriage providers deploy these systems to reduce detention penalties and improve asset turns.
- Maintenance Scheduling:Predictive algorithms trigger service interventions based on engine fault codes, mileage intervals, and component wear models. Refrigerated transport fleets prioritize these capabilities to prevent cargo spoilage from unexpected breakdowns.
Revenue concentration sits with Route Optimization. Fastest share gains belong to Fuel Management as emissions regulations tighten.
End User:
Application intensity varies sharply across verticals, with safety-critical operations demanding deeper sensor integration than asset-light service models.
- Transportation:For-hire trucking carriers and private fleet operators constitute the core demand base, with regulatory compliance mandates driving platform standardization across interstate operations.
- Logistics:Third-party providers managing multi-customer networks require unified visibility across heterogeneous vehicle types and subcontractor relationships.
- Construction:Heavy equipment fleets and mobile workforce coordination create specialized requirements for ruggedized hardware and geofenced site management.
- Emergency Services:Police, fire, and ambulance fleets demand mission-critical reliability with redundant communication pathways and integration with dispatch computer-aided dispatch systems.
Transportation absorbs the majority of current platform deployments. Construction represents the fastest-climbing vertical as equipment monitoring converges with fleet telematics.
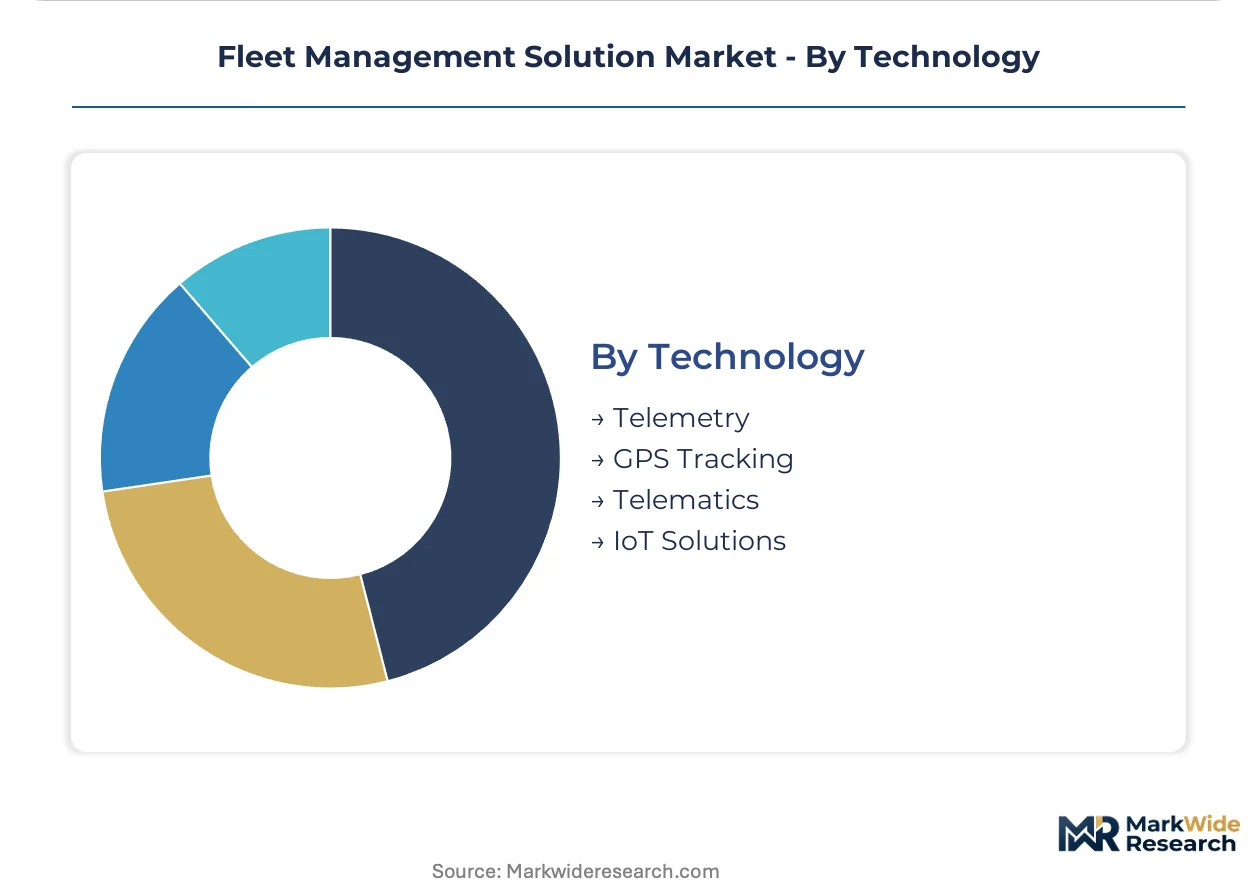
Technology:
Legacy standalone systems face displacement pressure as integrated platforms consolidate data streams from previously siloed hardware generations.
- Telematics:Cellular-connected onboard computers capture vehicle location, engine diagnostics, and driver behavior through standardized OBD-II interfaces. This technology layer anchors modern fleet platforms and subsumes narrower point solutions.
- GPS Tracking:Satellite-based location services provide foundational position data, though pure-play GPS vendors lose ground to richer telematics suites offering predictive maintenance and compliance documentation.
- Telemetry:Remote sensor data transmission from cargo compartments, refrigeration units, and auxiliary equipment extends visibility beyond vehicle mechanics to payload condition.
- IoT Solutions:Distributed sensor networks and edge computing modules enable real-time cargo monitoring, automated gate check-in, and predictive component failure detection.
Telematics infrastructure underpins the largest installed base. IoT Solutions demonstrate the steepest expansion trajectory as 5G connectivity and edge AI hardware proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in the United States, Germany, and India anchor fleet management solution development. Regional demand patterns reflect varying regulatory stringency and fleet operator consolidation trajectories.
United States
Large trucking carriers and logistics operators drive platform consolidation around unified telematics architectures. The EPA's Phase 3 greenhouse gas standards and the DOT's electronic logging device mandate shape procurement requirements. Dallas-Fort Worth and Atlanta metropolitan areas concentrate fleet operator headquarters deploying integrated fuel management systems.
Germany
Automotive OEM captive telematics units and independent software vendors compete for commercial fleet contracts. The EU Green Deal and Germany's national emissions trading scheme for transport accelerate investment in route optimization. Stuttgart and Munich industrial corridors host engineering centers developing predictive maintenance algorithms for heavy-duty vehicles.
China
Domestic logistics platforms and state-owned transport enterprises scale telematics deployments across fragmented trucking markets. MIIT regulations governing connected vehicle data security and the dual carbon goals influence platform architecture decisions. Yangtze River Delta manufacturing clusters around Shanghai generate demand for cargo condition monitoring across intermodal supply chains.
India
Rapid digitization of road freight brokerage and long-haul trucking creates demand for affordable fleet visibility solutions. The PLI scheme for automotive and auto component manufacturing supports local telematics hardware production. Karnataka's Bangalore-Tumkur corridor and Maharashtra's Pune-Nashik belt concentrate logistics technology startups and fleet operator back-offices.
United Kingdom
Third-party logistics providers and grocery delivery fleets prioritize driver safety analytics and customer delivery window compliance. The UK's net-zero transport strategy and London's ultra-low emission zone regulations drive electric fleet transition planning tool adoption. Midlands distribution hubs around Birmingham and Leicester deploy integrated asset tracking across subcontractor networks.
Fleet Management Solution Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the fleet management solution landscape. The market exhibits tiered concentration with a handful of scaled platform providers anchoring enterprise accounts alongside numerous regional specialists serving mid-market niches. Three strategic archetypes dominate: open-platform ecosystem orchestrators, vertically integrated connectivity-software bundles, and AI-native vertical specialists. Competitive dynamics center on strategic partnerships with automotive OEMs and tier-one suppliers, alongside geographic expansion through reseller channel development.
Within the open-platform ecosystem tier, Geotab Inc. and Samsara Inc. occupy positions exemplifying divergent architectural philosophies. Verizon Connect represents the integrated connectivity-software bundle archetype leveraging telecommunications infrastructure. These three anchors illustrate how vendor selection criteria vary across fleet operator IT maturity levels and regulatory exposure profiles.
| Leading Market Players |
|---|
| Geotab Inc. |
| Verizon Connect |
| Samsara Inc. |
| Trimble Inc. |
| Omnitracs LLC |
| PowerFleet Inc. |
| MiX Telematics Ltd. |
| Teletrac Navman |
| Fleet Complete |
| Others |
Supply Flow & Price Mechanics
Mid-sized logistics operators consolidating around unified cloud platforms are squeezing hardware procurement budgets and forcing telematics vendors to absorb cellular module cost volatility or lose multi-year SaaS contracts.
Pricing Analysis
Capacity additions in Mexico and Vietnam are reshaping price floors for ruggedized telematics hardware assembly. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade edge AI systems from basic GPS-enabled units. Cost compression in the mid-market tier is intensifying because semiconductor foundry allocation favors automotive OEM volumes over aftermarket fleet hardware. Small owner-operator fleets exhibit acute price sensitivity, while national LTL carriers prioritize integration depth over unit economics.
Supply Chain Analysis
Regional distribution centers in Texas, Ontario, and Rotterdam anchor hub-and-spoke fulfillment for telematics hardware kits. Manufacturing concentrates in China, Taiwan, and Mexico for cellular modules, GPS chipsets, and OBD-II interface components. The supply chain rests on lithium-ion battery cells for backup power units and specialized automotive-grade semiconductors. Single-source vulnerability around FCC-certified cellular modems creates certification bottlenecks when foundry capacity tightens. Distribution runs through value-added resellers and direct OEM partnerships rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management solution vendors face a geographic-arbitrage play between US regulatory compliance premiums and Asia-Pacific manufacturing cost bases, with EPA Phase 3 standards widening the effective price umbrella for emissions-optimized platforms.
For Market Incumbents: Anticipate margin compression from AI-native challengers by deepening backward integration into edge computing hardware and securing exclusive FCC certification timelines with cellular module suppliers. Anchor enterprise accounts through multi-year fuel management system deployments that embed switching costs before contract renewals. For New Entrants and Emerging Players: Enter via construction equipment monitoring verticals where telematics penetration lags transportation fleets by a decade. Target agricultural machinery cooperatives in the US Midwest with smartphone-dependent mobile solutions that minimize upfront hardware procurement. Lead with geofenced site compliance tools that address OSHA proximity regulations. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid deployment specialists bridging on-premises security requirements with cloud analytics scalability. Five-to-ten year viability hinges on regulatory persistence rather than technology differentiation alone. Monitor state-level zero-emission mandate adoption velocity as the inflection indicator for EV fleet transition planning tool demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented ELD, fuel card, and maintenance data streams into single-pane visibility. |
| Edge AI Hardware Launch | Enables millisecond-latency hazard detection that compresses insurance premium differentiation. |
| Strategic Partnership with Automotive OEM | Captures factory-installed telematics channels before aftermarket retrofit decisions solidify. |
| Acquisition of Specialist Firm | Secures predictive maintenance algorithms trained on refrigerated transport cargo condition data. |
| Geographic Expansion via Reseller Channel | Penetrates mid-sized 50-500 power unit fleets through regional IT integrators with existing logistics relationships. |
Methodological Framework
Multiple input streams — fleet operator procurement directors, telematics platform engineers, cellular module supply chain managers, and third-party logistics CTOs — were reconciled against DOT regulatory filings, FCC equipment authorization databases, EPA emissions compliance reports, and commercial vehicle registration data. Bottom-up unit deployment estimates across fleet size tiers were triangulated with top-down SaaS revenue aggregation from disclosed customer counts.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution application, fleet size tier, and vertical regulatory exposure. CAGRs were derived from fitted growth curves incorporating EPA Phase 3 compliance deadlines and diesel-electric total cost parity trajectories. Forecast inputs included carrier bankruptcy filing rates and state-level zero-emission mandate adoption schedules.
Inputs from fleet operator financial disclosures and telematics vendor customer announcements were available through the study window; gaps in private carrier technology spend data introduce uncertainty bands around mid-market penetration estimates. Forecasts reflect documented assumptions around regulatory persistence and cellular connectivity cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Shared Mobility Market