
 GDPR Software and Tools Market | 2026-2036
GDPR Software and Tools Market Size, Share, and Industry Trends Forecast 2026-2036
GDPR Software and Tools Market Foresight
The EU Green Deal's digital sustainability targets are rebalancing procurement criteria for enterprise software across European member states. OneTrust leverages its integrated platform architecture to anchor compliance workflows for multinational corporations navigating overlapping ESG and privacy obligations. IBM competes through its hybrid cloud infrastructure, sustaining data residency controls that align with national supervisory interpretations of GDPR Article 44 transfer mechanisms. TrustArc specializes in automated risk assessment tooling, differentiating through pre-configured regulatory templates that reduce implementation cycles for mid-market enterprises.
GDPR software and tools encompass automated platforms that map personal data flows, enforce retention policies, manage consent lifecycles, and generate audit-ready documentation for supervisory authority inquiries. These systems typically integrate with existing enterprise resource planning and customer relationship management architectures through standardized APIs, processing structured and unstructured data across on-premises, cloud, and edge environments. Cloud-based deployment leads current adoption among European enterprises seeking scalable infrastructure without capital-intensive hardware commitments, while consent management solutions represent the fastest-growing solution type as real-time preference management becomes embedded in digital customer journeys. Subscription pricing dominates the vendor landscape, creating recurring revenue pools that fund continuous regulatory content updates as national implementations of GDPR evolve.
The European Data Protection Board coordinates enforcement consistency across EU member state regulators including France's CNIL and Germany's federal data protection authorities, directly shaping product roadmaps through binding decision precedents on automated decision-making and cross-border processing. The EU AI Act introduces additional conformity assessment requirements for high-risk AI systems processing personal data, expanding the functional scope that GDPR software must address. Organizations should monitor how supervisory authority guidance on AI model training datasets intersects with existing data minimization and purpose limitation obligations.
Market Dynamics
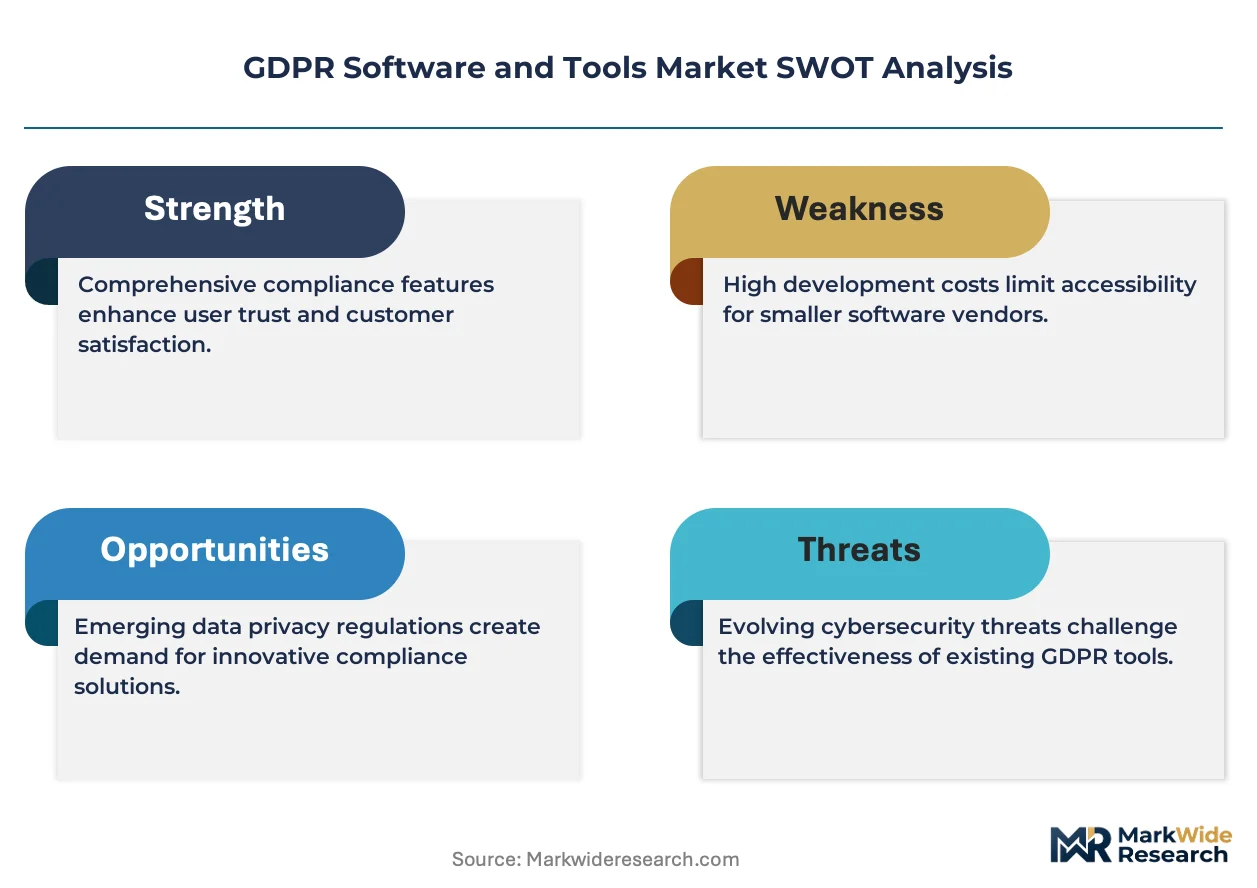
The EU AI Act's conformity assessment requirements for high-risk systems are forcing GDPR software vendors to expand functional scope beyond traditional data protection into automated decision-making governance and model training dataset documentation.
Growth Catalysts
- EU AI Act layering:High-risk AI system mandates create immediate procurement pull for integrated privacy-AI governance platforms across European financial services and healthcare sectors.
- France:CNIL enforcement precedents on automated decision-making are accelerating enterprise investment in audit-ready documentation workflows and real-time consent management infrastructure.
- Consent lifecycle automation:Real-time preference management embedded in digital customer journeys is displacing static consent collection, driving replacement cycles for legacy compliance tooling.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dominance in EU data residency-compliant hosting creates vendor lock-in risk for mid-market enterprises seeking multi-cloud portability.
- Regulatory fragmentation:Divergent national supervisory interpretations of GDPR Article 44 transfer mechanisms impose compliance cost multipliers on cross-border data processing architectures.
- Technical debt:Legacy on-premises ERP and CRM systems lack standardized API connectivity, constraining automated data mapping and retention policy enforcement.
Strategic Opportunities
- Digital Operational Resilience Act:DORA's ICT risk management mandates for financial entities create adjacent demand for integrated operational resilience and privacy governance tooling.
- Germany:Federal data protection authority guidance on employee monitoring and works council consultation is opening specialized workforce analytics compliance modules.
- Edge computing convergence:Distributed processing architectures are converging with privacy-preserving computation techniques, enabling new product categories for IoT and industrial data governance.
Industry Challenges
- Cross-functional talent scarcity:Shortage of professionals combining data protection law expertise with cloud architecture and API integration skills is extending implementation timelines.
- Continuous regulatory content maintenance:Subscription pricing models require sustained investment in tracking 27 national GDPR implementations and EDPB binding decisions without margin compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GDPR Software and Tools Market |
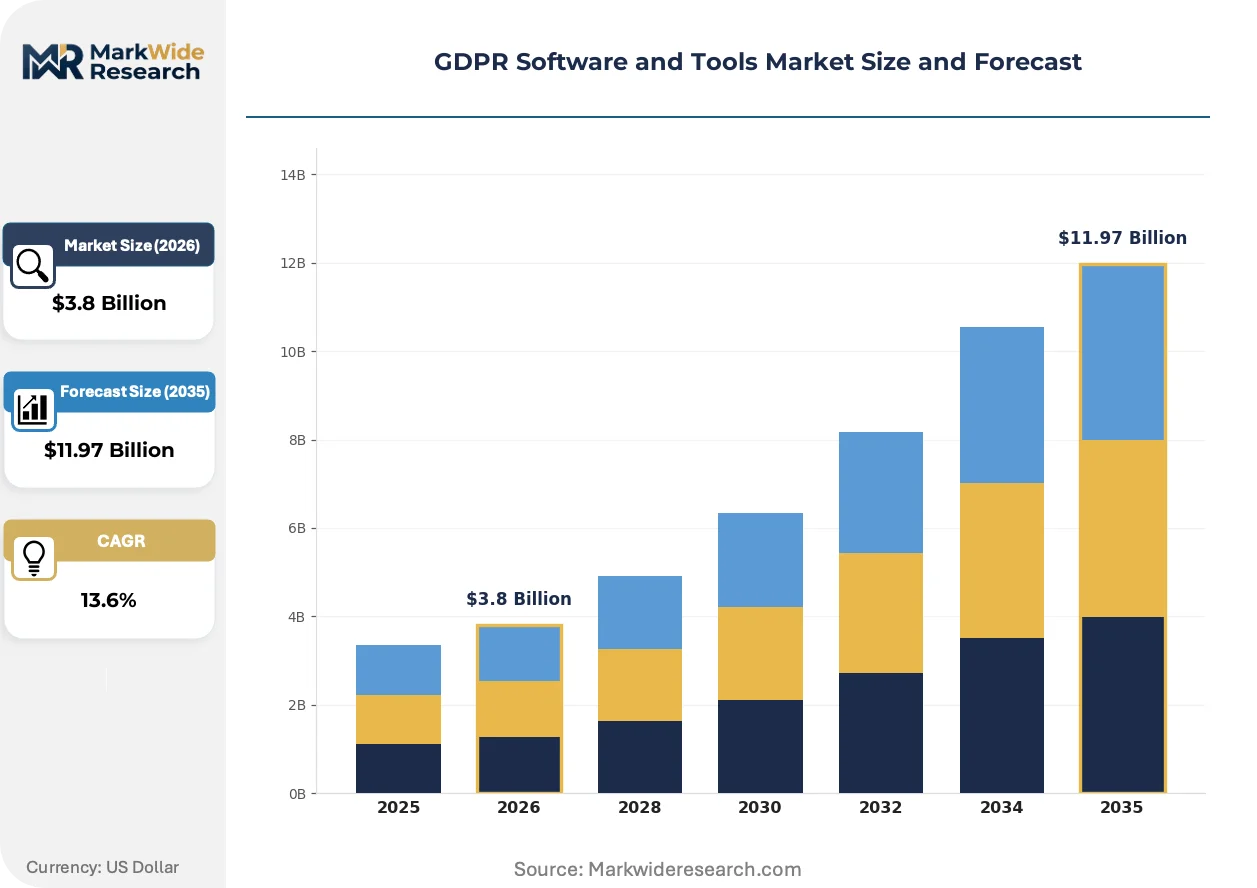
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Type: Data Discovery, Consent Management, Risk Assessment, Compliance Reporting, Incident Management End User: Enterprises, Government Agencies, Educational Institutions, Financial Institutions, Technology Firms Pricing Model: Subscription, Perpetual License, Freemium, Pay-As-You-Go |
| Companies Covered | OneTrust, IBM, SAP, Oracle, SAS Institute, Informatica, Proofpoint, Nymity, TrustArc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GDPR Software and Tools Market Shifts & Advancements
Privacy-enhancing computation techniques are reshaping how enterprises process sensitive data, embedding compliance into infrastructure rather than layering it atop existing systems. This architectural shift is compressing vendor differentiation and elevating hybrid deployment expertise.
Differential privacy and federated learning architectures are converging with cloud-native compliance platforms, enabling pharmaceutical and financial services firms to train models on distributed datasets without centralizing raw personal data. European health technology adopters are moving fastest, driven by EMA guidance on real-world evidence generation. This convergence is compressing the addressable market for traditional data anonymization tooling while expanding demand for cryptographically verifiable compliance attestation.
EDPB binding decisions on automated decision-making are reshaping product roadmaps, requiring vendors to embed explainability logging and human-in-the-loop workflow documentation as core platform functions. The industrial consequence is functional scope expansion beyond static data inventories into dynamic algorithmic governance. German automotive and French insurance sectors are responding with accelerated procurement of integrated AI-privacy platforms that satisfy both GDPR and emerging EU AI Act conformity assessment requirements.
Enterprise buyers are consolidating vendor relationships, preferring integrated platforms over point solutions for consent management, data discovery, and risk assessment. Mid-market enterprises in the United Kingdom and Netherlands are displacing multi-vendor stacks with single-platform subscriptions that reduce integration overhead. This concentration is most visible in banking and insurance, where procurement teams prioritize supervisory authority pre-certification and continuous regulatory content updates over best-of-breed functional depth.
GDPR Software and Tools Market Segmentation
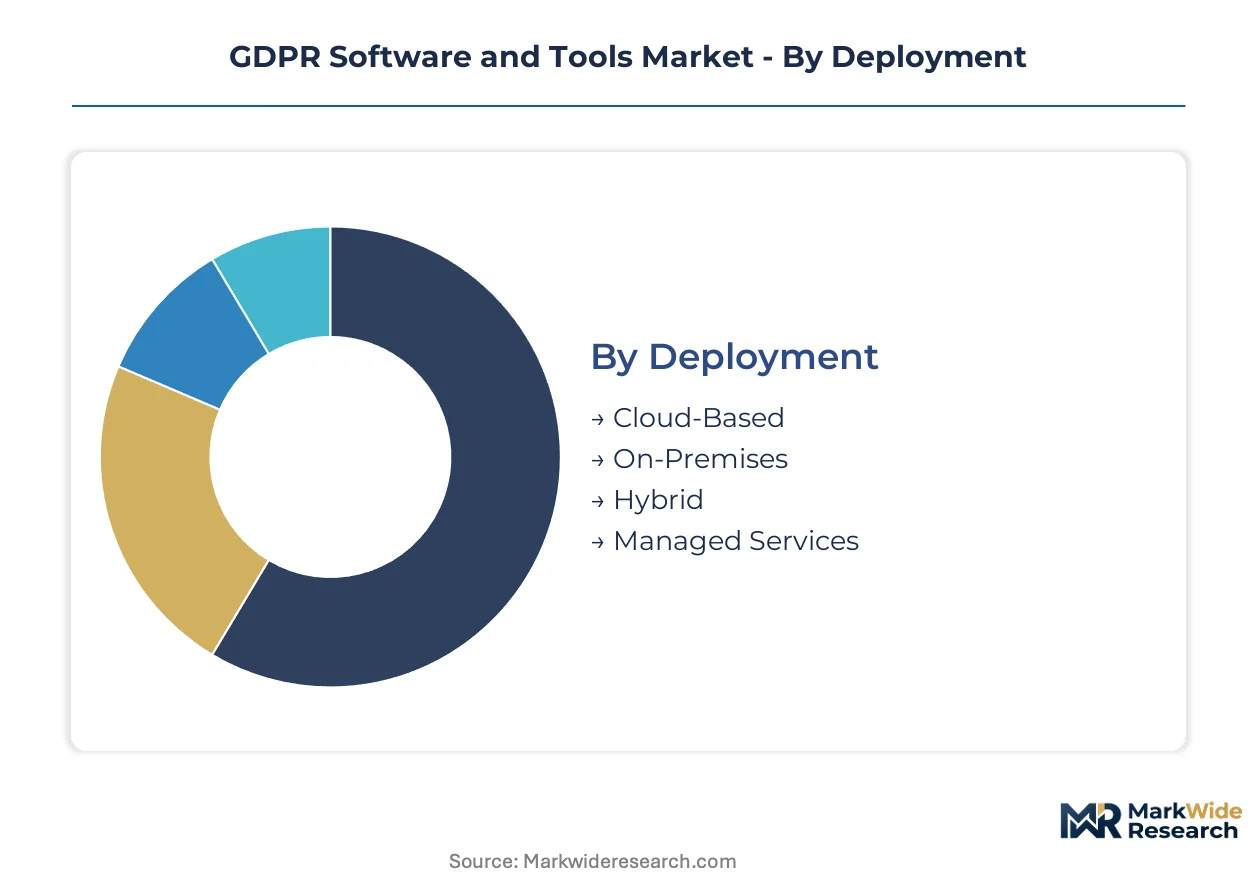
GDPR software procurement patterns diverge sharply between cost-conscious mid-market buyers and compliance-intensive regulated sectors. Deployment choices, solution architecture, and pricing structures cluster around organizational scale, data processing volume, and supervisory authority exposure.
Deployment:
Volume deployment dominates cloud-based adoption while premium customization anchors on-premises retention.
- Cloud-Based:Scalable infrastructure processes structured and unstructured data across distributed environments without capital-intensive hardware. European banking and insurance sectors in Germany, France, and the United Kingdom disproportionately demand cloud-based models as supervisory authorities enforce cross-border data governance standards.
- On-Premises:Dedicated hardware maintains data residency controls for organizations with strict sovereignty requirements or legacy system dependencies. German automotive manufacturers and French defense contractors retain on-premises architectures to satisfy works council consultation mandates and national security classifications.
- Hybrid:Split architectures process sensitive personal data on-premises while pushing analytics workloads to cloud environments.
- Managed Services:Outsourced compliance operations handle continuous regulatory content updates and supervisory authority inquiry response.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Solution Type:
Functional specialization separates integrated platforms from point solutions across the compliance workflow chain.
- Data Discovery:Automated mapping engines scan structured and unstructured repositories to identify personal data flows and retention policy violations. Financial institutions across Germany, France, and the United Kingdom are expanding procurement of data discovery platforms as the EU AI Act layers new obligations atop existing GDPR mandates.
- Consent Management:Real-time preference management infrastructure embeds granular consent collection and withdrawal mechanisms into digital customer journeys. This segment is expanding most quickly as static consent collection displaces legacy compliance tooling in retail banking and e-commerce.
- Risk Assessment:Automated scoring algorithms evaluate processing activity against regulatory templates and supervisory authority precedents.
- Compliance Reporting:Audit-ready documentation generators assemble evidence packages for Data Protection Authority inquiries.
- Incident Management:Breach notification workflows coordinate 72-hour supervisory authority reporting and affected individual communication.
Procurement consolidation favors Data Discovery and Consent Management as anchor modules. Point solution adoption persists in Incident Management for specialized breach response.
End User:
Regulatory exposure intensity shapes solution sophistication requirements across organizational types.
- Financial Institutions:Integrated privacy-AI governance platforms address overlapping GDPR, EU AI Act, and Digital Operational Resilience Act mandates. German, French, and United Kingdom banking and insurance sectors drive disproportionate demand for consent management and data discovery platforms with supervisory authority pre-certification.
- Enterprises:Multinational corporations navigate overlapping ESG and privacy obligations through integrated platform architectures. Mid-market enterprises in the United Kingdom and Netherlands are displacing multi-vendor stacks with single-platform subscriptions that reduce integration overhead.
- Government Agencies:Public sector procurement emphasizes sovereign cloud requirements and national data residency controls.
- Educational Institutions:University and research consortia deploy privacy-preserving computation for cross-border academic collaboration.
- Technology Firms:High-velocity software developers embed compliance-by-design into continuous deployment pipelines.
Compliance spend concentrates in Financial Institutions. Fastest adoption velocity appears in Enterprises consolidating fragmented tooling.
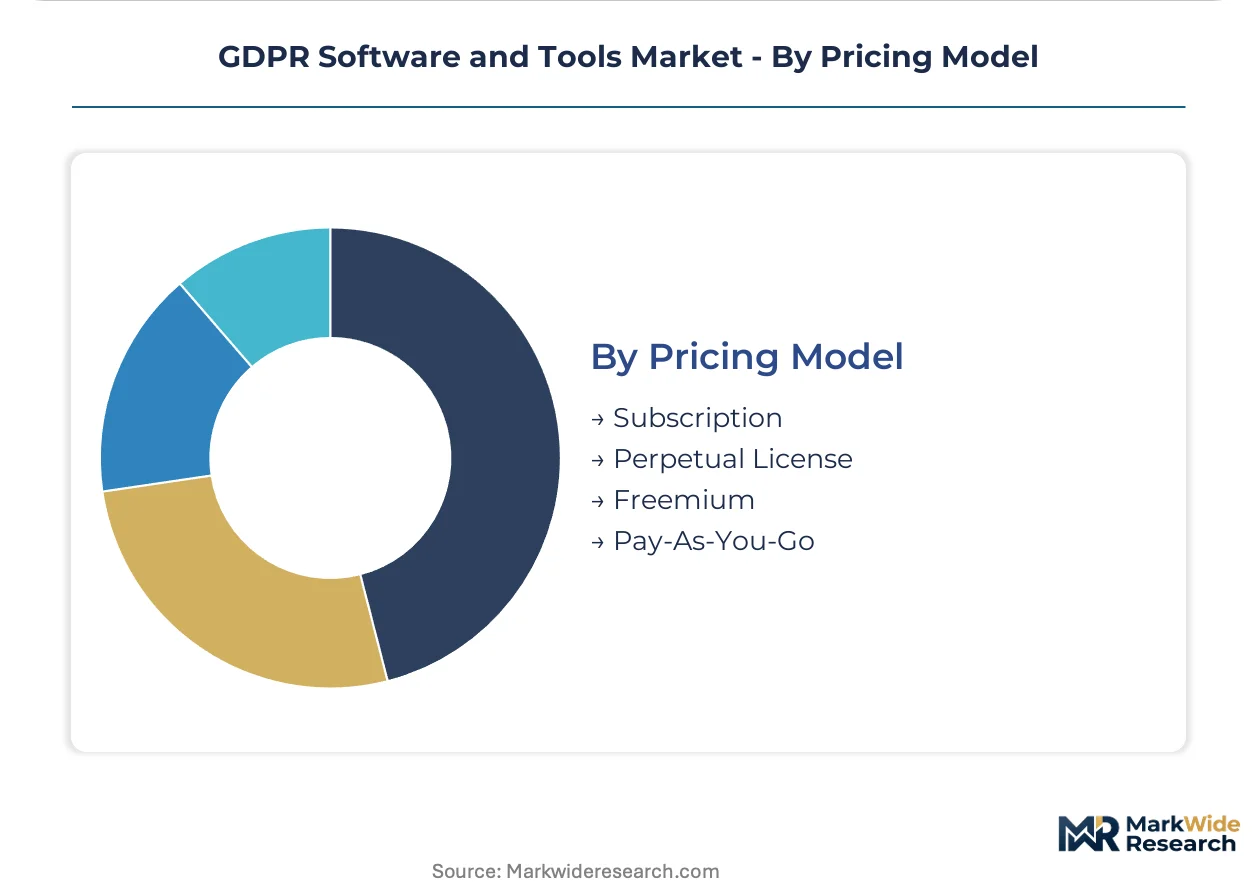
Pricing Model:
Recurring revenue structures dominate vendor economics while perpetual licenses retain footholds in capital-favorable procurement regimes.
- Subscription:Recurring pricing funds continuous regulatory content updates as national implementations of GDPR evolve. European enterprises seeking scalable infrastructure without capital-intensive hardware commitments drive subscription dominance.
- Perpetual License:One-time acquisition with maintenance contracts suits organizations with fixed compliance scopes and multi-year depreciation schedules.
- Freemium:Tiered entry points convert basic data inventory users to premium automated workflow subscribers.
- Pay-As-You-Go:Consumption-based metering aligns costs with processing volume spikes in seasonal or project-based data activities.
Revenue concentration sits with Subscription. Perpetual License retention is strongest in public sector and defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GDPR software market concentrates consumption in European financial centers while production capacity clusters in cloud infrastructure hubs across Germany, the United Kingdom, and France. German banking regulators enforce the strictest cross-border data governance standards, driving premium procurement. French and British institutions follow with accelerated consent management platform deployment.
Germany
Bundesbank oversight and BaFin guidance on operational resilience propel demand for integrated privacy-AI governance platforms among Frankfurt-based financial institutions. The Federal Data Protection Authority mandates works council consultation for employee monitoring systems, opening specialized workforce analytics compliance modules. Munich automotive manufacturers retain on-premises architectures to satisfy national security classifications and labor representation requirements.
United Kingdom
Financial Conduct Authority supervision and post-Brexit data adequacy negotiations drive procurement of audit-ready documentation workflows in London's banking district. The Information Commissioner's Office enforcement on automated decision-making accelerates real-time consent management infrastructure replacement cycles. Edinburgh and Manchester insurance clusters displace multi-vendor stacks with single-platform subscriptions to reduce integration overhead.
France
CNIL enforcement precedents on algorithmic transparency compel Paris-based insurers and asset managers to invest in explainability logging and human-in-the-loop documentation. The EU AI Act conformity assessment timeline creates immediate procurement pull for high-risk system governance tooling. Lyon pharmaceutical adopters deploy privacy-preserving computation for real-world evidence generation under EMA guidance.
Netherlands
De Nederlandsche Bank operational resilience expectations and Dutch Data Protection Authority guidance on cross-border processing attract mid-market enterprises to cloud-based subscription models. Amsterdam's fintech cluster consolidates fragmented compliance tooling into integrated platforms to satisfy supervisory authority pre-certification requirements. Rotterdam logistics firms embed consent lifecycle automation into digital customer journey architectures.
Italy
Garante per la Protezione dei Dati Personali enforcement on data retention policies drives automated mapping engine procurement among Milan-based banking groups. National recovery and resilience plan funding accelerates public sector sovereign cloud requirements for government agencies in Rome. Turin automotive suppliers adopt hybrid deployment models to process sensitive personal data on-premises while pushing analytics workloads to cloud environments.
GDPR Software and Tools Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with continuous regulatory content update capabilities. Subscription pricing models dominate vendor economics, creating recurring revenue pools that fund tracking of national GDPR implementations. Three archetypes occupy distinct positions: enterprise-grade integrated suites, mid-market automated risk assessment specialists, and cloud-native consent management point solutions. M&A activity concentrates on acquiring API connectivity layers for legacy ERP integration, while portfolio diversification extends into adjacent EU AI Act conformity assessment tooling.
Within the integrated platform tier, OneTrust and IBM exemplify contrasting architectural approaches—OneTrust anchors compliance workflows for multinational corporations navigating overlapping ESG and privacy obligations, while IBM sustains data residency controls through hybrid cloud infrastructure aligned with national supervisory interpretations. TrustArc occupies a position among automated risk assessment specialists, differentiating through pre-configured regulatory templates that reduce implementation cycles for mid-market enterprises in the United Kingdom and Netherlands.
| Leading Market Players |
|---|
| OneTrust |
| IBM |
| SAP |
| Oracle |
| SAS Institute |
| Informatica |
| Proofpoint |
| Nymity |
| TrustArc |
| Others |
Supply & Pricing Matrix
Cloud infrastructure licensing fees cascade through subscription pricing tiers as hyperscaler concentration in Germany, France, and the United Kingdom elevates data residency compliance costs for mid-market enterprises. These input costs stratify vendor offerings across enterprise, mid-market, and small-business segments.
Pricing Analysis
Value-based pricing anchored to audit-ready documentation throughput dominates vendor economics, with subscription tiers scaling by data volume processed and regulatory jurisdiction coverage. Price differentiation rests on supervisory authority pre-certification depth and continuous content update frequency for national GDPR implementations. Pricing pressure stems from mid-market consolidation toward single-platform subscriptions that displace multi-vendor stacks. Small enterprises exhibit highest price sensitivity, while Frankfurt and London banking clusters absorb premium tiers for integrated privacy-AI governance functionality.
Supply Chain Analysis
Cross-border data transfer compliance logistics tether vendor operations to EU-based hosting infrastructure across Germany, Ireland, and the Netherlands. Software development draws from specialized privacy engineering talent pools concentrated in Berlin, Paris, and Amsterdam, with API integration expertise sourcing from London fintech clusters. Single-source vulnerability concentrates in hyperscaler-dependent hosting architectures. Distribution runs through direct enterprise sales teams and channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory content maintenance capacity constraints prop pricing power for vendors sustaining continuous national implementation tracking across EU member states.
For Market Incumbents: Lock in multi-year enterprise subscriptions by embedding EU AI Act conformity assessment modules ahead of enforcement timelines. Acquire API connectivity specialists to bridge legacy ERP integration gaps constraining automated data mapping. Vertical integration into privacy-preserving computation techniques defends against cloud-native entrants. For New Entrants and Emerging Players: Mid-market enterprises in Italy and Spain displacing fragmented compliance tooling represent the most penetrable buyer archetype. Target cloud-native consent management point solutions for retail banking segments underserved by integrated platform complexity. Pursue supervisory authority pre-certification partnerships as primary go-to-market acceleration. For Investors and Strategic Acquirers: EDPB binding decision velocity on automated decision-making is the leading indicator that algorithmic governance tooling will command premium valuations. Position acquisition screening toward API-first data discovery specialists with pre-configured regulatory templates. Monitor CNIL enforcement precedent frequency as the signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates consent management, data discovery, and risk assessment for Deutsche Bank-tier clients. |
| Acquisition of Specialist Firm | Captures API connectivity layers bridging SAP and Oracle ERP systems for automotive manufacturers. |
| Geographic Expansion | Establishes sovereign cloud hosting in Rome and Madrid for public sector procurement requirements. |
| Product Launch | Introduces workforce analytics compliance modules addressing German works council consultation mandates. |
| Strategic Partnership | Aligns with EMA guidance frameworks for Lyon pharmaceutical real-world evidence generation deployments. |
Research Methodology
Independent corroboration across chief privacy officers, data protection authority enforcement leads, and cloud procurement directors underwrites the qualitative findings. Primary interviews with IT compliance managers at Frankfurt banking groups, Paris insurance firms, and Amsterdam fintech clusters combined with secondary validation from EDPB binding decisions, CNIL enforcement precedents, and BaFin operational resilience guidance. Bottom-up vendor revenue triangulation against top-down enterprise software spend estimates anchors segmentation sizing.
Rate-of-change decomposition across deployment model transitions, solution type replacement cycles, and end-user procurement consolidation patterns structured the analytical framework. Segmentation dimensions modeled include cloud-based versus on-premises deployment, consent management versus data discovery solution types, and financial institution versus enterprise end-user categories. CAGRs derived from historical procurement velocity adjusted for EU AI Act and DORA regulatory layering effects. Forecast inputs incorporated supervisory authority guidance publication frequency and hyperscaler data residency certification timelines.
Revisions become necessary when EDPB binding decision divergence across member states materializes or when hyperscaler concentration triggers regulatory intervention. Forecasts reflect assumptions regarding continuous regulatory content update viability and mid-market single-platform consolidation momentum. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Battery-Powered Doorbell Camera Market
Security Software
United States Lawful Interception Market
Security Software
Mobile Security Market
Security Software
POS Security Market
Security Software
Smart Video Doorbell Market
Security Software
Facial Recognition Market
Security Software
Embedded Security Market
Security Software
Anti-Fraud Management System Market
Security Software
Global Consumer IAM Market
Security Software
Spain Endpoint Detection and Response Market
Security Software
IAM Security Services Market
Security Software
Encryption Software Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
BYOD Security Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Hardware Encryption Market