
 Europe IP Video Intercom Device and Equipment Market | 2026-2036
Europe IP Video Intercom Device and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IP Video Intercom Device and Equipment Market Foresight
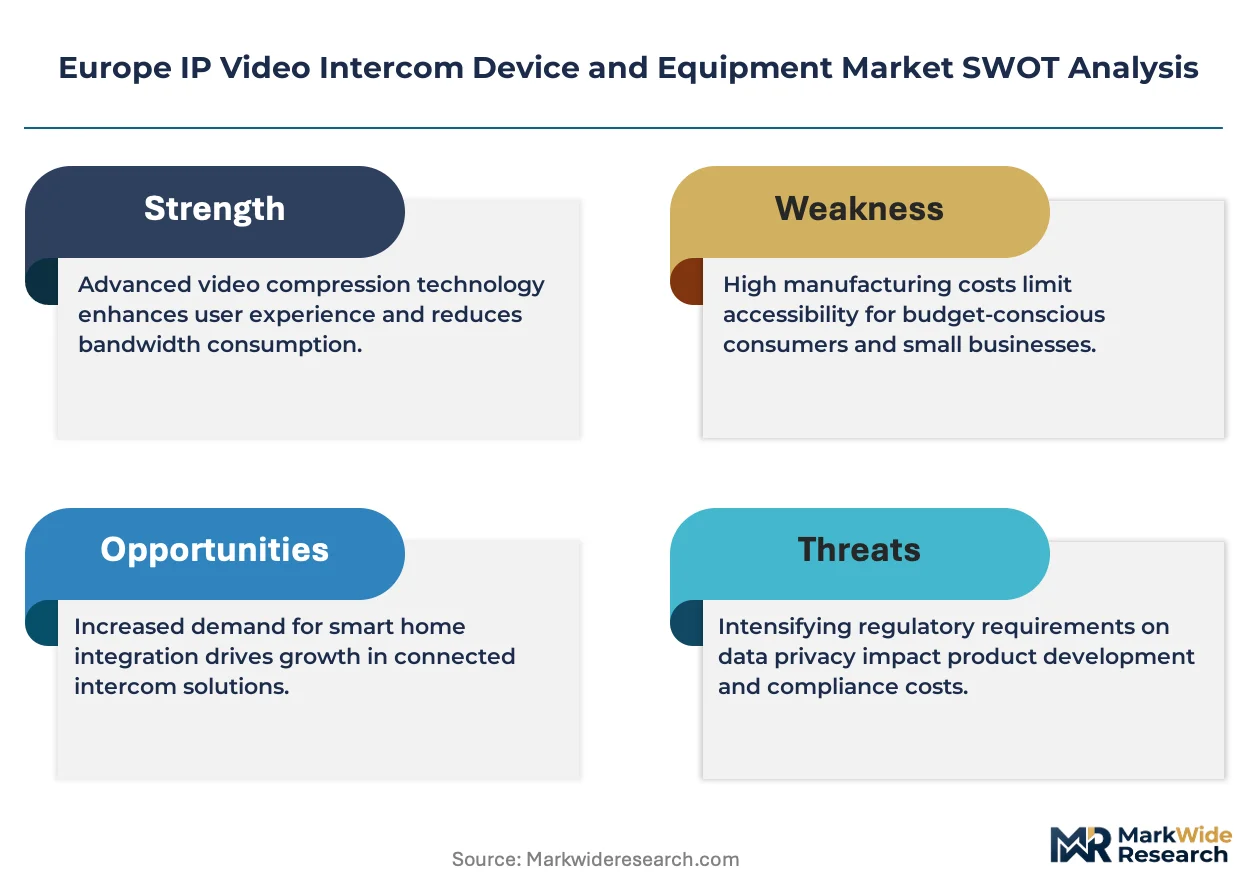
The EU Green Deal's building efficiency mandates is broadening the addressable base for networked entry infrastructure across European commercial stock. Doorbird leverages its German manufacturing base to sustain short-lead-time fulfillment for premium residential installations. Commend International Gmbh anchors its position through specialized solutions for transportation and critical infrastructure verticals. Urmet Spa competes via deep integration with Italian building automation ecosystems and established installer relationships.
Europe IP Video Intercom Device and Equipment encompasses networked audiovisual entry systems transmitting voice, video, and access control signals over Internet Protocol infrastructure, typically operating on Power-over-Ethernet standards at 802.3af or 802.3at wattage classes to enable single-cable deployment. These systems serve primary commercial and residential purposes including visitor verification, remote access management, and integration with broader building security platforms. Wired intercoms retain dominant share in new commercial construction across Northern Europe where structured cabling precedes occupancy, while cloud-based systems represent the fastest-expanding technology segment as property managers seek centralized multi-site administration without on-premise server maintenance. Access control systems capture concentrated margin pools through recurring software licensing and credential management services layered over hardware installations.
The European Telecommunications Standards Institute and national regulators implementing the Radio Equipment Directive shape device interoperability and electromagnetic compatibility requirements, while GDPR compliance obligations constrain cloud video storage architectures and data residency provisions. CE marking and ETSI EN 301 489 certification create non-trivial market access barriers for non-European suppliers unfamiliar with notified body pathways. Stakeholders must monitor evolving EU cybersecurity certification schemes for connected building products, as forthcoming mandatory ratings will likely reshape competitive positioning between established European manufacturers and emerging Asian competitors.
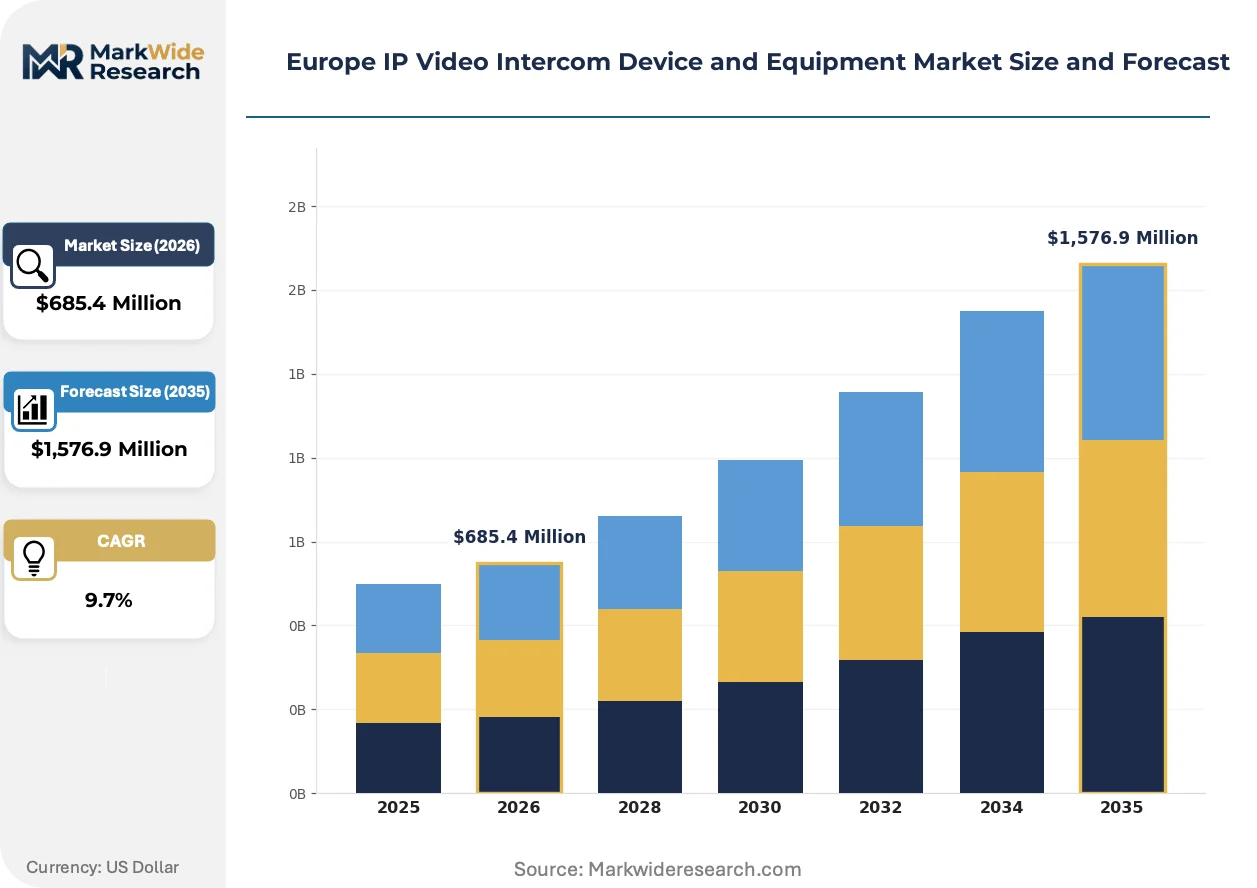
Market Dynamics
Cloud-native architectures are compressing deployment timelines for multi-tenant properties across Europe, while GDPR-mandated data residency requirements force vendors to restructure their backend infrastructure. This tension between operational agility and compliance rigor defines current competitive maneuvering.
Growth Catalysts
- EU Green Deal building retrofits:Efficiency mandates for commercial stock are mandating networked entry infrastructure upgrades across France, Belgium, and the Netherlands.
- Power-over-Ethernet standards:802.3at wattage classes enable single-cable deployment, reducing installation labor and material costs for structured cabling contractors.
- Multi-tenant commercial retrofits:Property managers in Paris, Brussels, and Amsterdam are consolidating legacy analog systems into centralized IP platforms.
Market Restraints
- Copper and semiconductor input volatility:Structured cabling and PoE switch components face price instability from concentrated Asian foundry supply.
- CE marking pathway complexity:The Radio Equipment Directive's notified body requirements create six-to-twelve month certification delays for non-European suppliers unfamiliar with ETSI EN 301 489 protocols.
- Legacy analog substitution inertia:Existing two-wire intercom installations in aging European commercial stock resist full IP replacement due to tenant disruption costs.
Strategic Opportunities
- Eastern European underpenetration:Poland, Czechia, and Romania exhibit sub-15% IP intercom penetration in residential construction, creating first-mover whitespace.
- Transportation vertical specialization:Rail stations, airports, and critical infrastructure require hardened IP intercom systems with EN 50121 electromagnetic compatibility certification.
- AI Act compliance services:Biometric video analytics for access control create recurring revenue streams through audit and certification support.
Industry Challenges
- Cybersecurity certification timeline compression:Forthcoming EU cybersecurity rating schemes for connected building products demand engineering retooling before mandatory implementation.
- Legacy system integration complexity:Hybrid deployments combining IP video with existing door hardware require specialized protocol bridging expertise scarce among regional installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IP Video Intercom Device and Equipment Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Intercoms, Wireless Intercoms, Video Door Phones, Access Control Systems Technology: IPv4, IPv6, PoE, Cloud-based Systems End User: Residential Buildings, Commercial Offices, Hotels, Educational Institutions Installation Type: Indoor, Outdoor, Surface-mounted, Flush-mounted |
| Companies Covered | Doorbird (Bird Home Automation GmbH), Commend International Gmbh, Urmet Spa, Paxton Access Ltd, Loxone Electronics Gmbh, Siedle, Bas-ip Intercom Systems, Farfisa, 2n Telekomunikace, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IP Video Intercom Device and Equipment Market Shifts & Advancements
Edge computing architectures are redistributing processing loads from centralized servers to door station hardware, while biometric authentication modules are displacing credential-based access. These shifts are compressing vendor differentiation around software capabilities rather than hardware specifications.
Cloud-based intercom platforms are expanding into property management software stacks, enabling remote multi-site administration without on-premise server maintenance. Mid-size property management firms in Germany and the Benelux are adopting these systems fastest. This expansion is compressing margins for traditional on-premise vendors while opening subscription revenue pools.
The EU AI Act's risk classification framework for biometric identification systems is forcing re-engineering of facial recognition capabilities in premium intercom lines. Vendors must now document training data provenance and algorithmic audit trails for CE marking compliance. French and German regulators are conducting the first conformity assessments, creating precedent for broader European enforcement.
Facility managers are unbundling hardware procurement from software licensing and installation services, treating intercom systems as separable cost centers. This pattern is displacing traditional turnkey contracts in the United Kingdom and Nordic markets. Commercial real estate investment trusts are driving this shift to optimize capital expenditure timing against lease renewal cycles.
Europe IP Video Intercom Device and Equipment Market Segmentation
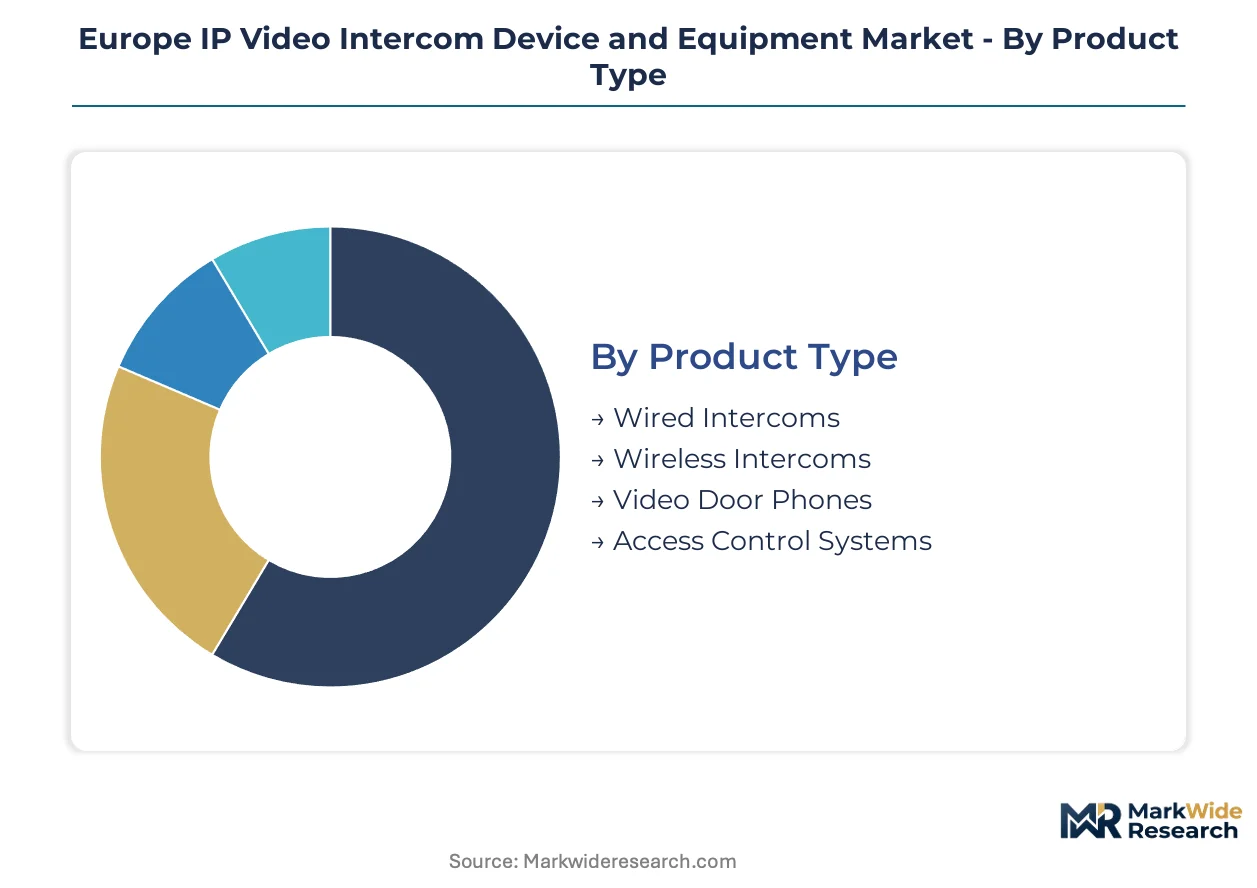
Segmentation in the European IP video intercom market reveals divergent capital requirements and margin structures across hardware, connectivity, and service layers. Product and technology choices determine whether deployments emphasize upfront infrastructure investment or recurring software expenditure.
Product Type:
Capital intensity varies sharply across hardware categories, with infrastructure-heavy segments demanding structured cabling investment while integrated platforms capture recurring service revenue.
- Wired Intercoms:These systems transmit audiovisual signals over dedicated Ethernet cabling, typically requiring 802.3af or 802.3at Power-over-Ethernet switches and conduit installation. Demand concentrates in new commercial construction across Germany and the Netherlands where structured cabling precedes occupancy, driven by EU Green Deal mandates for building efficiency retrofits. Wired intercoms absorb the bulk of installed capacity; Cloud-based Systems are expanding most quickly.
- Access Control Systems:Integrated platforms combining video verification with credential management and audit logging, often layered with biometric analytics modules. French and Benelux property managers in multi-tenant commercial retrofits prioritize these systems for centralized tenant administration and GDPR-compliant visitor logging.
- Wireless Intercoms:Battery-powered or WiFi-connected units reducing installation labor in heritage buildings where conduit runs prove impractical.
- Video Door Phones:Compact single-dwelling units serving detached residential installations, prevalent in Italian and Spanish suburban construction.
Wired infrastructure dominates current installed base; integrated access platforms are climbing the fastest.
Technology:
Protocol migration and backend architecture choices segment vendors by engineering legacy and cloud-native capability depth.
- Cloud-based Systems:Browser-administered platforms eliminating on-premise server hardware, with video storage distributed across EU-resident data centers to satisfy GDPR data residency obligations. German mid-size property management firms adopt these fastest for multi-site portfolio administration without IT staffing expansion. IPv4 retains legacy compatibility burdens; Cloud-based Systems are gaining share fastest.
- PoE:Power-over-Ethernet deployment at 802.3at wattage classes enabling single-cable installation, reducing material costs and contractor labor hours for structured cabling installers across Northern Europe.
- IPv6:Next-generation addressing protocol supporting expanded device mesh density in smart building deployments, required for EN 303 645 cybersecurity certification pathways.
- IPv4:Legacy addressing scheme still prevalent in installed base, creating protocol bridging complexity for hybrid upgrade scenarios.
Cloud architectures command premium pricing; PoE deployment shows steepest volume expansion.
End User:
Customer type determines procurement sophistication, with institutional buyers emphasizing compliance documentation and multi-year service agreements.
- Commercial Offices:Multi-tenant properties requiring centralized visitor management, tenant credential provisioning, and integration with building automation platforms. Paris, Brussels, and Amsterdam retrofits drive concentrated demand as property managers consolidate legacy analog systems into IP platforms.
- Residential Buildings:Smart apartment developments in Germany integrating cloud-connected entry with tenant mobile applications, funded through service charge structures rather than capital expenditure.
- Hotels:Guest-facing installations requiring multilingual interfaces and property management system integration, with Nordic chains leading mobile key and video verification convergence.
- Educational Institutions:Campus-wide deployments emphasizing emergency communication capabilities and lockdown integration, subject to national critical infrastructure procurement frameworks.
Commercial offices absorb dominant procurement volume; residential smart buildings show fastest adoption velocity.
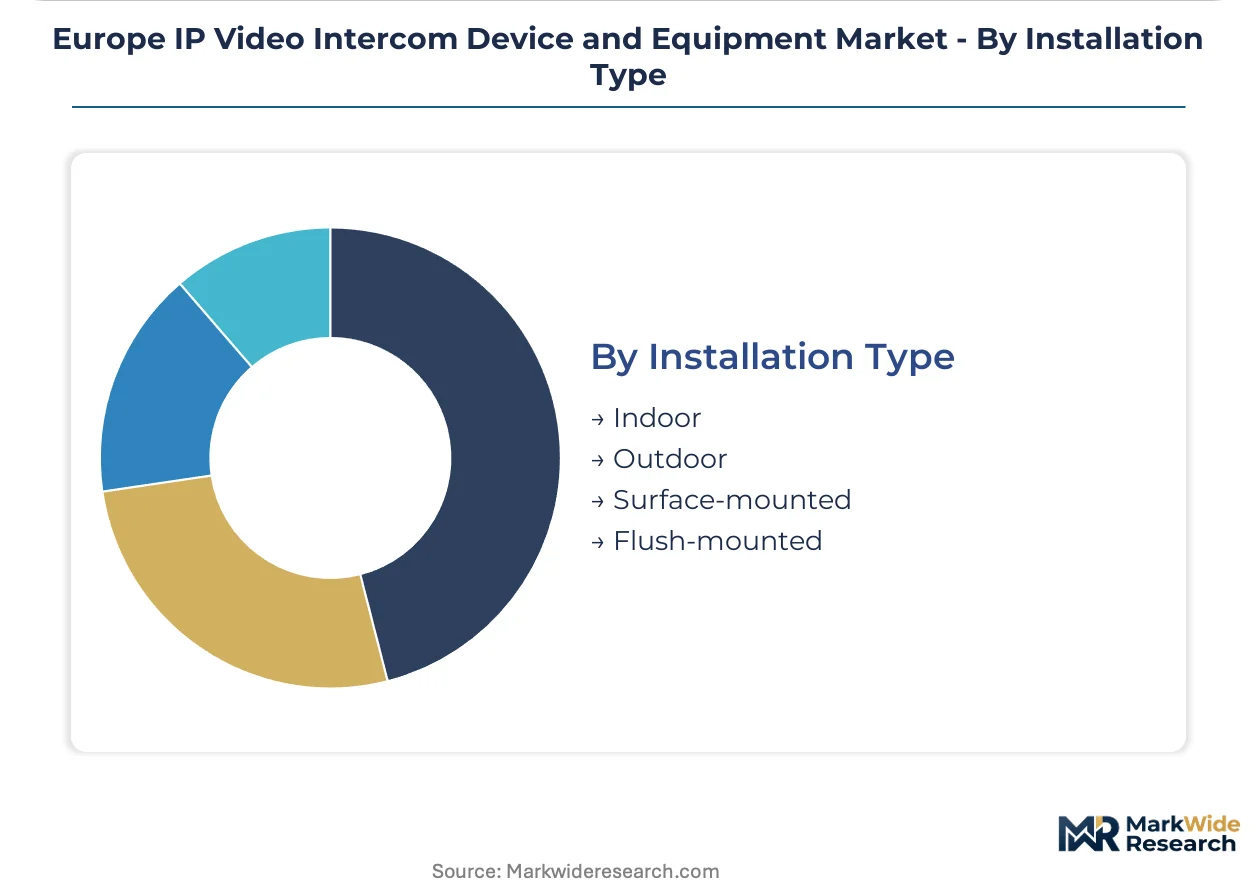
Installation Type:
Mounting configuration shapes contractor specialization requirements and aesthetic integration constraints across building vintages.
- Outdoor:Hardened enclosures rated for IP65 environmental protection and EN 50121 electromagnetic compatibility, required for rail station and airport deployments in transportation verticals. These installations demand the highest capital allocation for thermal management and vandal resistance engineering.
- Flush-mounted:Recessed wall integration preserving architectural finishes in premium residential and hospitality settings, requiring precise rough-in coordination with general contractors.
- Indoor:Climate-controlled environment units serving apartment interiors and reception desks, with simplified installation protocols.
- Surface-mounted:Exposed retrofit installations minimizing tenant disruption in aging commercial stock where wall cavity access proves impractical.
Outdoor hardened systems carry premium engineering overhead; flush-mounted configurations are expanding most quickly in premium residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates manufacturing capacity for premium IP intercom hardware, while France and the Benelux region absorb the dominant share of commercial retrofit demand. This production-consumption split shapes vendor logistics strategies across the continent.
Germany
Smart residential construction in Bavaria and North Rhine-Westphalia drives cloud-connected entry system procurement, with property developers bundling intercom services into tenant service charges. The EU AI Act's biometric risk classifications force re-engineering of facial recognition modules by German manufacturers. Berlin-Brandenburg hosts specialized engineering firms supplying hardened systems for transportation verticals requiring EN 50121 certification.
France
Paris commercial real estate investment trusts accelerate multi-tenant analog-to-IP consolidations to align with EU Green Deal efficiency mandates. CNIL enforcement of GDPR video storage provisions compels vendors to maintain EU-resident data centers. The Île-de-France corridor concentrates demand for integrated access control platforms with visitor audit logging capabilities.
Netherlands
Amsterdam property managers adopt browser-administered intercom platforms for multi-site portfolio administration without IT staffing expansion. The Radio Equipment Directive's CE marking pathways create compliance bottlenecks for non-European suppliers entering Dutch distribution channels. Randstad urban cores exhibit highest penetration of PoE-based single-cable deployments in new commercial construction.
Belgium
Brussels commercial retrofits prioritize centralized tenant credential management systems for GDPR-compliant visitor tracking. Federal building efficiency regulations mandate networked entry infrastructure upgrades in aging commercial stock. Flemish industrial clusters supply structured cabling components supporting 802.3at Power-over-Ethernet installations.
Italy
Milan and Rome smart building integrators specify deep interoperability with established automation ecosystems, favoring vendors with legacy protocol expertise. Italian building codes for heritage structures drive demand for wireless and surface-mounted retrofit configurations where conduit runs prove impractical. Lombardy-based installer networks maintain entrenched relationships with domestic equipment suppliers.
Europe IP Video Intercom Device and Equipment Market Competitive Landscape
The competitive structure tilts toward specialized mid-cap manufacturers with deep regional installer relationships rather than consolidated multinational electronics conglomerates. Engineering-intensive archetypes dominate premium segments, while scale-driven assemblers compete on lead-time fulfillment for standardized residential units. Two strategic archetypes prevail: German-based hardware specialists leveraging manufacturing proximity for short-lead-time delivery, and Italian-anchored systems integrators bundling intercom platforms with broader building automation portfolios. Dominant competitive moves include geographic expansion through distributor partnerships in Eastern European whitespace markets and portfolio diversification into AI Act compliance services for biometric video analytics.
Among German-based manufacturers, Doorbird (Bird Home Automation GmbH), Commend International GmbH, and Loxone Electronics GmbH exemplify the engineering-specialist archetype. Doorbird occupies a position anchored in premium residential fulfillment capabilities. Commend International GmbH sits within the critical infrastructure vertical, representing hardened system expertise for transportation applications. Loxone Electronics GmbH exemplifies smart building ecosystem integration. Italian presence concentrates through Urmet Spa, which anchors the Mediterranean automation-integrator archetype with deep installer network penetration. British and Czech competitors including Paxton Access Ltd and 2n Telekomunikace occupy positions on the scale-driven, multi-tenant commercial vector.
| Leading Market Players |
|---|
| Doorbird (Bird Home Automation GmbH) |
| Commend International Gmbh |
| Urmet Spa |
| Paxton Access Ltd |
| Loxone Electronics Gmbh |
| Siedle |
| Bas-ip Intercom Systems |
| Farfisa |
| 2n Telekomunikace |
| Others |
Supply & Pricing Matrix
Copper conductor and PoE switch component costs cascade through three distinct pricing tiers, with German-manufactured hardware commanding premiums against Asian-assembled alternatives subject to Radio Equipment Directive certification delays. Structured cabling labor rates in Northern Europe amplify the total cost of ownership gap between wired infrastructure and wireless retrofit configurations.
Pricing Analysis
Value-based pricing anchored to system uptime guarantees and GDPR compliance outcomes separates premium vendors from commodity assemblers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by CE marking tier, installer certification depth, and after-sales service bundling. Cost compression in economy-tier residential units intensifies because Polish and Czech contractors source unbranded Asian hardware through gray distribution channels. Commercial property managers in France and the Benelux show least price sensitivity, prioritizing audit logging capabilities and multi-site administration platforms over unit economics.
Supply Chain Analysis
CE marking and ETSI EN 301 489 electromagnetic compatibility certification gate market access for non-European suppliers, creating six-to-twelve month qualification timelines that favor established German and Italian manufacturers. Component sourcing draws from Taiwan for PoE chipsets, China for camera sensor modules, and Germany for precision mechanical enclosures. Single-source vulnerability concentrates in Asian foundry capacity for semiconductor switching fabric. Distribution runs through specialized building automation distributors in Germany, France, and Italy, with installer relationships determining downstream access rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive certification expertise and installer network control, as the EU AI Act's biometric risk classifications force engineering retooling costs that weaker players cannot absorb.
For Market Incumbents: To counter cloud-native entrants compressing deployment timelines, deepen backward integration into PoE switch manufacturing to sustain margin pools against hardware commoditization. Anchor channel control through exclusive installer certification programs in France and the Benelux, where multi-tenant commercial retrofits concentrate procurement volume.
For New Entrants and Emerging Players: Launch via white-label partnerships with Eastern European distributors targeting Poland, Czechia, and Romania, where IP intercom penetration in residential construction remains below fifteen percent. Prioritize wireless and surface-mounted retrofit configurations for Italian heritage building stock, where conduit installation proves impractical and domestic suppliers lack specialized form factors.
For Investors and Strategic Acquirers: First conformity assessments under the EU AI Act by French and German regulators are the leading indicator that biometric video analytics capabilities will become mandatory differentiators rather than premium options. Target acquisition profiles center on mid-cap engineering specialists with EN 50121 transportation certification and established notified body relationships, positioned for mandatory EU cybersecurity rating schemes.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Compliance Service Development | Biometric audit capabilities create recurring revenue streams as French and German regulators enforce conformity assessments. |
| Eastern European Distribution Partnership | First-mover positioning in Poland, Czechia, and Romania captures sub-fifteen-percent penetration whitespace before incumbent expansion. |
| EN 50121 Certification Investment | Transportation vertical access for rail stations and airports requires hardened electromagnetic compatibility credentials. |
| Cloud-Native Platform Migration | Browser-administered architectures displace on-premise servers for German mid-size property management firms. |
| Installer Network Exclusive Arrangements | Channel control in Italy and the Benelux determines downstream access more than direct OEM sales capability. |
Research Methodology
Independent corroboration across primary interviews with building automation integrators, structured cabling contractors, property management procurement officers, and notified body certification specialists underwrites the qualitative findings. Secondary validation draws from ETSI standards documentation, CE marking registry databases, EU regulatory filings, and national building efficiency mandate records. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition across product type, technology protocol, end-user vertical, and installation configuration dimensions structures the analytical framework. CAGRs derive from segmented volume and value build-ups incorporating PoE deployment velocity, cloud platform adoption curves, and retrofit cycle timing. Industry-specific forecast inputs include GDPR data residency infrastructure build-out rates and EU AI Act implementation timelines.
Copper commodity volatility, semiconductor foundry allocation shifts, and cybersecurity certification scheme acceleration are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in notified body processing timelines or mandatory EU cybersecurity rating implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Unified Threat Management (UTM) Market
Security Software
Hardware Encryption Market
Security Software
Secaas Market
Security Software
Stalkerware Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Doorbell Camera Market
Security Software
Global IMSI Catcher Market
Security Software
Mobile Identity Management Market
Security Software
Global Data Breach Notification Software Market
Security Software
Digital Credential Management Software Market
Security Software
Video Intercom Devices and Equipment Market
Security Software
Global User Activity Monitoring Market
Security Software
Global User Provisioning Market
Security Software
Key Management Service Market
Security Software
ATM Security Market