
 Leather Cutting Machine Market | 2026-2036
Leather Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Cutting Machine Market Insights
Multi-source procurement among tier-one tanneries is repositioning equipment vendor relationships across the leather cutting machine supply base. Lectra sustains technology leadership through embedded nesting software and connected workflow platforms. Fratelli Carlessi Srl anchors its position in Italian artisan-grade machinery, serving heritage footwear and luxury leather goods producers. AMOR competes on price-accessible CNC configurations for mid-scale upholstery shops in Eastern Europe and Southeast Asia.
A leather cutting machine mechanically severs hides and skins into precise patterns using blades, lasers, or water jets operating at pressures up to 60,000 psi for jet-based systems, with CNC-controlled gantry systems achieving repeatability within 0.1 mm for high-value automotive upholstery. The equipment serves tanneries, contract manufacturers, and vertically integrated brands seeking yield optimization from irregular raw material geometries. CNC product types command the widest installed base expansion as programming simplicity reduces operator skill barriers across emerging manufacturing centers. Laser technology segments attract premium positioning where edge-sealing and minimal kerf waste justify higher capital outlay for exotic leather applications.
EU REACH restrictions on chromium tanning effluents and China's GB standards for industrial laser safety classification reshape equipment specifications and filter out non-compliant suppliers from these markets. The US OSHA machine guarding standards and California's Proposition 65 labeling requirements add compliance layers for imported cutting systems. Stakeholders must monitor evolving chemical processing regulations alongside automation labor-displacement policies as dual vectors determining equipment replacement timing and technology selection.
Market Dynamics
Automated nesting algorithms and connected workflow platforms are compressing operator skill requirements while tannery-to-finished-goods clusters in Guangdong province drive integrated equipment procurement decisions across Asia-Pacific manufacturing floors.
Growth Catalysts
- REACH effluent mandates:EU chromium tanning restrictions accelerate replacement cycles as European tanneries retire non-compliant cutting systems ahead of enforcement deadlines.
- Export quality requirements:Footwear manufacturers in Vietnam and India expand automated cutting floors to satisfy international buyer specifications for precision and traceability.
- GB laser safety standards:China's industrial machinery safety classifications filter out non-compliant suppliers, creating procurement pull for certified CNC gantry systems.
Market Restraints
- Exotic hide price volatility:Irregular raw material geometries from crocodile and ostrich suppliers concentrate cost risk in luxury automotive upholstery segments.
- Component supply concentration:High-pressure pump assemblies for water-jet systems depend on a narrow German and Italian supplier base vulnerable to extended lead times.
- Edge-sealing limitations:Blade-based systems cannot match laser kerf quality on full-grain exotic leathers, restricting technology choice in premium applications.
Strategic Opportunities
- Indonesian contract manufacturing:Mid-scale upholstery shops in Java and Sumatra remain underpenetrated by CNC configurations priced for Eastern European accessibility.
- AI-actuated nesting convergence:Machine vision integration with generative pattern algorithms opens yield optimization white space beyond traditional CAD-CAM workflows.
- Aftermarket service unbundling:Remote diagnostics platforms enable subscription-based maintenance models distinct from historical bundled warranty structures.
Industry Challenges
- CNC programming expertise gaps:Emerging manufacturing centers in Southeast Asia face shortages of operators capable of optimizing gantry path algorithms for irregular hide geometries.
- Multi-jurisdiction certification timelines:Simultaneous OSHA machine guarding, CE marking, and GB standard compliance extends product launch cycles for equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Cutting Machine Market |
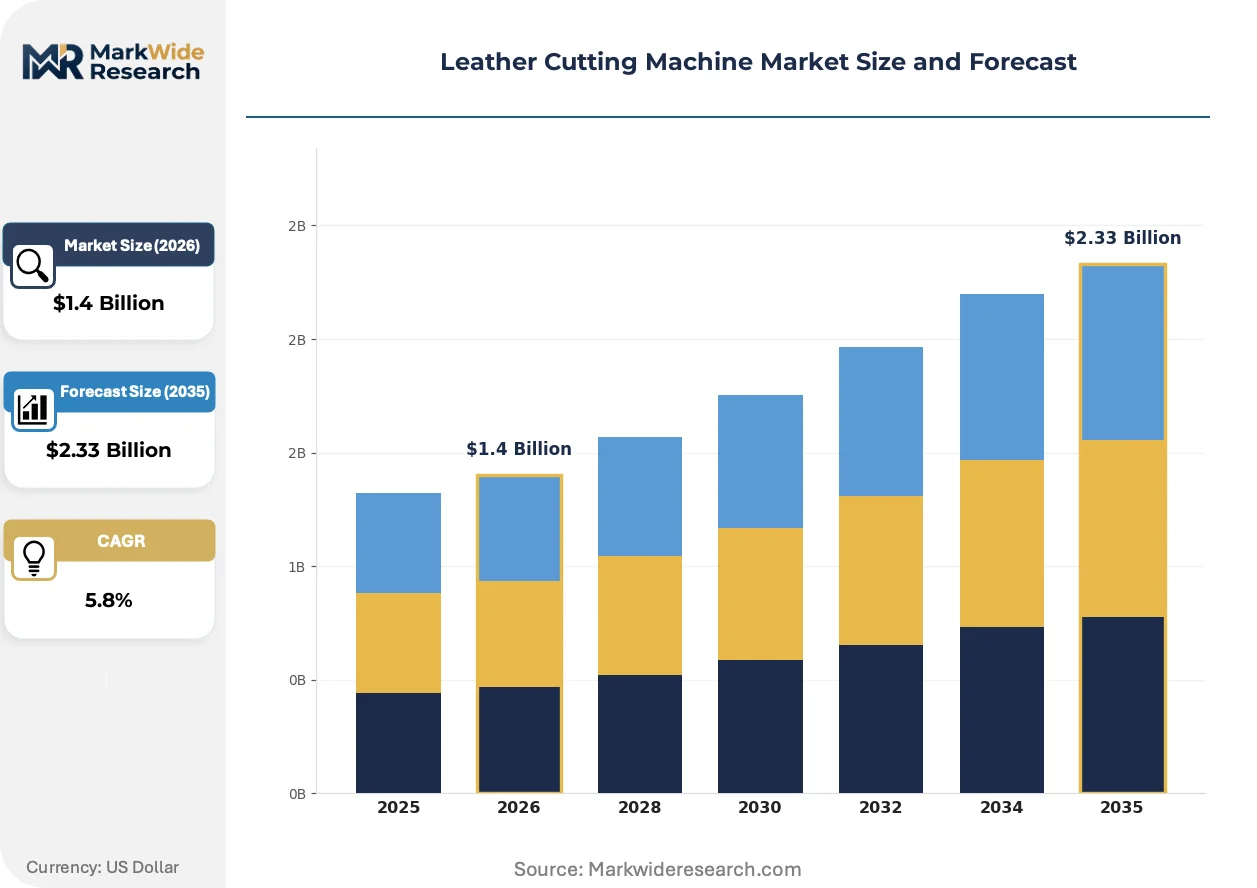
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Hydraulic, CNC Technology: Laser, Rotary Blade, Die-Cutting, Water Jet End User: Footwear Manufacturers, Automotive Suppliers, Upholstery Providers, Fashion Designers Application: Custom Leather Goods, Industrial Applications, Fashion Accessories, Upholstery |
| Companies Covered | Oshima, Jinan Top CNC Machines Co., Ltd., Aletti Giovanni & Figli Srl, Fratelli Carlessi Srl, AMOR, Edgemills, Leather Machine Co, Gerber Technology, Lectra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Cutting Machine Market Trends and Innovations
Digital thread integration from hide grading through finished pattern cutting is collapsing traditional process silos. Vendors now compete on workflow continuity rather than isolated machine specifications.
Vision-guided nesting software is electrifying yield optimization in high-value automotive upholstery. Tier-one seating suppliers in Germany and the United States deploy these systems at accelerated cadences. The technology is electrifying competitive differentiation around material efficiency guarantees rather than throughput metrics alone.
EU F-Gas Regulation phase-down schedules pressure refrigerant-dependent laser cooling systems in European installations. Industrial buyers face retrofit decisions or alternative technology selection. Automotive leather goods producers in Italy and Spain absorb the highest compliance burden through accelerated capital cycles.
Buyer consortiums among heritage footwear brands are consolidating equipment procurement decisions previously fragmented across individual tannery relationships. Italian artisan-grade machinery vendors face concentrated negotiation leverage from coordinated purchasing committees. This concentration is most visible in Tuscany and Marche regional clusters serving luxury export markets.
Leather Cutting Machine Market Segmentation
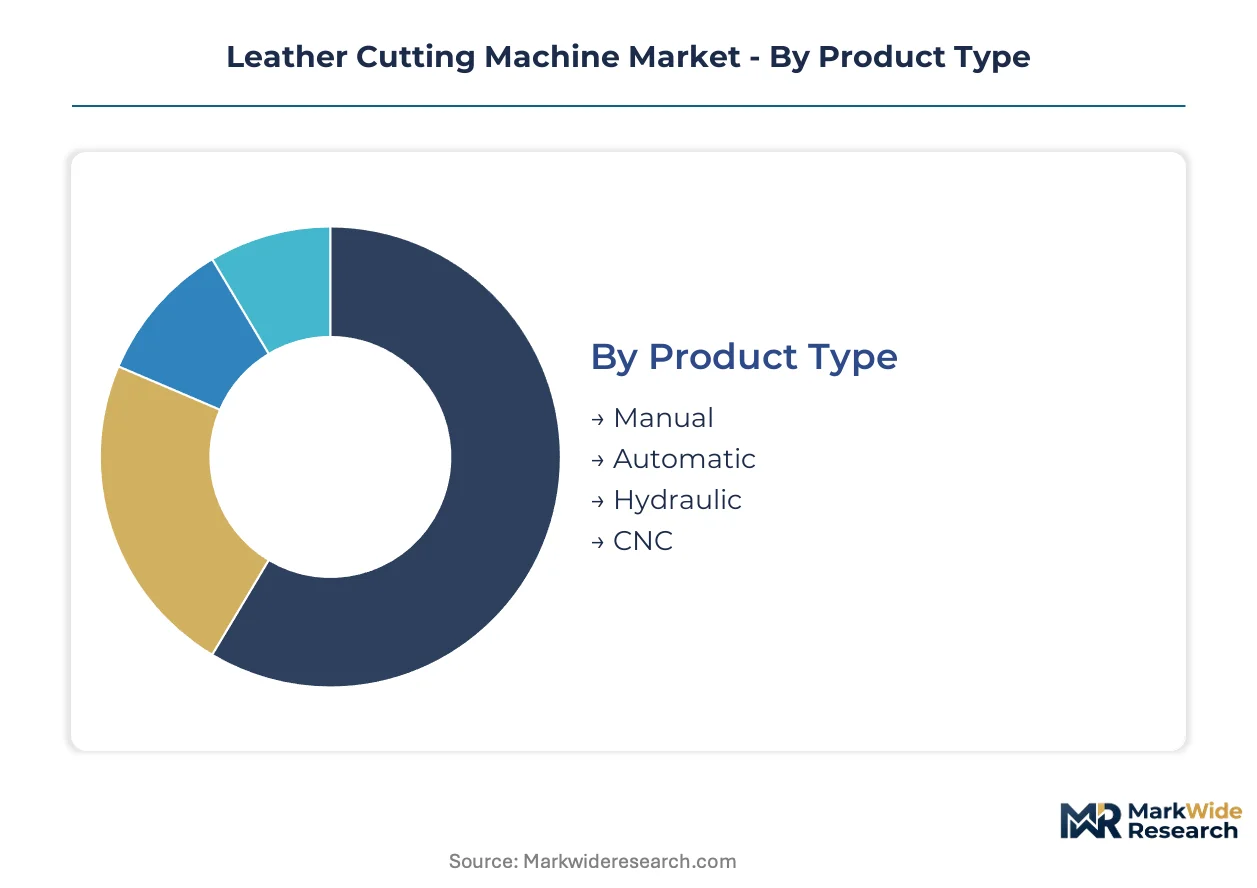
Leather cutting equipment selection hinges on material value, volume requirements, and regulatory constraints that vary sharply across end-use applications. Procurement decisions in Guangdong province and Vietnam's export zones demonstrate how technology-product pairings cluster around specific manufacturing workflows.
Product Type:
Supply concentration in high-precision CNC assemblies favors vendors with integrated software platforms over standalone mechanical suppliers.
- CNC:Computer numerical control systems achieve 0.1 mm repeatability through gantry-mounted cutting heads with programmable path optimization. Demand concentrates in China's Guangdong province where tannery-to-finished-goods clusters require yield-maximizing automation for irregular hide geometries. GB standards for industrial machinery safety filter procurement toward certified configurations.
- Automatic:Automated nesting systems compress operator skill barriers while maintaining throughput for mid-scale upholstery producers. Vietnam's footwear export manufacturers deploy these systems to satisfy international buyer traceability requirements without full CNC programming overhead.
- Hydraulic:High-force mechanical cutting for thick leather stacks serves traditional tannery operations with established maintenance capabilities.
- Manual:Hand-operated clicker presses persist in artisan footwear workshops and small-batch fashion accessory production.
Today's leader: CNC. Tomorrow's challenger: Automatic.
Technology:
Cost tier differentiation separates premium edge-sealing applications from volume-focused mechanical cutting.
- Laser:Thermal cutting systems seal edges during severance, eliminating post-processing for exotic leathers in automotive upholstery. EU F-Gas Regulation phase-down pressures refrigerant-dependent cooling retrofits in Italian and Spanish installations.
- Water Jet:Abrasive jet systems operating at 60,000 psi cut without heat-affected zones, preserving full-grain integrity for luxury goods. Component supply concentration in German and Italian high-pressure pump assemblies creates lead time vulnerability.
- Rotary Blade:Continuous blade rotation suits high-speed nesting of standard upholstery hides where kerf quality tolerances permit mechanical severance.
- Die-Cutting:Steel rule dies deliver economical pattern replication for high-volume footwear components with standardized geometries.
Today's leader: Laser. Tomorrow's challenger: Water Jet.
End User:
Application-specific precision requirements drive technology selection across customer types with diverging capital deployment timelines.
- Automotive Suppliers:Tier-one seating manufacturers in Germany and the United States deploy vision-guided nesting for material efficiency guarantees on high-value upholstery contracts. REACH chromium tanning restrictions reshape raw material sourcing alongside cutting equipment specifications.
- Footwear Manufacturers:Vietnam and India export producers expand automated cutting floors to meet international buyer precision standards. Buyer consortiums among heritage Italian brands concentrate negotiation leverage toward artisan-grade machinery vendors.
- Upholstery Providers:Mid-scale Eastern European and Southeast Asian shops prioritize price-accessible CNC configurations with simplified programming interfaces.
- Fashion Designers:Small-batch custom producers favor manual and semi-automatic systems for prototype flexibility.
Today's leader: Automotive Suppliers. Tomorrow's challenger: Footwear Manufacturers.
Application:
Volume concentration in standardized industrial output contrasts with margin premiums in bespoke production segments.
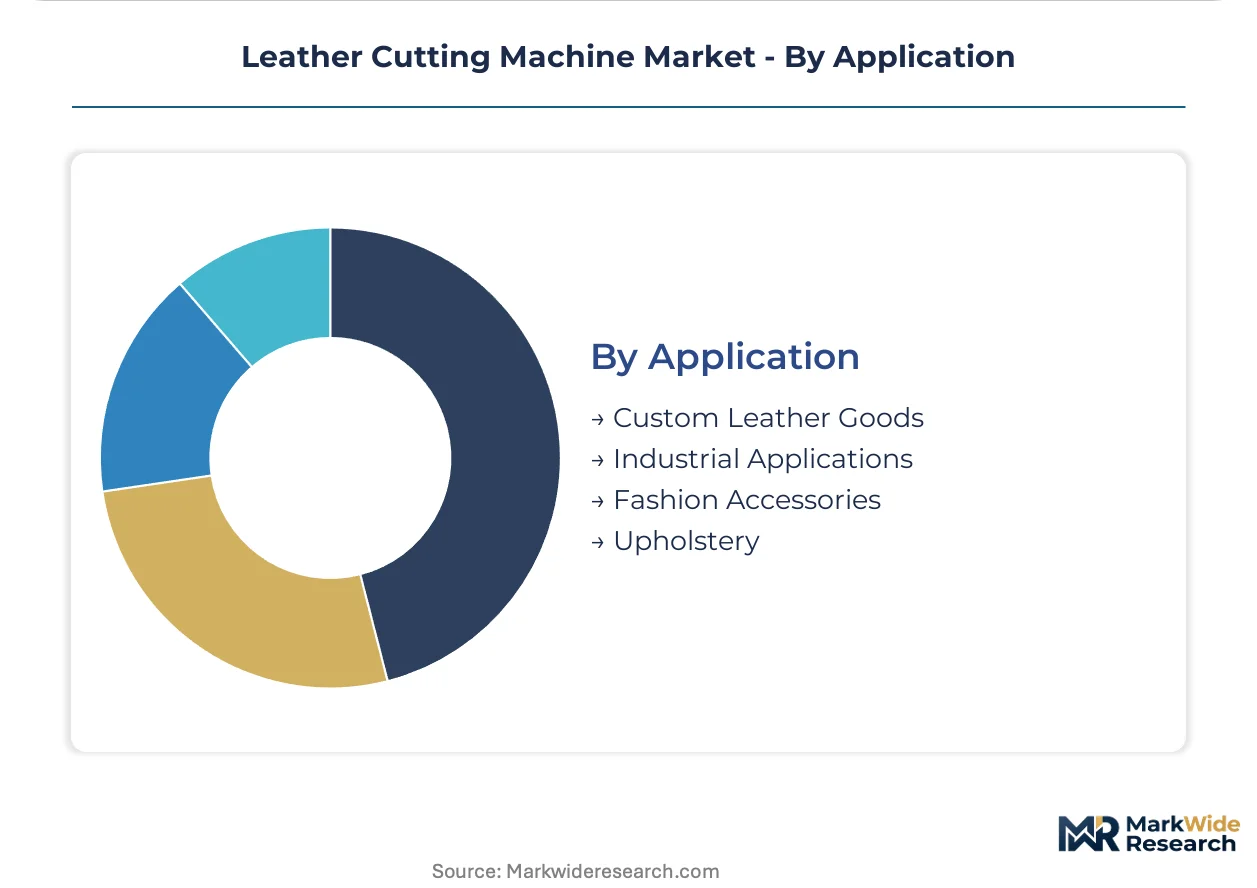
- Industrial Applications:High-volume contract manufacturing for automotive and mass footwear sectors commands the widest equipment deployment. OSHA machine guarding and CE marking requirements extend vendor certification timelines for multi-jurisdiction sales.
- Custom Leather Goods:Bespoke production for luxury accessories and small-batch footwear sustains demand for programmable systems with rapid pattern changeover. Italian Tuscany and Marche regional clusters anchor heritage machinery procurement.
- Upholstery:Residential and commercial furniture applications balance material yield against throughput in mid-market equipment configurations.
- Fashion Accessories:Handbag and small goods production favors die-cutting and rotary blade economics for repetitive pattern volumes.
Today's leader: Industrial Applications. Tomorrow's challenger: Custom Leather Goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province's tannery-to-finished-goods clusters command the dominant share of leather cutting equipment procurement, with integrated manufacturing floors driving synchronized technology adoption across Asia-Pacific production networks.
China
Guangdong province anchors equipment demand through vertically integrated leather goods manufacturing corridors stretching from raw hide processing to finished automotive upholstery. GB standards for industrial laser safety classification filter procurement toward certified CNC gantry systems, eliminating non-compliant suppliers from state procurement channels. Dongguan and Foshan municipal clusters specialize in high-volume contract manufacturing for export footwear brands.
Germany
Tier-one automotive seating suppliers deploy vision-guided nesting systems for material efficiency guarantees on premium upholstery contracts. EU F-Gas Regulation phase-down schedules pressure refrigerant-dependent laser cooling retrofits across Baden-Württemberg and Bavaria manufacturing installations. Stuttgart's automotive leather cluster concentrates technology deployment for Mercedes-Benz and Porsche supply chains.
Italy
Heritage footwear brands in Tuscany and Marche regional clusters sustain demand for artisan-grade machinery with programmable pattern changeover capabilities. REACH chromium tanning restrictions reshape raw material sourcing alongside cutting equipment specifications for luxury export producers. Florence-based buyer consortiums concentrate negotiation leverage toward specialized machinery vendors.
Vietnam
Export footwear manufacturers expand automated cutting floors to satisfy international buyer traceability requirements without full CNC programming overhead. The country's national industrial safety regulator enforces machinery certification standards aligned with European export market expectations. Ho Chi Minh City industrial zones concentrate mid-scale upholstery shops transitioning from manual to automatic nesting systems.
United States
Automotive leather goods producers absorb compliance burdens through accelerated capital cycles driven by California's Proposition 65 labeling requirements and federal OSHA machine guarding standards. Tier-one seating suppliers in Michigan and Ohio deploy yield-optimization technology for domestic OEM contracts. Detroit-area manufacturing corridors anchor industrial application demand for high-precision cutting systems.
Leather Cutting Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue price-accessible CNC configurations for mid-scale upholstery shops. The vendor base stratifies across three maturity levels: heritage European specialists, integrated software-hardware platforms, and regional fabricators serving localized demand. Three archetypes dominate competitive positioning: technology-integrated solution providers, artisan-grade machinery specialists, and volume-focused equipment assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with vendors prioritizing aftermarket service unbundling and remote diagnostics platforms.
Within the heritage machinery tier, Fratelli Carlessi Srl exemplifies Italian artisan-grade specialization serving luxury leather goods producers. Lectra occupies a position representing integrated software-hardware platforms with embedded nesting capabilities and connected workflow systems. AMOR anchors the price-accessible segment, with Jinan Top CNC Machines Co., Ltd. representing Chinese regional fabricators targeting Eastern European and Southeast Asian mid-scale installations.
| Leading Market Players |
|---|
| Oshima |
| Jinan Top CNC Machines Co., Ltd. |
| Aletti Giovanni & Figli Srl |
| Fratelli Carlessi Srl |
| AMOR |
| Edgemills |
| Leather Machine Co |
| Gerber Technology |
| Lectra |
| Others |
Pricing and Supply Chain Analysis
CNC programming specialists in Vietnam and Indonesia compress labor-cost differentials into pricing-tier spreads across automated and manual equipment categories. REACH compliance investments in European tanneries widen premium-standard-economy gaps as certification overhead concentrates in higher tiers.
Pricing Analysis
Input-cost pass-through from German and Italian high-pressure pump assemblies concentrates pricing pressure in water-jet system tiers. Three-tier pricing structure across premium, standard, and economy levels separates laser CNC configurations with embedded nesting software from basic gantry systems and refurbished hydraulic presses. Pricing pressure stems from component supply concentration as lead time volatility feeds into equipment financing terms. Mid-scale upholstery shops in Eastern Europe exhibit highest price sensitivity, while tier-one automotive seating suppliers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Refurbishment flows for CNC gantry systems create secondary market circulation between European automotive suppliers and Southeast Asian contract manufacturers. Component manufacturing concentrates in Germany, Italy, and China, with high-pressure pump assemblies and precision linear motion systems drawing from specialized regional fabricators. Supply chain risk centers on single-source vulnerability for 60,000 psi pump assemblies as extended lead times cascade through equipment delivery schedules. Distribution runs through OEM-direct channels for large installations and regional machinery distributors for mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leather cutting machine market compounds steadily as regulatory compliance mandates in Europe and China force predictable replacement cycles across installed base expansions.
For Market Incumbents: To counter price-accessible CNC entrants from Chinese regional fabricators, deepen software-hardware integration through embedded AI-actuated nesting platforms and establish captive service networks in Vietnam's export zones. Certification investment in simultaneous OSHA, CE marking, and GB standard compliance extends product launch cycles but filters out non-compliant competitors. For New Entrants and Emerging Players: Enter via Indonesian contract manufacturing clusters in Java and Sumatra, where mid-scale upholstery shops remain underpenetrated by automatic nesting systems priced for Eastern European accessibility. Target aftermarket service unbundling through remote diagnostics subscriptions as the primary go-to-market angle, displacing historical bundled warranty structures with recurring revenue models. For Investors and Strategic Acquirers: Tier-one automotive seating suppliers are the most active acquirer in this space, consolidating vision-guided nesting capabilities for material efficiency guarantees on premium upholstery contracts. Over the extended horizon, acquisition targets cluster around software-integrated platform vendors with established GB standard certification. Monitor EU F-Gas Regulation enforcement timelines as inflection indicators for laser cooling retrofit demand and alternative technology selection.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Nesting Software Development | Lectra sustains technology leadership through connected workflow platforms that compress operator skill barriers. |
| Aftermarket Service Unbundling | Remote diagnostics platforms enable subscription-based maintenance models distinct from bundled warranty structures. |
| Multi-Jurisdiction Certification Investment | Simultaneous OSHA, CE marking, and GB compliance extends launch cycles but eliminates non-compliant suppliers. |
| Machine Vision Integration | AI-actuated nesting convergence opens yield optimization white space beyond traditional CAD-CAM workflows. |
| Regional Capacity Expansion | Vietnam's footwear export manufacturers expand automated cutting floors to satisfy international buyer traceability requirements. |
Research Methodology
Coverage spans China, Germany, Italy, Vietnam, and the United States, with primary inputs from each market combining interviews with plant engineers, OEM procurement teams, aftermarket service heads, and tannery operations managers alongside secondary validation. Secondary sources include customs and trade data, SEC filings from publicly traded equipment vendors, industrial machinery safety certification databases, and regional production statistics. Bottom-up equipment deployment estimates triangulate against top-down market value reconstruction across the analysis window.
Rate-of-change decomposition separates volume expansion from price-mix effects across product type, technology, end user, and application dimensions throughout the forecast period. CAGRs derive from segmented growth trajectory modeling with cross-validation against macroeconomic indicators and industry-specific inputs including REACH enforcement timelines, GB standard adoption curves, and automotive upholstery contract award patterns.
Inputs from certification databases and trade statistics were available through the study window; gaps in private equipment transaction pricing introduce uncertainty bands around market value estimates. Practitioners should monitor EU F-Gas Regulation phase-down schedules and emerging manufacturing center labor cost trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Squeegee Market
Tools
Orbital Recip Saw Market
Tools
Automatic Lathe Machines Market
Tools
Bottle Jack Market
Tools
Horizontal Milling Machine Market
Tools
Leather Embossing Machine Market
Tools
Entrenching Tool Market
Tools
US Hitter Based Hand Tools Market
Tools
Friction Washer Market
Tools
Bearing Installation Tool Kit Market
Tools
Metal Cutting Tools Market
Tools
Drill Bit Market
Tools
Industrial Floor Scrubber Market
Tools
Mechanical Hand Tools Market
Tools
Sander Market
Tools
Extensometer Market