
 Tapping Machine Market | 2026-2036
Tapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tapping Machine Market Analytics
The EU Machinery Directive is expanding compliance requirements for automated metalworking equipment across European manufacturing floors. DMG MORI leverages its integrated spindle technology to serve aerospace thread-machining contracts in Germany and Japan. Yamazaki Mazak Corporation anchors its position through dedicated tapping centers optimized for automotive powertrain production. FANUC Corporation competes by embedding force-controlled tapping cycles into its robotic machining cells.
A tapping machine is a machine tool engineered to cut internal threads into pre-drilled holes using a rotating tap held in a rigid spindle with controlled feed rates and torque limits; its primary purpose is producing precision-threaded components for assembly-critical applications across metalworking industries. Electric tapping machines dominate volume shipments due to their balance of portability and repeatability in job shop environments, while CNC tapping systems capture the highest margin pools through multi-axis synchronization and unmanned operation in automotive and aerospace production lines. Multi-spindle tapping technology is displacing conventional single-spindle units in high-volume electronics assembly where cycle time compression determines contract awards.
OSHA machine guarding standards in the United States and the EU Machinery Directive collectively mandate interlocked enclosures and emergency stop protocols that elevate equipment costs but also filter out uncertified suppliers. Japan's METI promotes smart factory adoption through JIS-compliant connected machine tools, including tapping systems with predictive maintenance interfaces. Stakeholders must monitor how China's GB standards evolution and its dual carbon goals reshape import requirements for foreign-built precision equipment.
Market Dynamics
Automotive powertrain electrification is forcing thread-machining tolerances tighter than legacy mechanical systems required, pulling precision tapping equipment onto every major OEM's capital expenditure slate.
Growth Catalysts
- EU Machinery Directive compliance mandates:European metalworking floors must replace unguarded legacy equipment with interlocked automated systems, creating replacement demand across Germany, Italy, and France.
- China's automotive build-out:Domestic machine tool builders are scaling CNC tapping centers to supply local EV battery tray and motor housing production lines.
- Multi-spindle synchronization:Electronics contract manufacturers in South Korea and Taiwan are adopting parallel-tapping architectures to compress cycle times on smartphone chassis contracts.
Market Restraints
- High-alloy tool steel volatility:Tap and collet raw material costs swing with nickel and cobalt exchange prices, squeezing margin predictability for mid-tier equipment suppliers.
- Single-source spindle bearing concentration:Precision angular-contact bearing supply clusters in southern Germany and western Japan create vulnerability for builders outside those geographies.
- Substitution by cold-forming:Flange and fastener makers in high-volume automotive applications are shifting to thread-rolling where material ductility permits, eliminating cutting taps entirely.
Strategic Opportunities
- India's PLI scheme for machine tools:Component-level incentives for precision equipment are attracting joint-venture assembly operations to serve domestic automotive and defense threading demand.
- Force-controlled robotic tapping:Convergence of collaborative robot arms with torque-feedback spindles is opening unmanned job-shop applications previously reserved for dedicated CNC cells.
- Predictive maintenance interfaces:JIS-compliant connected tapping systems with METI-backed smart factory certification command premium positioning in Japanese and Southeast Asian markets.
Industry Challenges
- Multi-axis programming skill scarcity:Synchronized tapping on five-axis machining centers requires CAM competency that vocational pipelines in North America and Western Europe are not filling.
- CE-MDR dual certification timelines:Builders targeting both European machinery safety and medical device threading markets face eighteen-month approval cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapping Machine Market |
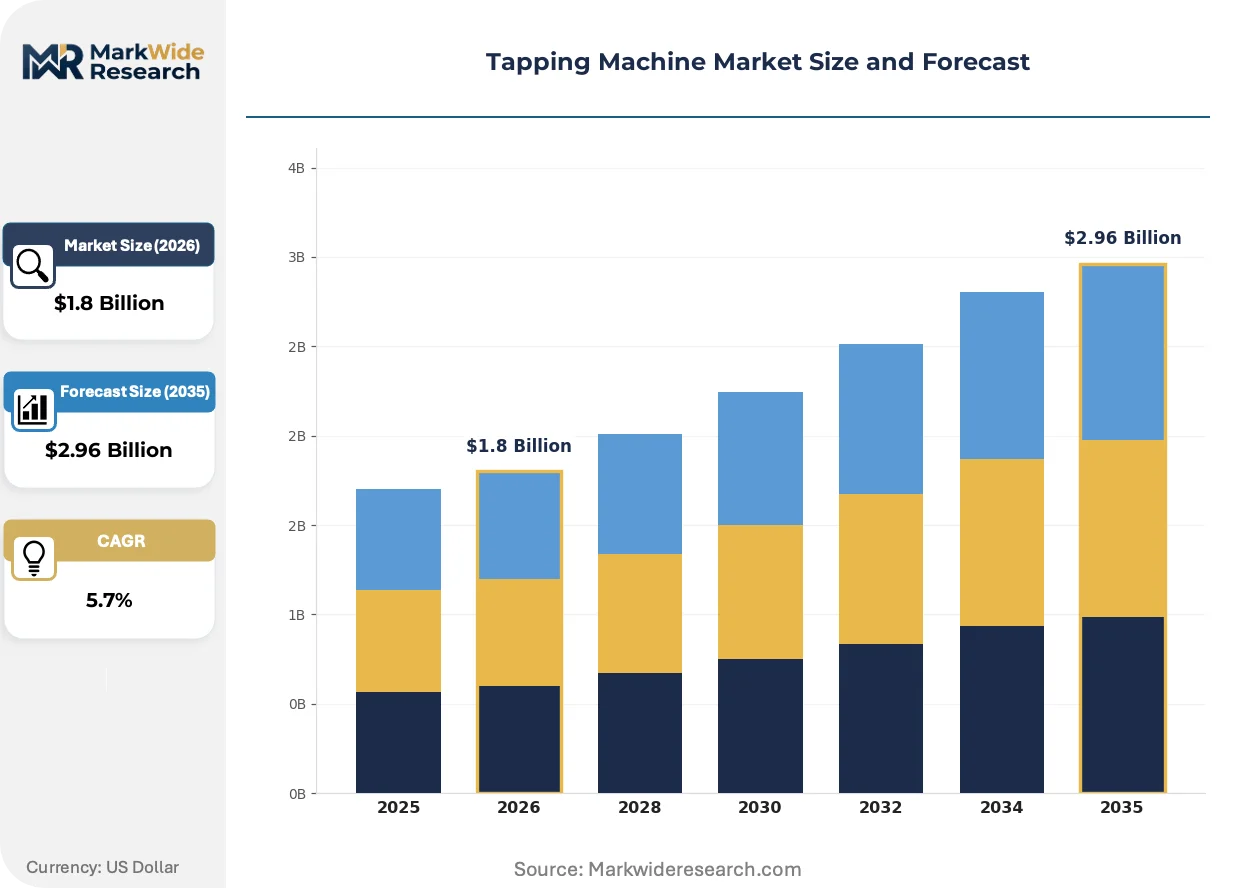
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tapping Machine, Electric Tapping Machine, Pneumatic Tapping Machine, Radial Tapping Machine Application: Automotive Manufacturing, Aerospace Component Machining, Construction Equipment Production, Electronics Assembly End User: OEMs, Tier-1 Suppliers, Machine Shops, SMEs Technology: CNC Tapping, Conventional Tapping, Multi-Spindle Tapping, Automated Tapping |
| Companies Covered | DMG MORI, Yamazaki Mazak Corporation, Okuma Corporation, HAAS Automation, Brother Industries, Baileigh Industrial, FANUC Corporation, Hardinge Inc., Roscamat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapping Machine Market Evolving Landscape
Thread-machining technology is fragmenting across precision tiers, with portable electric units, fixed CNC centers, and robotic cells each carving distinct application territories based on tolerance requirements and lot sizes.
Portable electric tapping arms with integrated torque feedback are decentralizing precision threading from centralized machining departments onto assembly floors. Tier-two automotive suppliers in Mexico and Poland are deploying these units at weld stations to eliminate WIP transport to distant machine shops. This topology shift is compressing floor-space requirements and reducing work-in-process inventory holding costs for mid-volume production environments.
Japan's METI smart factory certification program is mandating OPC-UA data interfaces on subsidized equipment purchases. Tapping machine builders must embed spindle load monitoring and tool-life prediction algorithms to qualify for public procurement and incentive schemes. This regulatory architecture favors connected equipment vendors while filtering out legacy mechanical suppliers from public-sector and tier-one automotive contracts.
Contract electronics manufacturers are unbundling after-sales service from equipment purchase, demanding per-thread pricing or availability-guarantee contracts instead of traditional maintenance agreements. This procurement model shift is pressuring OEMs in Taiwan and Malaysia to restructure revenue recognition and build regional spare-part depots. The transformation is most visible in consumer electronics supply chains where annual model turnover demands maximum equipment uptime guarantees.
Tapping Machine Market Segmentation
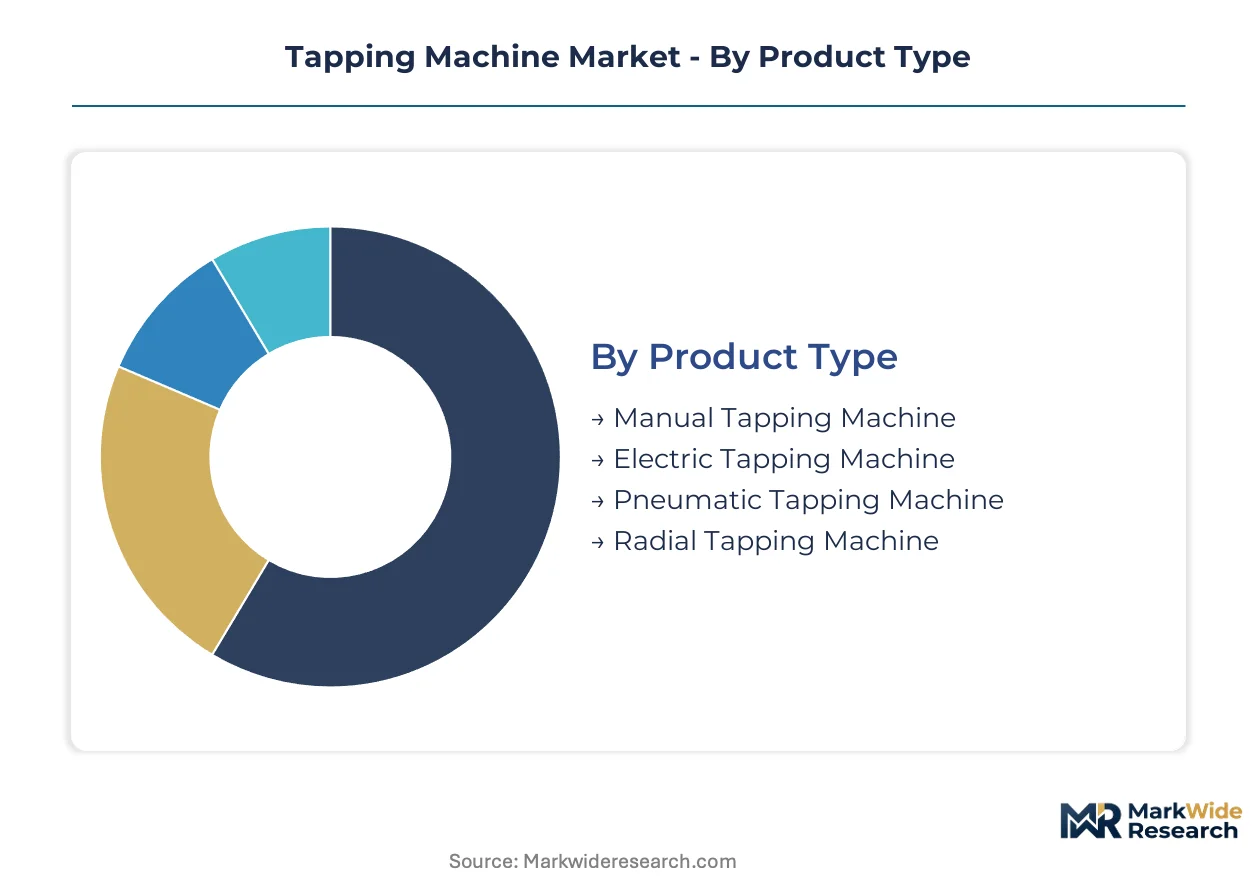
Tapping machine segmentation reveals a market split between high-volume commodity equipment and precision systems commanding substantial margin premiums. Understanding where volume concentrates versus where value accumulates shapes capital allocation decisions for builders and procurement strategies for end-users.
Product Type:
Electric tapping machines dominate shipment volumes through job shop portability, while CNC-class systems capture the steepest margin pools in automated production environments.
- Electric Tapping Machine:These units integrate brushless spindle motors with programmable torque limits for repeatable thread formation. Demand concentrates in German and Italian metalworking clusters where OSHA and EU Machinery Directive compliance mandates are forcing replacement of unguarded legacy equipment.
- Pneumatic Tapping Machine:Compressed-air drive systems deliver high power-to-weight ratios for hazardous environments. Mexican and Polish automotive weld stations are adopting these units to decentralize threading operations from centralized machine shops, compressing work-in-process inventory.
- Manual Tapping Machine:Hand-cranked bench units serve maintenance departments and prototype shops with minimal capital outlay.
- Radial Tapping Machine:Articulated-arm designs extend reach across large workpieces in construction equipment fabrication.
Today's leader: Electric Tapping Machine. Tomorrow's challenger: Pneumatic Tapping Machine.
Application:
Automotive powertrain electrification is pulling precision tapping equipment onto every major OEM's capital expenditure slate, while electronics assembly demands cycle-time compression through parallel processing architectures.
- Automotive Manufacturing:EV battery tray and motor housing production lines require thread tolerances tighter than legacy mechanical systems. China's domestic machine tool builders are scaling CNC tapping centers to supply local automotive build-out.
- Electronics Assembly:Smartphone chassis contracts in South Korea and Taiwan drive multi-spindle synchronization for parallel-tapping architectures. Contract manufacturers are demanding per-thread pricing models instead of traditional maintenance agreements.
- Aerospace Component Machining:Titanium and nickel-alloy threading for turbine housings and structural fasteners requires force-controlled cycles with real-time feedback.
- Construction Equipment Production:Large-bore threading for hydraulic cylinders and frame assemblies favors radial-arm configurations with extended reach.
Automotive Manufacturing commands current volume leadership. Electronics Assembly is climbing the fastest as consumer electronics model turnover accelerates equipment refresh cycles.
End User:
OEMs and Tier-1 suppliers drive specification standards downstream, while SME procurement patterns favor portable electric units with minimal integration requirements.
- OEMs:Original equipment manufacturers mandate JIS-compliant connected machine tools with predictive maintenance interfaces to qualify for METI smart factory subsidies in Japan.
- Tier-1 Suppliers:These stakeholders face eighteen-month CE-MDR dual certification timelines when targeting both European machinery safety and medical device threading markets.
- Machine Shops:Job shop environments balance portability against repeatability, favoring electric tapping arms with integrated torque feedback.
- SMEs:Small and medium enterprises prioritize capital efficiency, often sourcing refurbished conventional equipment or entry-level pneumatic units.
Tier-1 Suppliers currently anchor equipment demand. SMEs are expanding most quickly as India's PLI scheme for machine tools attracts joint-venture assembly operations.
Technology:
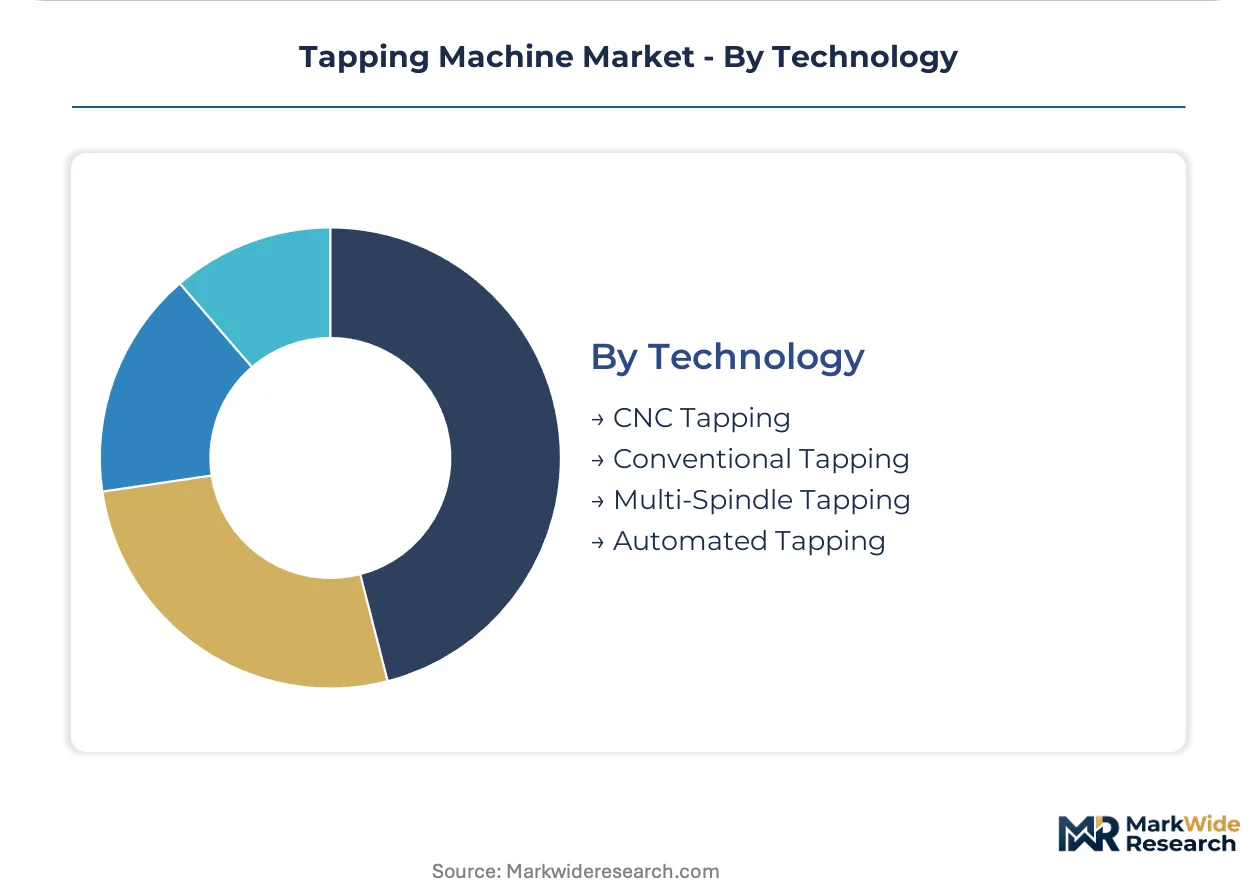
CNC systems with multi-axis synchronization capture premium positioning, while conventional mechanical tapping retains share in cost-sensitive maintenance applications.
- CNC Tapping:Computer-numerical control enables unmanned operation with multi-axis synchronization for automotive and aerospace production lines. DMG MORI leverages integrated spindle technology to serve aerospace thread-machining contracts in Germany and Japan.
- Multi-Spindle Tapping:Parallel spindle architectures compress cycle times through simultaneous hole processing. Electronics contract manufacturers in Taiwan and Malaysia are unbundling after-sales service from equipment purchase, demanding availability-guarantee contracts.
- Automated Tapping:Robotic cells with force-controlled tapping cycles open unmanned job-shop applications previously reserved for dedicated CNC cells.
- Conventional Tapping:Mechanical feed systems with fixed gear ratios serve low-volume applications with minimal programming requirements.
CNC Tapping holds technology leadership. Multi-Spindle Tapping is gaining share fastest as consumer electronics production scales in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering heritage established tapping machine standards that still govern global thread-machining specifications. Japanese builders scaled CNC tapping centers through METI-backed automation programs. Chinese domestic manufacturers now challenge incumbent positions as EV production localizes.
United States
Automotive electrification in Michigan and Ohio drives capital expenditure on precision threading equipment for battery tray assembly. OSHA machine guarding standards mandate interlocked enclosures for metalworking floors, filtering uncertified suppliers from federal defense contracts. Detroit-area tier-one suppliers deploy electric tapping arms at weld stations to eliminate work-in-process transport.
Germany
The EU Machinery Directive compels replacement of unguarded legacy equipment across Baden-Württemberg and Bavaria manufacturing clusters. DMG MORI anchors aerospace thread-machining contracts through integrated spindle technology. Stuttgart's automotive supply chain demands CE-certified automated systems with documented safety protocols.
China
Domestic machine tool builders scale CNC tapping centers for local EV battery tray and motor housing production lines. GB standards evolution and dual carbon goals reshape import requirements for foreign-built precision equipment. Shanghai and Shenzhen electronics manufacturers drive multi-spindle adoption for smartphone chassis contracts.
Japan
METI smart factory subsidies require JIS-compliant connected machine tools with predictive maintenance interfaces. Yamazaki Mazak Corporation serves automotive powertrain production through dedicated tapping centers. Nagoya's industrial corridor concentrates spindle bearing supply chains that create geographic vulnerability for foreign builders.
India
The PLI scheme for machine tools attracts joint-venture assembly operations to serve domestic automotive and defense threading demand. BIS certification requirements elevate equipment costs but filter substandard imports. Maharashtra and Gujarat automotive clusters expand precision equipment procurement as OEM localization accelerates.
Tapping Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and certification breadth. The vendor base organizes into three tiers: integrated machine tool conglomerates with spindle technology, specialized tapping equipment builders with regional service networks, and contract manufacturers assembling standardized electric units. Consolidation pressure concentrates among mid-tier pneumatic and manual equipment suppliers lacking connected machine interfaces. Dominant competitive moves include backward integration into spindle bearing supply and geographic expansion through joint-venture assembly in tariff-protected markets.
Within the integrated machine tool tier, DMG MORI and Yamazaki Mazak Corporation exemplify premium positioning through multi-axis synchronization capabilities. FANUC Corporation occupies a distinct position embedding force-controlled cycles into broader robotic machining portfolios. Among specialized equipment builders, Roscamat represents the dedicated tapping center archetype focused on portable electric and pneumatic configurations.
| Leading Market Players |
|---|
| DMG MORI |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| HAAS Automation |
| Brother Industries |
| Baileigh Industrial |
| FANUC Corporation |
| Hardinge Inc. |
| Roscamat |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany and Japan anchor precision spindle production, translating concentrated supply control into pricing discipline that resists commodity erosion despite input cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. Premium CNC systems with CE-MDR dual certification command substantial markups over entry-level pneumatic units lacking connected interfaces. Cost compression in the economy tier is intensifying because Chinese domestic builders are scaling production for local EV supply chains. SME machine shops exhibit the highest price sensitivity, while automotive OEMs prioritize uptime guarantees over unit acquisition cost.
Supply Chain Analysis
Freight cost differentials between Asian component sources and European assembly locations are widening margin gaps for builders lacking regional manufacturing footprints. Precision angular-contact bearing supply clusters in southern Germany and western Japan feed spindle production for DMG MORI and Yamazaki Mazak. Raw material dependency on high-alloy tool steel with nickel and cobalt exposure creates margin unpredictability. Single-source vulnerability in Japanese bearing supply chains threatens builders outside East Asia. Distribution runs through authorized dealer networks with regional service depots for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive operates as a regulatory compounder, forcing replacement cycles that sustain demand regardless of industrial production cyclicality.
For Market Incumbents: Anticipate cold-forming substitution in high-volume automotive fastener applications by embedding force-feedback capabilities that thread-forming cannot replicate. Backward integration into spindle bearing supply insulates margin stability against Japanese supply concentration. Prioritize JIS-compliant connected interfaces to capture METI smart factory subsidy flows. For New Entrants and Emerging Players: Direct-to-end-user digital channels bypass entrenched dealer networks that DMG MORI and Yamazaki Mazak dominate. India's PLI scheme for machine tools offers the most penetrable entry point through joint-venture assembly partnerships with local automotive suppliers. Target aftermarket service unbundling in Taiwan and Malaysia electronics supply chains with availability-guarantee contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier pneumatic equipment builders lacking connected machine interfaces and certification breadth. Long-term viability favors specialists with captive spindle technology and multi-axis programming competency. Watch for force-controlled robotic tapping adoption rates in unmanned job-shop environments as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Bearings | Captive supply from German and Japanese bearing clusters reduces single-source vulnerability for premium builders. |
| Joint Venture Assembly in India | PLI scheme incentives attract foreign precision equipment partners to serve domestic automotive and defense demand. |
| JIS-Compliant Connected Interface Development | METI smart factory certification qualifies equipment for public procurement and tier-one automotive contracts. |
| Force-Controlled Robotic Tapping Launch | Torque-feedback spindles on collaborative arms open unmanned job-shop applications beyond dedicated CNC cells. |
| Regional Spare-Part Depot Expansion | Electronics manufacturers in Taiwan and Malaysia demand uptime guarantees that require localized inventory positioning. |
Research Methodology
Coverage spans Germany, Japan, China, the United States, and India, with primary inputs from each market's metalworking clusters. The research combines interviews with maintenance directors at automotive tier-one suppliers, plant engineers in electronics contract manufacturing, OEM procurement teams specifying connected machine tools, and aftermarket service heads at regional distributors. Secondary validation draws from EU Machinery Directive compliance filings, METI smart factory certification registries, SEC 10-K disclosures from listed machine tool builders, and customs data on spindle bearing trade flows. Bottom-up equipment shipment estimates triangulate against top-down metalworking capital expenditure surveys.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, application end-use, technology tier, and regional production cluster. The analytical framework derives CAGRs from historical replacement cycles, regulatory compliance deadlines, and localized automotive build-out trajectories. Industry-specific forecast inputs include EV battery tray threading intensity per vehicle and multi-spindle adoption rates in consumer electronics chassis production.
The model assumes a particular technology adoption path; alternative pathways for cold-forming thread rolling would alter the outlook for cutting-tap equipment demand. Forecasts reflect assumptions about regulatory enforcement consistency, raw material price stability, and vocational training pipeline recovery. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Hand Tools Market
Tools
Ratchet Wringer Market
Tools
MIG Guns Market
Tools
Fatigue Testing Machine Market
Tools
Portable Grinders Market
Tools
Fastening Power Tools Market
Tools
Gear Hobbing Cutter Market
Tools
Horizontal Milling Machine Market
Tools
Coil Thread Insert Market
Tools
Tool Setting Gauges Market
Tools
Flooring Tools Market
Tools
Power Drill Market
Tools
Automatic Heat Press Machines Market
Tools
Diamond Hole Saw Market
Tools
Water Pump Pliers Market
Tools
Gas Cutting Machine Market