
 Electrical Substation Management Market | 2026-2036
Electrical Substation Management Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Substation Management Market Foresight
The capability gap between full-stack platform providers and component specialists is reorganizing competitive dynamics across electrical substation management. Siemens Energy leverages its digital twin portfolio to anchor large-scale transmission utility contracts across Europe and North America. Hitachi Energy differentiates through its Lumada platform integration, sustaining premium positioning in renewable interconnection projects. GE Vernova competes aggressively on grid edge software, extending its reach into utility asset performance management.
Electrical substation management encompasses the integrated hardware, software, and communication systems that monitor, control, and protect high-voltage power transformation and distribution facilities, typically operating at voltage levels from 69 kV to 765 kV. These systems perform real-time fault detection, load balancing, and predictive maintenance to ensure grid stability and minimize unplanned outages across transmission and distribution networks. Automation systems currently lead technology adoption as utilities pursue remote operation and reduced on-site staffing, while monitoring solutions represent the fastest-expanding segment driven by sensor proliferation and edge analytics deployment. Among components, switchgear commands the largest installed base though transformers capture disproportionate margin pools due to extended replacement cycles and bespoke engineering requirements.
The US Federal Energy Regulatory Commission enforces mandatory reliability standards through NERC CIP that dictate cybersecurity architecture for critical substation assets, directly shaping vendor product roadmaps and procurement specifications. Europe's CE marking and EU Green Deal requirements are forcing accelerated phase-out of SF6-insulated equipment, redirecting R&D investment toward vacuum interrupter and dry air insulation alternatives. India's Central Electricity Authority mandates smart grid compatibility standards that condition market access on communication protocol interoperability. Stakeholders must monitor how divergent regional decarbonization timelines reshape equipment replacement schedules and supplier qualification criteria.
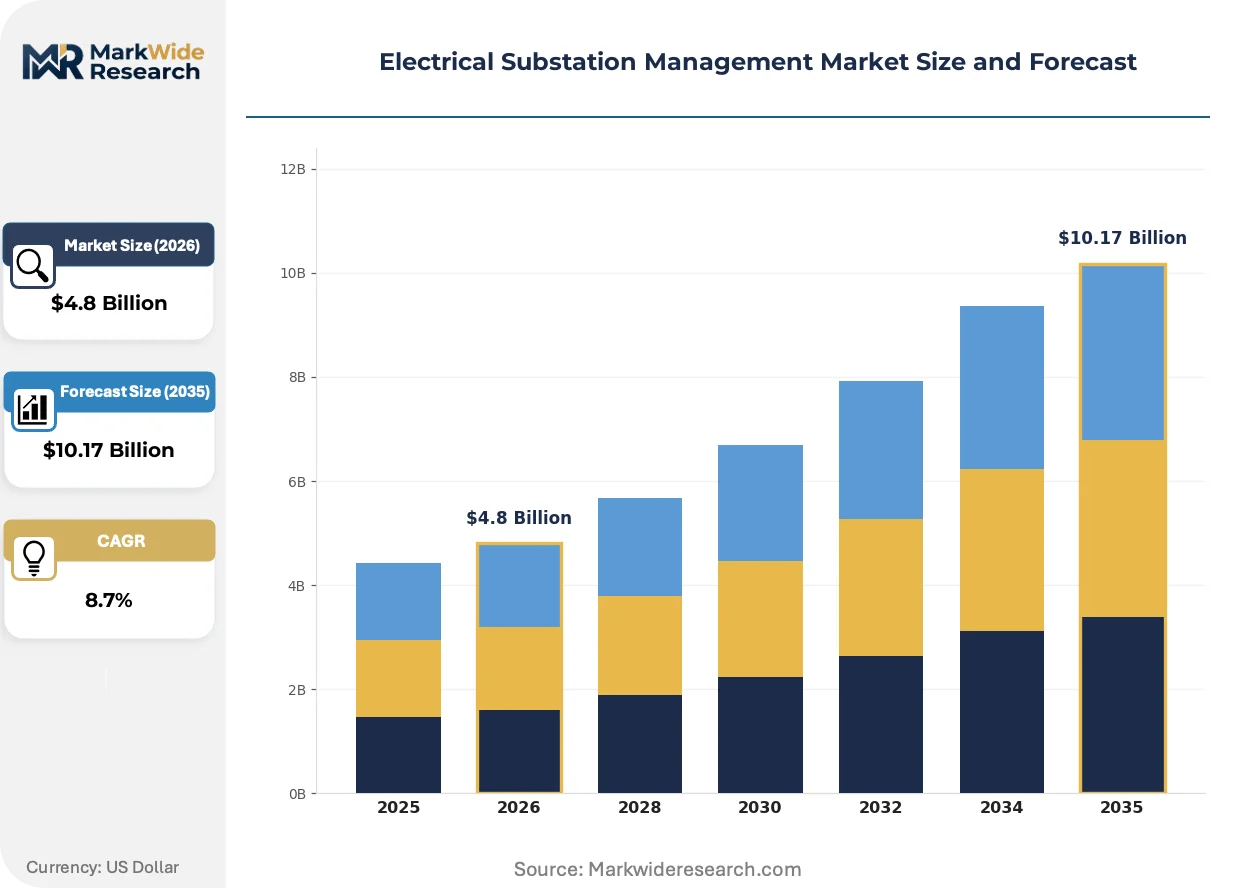
Market Dynamics
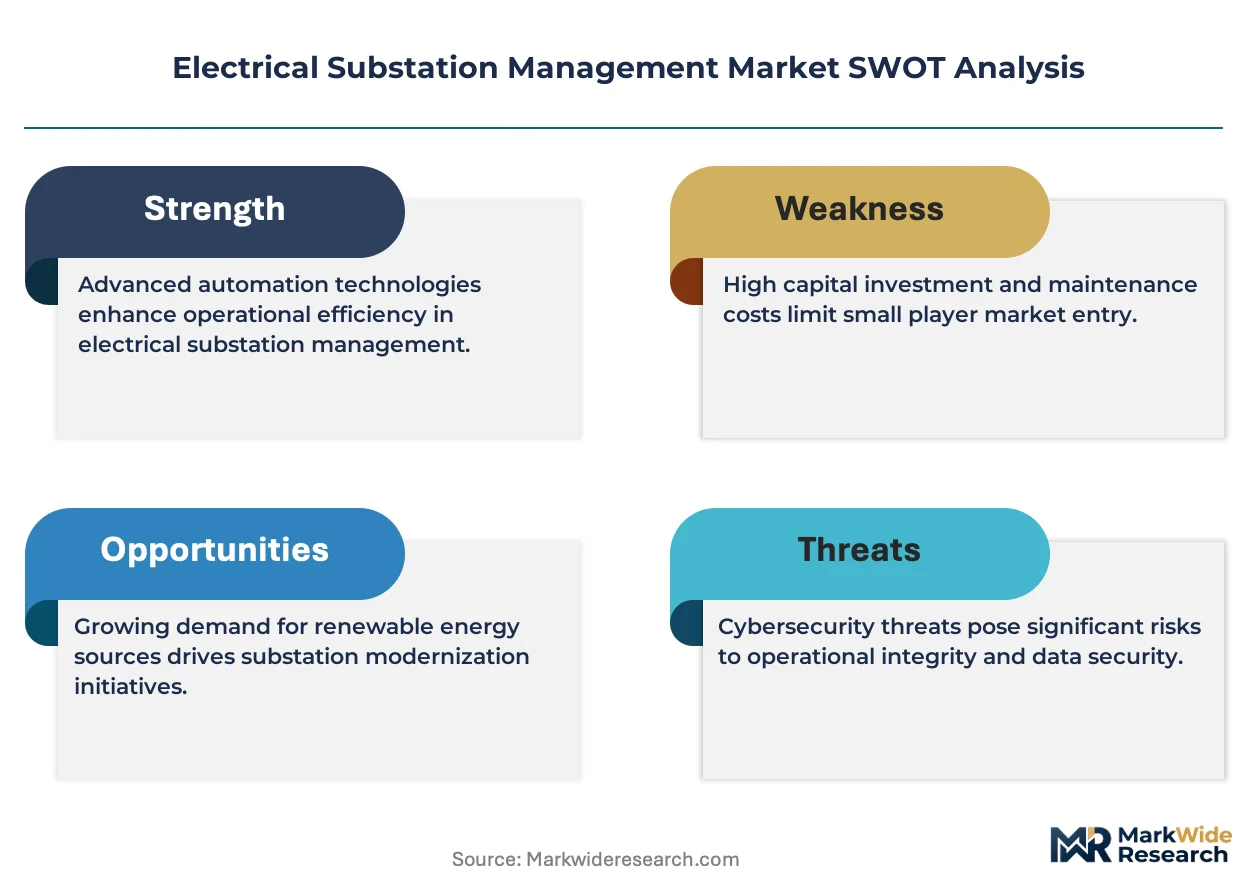
The transition from sulfur hexafluoride-dependent switchgear to vacuum and dry air insulation technologies is compressing equipment replacement cycles and forcing simultaneous upgrades to digital monitoring architectures across transmission utilities.
Growth Catalysts
- US Inflation Reduction Act grid modernization funding:Direct federal investment accelerates digital substation deployments, mandating cybersecurity-hardened control systems for critical infrastructure.
- Renewable interconnection queues:Wind and solar project backlogs in Germany, Texas, and Gujarat require automated fault isolation and dynamic load balancing capabilities.
- Edge analytics sensor proliferation:Transformer health monitoring through dissolved gas analysis and thermal imaging reduces unplanned outage duration for transmission operators.
Market Restraints
- Copper and grain-oriented electrical steel price volatility:Transformer core material costs fluctuate with mining output and trade policy, compressing OEM margins on fixed-price utility contracts.
- Specialized relay protection engineering scarcity:Fewer than twelve universities globally maintain accredited power systems programs, constraining talent pipelines for commissioning teams.
- EU F-Gas Regulation phase-out timelines:Accelerated SF6 equipment retirement forces premature capital expenditure before full lifecycle depreciation.
Strategic Opportunities
- India rural electrification expansion:Central Electricity Authority smart grid mandates create first-mover advantage for communication-protocol-agnostic platform providers.
- Predictive maintenance-as-a-service:Subscription-based thermal monitoring and partial discharge analytics unbundle traditional equipment sales into recurring revenue streams.
- Vacuum interrupter dry air convergence:Combined medium-voltage switchgear designs eliminate gas handling infrastructure, reducing site preparation costs for utilities.
Industry Challenges
- IEC 61850 multi-vendor interoperability:Protocol implementation inconsistencies between protection relay manufacturers delay commissioning schedules and require custom gateway development.
- NERC CIP-014 physical security compliance:Transmission substation operators must harden perimeter detection and access control systems against evolving threat assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Substation Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automation Systems, Monitoring Solutions, Control Systems, Communication Infrastructure Component: Transformers, Circuit Breakers, Switchgear, Relays End User: Utility Companies, Industrial, Government, Commercial Application: Grid Optimization, Asset Management, Emergency Services, Safety Management |
| Companies Covered | Siemens Energy, Hitachi Energy, GE Vernova, ABB, Schneider Electric, Eaton, Mitsubishi Electric Corporation, Toshiba Energy Systems & Solutions Corporation, Larsen & Toubro Electrical & Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Substation Management Market Shifts & Advancements
Digital twin architecture and sulfur hexafluoride-free insulation are converging to redefine equipment procurement specifications and vendor qualification criteria across high-voltage infrastructure planning.
Intelligent electronic devices with embedded edge computing capabilities are miniaturizing protection and control functions previously housed in standalone rack-mounted systems. Transmission utilities in Germany and Texas are deploying these compact units for distributed automation, reducing substation footprint requirements by consolidating multiple relay functions into single hardware platforms. This consolidation is miniaturizing conventional control house construction, shifting capital allocation toward software-defined functionality and away from civil infrastructure.
Europe's F-Gas Regulation mandates complete phase-out of SF6-insulated equipment in new installations by 2032, with stringent reporting requirements accelerating R&D investment in alternative insulation media. Vacuum interrupter manufacturers and dry air insulation specialists are capturing disproportionate tender volumes as utilities front-load procurement to avoid supply bottlenecks. The regulation most heavily affects 145 kV and 245 kV switchgear categories, where SF6 historically dominated interrupting performance benchmarks.
Asset performance management software unbundling is separating predictive analytics from hardware procurement, enabling third-party algorithm providers to compete for utility O&M budgets independent of original equipment manufacturers. European transmission system operators are piloting multi-asset fleet optimization platforms that aggregate transformer, switchgear, and protection relay data into unified risk scoring. This unbundling is most advanced in Germany, where unbundling regulations already separate network operation from generation ownership, creating organizational readiness for outsourced digital services.
Electrical Substation Management Market Segmentation
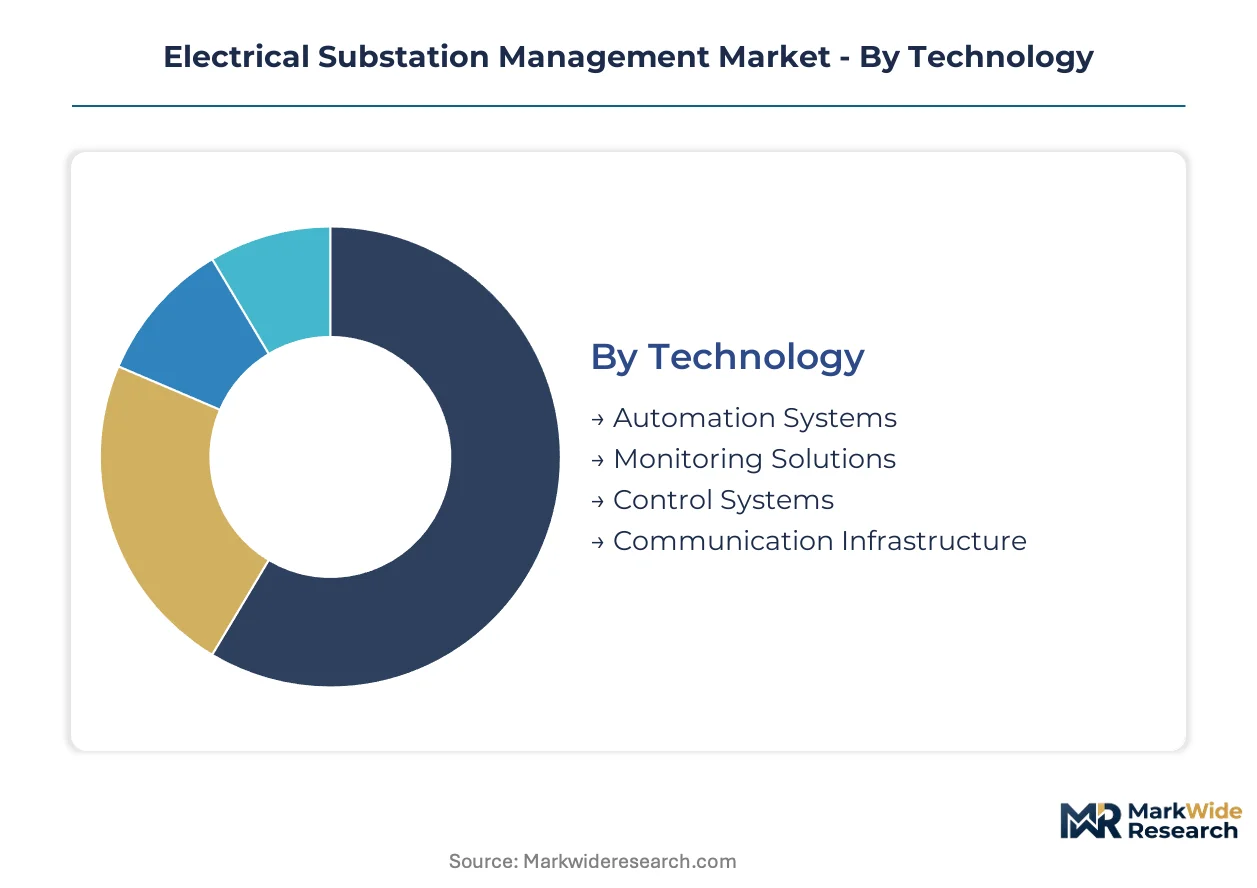
Segmentation in electrical substation management reveals how capital allocation splits between hardware replacement cycles and software unbundling. Procurement patterns diverge sharply between transmission utilities prioritizing reliability and industrial operators optimizing for energy arbitrage.
Technology:
Margin pools concentrate in software layers that decouple from hardware refresh timelines, with automation systems commanding premium pricing through reduced staffing dependencies.
- Automation Systems:These platforms execute remote switching, load shedding, and fault isolation without on-site personnel. Demand clusters in Germany and Texas where renewable intermittency forces sub-second response protocols.
- Monitoring Solutions:Sensor networks for dissolved gas analysis, thermal imaging, and partial discharge detection feed predictive algorithms. European transmission operators are front-loading procurement to meet EU Green Deal reporting mandates.
- Control Systems:SCADA and energy management platforms with IEC 61850 protocol compliance.
- Communication Infrastructure:Fiber and wireless networks enabling substation-to-control-center data transmission.
Automation Systems holds installed capacity. Monitoring Solutions is rotating up the share rankings.
Component:
Transformer replacement cycles stretch across decades, locking margin into aftermarket services and spare parts rather than original equipment sales.
- Transformers:Core and shell designs using grain-oriented electrical steel dominate high-voltage installations. India's Central Electricity Authority mandates smart grid compatibility for new 765 kV units.
- Switchgear:Vacuum interrupters and dry air insulation variants are displacing SF6-dependent designs. Germany's transmission utilities are accelerating procurement ahead of EU F-Gas Regulation deadlines.
- Circuit Breakers:Spring-operated and magnetic actuation mechanisms for fault current interruption.
- Relays:Microprocessor-based protection devices with embedded cybersecurity per NERC CIP standards.
Switchgear dominates tender volumes. Transformers is climbing the fastest on replacement backlog.
End User:
Utility procurement concentrates investment in grid-scale reliability, while industrial users prioritize power quality for sensitive manufacturing loads.
- Utility Companies:Transmission and distribution operators with rate-base recovery mechanisms fund multi-year digital substation programs. US Inflation Reduction Act allocations are accelerating deployments.
- Industrial:Heavy manufacturing and data center operators managing captive substations for voltage sag mitigation.
- Government:Federal and state entities owning strategic infrastructure.
- Commercial:Campus and district energy systems with behind-the-meter automation.
Utility Companies anchor contract values. Industrial is gaining share fastest on captive generation expansion.
Application:
Asset Management software unbundling is redirecting O&M budgets from equipment vendors to third-party analytics providers.
- Grid Optimization:Real-time power flow balancing and renewable integration algorithms. Texas ERCOT operators deploy these tools to manage wind and solar variability.
- Asset Management:Fleet-wide risk scoring and predictive maintenance scheduling. German transmission system operators pilot multi-asset platforms aggregating transformer and switchgear data.
- Emergency Services:Black start capability and restoration sequencing protocols.
- Safety Management:Arc flash detection and personnel protection systems.
Grid Optimization commands deployment priority. Asset Management represents the fastest-growing trajectory on subscription revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Industrial operators in Germany absorb premium pricing for SF6-free switchgear, while Indian utilities prioritize lowest first-cost procurement despite higher lifecycle expenses. This elasticity gap is widening as regulatory timelines diverge.
United States
Texas ERCOT operators deploy automated fault isolation to manage wind and solar intermittency. The Inflation Reduction Act channels federal investment toward cybersecurity-hardened control systems. Houston and Dallas-Fort Worth clusters concentrate transmission utility procurement teams front-loading digital substation investments.
Germany
Transmission system operators accelerate vacuum interrupter procurement ahead of EU F-Gas Regulation deadlines. The EU Green Deal mandates complete SF6 phase-out in new installations by 2032. Berlin and Munich engineering centers pilot multi-asset fleet optimization platforms aggregating transformer and switchgear data.
India
Gujarat and Rajasthan renewable interconnection queues drive demand for dynamic load balancing capabilities. The Central Electricity Authority mandates smart grid compatibility standards conditioning market access on protocol interoperability. Ahmedabad and Surat industrial corridors attract first-mover platform providers seeking communication-protocol-agnostic positioning.
Japan
Tokyo Electric Power and regional utilities invest in compact intelligent electronic devices for distributed automation. METI efficiency standards push miniaturization of protection functions previously housed in standalone rack-mounted systems. Osaka and Nagoya manufacturing belts concentrate relay protection engineering talent for commissioning teams.
South Korea
KEPCO and independent power producers expand edge analytics deployment for transformer health monitoring. The country's national grid regulator enforces cybersecurity architecture standards for critical substation assets. Seoul Capital Area and Busan-Ulsan industrial zones drive premium pricing for predictive maintenance-as-a-service subscriptions.
Electrical Substation Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Full-stack platform providers anchor large-scale transmission contracts through integrated digital twin portfolios. Component specialists capture margin in bespoke engineering segments with extended replacement cycles. The market structure consolidates around three strategic archetypes: integrated energy technology conglomerates, industrial automation multinationals, and regional electrical infrastructure specialists. Dominant competitive moves include portfolio diversification into predictive analytics software and strategic partnerships for IEC 61850 interoperability certification.
Among Germany-based energy technology providers, Siemens Energy and ABB exemplify the full-stack platform archetype, anchoring European and North American transmission utility relationships. Hitachi Energy, with Japanese corporate origins, occupies a position representing the integrated industrial conglomerate model. These three companies illustrate how geographic engineering heritage and captive R&D infrastructure create defensive positioning against pure-play software entrants.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy |
| GE Vernova |
| ABB |
| Schneider Electric |
| Eaton |
| Mitsubishi Electric Corporation |
| Toshiba Energy Systems & Solutions Corporation |
| Larsen & Toubro Electrical & Automation |
| Others |
Supply & Pricing Matrix
NERC CIP cybersecurity certification gates vendor qualification and price differentiation simultaneously, forcing OEMs to absorb compliance costs upfront while utilities pay premiums for hardened architectures. Copper and grain-oriented electrical steel volatility feeds directly into transformer pricing, compressing margins on fixed-rate transmission contracts.
Pricing Analysis
Aftermarket service contracts and spare parts revenue anchor lifetime value for transformer OEMs, stretching across decades-long replacement cycles. Three-tier pricing structure across premium, standard, and economy levels segments procurement by voltage class and smart grid compatibility. Cost compression in switchgear is intensifying because vacuum interrupter manufacturers compete aggressively for EU F-Gas Regulation-driven replacement demand. Industrial captive substation operators in Texas and Gujarat exhibit highest price sensitivity, while German transmission utilities absorb premiums for SF6-free certification.
Supply Chain Analysis
Grain-oriented electrical steel production concentrates in Japan, South Korea, and Germany, creating chokepoint vulnerability for transformer core manufacturing. Vacuum interrupter ceramics draw from specialized Japanese and German suppliers, while copper winding conductors rest on Chilean and Peruvian mining output. Single-source vulnerability runs through SF6 gas handling equipment as EU phase-out timelines strain alternative insulation component capacity. Distribution runs through EPC contractors and direct utility procurement teams, with regional specialists capturing commissioning and aftermarket service tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical substation management market tracks a cyclical recovery anchored to grid modernization capital deployment waves under US Inflation Reduction Act allocations and EU Green Deal implementation timelines.
For Market Incumbents: Shield installed base relationships through predictive maintenance-as-a-service unbundling, converting equipment sales into recurring revenue streams. Deepen backward integration into transformer core steel and vacuum interrupter ceramics to offset commodity volatility. Counter pure-play software entrants by embedding edge analytics directly into intelligent electronic device firmware, preserving hardware-software bundling power.
For New Entrants and Emerging Players: Third-party IEC 61850 protocol gateway development presents immediate white-space opportunity, as multi-vendor interoperability failures delay commissioning schedules across protection relay deployments. Target India's rural electrification corridors where CEA smart grid mandates create first-mover advantage for communication-protocol-agnostic platforms. Pursue asset performance management software licensing to European transmission system operators already unbundled from generation ownership.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation specialists holding captive relay protection engineering talent pools. Five-to-ten year viability hinges on SF6-free technology transition completion and digital twin platform consolidation. Monitor EU F-Gas Regulation enforcement acceleration as inflection signal for vacuum interrupter demand spikes and stranded SF6 equipment write-downs.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance-as-a-Service Launch | Converts transformer and switchgear sales into recurring O&M revenue streams for transmission utilities. |
| SF6-Free Switchgear Certification | Secures EU tender eligibility ahead of F-Gas Regulation 2032 phase-out deadlines. |
| IEC 61850 Interoperability Partnership | Reduces commissioning delays from multi-vendor protection relay protocol inconsistencies. |
| Edge Analytics Sensor Integration | Embeds dissolved gas analysis and thermal monitoring into intelligent electronic devices. |
| India Smart Grid Platform Expansion | Captures CEA-mandated protocol-agnostic positioning in Gujarat and Rajasthan renewable corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC filings, EIA grid infrastructure databases, EU Green Deal implementation trackers, and IEC standardization committee records. Utility planning officers, EPC contractor project managers, relay protection engineering leads, and aftermarket service directors provided structured input across Germany, the United States, and India. Bottom-up equipment procurement tracking triangulates against top-down grid investment flow analysis.
Segmentation dimensions modeled span technology layer, voltage class tier, component category, end-user archetype, and regional regulatory framework across the projection horizon. CAGRs derive from equipment replacement cycle analysis, renewable interconnection queue processing rates, and digital substation deployment velocity. Forecast inputs incorporate copper and electrical steel price trajectory assumptions alongside SF6 phase-out timeline enforcement probability.
Forecasts assume regulatory continuity in US Inflation Reduction Act grid modernization funding and EU F-Gas Regulation phase-out schedules; material policy shifts would require re-modeling capital allocation timelines and equipment retirement schedules. Practitioners should keep alternative scenarios live as NERC CIP cybersecurity standard evolution and India CEA smart grid mandate enforcement intensity develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market