
 Global Anti-Vibration Polymer Market | 2026-2036
Global Anti-Vibration Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Vibration Polymer Market Foresight
Modularization of anti-vibration component kits is shifting how Tier-1 suppliers specify polymer isolators for platform-sharing vehicle programs. Vibracoustic leverages captive rubber compounding capacity to control formulation consistency across axle and powertrain mounts. ContiTech anchors European aftermarket distribution through direct OEM service contracts. Sumitomo Riko specializes in multi-layer laminates for hybrid vehicle battery trays, a segment where thermal and vibration isolation requirements overlap.
Anti-vibration polymers are elastomeric compounds engineered with damping coefficients between 0.1 and 0.8 and loss factors optimized for targeted frequency attenuation, typically manufactured through injection molding or compression molding of sulfur-cured rubber blends with mineral fillers. These materials absorb mechanical oscillation energy in rotating machinery, vehicle suspensions, and precision equipment to prevent fatigue failure and noise transmission. Polyurethane formulations command premium positioning in machine mounts due to tunable hardness grades and oil resistance, while silicone dominates aerospace and defense applications where extreme temperature cycling from minus 55 to 200 degrees Celsius demands stable viscoelastic performance. EPDM occupies mature volume pools in HVAC and building foundation pads where cost efficiency outweighs performance specialization.
The US EPA and NHTSA regulate automotive polymer content through volatile organic compound limits and crashworthiness material standards, while the EU REACH framework restricts phthalate plasticizers and heavy metal catalyst residues in rubber compounds sold across member states. Japan's METI enforces JIS K 6250 series testing protocols that govern compression set and tensile strength certification for industrial vibration isolators. Stakeholders must monitor evolving material passport requirements under the EU CSRD and assess backward integration into custom compounding operations to secure formulation flexibility against tightening chemical disclosure mandates.
Market Dynamics
Platform-sharing architectures across automotive OEMs are compressing specification diversity for anti-vibration mounts, forcing polymer compounders to develop tunable formulations that serve multiple vehicle segments from a single material grade. This standardization pressure is reshaping how suppliers structure compounding operations and certification portfolios.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon blowing agents in polyurethane foams is accelerating adoption of water-blown and pentane-based alternatives for HVAC and appliance mounts.
- Electric powertrain assemblies:Battery pack and motor mounting systems require vibration isolation across broader temperature ranges than internal combustion counterparts, expanding specification opportunities for silicone and fluorocarbon elastomers.
- German precision manufacturing clusters:Machine tool and semiconductor equipment producers in Baden-Württemberg and Bavaria sustain premium consumption of tuned-mass damper polymers with sub-micron positional stability requirements.
Market Restraints
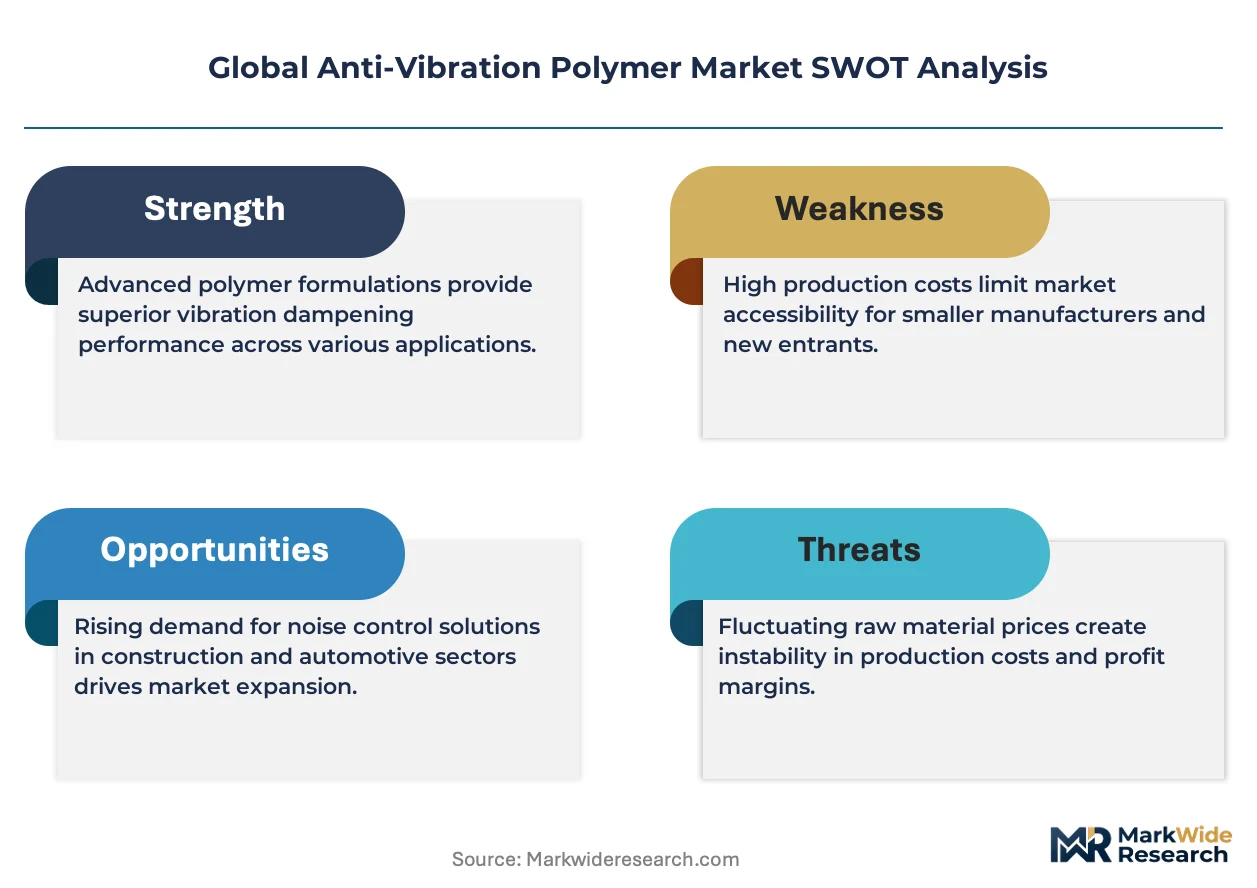
- Petrochemical feedstock volatility:Polyether polyol and isocyanate prices track crude oil and natural gas benchmarks, compressing margin predictability for polyurethane compounders without long-term offtake agreements.
- Carbon black supply concentration:Reinforcing filler production clusters in China and India create geographic single-point-of-failure exposure for EPDM and natural rubber formulations.
- REACH SVHC disclosure thresholds:Substances of very high concern candidate list expansion forces reformulation cycles that extend qualification timelines by 18-24 months for European-bound products.
Strategic Opportunities
- India automotive component exports:PLI scheme incentives for advanced chemistry cell manufacturing are creating localized demand for battery tray isolation systems with thermal-runaway containment properties.
- Convergence of additive manufacturing and topology optimization:Lattice-structured TPU mounts with variable density zones enable part-count reduction and frequency-tuning without mold retooling.
- EU CSRD material passport mandates:Early compliance with digital product traceability requirements positions compounders for preferred supplier status in European defense and medical equipment procurement.
Industry Challenges
- Compounding chemist scarcity:Formulation expertise in sulfur-cure kinetics and filler-silane coupling chemistry is retiring faster than university polymer programs replenish qualified talent.
- Multi-standard certification burden:Simultaneous pursuit of NHTSA FMVSS, JIS K 6250, and OEM-specific test protocols extends product launch timelines and strains testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Vibration Polymer Market |
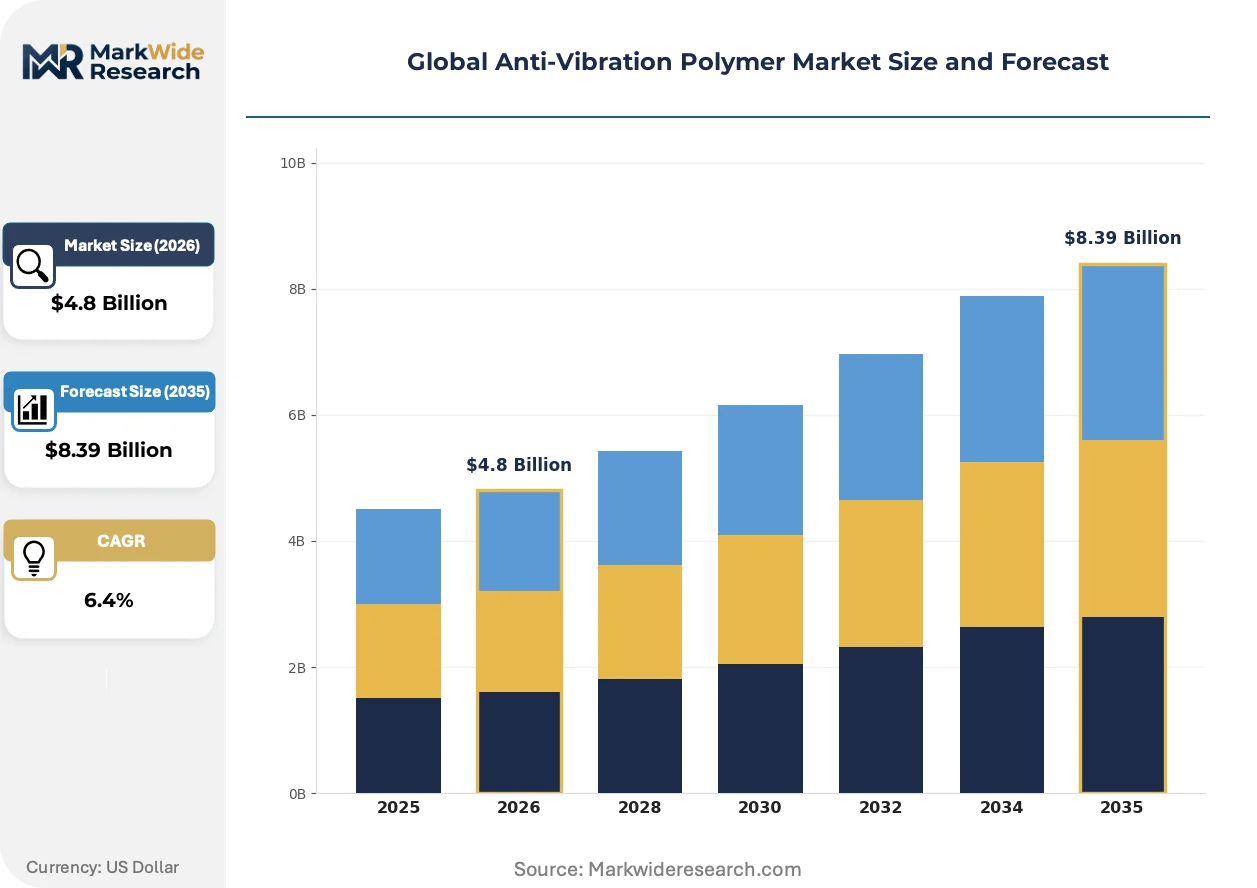
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
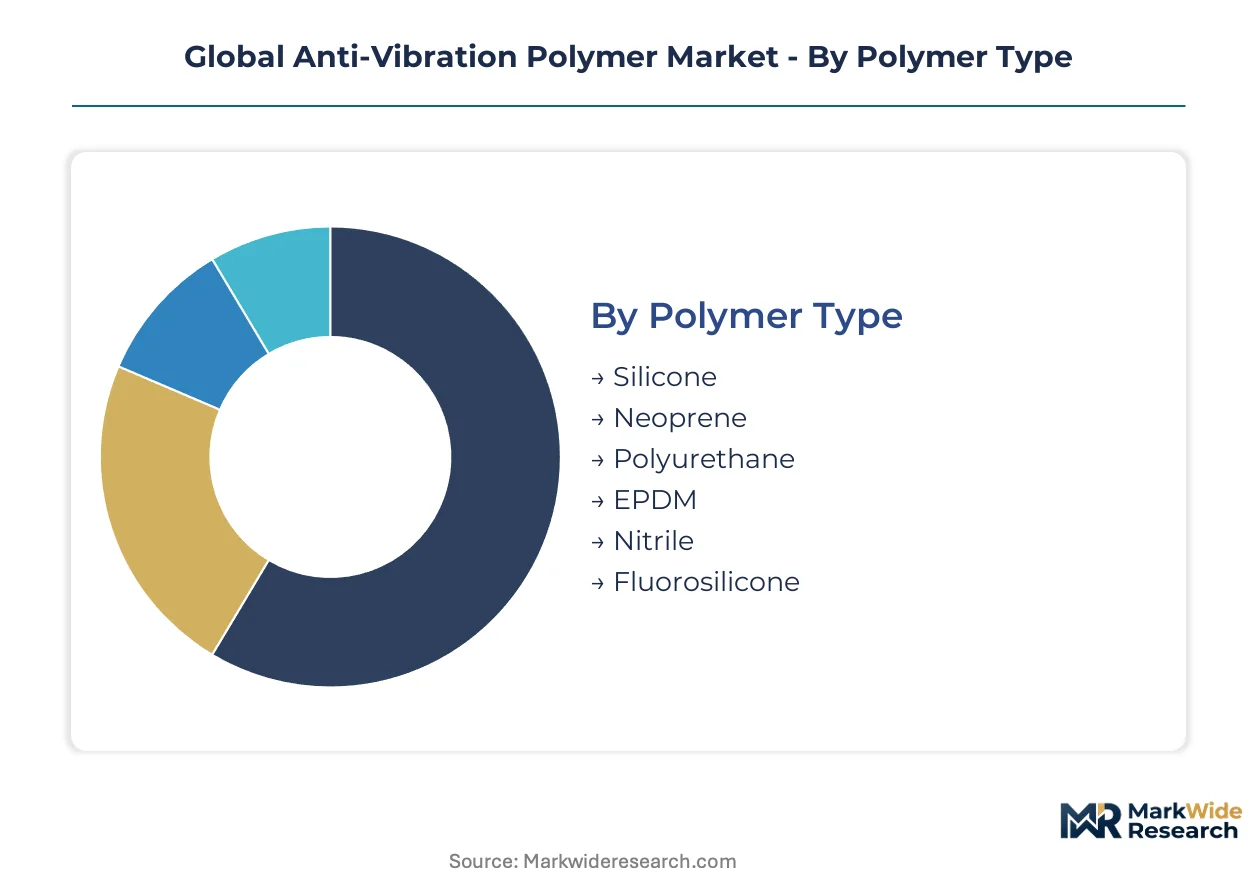
| Segmentation | Polymer Type: Silicone, Neoprene, Polyurethane, EPDM, Nitrile, Fluorosilicone End Use Industry: Aerospace, Power Generation, Maritime, Consumer Electronics, Defense, Telecommunications Application: Machine Mounts, Automotive Parts, Building Foundations, HVAC Systems, Electronic Device Isolation Form: Sheets, Molded Components, Rods, Extruded Profiles, Films |
| Companies Covered | Vibracoustic, ContiTech, Trelleborg AB, Hutchinson, Sumitomo Riko, Bridgestone Corporation, Sorbothane, Inc., Polymer Technologies, Inc., LORD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Vibration Polymer Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are converging to redefine how anti-vibration polymers are specified, tested, and supplied across industrial value chains. Three developments are restructuring competitive positioning.
Magnetorheological elastomer composites are modularizing adaptive damping systems for semi-active suspension architectures. Automotive Tier-1 suppliers in Japan and Germany are qualifying these field-responsive materials for premium electric vehicle platforms. The technology is modularizing what were previously discrete hydraulic valve and rubber spring subsystems into unified smart-mount assemblies with real-time stiffness tuning.
REACH Annex XVII restrictions on microplastic release from abrasion are compelling reformulation of tire and track pad compounds that historically relied on thermoset crumb rubber fillers. Industrial flooring and conveyor belt manufacturers serving European markets are accelerating substitution toward thermoplastic polyurethane and copolyester elastomers with controlled wear debris characteristics. Material certification laboratories in Germany report 40% capacity expansion to handle accelerated retesting schedules.
Defense procurement agencies in the United States and United Kingdom are unbundling vibration isolation from platform integration contracts, creating direct specification authority for polymer compounders. This channel disintermediation compresses margin capture for systems integrators while rewarding compounders with MIL-STD-810 test data packages and domestic production footprints. Maritime and aerospace applications in Norfolk and Glasgow clusters exhibit the most pronounced buying-pattern shift toward direct material qualification.
Global Anti-Vibration Polymer Market Segmentation
Anti-vibration polymer specifications diverge sharply across end-use certifications, with aerospace MIL-STD-810G requirements demanding fundamentally different formulation protocols than building foundation EPDM pads. Segmentation clarity enables compounders to align R&D spending with qualification timelines that stretch from 18 months for automotive platforms to 4 years for defense airframe mounts.
Polymer Type:
Silicone and fluorosilicone formulations require FAA flame-resistance certification for aircraft interiors, while polyurethane and EPDM grades face NHTSA FMVSS 302 automotive flammability standards. Neoprene and nitrile compounds must satisfy REACH SVHC disclosure thresholds for European industrial machinery exports.
- Silicone:Cross-linked polydimethylsiloxane networks with stable viscoelastic performance across minus 55 to 200 degrees Celsius temperature cycling. Aerospace OEMs in Toulouse and Seattle specify these grades for engine pylon isolators where FAA Part 25 airworthiness directives govern material selection. Defense procurement in the United Kingdom is accelerating direct qualification of silicone mounts for maritime propulsion systems.
- Polyurethane:Tunable polyether or polyester backbone structures with hardness grades spanning 40A to 90A Shore scale. German machine tool manufacturers in Baden-Württemberg specify castable polyurethane mounts for sub-micron positional stability in semiconductor lithography equipment. Water-blown formulations are displacing HFC-blown alternatives under EU F-Gas Regulation phasedown schedules.
- EPDM:Sulfur-cured ethylene-propylene-diene monomer compounds with saturated backbone architecture for ozone resistance.
- Neoprene:Chloroprene-based general-purpose elastomers balancing oil resistance against cost efficiency in industrial conveyor applications.
- Nitrile:Acrylonitrile-butadiene copolymers with elevated acrylonitrile content for petroleum fluid compatibility in power generation equipment.
- Fluorosilicone:Fluorinated backbone variants combining fuel resistance with extreme temperature performance for aerospace fuel system isolators.
Leading the category by volume: EPDM in building and HVAC applications. Growing fastest: Polyurethane expanding most quickly on electric vehicle platform demand and machine tool precision requirements.
End Use Industry:
Customer procurement patterns separate into capital-equipment buyers with 10-year specification cycles versus aftermarket service contractors with 90-day replenishment horizons. Defense and aerospace segments concentrate specification authority with prime contractors, while power generation and telecommunications channels fragment across maintenance procurement networks.
- Aerospace:Primary and secondary structure isolation systems for commercial airframes and rotorcraft. Boeing and Airbus supply chains in Washington State and Haute-Garonne specify thermally stable silicone grades for engine and APU mounts. FAA certification timelines extend 3-4 years for new material qualifications.
- Defense:Platform-agnostic vibration isolation for ground vehicles, naval vessels, and unmanned aerial systems. UK Ministry of Defence and US Department of Defense procurement is disintermediating systems integrators to specify polymers directly from compounders with MIL-STD-810 test data packages. Maritime applications in Norfolk and Glasgow clusters exhibit pronounced buying-pattern shifts toward direct material qualification.
- Power Generation:Turbine and generator isolation for gas, steam, and renewable energy installations.
- Maritime:Propulsion system and auxiliary machinery mounts for commercial and naval vessels.
- Consumer Electronics:Micro-vibration isolation for hard disk drives, camera modules, and handheld device speakers.
- Telecommunications:Base station and data center equipment isolation for 5G infrastructure deployment.
Highest certification burden: Aerospace and defense with multi-agency approval requirements. Steepest expansion trajectory: Defense procurement channel restructuring toward direct polymer specification.
Application:
Functional performance requirements dictate formulation architecture, with dynamic stiffness targets varying by three orders of magnitude between heavy industrial machine mounts and consumer electronic micro-isolators. Building foundation applications prioritize static load-bearing capacity over frequency-tuned damping.
- Automotive Parts:Powertrain, suspension, and battery pack isolation systems for internal combustion and electric vehicle platforms. OEM platform-sharing architectures in Germany and Japan are compressing specification diversity, forcing compounders to develop tunable formulations serving multiple vehicle segments from single material grades. Silicone and fluorocarbon elastomers are gaining specification share for battery tray applications requiring thermal-runaway containment properties.
- Machine Mounts:Precision equipment isolation for semiconductor manufacturing, metrology, and machine tool applications. Japanese and German equipment producers sustain premium consumption of tuned-mass damper polymers with sub-micron positional stability requirements. METI JIS K 6250 series protocols govern compression set and tensile strength certification for industrial isolators exported to Japan.
- Building Foundations:Structural isolation pads for seismic protection and noise attenuation in commercial and residential construction.
- HVAC Systems:Compressor and fan isolation for heating, ventilation, and air conditioning equipment.
- Electronic Device Isolation:Micro-scale vibration management for sensitive electronic components.
Widest specification diversity: Automotive parts spanning 12+ OEM-specific test protocols. Tightest qualification timelines: Electronic device isolation with 6-9 month consumer product cycles.
Form:
Manufacturing process selection determines geometric complexity capability and economic order quantity thresholds, with molded components requiring steel tool investments that amortize across 50,000-plus unit volumes. Sheet and film forms enable prototype iteration without mold fabrication lead times.
- Molded Components:Injection-molded or compression-molded isolators with integrated attachment features and variable wall thickness. Tier-1 automotive suppliers specify molded polyurethane and silicone isolators for electric powertrain assemblies where geometric complexity integrates mounting brackets with elastomeric elements. Tooling investments concentrate specification authority with compounders possessing captive mold fabrication capability.
- Sheets:Calendered or cast flat-stock materials for fabrication into gaskets, pads, and custom-cut isolators. Building foundation and industrial machinery aftermarket channels specify sheet stock for field-fabricated installations where geometric customization exceeds standard molded component catalogs.
- Extruded Profiles:Continuous cross-section geometries for edge seals, channel fills, and linear isolation applications.
- Rods:Solid cylindrical stock for machining into custom bushings and spherical bearings.
- Films:Thin-gauge materials for constrained-layer damping treatments and electronic component isolation.
Highest value-add capture: Molded components with integrated metal bonding and complex geometry. Lowest entry barrier: Sheet stock distributed through industrial supply channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, Japan, and the United States while consumption spreads across precision manufacturing hubs and defense procurement centers in multiple geographies. This geographic split shapes trade flows and qualification requirements.
United States
Defense procurement agencies in Norfolk and Washington State sustain premium silicone consumption for maritime and aerospace applications. The US EPA and NHTSA regulate automotive polymer content through volatile organic compound limits and crashworthiness material standards. Boeing supply chains in Washington State specify thermally stable grades for engine pylon isolators with FAA Part 25 airworthiness directives.
Germany
Machine tool and semiconductor equipment producers in Baden-Württemberg and Bavaria drive demand for tuned-mass damper polymers with sub-micron positional stability. The EU F-Gas Regulation and REACH compliance requirements tighten material certification standards across European supply chains. ContiTech anchors European aftermarket distribution through direct OEM service contracts from its continental base.
Japan
Automotive Tier-1 suppliers and precision equipment producers concentrate specification authority for electric vehicle platform components. METI enforces JIS K 6250 series testing protocols governing compression set and tensile strength certification for industrial vibration isolators. Sumitomo Riko specializes in multi-layer laminates for hybrid vehicle battery trays where thermal and vibration isolation requirements overlap.
India
PLI scheme incentives for advanced chemistry cell manufacturing create localized demand for battery tray isolation systems with thermal-runaway containment properties. BIS standards govern industrial rubber product certification for domestic and export markets. Automotive component export clusters in Maharashtra and Tamil Nadu are qualifying water-blown polyurethane formulations to serve European OEM platform-sharing programs.
United Kingdom
Defense procurement is disintermediating systems integrators to specify polymers directly from compounders with MIL-STD-810 test data packages. The UK Ministry of Defence procurement frameworks prioritize domestic production footprints for maritime applications. Glasgow clusters exhibit pronounced buying-pattern shifts toward direct material qualification for naval vessel propulsion systems.
Global Anti-Vibration Polymer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation development and qualification timelines. Market structure tilts toward tiered supplier networks where captive compounding capacity determines margin capture. Three archetypes dominate: rubber specialists with captive mixing operations, diversified industrial conglomerates with polymer divisions, and regional compounders serving aftermarket channels. Competitive moves center on backward integration into custom compounding operations and geographic expansion into defense procurement clusters.
Among diversified industrial conglomerates, Vibracoustic and ContiTech exemplify scale-driven positions anchored in European automotive supply chains. Sumitomo Riko represents the specialist tier with focused expertise in multi-layer laminates for electrified vehicle platforms. These three companies illustrate how competitive positioning diverges between broad portfolio coverage and targeted application dominance.
| Leading Market Players |
|---|
| Vibracoustic |
| ContiTech |
| Trelleborg AB |
| Hutchinson |
| Sumitomo Riko |
| Bridgestone Corporation |
| Sorbothane, Inc. |
| Polymer Technologies, Inc. |
| LORD Corporation |
| Others |
Supply & Pricing Matrix
Compounding chemist concentrations in Baden-Württemberg and Bavaria widen pricing-tier spreads between formulation-intensive silicone grades and commodity EPDM pads, as labor-cost differentials compound raw material premiums for aerospace-qualified compounds.
Pricing Analysis
Margin tightening in standard-grade polyurethane reflects automotive OEM platform-sharing mandates that compress specification diversity. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810 certified silicone from JIS K 6250 industrial grades and uncertified building foundation EPDM. Cost-down pressure on economy-tier compounds accelerates because REACH SVHC disclosure cycles extend qualification timelines. Aftermarket service contractors exhibit highest price sensitivity; defense procurement agencies show lowest.
Supply Chain Analysis
Formulation expertise scarcity in German and Japanese manufacturing clusters concentrates premium compound production with established suppliers. Geographic supply concentration centers on Germany, Japan, and the United States for precision-grade materials; China and India for carbon black reinforcing fillers. Raw material dependencies draw from polyether polyol, isocyanate, and mineral filler streams. Single-source vulnerability in carbon black supply creates geographic concentration risk. Distribution runs through Tier-1 automotive supplier networks and direct OEM service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compounding chemist retirement rates exceed university pipeline replenishment, constraining formulation capacity and sustaining premium pricing for qualified suppliers.
For Market Incumbents: Lock in captive rubber compounding capacity to control formulation consistency against emerging pure-play specialists. Secure backward integration into custom mixing operations to defend margin position from petrochemical feedstock volatility. Accelerate MIL-STD-810 test data package accumulation before defense procurement channel restructuring completes.
For New Entrants and Emerging Players: Begin with water-blown polyurethane formulations for Indian automotive export clusters qualifying under PLI scheme incentives. Target battery tray isolation systems where thermal-runaway containment requirements overlap with vibration management. Pursue direct qualification relationships with UK Ministry of Defence procurement frameworks disintermediating systems integrators.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap compounders possessing captive mold fabrication capability given lattice-structured TPU topology optimization convergence. Long-term viability favors suppliers with demonstrated REACH Annex XVII compliance and EU CSRD material passport readiness. Monitor defense procurement unbundling velocity in Norfolk and Glasgow clusters as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Compounding | Captive mixing operations secure formulation flexibility against REACH disclosure mandates. |
| Defense Procurement Direct Qualification | MIL-STD-810 test data packages unlock channel disintermediation in maritime applications. |
| Water-Blown Polyurethane Transition | EU F-Gas Regulation compliance displaces HFC-blown alternatives in HVAC mounts. |
| Lattice-Structured TPU Manufacturing | Additive manufacturing convergence enables part-count reduction without mold retooling. |
| EU CSRD Material Passport Compliance | Digital traceability positioning secures preferred supplier status in medical equipment procurement. |
Research Methodology
Multi-period observation of formulation patent filings, qualification timeline durations, and defense procurement contract unbundling patterns anchored the trend analysis, supplemented by interviews with rubber compounding plant managers, automotive Tier-1 procurement leads, distribution channel partners, and technical R&D directors at silicone specialists. Secondary validation drew from customs and trade data, ECHA SVHC candidate list updates, SEC 10-K polymer segment disclosures, and JIS K 6250 certification registry records. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across polymer type, end-use industry, application form, and regional production hub drove the analytical framework. CAGRs were derived from trend extrapolation of platform-sharing adoption rates, electric vehicle powertrain penetration, and defense procurement channel restructuring velocity across the projection horizon. Industry-specific forecast inputs incorporated METI JIS protocol update schedules and EU F-Gas Regulation phasedown compliance trajectories.
Underlying measurement precision varies by segment; aerospace and defense qualification timelines carry tighter precision than aftermarket sheet stock volumes. Forecasts reflect documented assumptions on compounding capacity expansion rates and regulatory disclosure threshold evolution. Material deviation in carbon black supply disruption, REACH SVHC list expansion velocity, or defense procurement unbundling completion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Europe Polypropylene Market