
 Rigid Packaging Market | 2026-2036
Rigid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Packaging Market Analysis
Modular container sizing is broadening buyer choice across retail and e-commerce channels. Amcor plc leverages its global manufacturing footprint to supply standardized formats that reduce line-changeover costs for food processors. Berry Global Inc. sustains R&D intensity in thin-wall injection molding for dairy and condiment segments. Silgan Holdings Inc. anchors its position through captive metal supply and decorated closure technologies for branded CPG customers.
Rigid packaging comprises structurally self-supporting containers—bottles, jars, boxes, and formed containers—manufactured from plastic resins, glass, metal, or paperboard at wall thicknesses and geometries that protect contents without supplemental support during handling, distribution, and shelf display. Its primary purpose is to preserve product integrity, enable stackability, and provide surfaces for branding and regulatory labeling across supply chain touchpoints. Plastic bottles and containers lead volume due to resin versatility and barrier customization, though glass jars command premium positioning in cosmetics and specialty foods where inertness and recyclability signal quality. Paperboard boxes represent the fastest-growing material conversion as e-commerce fulfillment demands lightweight, printable, and curbside-recyclable secondary packaging. Metal containers remain mature in food preservation but face displacement in non-acidic segments where polymer barriers now match shelf-life performance.
EPA guidelines on recycled content thresholds, EU Packaging and Packaging Waste Regulation requirements for extended producer responsibility, and FDA food-contact substance notifications collectively shape material selection, design-for-recycling mandates, and market access conditions for suppliers and brand owners. BIS certification for food-grade plastics and GB standards on heavy-metal limits in glass and ceramics add compliance layers for exporters serving India and China. Stakeholders must monitor how fragmented national EPR implementations alter cost structures and format preferences before committing capital to regional molding or forming capacity.
Market Dynamics
Lightweighting imperatives and EPR mandates are compressing format diversity while concentrating procurement toward suppliers with integrated recycling infrastructure and multi-material forming capabilities.
Growth Catalysts
- EPR mandates in Germany and the United States:Food and beverage brands are expanding reusable glass bottle systems under state-level recycling laws and federal packaging directives.
- PET barrier technology:Lightweighting innovations are redirecting material demand away from heavier glass and metal formats in condiment and dairy segments.
- India and Southeast Asia:FMCG companies are localizing supply chains to serve regional consumption growth in rigid containers.
Market Restraints
- Resin price volatility:Petrochemical feedstock fluctuations compress margin buffers for converters serving price-locked CPG contracts.
- Glass furnace concentration:Heavy capital requirements and energy intensity limit new entrant supply in premium cosmetic and specialty food segments.
- Multi-layer barrier incompatibility:Current mechanical recycling infrastructure cannot process bonded polymer structures, creating stranded material volumes.
Strategic Opportunities
- Curbside-recyclable paperboard:E-commerce fulfillment demand for printable, lightweight secondary packaging is accelerating format conversion from plastic corrugate.
- BIS certification pathways:Exporters serving India can capture food-grade plastic share by pre-qualifying against national standards ahead of competitors.
- Decorated closure integration:Convergence of metal forming and digital printing enables premium branded differentiation without separate label application.
Industry Challenges
- Design-for-recycling skill scarcity:Packaging engineers with cross-material expertise in polymer science and paperboard fiber engineering command premium compensation.
- Legacy line-changeover friction:Food processors face downtime costs and quality validation cycles when shifting between rigid format specifications.
- Fragmented EPR implementation:National variations in extended producer responsibility fee structures complicate pan-regional pricing and contract terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Packaging Market |
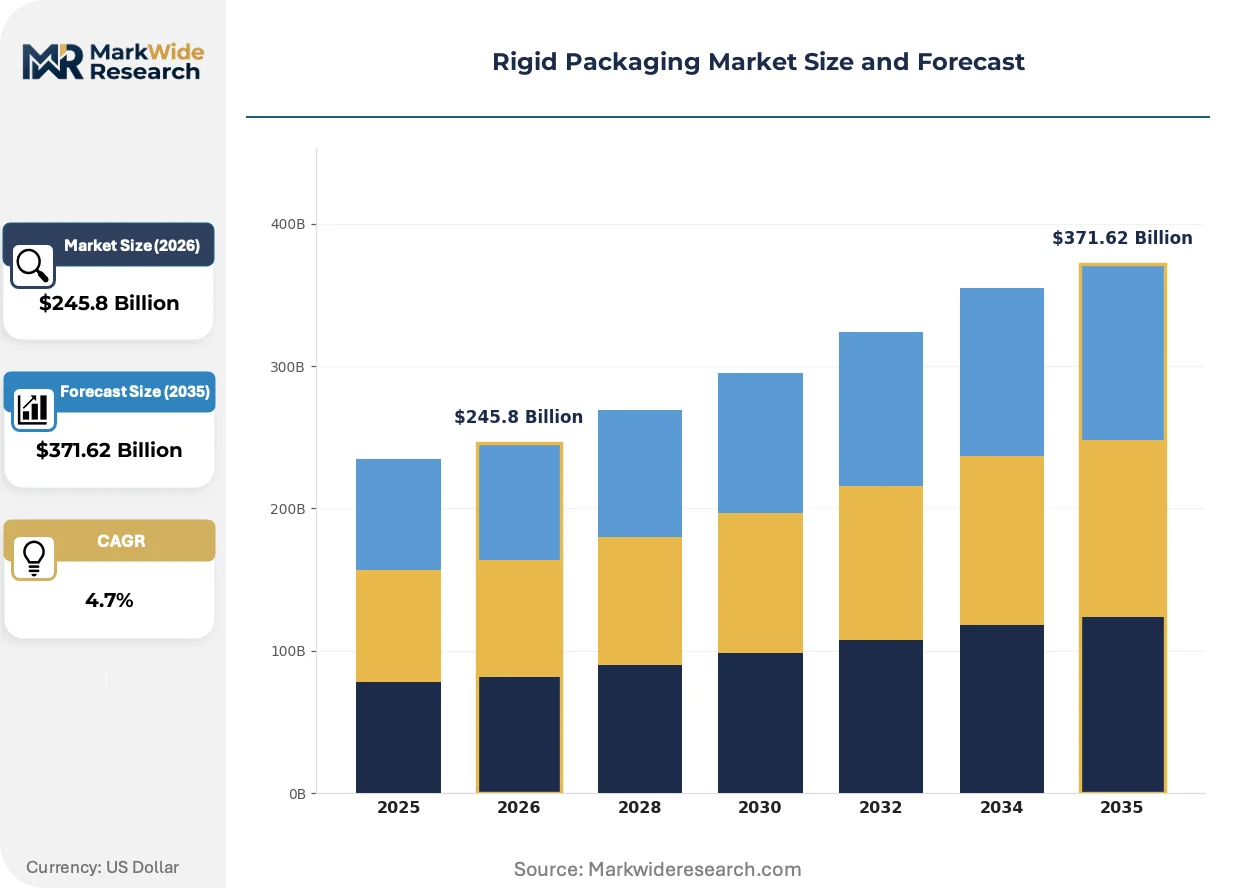
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $371.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Boxes Material: Plastic, Glass, Metal, Paperboard End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Shape: Square, Round, Rectangular, Custom |
| Companies Covered | Amcor plc, Berry Global Inc., Silgan Holdings Inc., DS Smith plc, ALPLA, Sonoco Products Company, Pactiv Evergreen Inc., Plastipak Holdings Inc., Graham Packaging Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Packaging Market Emerging Trajectories
Active and intelligent packaging integration, regulatory pressure on recycled content thresholds, and channel-specific format optimization are redefining competitive capability requirements across material categories.
Mono-material barrier films are consolidating technical pathways for shelf-life extension in non-acidic food preservation. Mid-tier CPG brands in North America and Western Europe are adopting these structures at accelerated validation cycles. This consolidation is compressing demand for traditional metal can formats in segments where polymer barriers now match performance specifications.
EU Packaging and Packaging Waste Regulation requirements for extended producer responsibility are mandating design-for-recycling protocols across all material classes. Industrial consequence includes mandatory recycled content minimums and harmonized collection infrastructure investments. Food-contact applications in France and Italy are responding fastest, with national transposition timelines accelerating supplier qualification deadlines.
Direct-to-consumer fulfillment is fragmenting secondary packaging specifications between retail-ready display formats and ship-alone protective structures. E-commerce pure-play brands are displacing traditional retail assortment economics with volume-optimized container sizing. This behavioral pivot is most visible in Southeast Asia, where platform logistics providers are dictating dimensional weight standards that favor collapsible or nestable rigid designs.
Rigid Packaging Market Segmentation
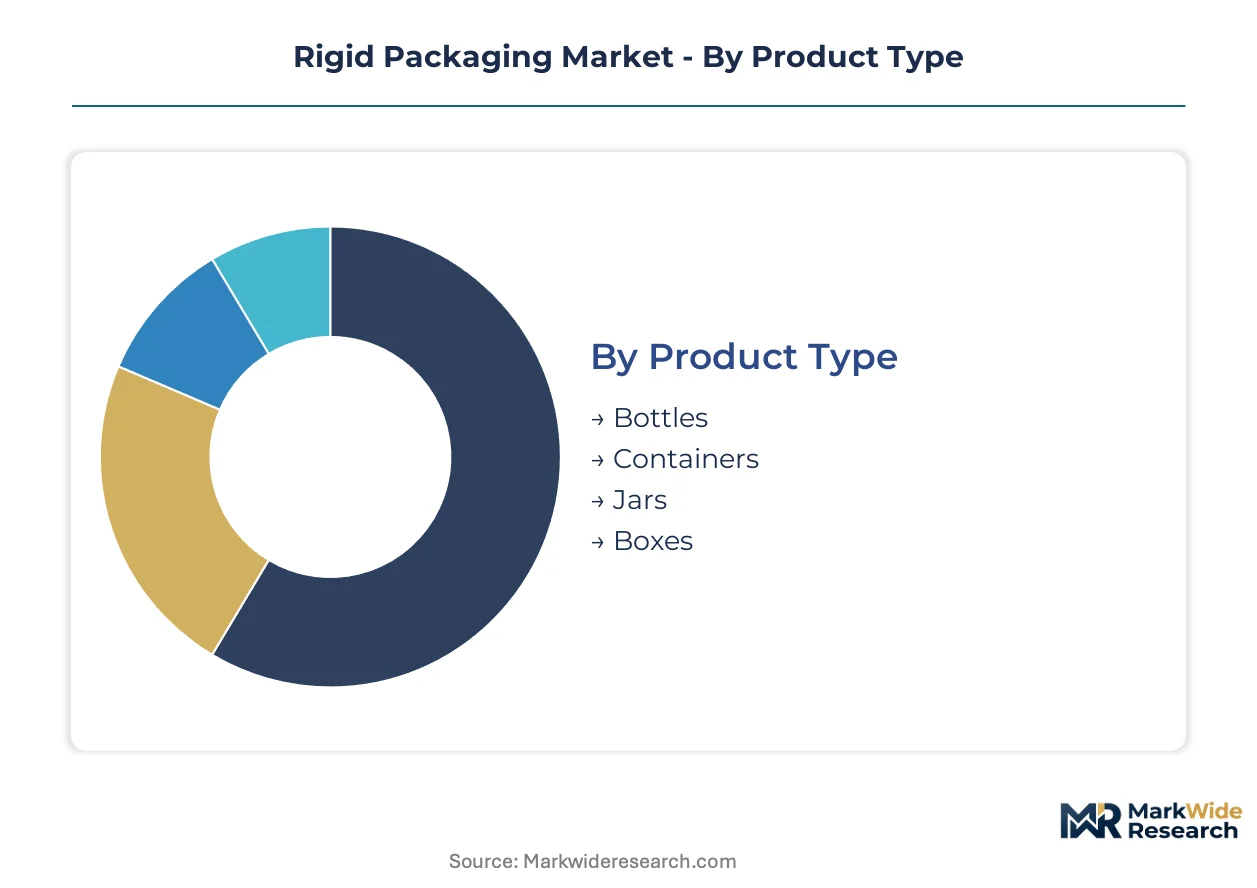
Rigid packaging segmentation reveals how capital allocation, regulatory compliance, and channel requirements fragment procurement decisions across converters and brand owners. Material selection and format geometry determine line compatibility, recycling infrastructure access, and logistics cost structures for end-users.
Product Type:
Capital intensity varies sharply across forming technologies, with blow molding and injection systems demanding the highest upfront tooling investment.
- Bottles:Blow-molded structures dominate liquid containment across beverages, condiments, and personal care. PET barrier innovations in Germany and the United States are displacing heavier glass formats under EPR mandates and lightweighting targets.
- Containers:Injection-molded tubs and trays serve dairy, prepared meals, and industrial chemicals. India and Southeast Asia concentrate new demand as FMCG companies localize supply chains for regional consumption growth.
- Jars:Wide-mouth formats preserve viscous products and enable spoon access. Glass variants command premium positioning in cosmetics and specialty foods where inertness signals quality.
- Boxes:Paperboard and corrugated formats provide stackable secondary protection. E-commerce fulfillment demand is accelerating format conversion from plastic corrugate to curbside-recyclable alternatives.
Bottles absorb the bulk of installed capacity; boxes are expanding most quickly.
Material:
Resin versatility and barrier customization drive procurement patterns, though regulatory pressure on recycled content thresholds is reshaping qualification criteria.
- Plastic:PET, HDPE, and PP resins offer tunable barrier properties and lightweight logistics. Multi-layer structures face mechanical recycling incompatibility, creating stranded material volumes and design-for-recycling imperatives.
- Glass:Silicate-based containers provide inertness and infinite recyclability. Heavy capital requirements and energy intensity limit new furnace supply in premium cosmetic and specialty food segments.
- Metal:Tinplate and aluminum preserve acidic and thermally processed foods. Polymer barrier advances in non-acidic segments are compressing traditional can demand.
- Paperboard:Fiber-based formats enable printing, nesting, and curbside recovery. Secondary packaging specifications fragment between retail-ready display formats and ship-alone protective structures.
Plastic commands the largest share of production assets; paperboard is climbing the fastest on e-commerce demand.
End User:
Regulatory stringency and shelf-life requirements segment material preferences across compliance-sensitive applications.
- Food & Beverage:The largest consumption category spanning preservation, convenience, and portion control. FDA food-contact substance notifications and EU Packaging and Packaging Waste Regulation shape material selection and design protocols.
- Pharmaceuticals:Barrier integrity and child-resistance mandates dominate specification. CDSCO and EMA requirements drive qualification cycles for primary and secondary packaging.
- Cosmetics:Aesthetic differentiation and premium signaling justify glass and decorated closure investments. Specialty brands in France and Italy respond fastest to harmonized collection infrastructure investments.
- Electronics:Anti-static and impact-resistant formats protect high-value components during distribution. Platform logistics providers in Southeast Asia dictate dimensional weight standards favoring nestable designs.
Food & Beverage holds the deepest installed base; cosmetics is gaining share fastest on premiumization trends.
Shape:
Geometry determines palletization efficiency, shelf presence, and line-changeover compatibility for automated filling systems.
- Square:Maximizes cube utilization in warehousing and transport. Retail-ready formats optimize shelf space productivity in constrained store environments.
- Round:Distributes internal pressure evenly for carbonated and pressurized contents. Blow molding tooling favors radial symmetry for material distribution control.
- Rectangular:Balances display surface area with logistics density. E-commerce pure-play brands favor volume-optimized sizing for dimensional weight calculations.
- Custom:Proprietary geometries enable branded differentiation and ergonomic handling. Digital printing convergence reduces minimum order quantities for specialized formats.
Round formats retain the widest tooling footprint; custom shapes are expanding most quickly on digital manufacturing flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, the United States, and China while consumption growth concentrates in India and Southeast Asia. This geographic mismatch shapes investment flows and regulatory arbitrage strategies for converters and brand owners.
United States
State-level recycling laws in California and New York drive reusable glass bottle expansion for beverage brands. EPA guidelines on recycled content thresholds reshape material selection for food-contact applications. Midwest industrial corridors concentrate blow molding capacity serving national CPG distribution networks.
Germany
EPR mandates accelerate lightweighting investments in PET barrier technology for condiment and dairy segments. EU Packaging and Packaging Waste Regulation transposition creates harmonized collection infrastructure deadlines. Bavaria hosts specialized glass furnace operations supplying premium cosmetic and specialty food markets.
China
GB standards on heavy-metal limits in glass and ceramics redirect export qualification protocols for rigid container manufacturers. NMPA food-contact substance notifications govern polymer selection for domestic pharmaceutical packaging. Yangtze River Delta clusters integrate injection molding capacity with e-commerce fulfillment platform specifications.
India
FSSAI compliance requirements and BIS certification pathways for food-grade plastics attract pre-qualified exporter investment. FMCG localization strategies concentrate demand in Maharashtra and Gujarat for dairy and prepared meal containers. DGFT import substitution policies accelerate domestic forming capacity expansion.
Vietnam
Regional supply chain repositioning by multinational CPG brands concentrates container sourcing in Ho Chi Minh City industrial zones. Platform logistics providers dictate dimensional weight standards favoring nestable rigid designs for cross-border e-commerce. Emerging technical workforce pools support thin-wall injection molding technology transfer from North Asian equipment suppliers.
Rigid Packaging Market Vendor Landscape
The competitive structure tilts toward diversified material specialists with integrated recycling infrastructure. Consolidation pressure concentrates procurement authority among converters offering multi-material forming capabilities and pan-regional compliance management. Three archetypes dominate: resin-versatile plastic converters, captive metal supply operators, and fiber-based secondary packaging innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure EPR-aligned collection and reprocessing networks.
Among diversified packaging conglomerates, Amcor plc and Berry Global Inc. exemplify scale-driven material versatility across blow molding and injection forming technologies. Silgan Holdings Inc. occupies a specialist position in metal container and closure integration for branded CPG applications. These three anchors represent distinct strategic pathways: resin customization, thin-wall process intensity, and decorated metal differentiation.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| DS Smith plc |
| ALPLA |
| Sonoco Products Company |
| Pactiv Evergreen Inc. |
| Plastipak Holdings Inc. |
| Graham Packaging Company Inc. |
| Others |
Supply Flow & Price Mechanics
Mono-material barrier film adoption simultaneously compresses per-unit production costs and concentrates supplier power among converters with integrated recycling infrastructure. This technical transition rewards early movers who pre-qualify against EU Packaging and Packaging Waste Regulation recycled content thresholds while penalizing legacy multi-layer producers facing stranded material volumes.
Pricing Analysis
Margin tightening in standard-grade plastic containers reflects resin price volatility and petrochemical feedstock fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates certified food-grade suppliers from commodity converters and virgin-material-dependent producers. Cost-down pressure accelerates because CPG procurement teams consolidate vendor lists toward EPR-compliant partners. Food processors locked into annual contracts show highest price sensitivity; premium cosmetic brands demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from multinational FMCG brands mandate qualified suppliers across Germany, the United States, and China to mitigate tariff exposure and regional disruption risks. Raw material dependencies center on PET resin, food-grade paperboard fiber, and tinplate for metal closures. Supply chain risk concentrates in single-source glass furnace operations serving premium cosmetic segments. Distribution runs through regional co-packing networks and direct-to-warehouse fulfillment for e-commerce pure-plays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lightweighting PET barrier technology is displacing glass and metal formats across condiment and dairy segments, compressing legacy converter margins while opening white-space for mono-material specialists.
For Market Incumbents: Extend backward integration into captive recycling infrastructure to secure EPR-compliant material streams before harmonized collection deadlines tighten. Add blow molding capacity in India and Southeast Asia where FMCG localization concentrates demand growth. Defend against emerging mono-material specialists by accelerating thin-wall injection molding R&D in dairy applications.
For New Entrants and Emerging Players: Begin with BIS certification pathways for food-grade plastics serving Maharashtra and Gujarat industrial corridors, where pre-qualified exporters capture share ahead of competitors. Target curbside-recyclable paperboard secondary packaging for Southeast Asian e-commerce fulfillment platforms dictating nestable dimensional standards. Go-to-market through platform logistics provider specifications rather than traditional retail channel penetration.
For Investors and Strategic Acquirers: Exit pathways concentrate in diversified converters with multi-material forming capabilities and pan-regional EPR compliance management. Five-to-ten year viability favors suppliers integrating decorated closure technologies with captive metal supply. Target acquisition archetype: thin-wall injection molding specialists with India-based technical workforce pools. Watch mono-material shelf-life performance validation cycles as inflection signal for metal can displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Secures EPR-compliant material streams ahead of EU harmonized collection deadlines. |
| Thin-Wall Injection Molding Scale-Up | Captures dairy and condiment demand in India and Southeast Asia localization zones. |
| BIS Certification Pre-Qualification | Unlocks food-grade plastic share in Maharashtra and Gujarat ahead of competitor entry. |
| Decorated Closure Technology Convergence | Enables premium branded differentiation without separate label application costs. |
| Curbside-Recyclable Paperboard Conversion | Aligns with platform logistics dimensional weight standards in Southeast Asian e-commerce. |
Methodological Framework
Independent corroboration across converter plant managers, FMCG procurement leads, and distribution channel partners underwrites the qualitative findings in this study. Primary interviews with packaging engineers and regulatory affairs specialists at food-contact substance notification firms combined with secondary validation from FDA food-contact substance databases, EU Packaging and Packaging Waste Regulation transposition documents, and BIS certification records. Bottom-up capacity assessments triangulate against top-down consumption estimates across material categories.
Comparable-period anchoring to historical PET barrier adoption curves and glass furnace investment cycles shaped the projection horizon. Segmentation modeling spans product type, material class, end-use industry, and regional regulatory cluster. CAGRs derive from installed capacity expansion schedules and localization-driven demand shifts. Forecast inputs include EPR fee structure variations and mechanical recycling infrastructure deployment timelines.
Underlying measurement precision varies by segment; plastic bottles and containers carry tighter precision than emerging paperboard secondary packaging categories. Forecasts reflect assumptions about regulatory implementation pace and resin price stabilization. Deviation in EU harmonized collection infrastructure investment or India FSSAI enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Mono-Material Trays Market