
 Fiber Rich Flours Market | 2026-2036
Fiber Rich Flours Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Rich Flours Market Analytics
Ingredient sourcing margins is narrowing as commodity wheat traders compete with branded specialty millers for premium fiber positions. Cargill Incorporated leverages its global grain origination network to secure high-fiber wheat varietals at scale. Bob's Red Mill Natural Foods anchors the natural channel through direct-to-retailer relationships and certified organic positioning. Ingredion Incorporated differentiates via modified resistant starch technologies that boost fiber claims without altering finished-product texture.
Fiber rich flours comprise milled grain, legume, nut, or seed products retaining substantial dietary fiber content, typically achieving minimum thresholds through controlled milling processes that preserve bran layers or incorporate whole-food fiber concentrates. These flours function primarily as nutritional fortifiers and texture modifiers in commercial food production, enabling manufacturers to achieve front-of-package fiber claims while maintaining acceptable rheological properties in dough and batter systems. Wheat flour and oat flour command the largest volume positions, with oat flour recording the fastest trajectory as gluten-free and beta-glucan positioning expands across breakfast foods and snack applications. Almond flour and coconut flour occupy premium niches where fat-content management and ketogenic-diet alignment justify substantially higher price points per unit.
FDA nutrition labeling rules and the EU Green Deal's Farm to Fork strategy are tightening permissible fiber-definition standards, compelling suppliers to substantiate physiological benefits through validated analytical methods. Health Canada and EFSA both mandate specific fiber-type disclosures that influence product-positioning strategies across North American and European retail channels. Stakeholders must monitor evolving codex definitions and procurement-grade specifications to avoid reformulation costs and market-access disruptions.
Market Dynamics
Clean-label reformulation mandates under the EU Green Deal and FDA nutrition labeling updates are forcing simultaneous fiber-content escalation and ingredient-list simplification across commercial baking operations.
Growth Catalysts
- EU Farm to Fork Strategy:Binding fiber-content targets in processed foods are accelerating wheat bran and oat beta-glucan incorporation across continental bakery chains.
- Gluten-free breakfast applications:Oat flour's beta-glucan positioning is capturing expanded shelf space in European and North American cereal and snack bar segments.
- Hamburg-Munich milling corridor:German specialty millers are scaling certified organic fiber blends to supply reformulating artisan and industrial bakeries.
Market Restraints
- High-fiber wheat varietal scarcity:Limited acreage dedicated to premium fiber-rich wheat strains concentrates supply risk among North American and Black Sea originators.
- Modified resistant starch IP concentration:Patent thickets around Ingredion-type texture-preserving fiber technologies restrict formulation freedom for mid-tier manufacturers.
- Almond flour input volatility:California drought cycles and water allocation disputes inject price instability into premium nut-flour positioning.
Strategic Opportunities
- Indian FSSAI fiber-definition modernization:Pending regulatory alignment with Codex standards opens formulation pathways for resistant starch and novel fiber entrants in processed food manufacturing.
- Ketogenic bakery subsegment:Coconut flour's fat-content profile aligns with low-carbohydrate diet protocols in North American and Australian specialty channels.
- Direct-to-manufacturer digital procurement:Specialty millers are bypassing traditional ingredient distributors to capture margin and formulation collaboration rights with mid-size food manufacturers.
Industry Challenges
- Analytical validation capacity gaps:EFSA and Health Canada fiber-type disclosure mandates require specialized in-house or contracted testing infrastructure that smaller suppliers struggle to fund.
- Cross-functional reformulation expertise:Bridging cereal chemistry, regulatory affairs, and sensory science competencies delays product relaunches and increases failed submission rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Rich Flours Market |
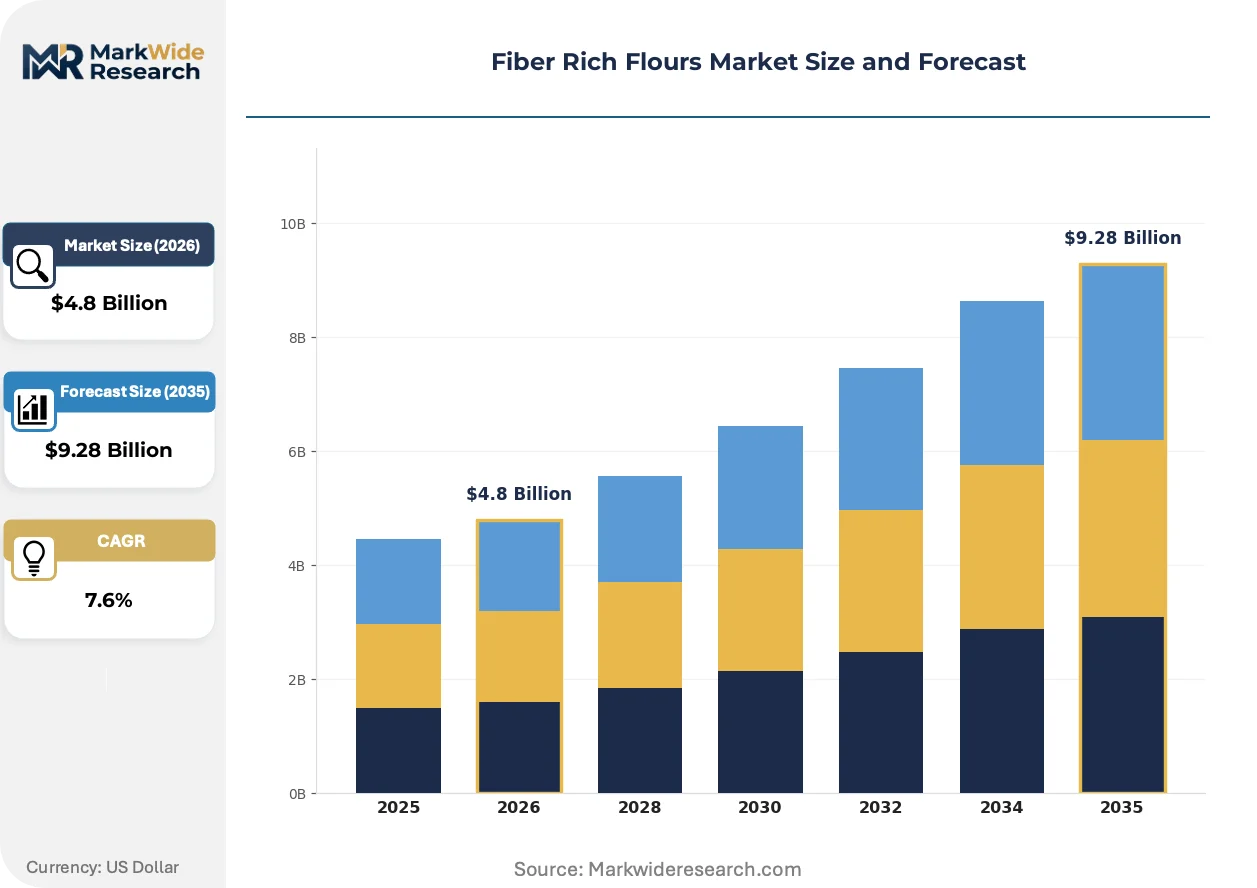
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour, Almond Flour, Oat Flour, Coconut Flour Application: Baking, Thickening Agent, Snack Foods, Breakfast Foods End User: Households, Food Manufacturers, Bakeries, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, General Mills Inc., Bob's Red Mill Natural Foods, Ingredion Incorporated, Associated British Foods plc, Bunge Limited, King Arthur Baking Company, SunOpta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Rich Flours Market Evolving Landscape
Controlled milling technologies and enzymatic fiber modification are compressing the trade-off between nutritional density and finished-product acceptability that historically constrained clean-label expansion.
Air-classification milling systems are collapsing the particle-size distribution gaps between refined and whole-grain flours. European industrial bakeries are adopting these systems at accelerated replacement cycles for legacy roller mills. This compression is collapsing the texture penalty that previously limited high-fiber claims in premium cake and pastry categories.
EFSA's 2022 guidance on dietary fiber health claims tightened substantiation requirements for isolated and synthetic fiber types. Manufacturers must now demonstrate physiological benefits through validated analytical methods for each fiber source. Bakery and cereal segments in Germany, France, and the Netherlands are reformulating toward intact botanical fibers to preempt claim rejection risks.
Ingredient buyers are consolidating supplier relationships around vertically integrated millers who control varietal selection through contract farming. Mid-size food manufacturers are displacing multi-source commodity purchasing with single-origin certified programs. This concentration is most visible in German milling clusters supplying private-label retail chains.
Fiber Rich Flours Market Segmentation
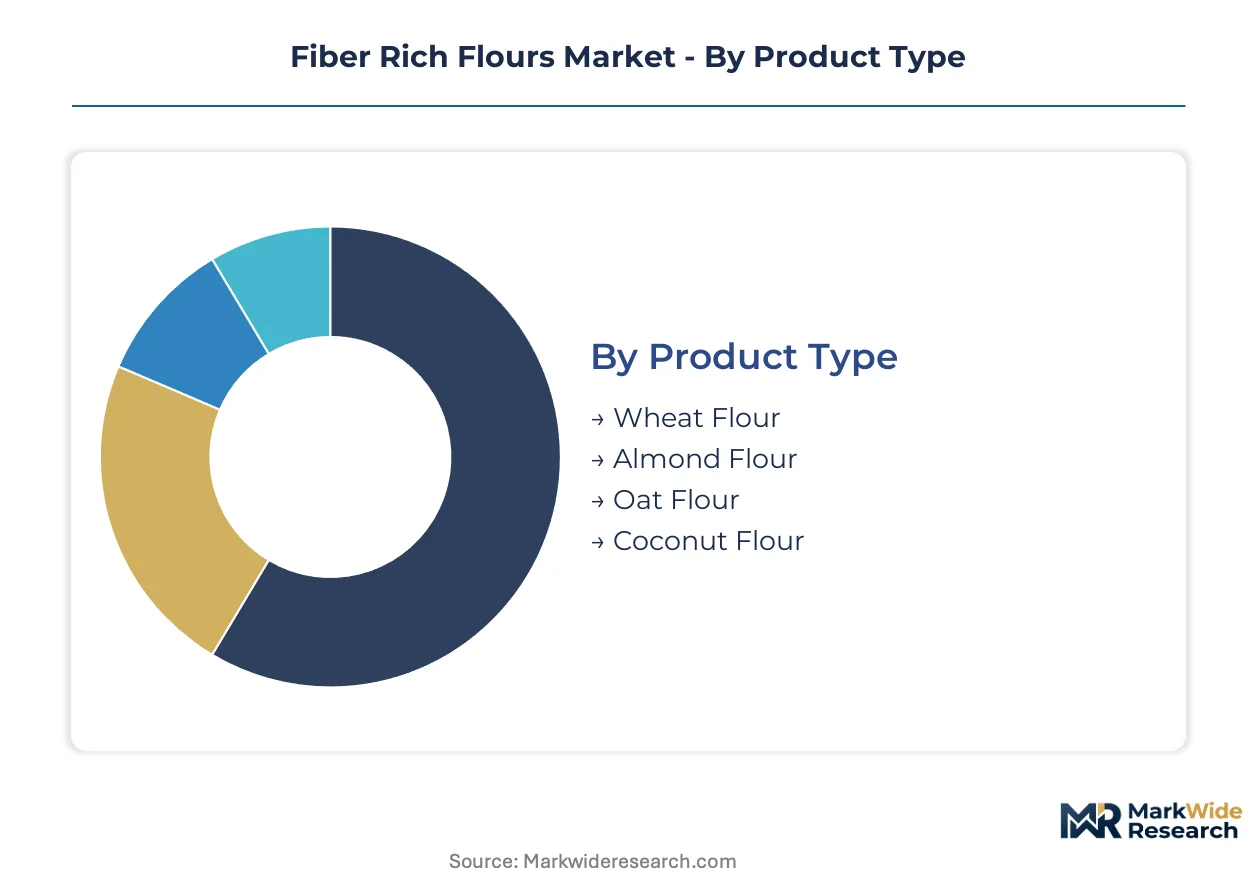
Fiber rich flours segment across four intersecting dimensions that determine procurement patterns and margin structures. Product type defines technical specifications and clean-label positioning, while application and end-user categories dictate volume concentration and channel strategy.
Product Type:
Wheat flour and oat flour turn inventory fastest through industrial bakery contracts, while almond and coconut flours move slower through premium specialty channels with higher per-unit margins.
- Wheat Flour:Retains bran layers through controlled milling to achieve fiber thresholds without sacrificing dough rheology. German milling clusters near Hamburg supply reformulating continental bakeries under EU Green Deal fiber mandates. Wheat flour anchors the volume base while oat flour gains share at the steepest rate.
- Oat Flour:Delivers beta-glucan soluble fiber with gluten-free positioning that captures expanded cereal and snack bar shelf space. North American breakfast food manufacturers are accelerating oat flour procurement for dual fiber-claim and allergen-free formulations.
- Almond Flour:Premium nut flour with high fat content serving ketogenic and paleo diet protocols through health food stores and direct-to-consumer channels.
- Coconut Flour:High-fiber byproduct of coconut oil extraction, absorbing moisture aggressively in low-carbohydrate bakery applications with concentrated demand in Australian and North American specialty segments.
Oat flour expands most quickly on gluten-free positioning, while wheat flour retains volume leadership through industrial bakery scale.
Application:
Cost tiers stratify sharply: baking commands commodity-scale pricing, while snack foods and breakfast foods support premium positioning through functional fiber claims.
- Baking:Largest volume sink for fiber-rich flours across artisan and industrial bread, cake, and pastry production. EFSA fiber-definition compliance is forcing German and French bakeries toward intact botanical fiber sources rather than isolated additives.
- Breakfast Foods:Cereal and granola manufacturers leverage oat flour's beta-glucan claims for front-of-package health positioning. This segment climbs the fastest as clean-label reformulation accelerates across European and North American retail chains.
- Snack Foods:Energy bars, crackers, and extruded snacks incorporate fiber flours for texture modification and nutritional fortification in grab-and-go formats.
- Thickening Agent:Functional applications in sauces, soups, and gravies where fiber content provides viscosity without caloric density.
Baking absorbs the highest absolute tonnage while breakfast foods drive the steepest expansion trajectory on regulatory-compliant fiber claims.
End User:
Procurement scale determines supplier relationship type: food manufacturers negotiate multi-year contracts, while households purchase through fragmented retail with minimal volume commitment.
- Food Manufacturers:Industrial-scale buyers driving formulation standardization across private-label and branded processed foods. These stakeholders face simultaneous FDA and EU Green Deal compliance deadlines that compress reformulation timelines.
- Bakeries:Range from artisan operations sourcing certified organic blends from German specialty millers to industrial chains requiring consistent fiber specification at commodity volumes.
- Health Food Stores:Curated channel for premium almond and coconut flour positioning toward dietary-specific consumers.
- Households:Fragmented demand through retail and online channels, with purchasing decisions driven by front-of-package fiber claims and clean-label ingredient lists.
Food manufacturers dominate procurement volume while health food stores capture the highest margin per kilogram.
Distribution Channel:
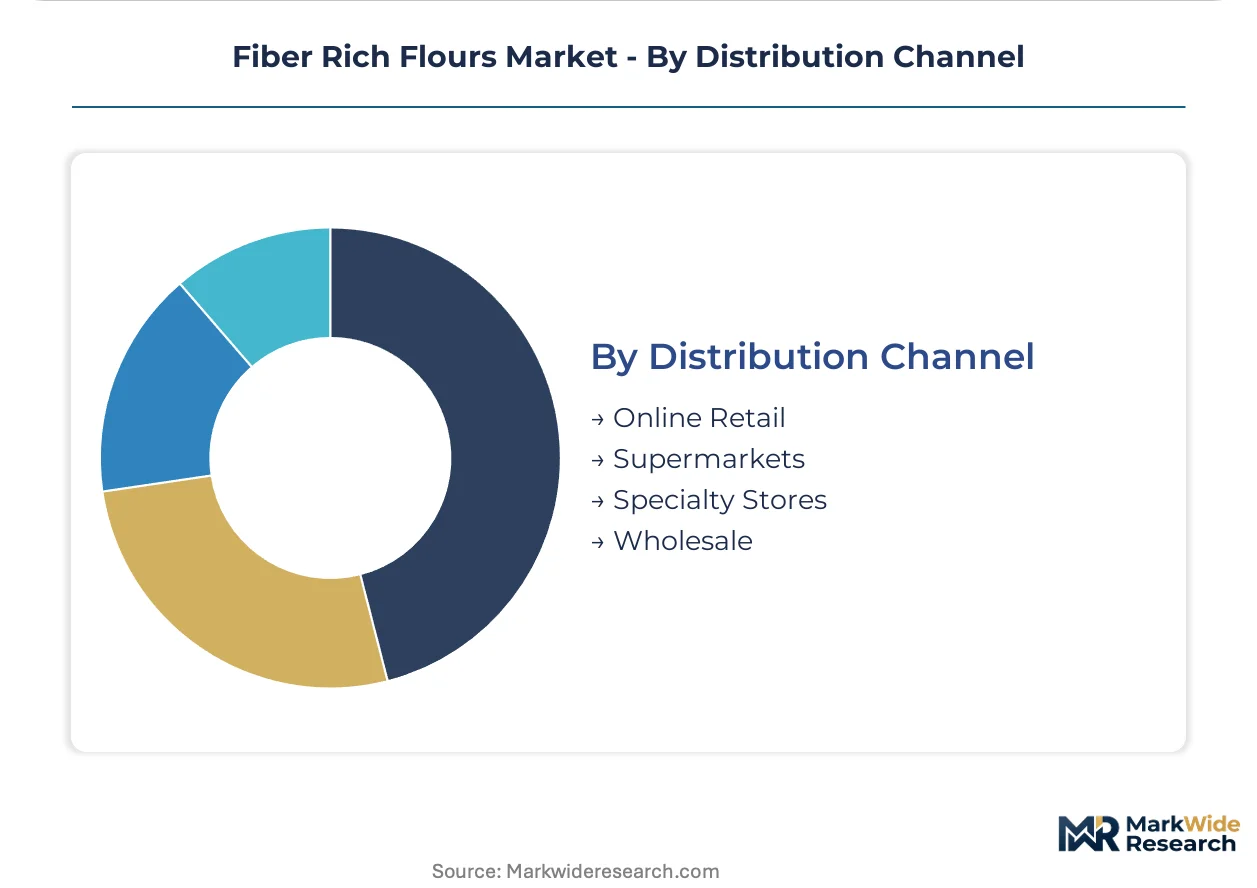
Channel selection correlates directly with end-user scale: wholesale and direct procurement serve manufacturers, while specialty stores and online retail fragment toward households and small bakeries.
- Wholesale:Bulk supply relationships between specialty millers and food manufacturers or industrial bakery chains, often with formulation collaboration and certified organic program integration.
- Supermarkets:Mass retail placement for wheat and oat flour SKUs with fiber callouts on primary packaging.
- Specialty Stores:Premium channel for almond, coconut, and certified organic wheat blends with narrative-driven provenance marketing.
- Online Retail:Direct-to-consumer growth channel enabling specialty millers to bypass traditional distributors and capture margin through subscription and bulk purchasing models.
Wholesale channels anchor volume throughput while online retail expands most rapidly on direct-to-manufacturer and direct-to-consumer disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: European buyers absorb premium pricing for certified organic fiber blends, while price-sensitive markets in Asia-Pacific prioritize volume-scale wheat bran fortification.
United States
FDA nutrition labeling updates are accelerating clean-label reformulation across industrial bakeries and breakfast food manufacturers. The agency's tightened fiber-definition standards compel suppliers to substantiate physiological benefits through validated analytical methods. Minneapolis-St. Paul anchors North American milling operations, with specialty millers scaling certified organic programs to supply reformulating national bakery chains.
Germany
EU Green Deal Farm to Fork binding fiber-content targets are driving wheat bran and oat beta-glucan incorporation across continental bakery chains. EFSA's 2022 guidance on dietary fiber health claims mandates specific fiber-type disclosures that reshape product-positioning strategies. The Hamburg-Munich milling corridor concentrates specialty miller capacity, with clusters near both cities scaling certified organic fiber blends for artisan and industrial bakeries.
India
FSSAI fiber-definition modernization pending alignment with Codex standards is opening formulation pathways for resistant starch and novel fiber entrants in processed food manufacturing. The country's national food regulator is tightening permissible fiber standards to match evolving international benchmarks. Maharashtra and Gujarat house expanding milling operations serving domestic breakfast food and snack manufacturers accelerating clean-label adoption.
Canada
Health Canada fiber-type disclosure mandates are influencing product-positioning strategies across North American retail channels, with Canadian manufacturers aligning formulation standards to U.S. export requirements. The Prairie Provinces concentrate high-fiber wheat varietal cultivation, with contract farming programs securing premium fiber-rich grain supplies for specialty millers. Toronto and Vancouver serve as formulation collaboration hubs linking Prairie grain origination to packaged food manufacturing.
Australia
Ketogenic diet protocol alignment is concentrating coconut flour demand in specialty channels, with health food stores and direct-to-consumer platforms capturing expanded shelf space for low-carbohydrate bakery applications. The country's national food standards code governs fiber claim substantiation requirements that parallel Codex Alimentarius frameworks. Sydney and Melbourne anchor premium nut-flour distribution networks supplying reformulating artisan bakeries and health-focused retail chains.
Fiber Rich Flours Market Competitive Landscape
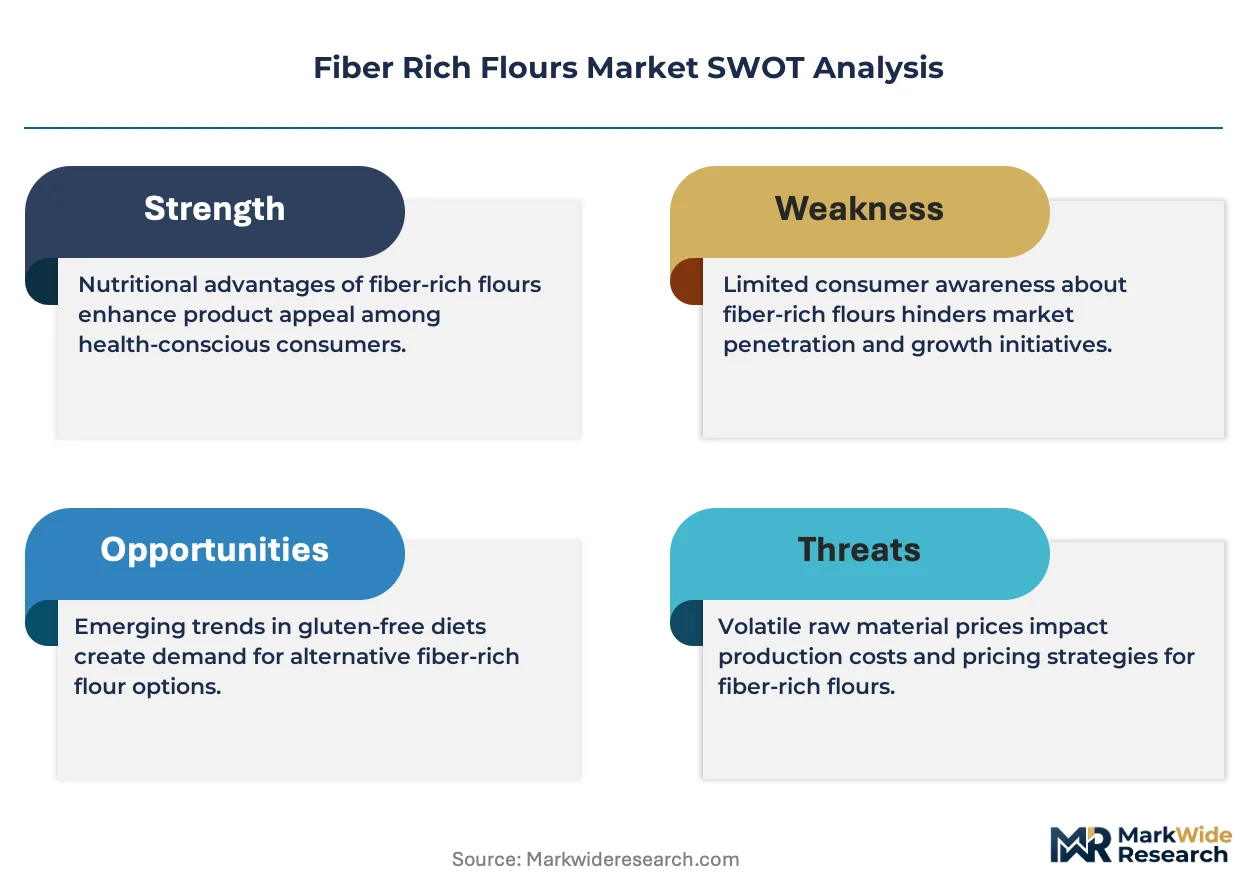
Capability concentration sits with specialty millers commanding certified organic and clean-label formulation expertise; scale advantage sits with diversified grain processors leveraging global origination networks. The market structures around three tiers: integrated agribusiness conglomerates, mid-cap specialty millers with vertical grain control, and niche organic-certified operators. Dominant competitive moves include backward integration into contract farming for high-fiber varietal security and direct-to-manufacturer digital procurement platforms that displace traditional ingredient distributors.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven origination and processing capabilities. Among specialty millers with natural-channel positioning, Bob's Red Mill Natural Foods occupies a position exemplifying certified organic and direct-to-retailer relationship models. Ingredion Incorporated represents the functional ingredient technology tier, with modified resistant starch capabilities serving manufacturers seeking texture-preserving fiber fortification.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| General Mills Inc. |
| Bob's Red Mill Natural Foods |
| Ingredion Incorporated |
| Associated British Foods plc |
| Bunge Limited |
| King Arthur Baking Company |
| SunOpta Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in German certified organic milling capacity is compressing supplier bargaining power and elevating contract premiums for reformulating continental bakeries. This utilization squeeze simultaneously tightens input procurement timelines and rewards millers who secured high-fiber wheat varietals through forward contract farming.
Pricing Analysis
After-sales formulation collaboration and multi-year technical service contracts drive lifetime value for specialty millers serving industrial bakery chains. Three-tier pricing structure across certified organic, conventional premium, and commodity-standard levels separates EFSA-compliant fiber blends from basic wheat bran fortification. Price differentiation hinges on beta-glucan assay certification and organic program integration. Cost compression in the commodity wheat fiber tier is intensifying because Black Sea originators are diverting acreage toward higher-margin protein wheat. Mid-size food manufacturers exhibit the sharpest price sensitivity, while artisan bakeries in the Hamburg-Munich corridor absorb premiums for provenance-verified supply.
Supply Chain Analysis
Upstream high-fiber wheat varietal development centers on the Prairie Provinces, Black Sea origins, and German contract farming programs. Raw material flows draw from certified seed multiplication, controlled atmosphere storage infrastructure, and enzymatic fiber modification inputs. Single-source vulnerability concentrates in California almond flour supply where drought-driven water allocation disputes disrupt harvest reliability. Distribution runs through direct-to-manufacturer digital procurement platforms that displace traditional ingredient distributors and capture formulation collaboration rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players who command scarce cross-functional expertise bridging cereal chemistry, regulatory affairs, and sensory science. The capability gap between integrated agribusiness conglomerates and mid-tier reformulation specialists is widening as EFSA and FDA compliance deadlines compress.
For Market Incumbents: Insulate fiber-claim substantiation capabilities through in-house analytical validation infrastructure that preempts EFSA rejection risks. Deepen backward integration into contract farming for high-fiber wheat varietals in the Prairie Provinces and Black Sea origins to secure supply continuity against acreage competition from protein wheat. Control channel position by acquiring direct-to-manufacturer digital procurement platforms that lock in formulation collaboration rights with mid-size food manufacturers. For New Entrants and Emerging Players: Build out resistant starch and novel fiber capabilities targeting India's FSSAI modernization pathway as regulatory alignment with Codex standards opens formulation access. The ketogenic bakery subsegment in North American and Australian specialty channels offers the most penetrable white space, with coconut flour's fat-content profile aligning to low-carbohydrate diet protocols. Lead with certified organic positioning and subscription-based direct-to-consumer distribution to bypass entrenched wholesale relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and analytical validation capital requirements are structurally disadvantaging sub-scale suppliers. Target vertically integrated specialty millers commanding certified organic programs and direct-to-manufacturer digital procurement capabilities. Watch the Indian FSSAI fiber-definition modernization timeline as an inflection signal for resistant starch market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Secures high-fiber wheat varietals in Prairie Provinces against protein wheat acreage competition. |
| Direct-to-Manufacturer Digital Procurement Platform | Captures margin and formulation collaboration rights with mid-size food manufacturers. |
| In-House Analytical Validation Infrastructure | Preempts EFSA fiber-claim rejection risks and accelerates product relaunch timelines. |
| Certified Organic Program Expansion | Aligns with EU Green Deal Farm to Fork binding fiber-content targets in continental bakeries. |
| Resistant Starch Technology Licensing | Opens formulation pathways in India pending FSSAI alignment with Codex standards. |
Research Methodology
Cross-validation between primary interviews with specialty millers, food manufacturer R&D directors, and regulatory affairs consultants anchors the qualitative findings against secondary validation from EFSA guidance documents, FDA nutrition labeling updates, and FSSAI regulatory circulars. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis and certified organic program disclosures. This approach combines field-sourced procurement pattern intelligence with published compliance deadlines and milling capacity utilization signals.
Calibration against historical fiber-fortification adoption curves and clean-label reformulation cycle timing informs the projection framework across the analysis window. Segmentation dimensions include product type, application, end-user scale, and distribution channel complexity, with regional regulatory cluster effects modeled separately. CAGRs derive from elasticity-adjusted volume projections and price trajectory assumptions tied to certified organic premium persistence. Industry-specific inputs incorporate beta-glucan assay standardization timelines and air-classification milling replacement cycle acceleration.
Stress conditions across Black Sea supply disruption, California drought recurrence, and EFSA claim rejection rate spikes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory deadline adherence and milling technology adoption curves. Cross-checking against customs trade data and specialty miller capacity expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Roll-Dried Starch Market
Ingredients
Astragalus Root Extract Market
Ingredients
Clean Label Flour Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Ice Cream Bases Market
Ingredients
Organic Pastry Flour Market
Ingredients
Black Seed Oil Market
Ingredients
Dairy Ingredients Market
Ingredients
Vegetable Concentrates Market
Ingredients
Campesterol Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Chickpea Protein Market
Ingredients
Dry Blended Products Market
Ingredients
Baking Ingredients Market
Ingredients
Dill Seed Oil Market
Ingredients
Asia-Pacific Lipids Market