
 Brewer's Yeast Market | 2026-2036
Brewer's Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Brewer's Yeast Market Intelligence
The direct-to-consumer channel for nutritional yeast and specialty strains is rewriting traditional B2B distribution models. This shift challenges established players to adapt their logistics and marketing. Lesaffre Group leverages its global production network to serve diverse industrial and consumer segments. Lallemand Inc. specializes in specific yeast and bacteria applications for brewing and health, while Cargill Incorporated incorporates yeast products into its vast agricultural supply chain solutions.
Brewer's yeast is a single-celled fungus, primarily Saccharomyces cerevisiae, used in fermentation processes. It is a rich source of B-complex vitamins, proteins, and minerals, making it valuable beyond its primary role in producing alcoholic beverages. While the alcoholic beverages application remains a core segment, demand from the dietary supplements and animal feed sectors is accelerating. Within product types, active dry yeast dominates industrial applications, whereas nutritional yeast formats are gaining significant traction in consumer health markets.
The market operates within strict food and feed safety regulations. In the United States, the FDA's guidelines on GRAS (Generally Recognized as Safe) status apply, while in Europe, EFSA's opinions on novel foods and health claims are critical. Compliance with international quality standards like ISO 22000 is also a key differentiator. Stakeholders must decide whether to invest in strain development for specialized health applications or focus on optimizing supply chains for bulk commodity yeast.
Market Dynamics
The central dynamic shaping the brewer's yeast market is its bifurcation from a low-value brewing by-product into a high-value, intentionally produced ingredient for health and nutrition, creating separate supply chains and value propositions for commodity and specialty segments.
Growth Catalysts
- Favorable Regulatory Status:The Generally Recognized as Safe (GRAS) designation by the US FDA and positive health claim opinions from Europe's EFSA provide a strong foundation for incorporating brewer's yeast into functional foods and dietary supplements, boosting consumer confidence.
- Animal Feed Formulation:Demand from the animal nutrition sector is a significant catalyst, as producers seek non-antibiotic growth promoters and protein-rich additives to improve livestock health and feed conversion ratios, particularly in poultry and aquaculture.
- Established Health Food Markets:Strong consumer demand for natural and nutrient-dense products in countries like Germany creates a pull for nutritional yeast formats, supporting premium product development and market expansion beyond its traditional brewing by-product origins.
Market Restraints
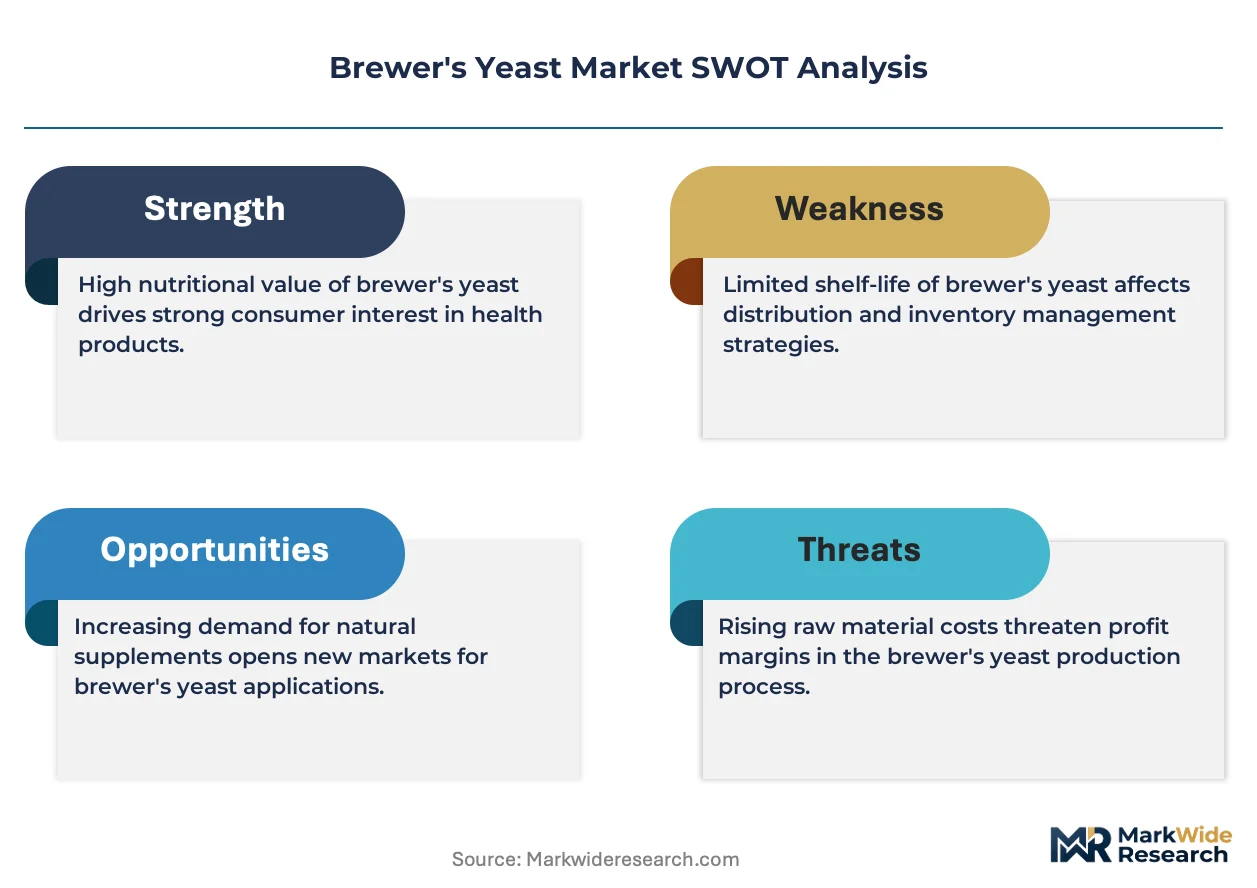
- Supply Dependency on Beer Production:The supply of traditional brewer's yeast is intrinsically linked to beer manufacturing volumes, creating potential price volatility and availability issues when demand from supplement or feed markets diverges from brewing industry trends.
- Competition from Alternative Proteins:In the supplement and feed markets, brewer's yeast faces competition from other protein sources like soy, pea, whey, and emerging microbial proteins, which may offer different nutritional profiles or lower costs.
- Processing Costs and Organoleptic Challenges:The inherent bitterness of raw brewer's yeast requires a debittering process to make it palatable for human consumption, adding significant cost and complexity compared to primary-grown nutritional yeast or other protein ingredients.
Strategic Opportunities
- Strain-Specific Health Applications:Developing and patenting specific strains of Saccharomyces cerevisiae for targeted health benefits, such as immune modulation or gut microbiome support, opens new high-margin opportunities in the medical foods and specialized nutraceuticals space.
- Direct-to-Consumer (DTC) Channels:Establishing DTC e-commerce platforms for specialty nutritional yeast allows producers to build brand equity, capture higher margins, and gather direct consumer feedback, bypassing traditional retail and B2B distribution intermediaries.
- Expansion in Asia-Pacific Markets:Untapped demand in developing Asian economies, where a growing middle class is increasingly focused on health and wellness, presents a significant opportunity for market entry with dietary supplements and functional food ingredients.
Industry Challenges
- Navigating Global Food Safety Standards:Manufacturers face the operational challenge of aligning production with a complex web of international regulations, such as meeting both FDA requirements in the US and EFSA's novel food guidelines in Europe, which can delay product launches.
- Logistical Complexity:Managing a fragmented supply chain that involves collecting, purifying, and stabilizing a perishable by-product from numerous breweries into a consistent, food-grade raw material poses significant logistical and quality control hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewer's Yeast Market |
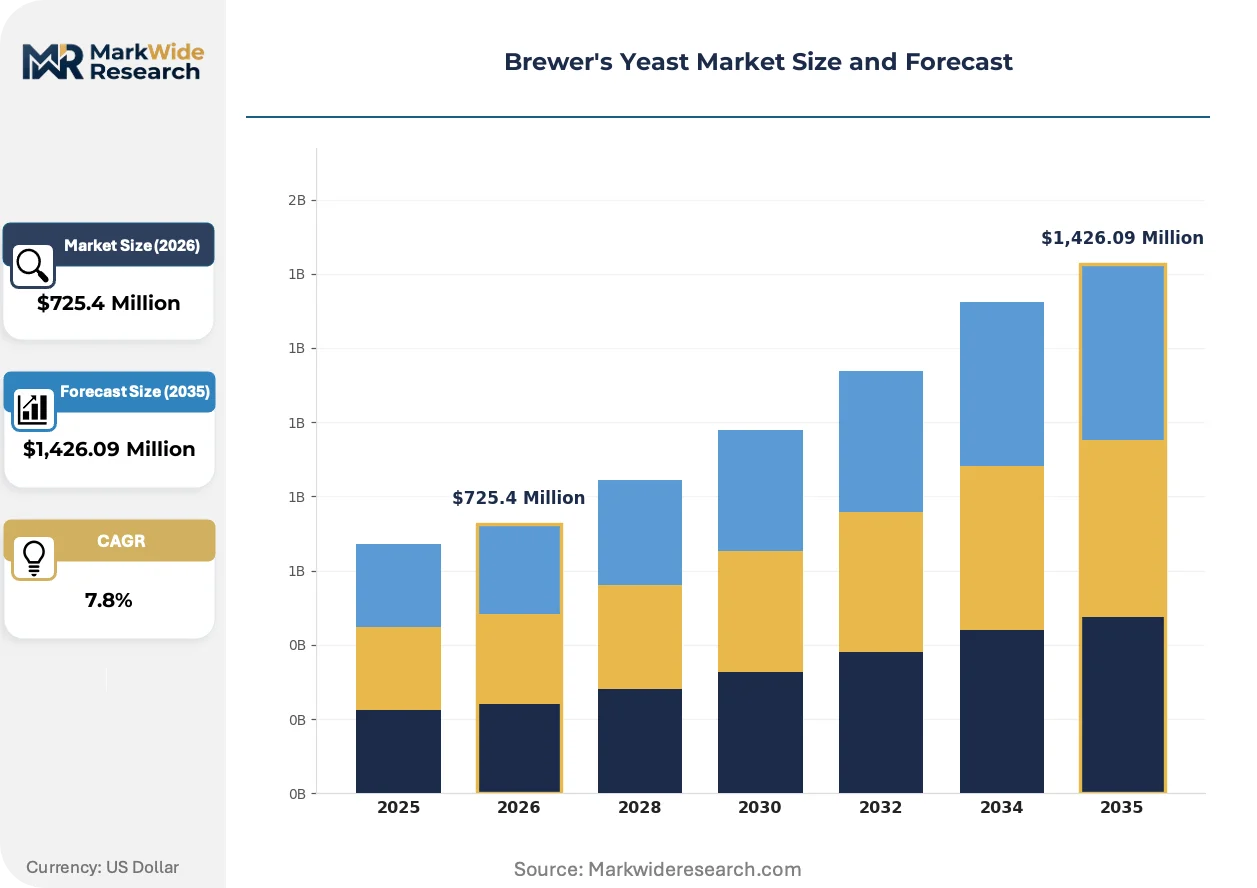
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,426.09 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Instant Yeast, Cream Yeast, Nutritional Yeast, Deactivated Yeast Application: Baking, Alcoholic Beverages, Animal Feed, Pharmaceuticals, Dietary Supplements End User: Bakeries, Breweries, Feed Manufacturers, Pharmaceutical Companies, Supplement Producers Packaging Type: Vacuum Packets, Airtight Containers, Bulk Bags, Sachets, Aerosol Cans |
| Companies Covered | Kerry Group Plc, Lesaffre Group, Cargill Incorporated, Chr Hansen Holding AS, AngelYeast Co Ltd, Archer-Daniels-Midland Company, Lallemand Inc., Leiber GmbH, Associated British Foods Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewer's Yeast Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from leveraging an incidental brewing by-product to the intentional cultivation of yeast as a high-performance bio-ingredient. This transformation is creating new value propositions centered on functionality, purity, and specific health outcomes.
Precision fermentation allows for the cultivation of yeast strains with specific, enhanced nutritional profiles, such as higher B-vitamin or selenium content. The functional food and nutraceutical sectors are rapidly adopting this technology to guarantee ingredient consistency and efficacy. Consequently, the market's core value proposition is migrating from the opportunistic sale of a variable brewing surplus to the reliable delivery of standardized, high-purity biological assets.
The European Food Safety Authority (EFSA) is enforcing stricter substantiation requirements for health claims on food supplements. This regulatory pressure compels producers of yeast-based products to invest in clinical research to validate benefits related to immunity or digestive health. The dietary supplement segment is most affected, as it must now build scientific dossiers to support marketing claims, moving beyond reliance on historical or compositional data.
A notable behavioral change is the consumer-led demand for supply chain transparency in food ingredients. This is disrupting traditional B2B procurement, where ingredient origin was often obscured, in favor of traceable, certified sources. The trend is most visible in the North American and European vegan food markets, where consumers actively seek products with clear non-GMO, gluten-free, and ethically sourced credentials, forcing suppliers to adapt their documentation and marketing.
Brewer's Yeast Market Segmentation
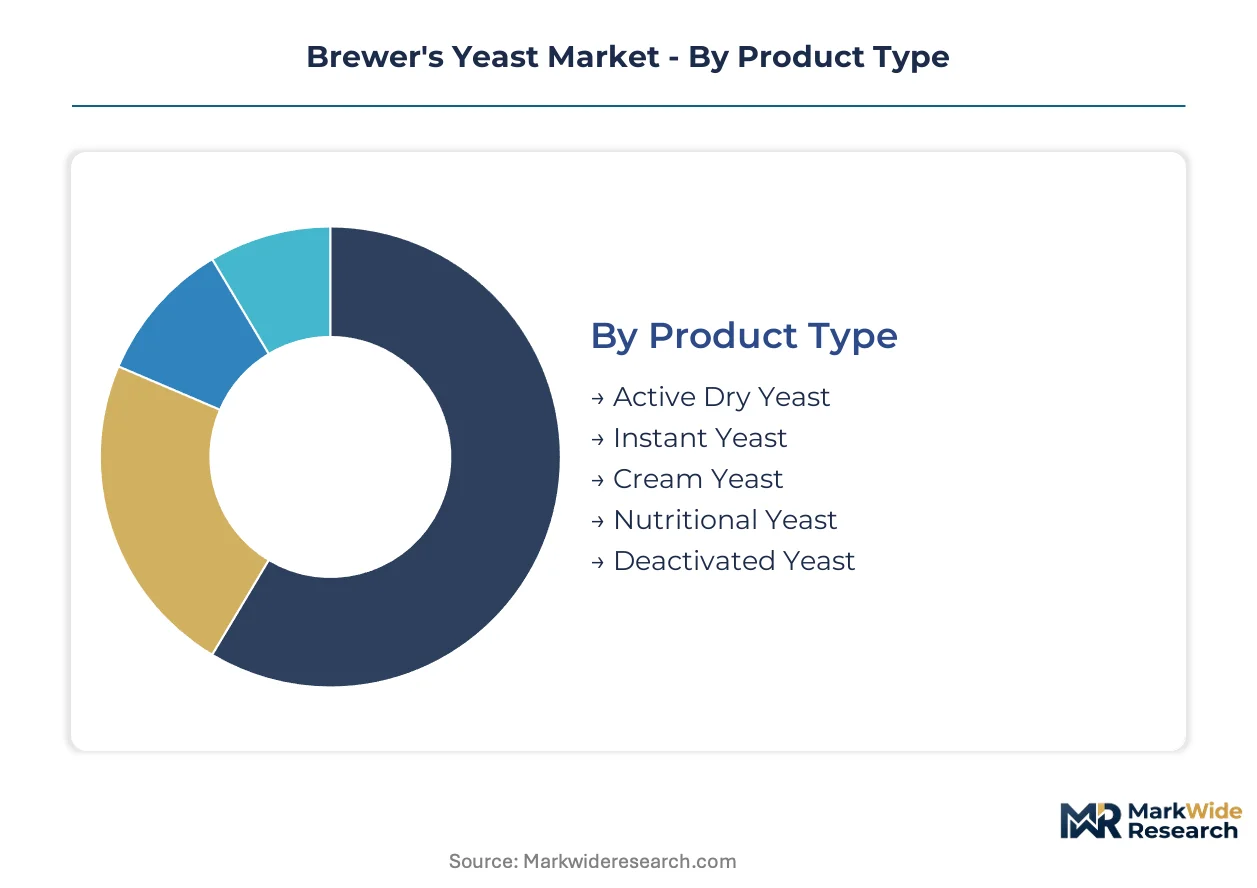
Segmentation within the brewer's yeast market is critical for understanding the diverse value streams emerging from both its traditional by-product origins and its intentional cultivation as a high-value ingredient. This differentiation allows stakeholders to pinpoint specific growth opportunities and tailor product development for distinct end-user needs.
Product Type:
The after-sales service intensity for brewer's yeast products varies significantly, reflecting the technical support and handling expertise required for different formulations.
- Active Dry Yeast:This granular form features low moisture content, offering extended shelf-life and stability for industrial applications. Demand concentrates in large-scale brewing and baking, driven by its ease of use and consistent fermentation performance across diverse environments.
- Nutritional Yeast:Deactivated and often flaky, this product is prized for its savory, umami flavor and rich B-vitamin profile, making it popular in vegan diets. Demand is particularly strong in North American and European health food markets, where consumers seek nutrient-dense and plant-based food additives.
- Instant Yeast:Characterized by its rapid activation, this form is widely adopted in commercial and home baking for efficient dough leavening.
- Cream Yeast:Available in a liquid or paste form, cream yeast is primarily utilized by large industrial bakeries requiring high fermentation activity and easy dispensing.
- Deactivated Yeast:This non-fermenting yeast type serves as a protein source, flavor enhancer, and functional ingredient in animal feed and processed foods.
Active Dry Yeast holds the largest share; momentum sits with Nutritional Yeast.
Application:
Cost-tiering within brewer's yeast applications reflects the value placed on specific functionalities and the volume requirements of each industry.
- Alcoholic Beverages:Brewer's yeast is fundamental for fermenting sugars into ethanol and carbon dioxide, defining the character of beers, wines, and spirits. This application maintains a foundational demand within the global brewing industry, where specific yeast strains are crucial for achieving desired flavor profiles and consistent product quality.
- Dietary Supplements:Leveraging its rich content of B-complex vitamins, proteins, and minerals, brewer's yeast is formulated into capsules, tablets, and powders for human consumption. Demand is accelerating from health-conscious consumers in Europe and North America, supported by favorable regulatory statuses like GRAS and positive health claim opinions.
- Animal Feed:As a protein-rich additive, brewer's yeast improves feed conversion ratios and supports gut health in livestock, particularly in poultry and aquaculture.
- Baking:Brewer's yeast acts as a primary leavening agent in bread and other baked goods, contributing to dough rise and texture development.
- Pharmaceuticals:Specific yeast strains find use in pharmaceutical formulations as excipients, probiotic agents, or for producing recombinant proteins.
The Alcoholic Beverages application maintains a foundational demand, while the Dietary Supplements segment is expanding most quickly.
End User:
Supply concentration for brewer's yeast varies across end-user segments, with large industrial players dominating procurement for commodity applications.
- Breweries:These entities are both primary users of brewer's yeast for fermentation and a significant source of its by-product for other industries. Demand from breweries remains intrinsically linked to global beer production volumes, requiring consistent quality and specific strain performance.
- Supplement Producers:These companies incorporate brewer's yeast into various health products, ranging from vitamin supplements to immune support formulations. Their demand is driven by the growing health and wellness market, seeking ingredients with established nutrient profiles and GRAS status.
- Feed Manufacturers:These companies integrate brewer's yeast into animal nutrition products, including livestock feed, pet food, and aquaculture diets for protein enrichment.
- Bakeries:Ranging from artisanal shops to industrial facilities, bakeries rely on yeast for leavening, demanding consistent activity and reliable performance.
- Pharmaceutical Companies:These firms utilize specialized yeast strains for biotechnological processes, drug formulation, or as a source of specific bioactive compounds.
Breweries represent a stable demand base, with Supplement Producers exhibiting significant market traction.
Packaging Type:
Margin structures for brewer's yeast are influenced by packaging type, reflecting varying costs associated with material, handling, and shelf-life requirements.
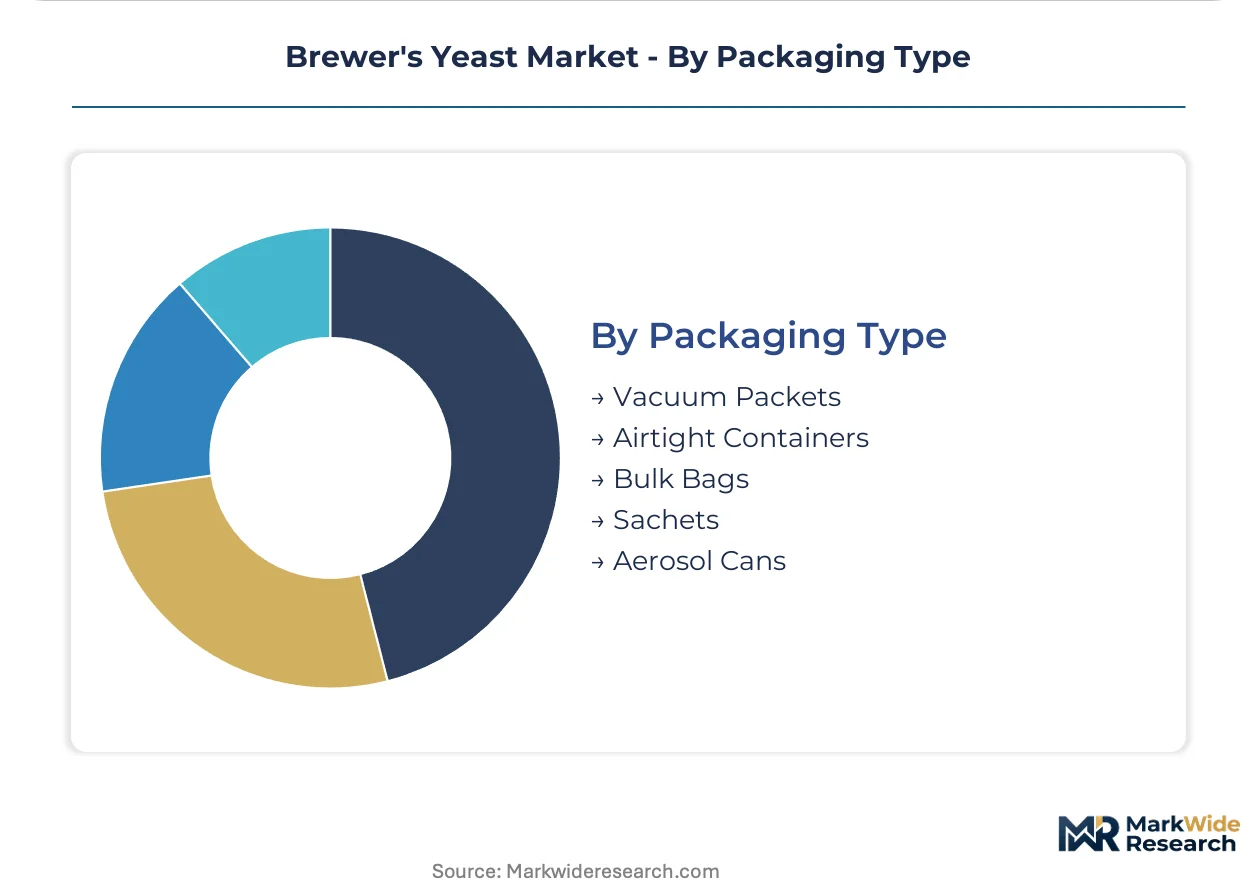
- Bulk Bags:These large-capacity containers are designed for industrial-scale users, providing a cost-effective solution for high-volume procurement. Demand is concentrated in the animal feed and large-scale brewing sectors, prioritizing logistics efficiency and a reduced unit cost per kilogram.
- Vacuum Packets:Offering enhanced moisture barriers and extended shelf-life in smaller portions, vacuum packets cater to retail consumers and smaller-scale commercial users. This packaging type is favored in home baking and specialty food markets, where freshness preservation and convenience are key purchasing factors.
- Airtight Containers:Providing robust protection against environmental factors, these containers are used for specialty yeast products and those requiring longer storage or reusability.
- Sachets:Small, single-use sachets are common in retail baking and dietary supplement markets, emphasizing convenience and precise portion control for consumers.
- Aerosol Cans:A niche packaging format, aerosol cans facilitate controlled dispensing for specific applications, though their market share remains limited.
Bulk Bags facilitate large-scale industrial distribution, while Vacuum Packets cater to expanding retail and specialty markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Favorable regulatory frameworks, including the Generally Recognized as Safe (GRAS) status by the US FDA, significantly influence the global brewer's yeast market. These policies encourage its integration into functional foods and dietary supplements. Such regulatory support underpins expansion across diverse geographic regions.
United States
Demand for brewer's yeast in the United States is driven by its use in dietary supplements and the expanding plant-based food market. The US FDA's GRAS designation provides a strong foundation for its inclusion in various consumer products. California's nutraceutical industry, particularly around Los Angeles, actively integrates yeast-based ingredients into health formulations.
Germany
Germany's market for brewer's yeast benefits from its established health food sector and a robust brewing industry. Positive health claim opinions from Europe's EFSA support consumer confidence in yeast-derived products. Bavaria, with its strong brewing tradition and advanced food processing sector, represents a significant hub for both supply and demand.
China
The Chinese market exhibits strong demand from the animal feed sector and a growing interest in health supplements. China's NMPA regulations for food ingredients are shaping product development and market entry strategies. Shanghai's expanding biotechnology and food processing hubs are driving innovation in yeast applications.
India
India's brewer's yeast market is expanding due to increasing demand in animal nutrition and the affordable supplements segment. The FSSAI provides guidelines for food additives, ensuring quality standards for yeast products. Maharashtra, with its large livestock and food manufacturing base, is a key region for yeast consumption.
Brazil
Brazil sees increasing demand for brewer's yeast in animal feed, particularly for poultry and aquaculture, and in functional food applications. ANVISA regulations for food supplements influence product formulation and market access. São Paulo's prominent agricultural and food processing industries contribute significantly to the country's market volume.
Brewer's Yeast Market Key Industry Players
On the supply side, the industry is tiered, with large, diversified agricultural and biotech corporations coexisting with specialized yeast producers. This structure features a mix of global players and regional specialists. Key archetypes include commodity yeast suppliers, specialized strain developers, and ingredient solution providers. Dominant competitive moves involve strategic partnerships for new applications and portfolio diversification into high-value nutraceuticals.
At the scale-driven end, Cargill Incorporated, a US-based agricultural giant, exemplifies a major player integrating yeast products into its vast supply chain solutions. This company leverages its expansive network to serve various industrial and consumer sectors with yeast-derived ingredients. Lesaffre Group, a French-headquartered company, represents a global leader with extensive production networks serving diverse industrial and consumer segments, particularly in baking and brewing. Lallemand Inc., a Canadian-based specialist, occupies a position focused on specific yeast and bacteria applications for brewing and health, offering tailored solutions for specialized markets.
| Leading Market Players |
|---|
| Kerry Group Plc |
| Lesaffre Group |
| Cargill Incorporated |
| Chr Hansen Holding AS |
| AngelYeast Co Ltd |
| Archer-Daniels-Midland Company |
| Lallemand Inc. |
| Leiber GmbH |
| Associated British Foods Plc |
| Others |
Cost & Logistics Intelligence
Transatlantic shipping lanes' cost dynamics directly influence brewer's yeast pricing, linking supply concentrations in Europe to consumer markets in North America and affecting downstream price differentiation for specialty ingredients.
Pricing Analysis
Certification level, including GRAS designation by the US FDA and EFSA opinions, creates the primary price spread for brewer's yeast products. Pricing operates on a hybrid model, combining long-term contracts for bulk commodity yeast with tiered transactional pricing for specialty strains. Volume scale and specific strain functionality further differentiate prices. Pricing softness affects commodity yeast due to competition from alternative proteins, making animal feed manufacturers highly price-sensitive. Pharmaceutical companies prioritize efficacy and certification.
Supply Chain Analysis
Export control regimes for bio-ingredients, though less stringent for brewer's yeast, could impact specialized strain flows between major producers. Supply concentration for brewer's yeast is notable in Germany, the United States, and China, drawing heavily from beer production by-products and dedicated fermentation inputs. A structural risk involves the inherent volatility of beer manufacturing volumes, impacting by-product availability. Distribution runs through established B2B channels for industrial users and direct-to-consumer platforms for nutritional yeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brewer's yeast market is experiencing a cyclical recovery, driven by renewed consumer focus on natural health ingredients post-pandemic. This shift creates distinct opportunities across its bifurcated commodity and specialty segments.
For Market Incumbents:Insulate core commodity business margins against competition from alternative proteins through efficient large-scale processing and long-term supply agreements with breweries. Invest in precision fermentation R&D for specialized strains to counter margin pressure from generic suppliers. Deepen vertical integration into processing and packaging to control quality. Prioritize compliance investments for international food safety standards like ISO 22000.
For New Entrants and Emerging Players:Build out niche positions in strain-specific health applications, targeting immune modulation or gut microbiome support. The dietary supplements segment in developing Asian economies represents the most penetrable market for specialized yeast products. Leverage direct-to-consumer e-commerce channels to establish brand equity and gather direct consumer feedback. Focus on robust clinical validation to support health claims, especially under EFSA's stricter requirements.
For Investors and Strategic Acquirers:Biotech firms with proprietary yeast strain libraries and specialized processing capabilities represent attractive acquisition targets for long-term value creation. The market's viability remains strong over a 5-10 year window, particularly in high-value nutraceutical applications. Seek companies demonstrating robust R&D pipelines for targeted health benefits. Increased patenting activity in specialized yeast strains will signal accelerating market maturation and future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | This initiative guarantees ingredient consistency and efficacy for high-value nutraceutical applications. |
| Strain-Specific Patenting | Patenting specific Saccharomyces cerevisiae strains secures intellectual property for targeted health benefits. |
| Direct-to-Consumer E-commerce Platform | This platform builds brand equity and captures higher margins for specialty nutritional yeast products. |
| ISO 22000 Certification Upgrade | Upgrading certification ensures compliance with international quality standards for global market entry. |
| By-product Collection Optimization | Optimizing collection processes reduces logistical complexity for perishable brewing by-products. |
Research Approach
Operator-level perspectives from brewery operations managers, supplement product development leads, and food safety compliance officers anchored the qualitative base. Primary interviews were triangulated with secondary validation from US FDA guidelines, EFSA opinions, and industry association reports. This approach combined bottom-up market insights with top-down industry trends. Data synthesis ensured a comprehensive understanding of market dynamics.
Scenario-bracketing around regulatory shifts and raw material supply volatility informed the quantitative analytical framework across the analysis window. Segmentation dimensions modeled included product type, application, end user, packaging type, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected demand. Key forecast inputs included global beer production volumes and dietary supplement consumption trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large biotech corporations or specialized strain developers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and consistent raw material supply. Material shifts in global beer production or unforeseen regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Egg White Peptide Market
Ingredients
Microencapsulated Oil Market
Ingredients
Europe Amino Acid Market
Ingredients
Broccoli Powder Market
Ingredients
Soy Flour Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Potato Starch Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
MCT Oil Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Camelina Oil Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Pea Peptones Market
Ingredients
Coconut Oil Market
Ingredients
Europe Sodium Reduction Ingredient Market