
 Vector Network Analyzer Market | 2026-2036
Vector Network Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Vector Network Analyzer Market Outlook
China's RF test equipment manufacturing corridor is narrowing the cost gap with Western instrumentation. Keysight Technologies dominates millimeter-wave calibration systems through in-house production of precision connectors and receivers. Rohde & Schwarz anchors European defense and automotive compliance testing with laboratories in Germany and France. Anritsu Corporation specializes in handheld and portable vector network analyzers for field maintenance of 5G infrastructure across Asia-Pacific markets.
A vector network analyzer measures the magnitude and phase of radio frequency signals reflected from and transmitted through a device under test, typically operating from kilohertz to terahertz frequencies with dynamic range exceeding 100 dB. Engineers use this instrument to characterize antennas, filters, amplifiers, and interconnects in telecommunications and aerospace systems. Benchtop configurations still capture the largest margin pool in metrology-grade applications, while modular architectures are displacing traditional form factors in automated production lines. The aerospace end-user segment sustains premium pricing through MIL-STD compliance requirements and extended calibration cycles.
The FCC mandates electromagnetic compatibility certification under Part 15 and Part 18 rules, compelling manufacturers to validate RF components before market entry. ETSI harmonizes test procedures across EU member states through EN 301 standards, while China's MIIT enforces GB/T specifications for domestic 5G base station deployments. Stakeholders must monitor spectrum auction timelines and evolving O-RAN conformance requirements to anticipate shifts in instrument specification demand.
Market Dynamics
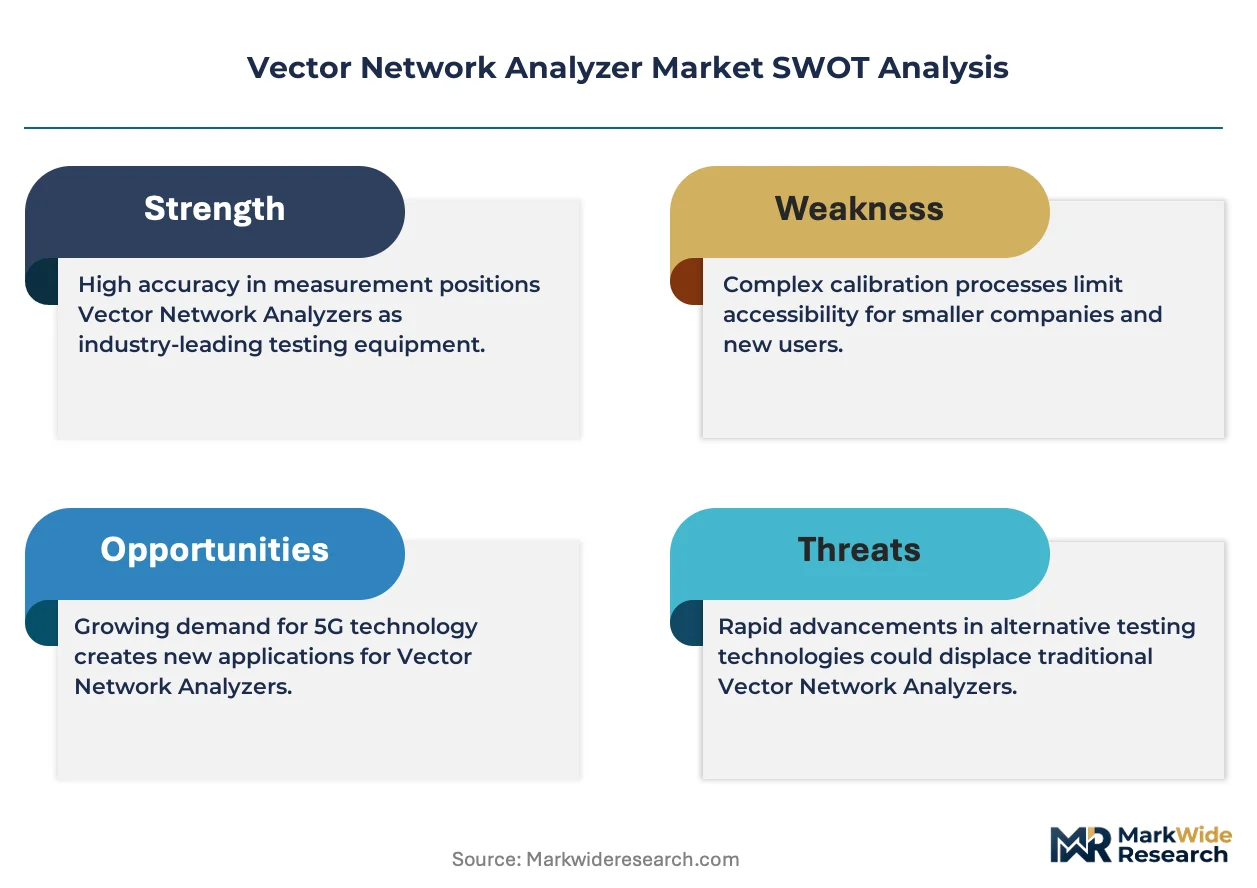
Millimeter-wave testing requirements for 5G and 6G infrastructure deployment are compressing instrument refresh cycles and forcing laboratory capital reallocation toward higher-frequency measurement platforms.
Growth Catalysts
- FCC Spectrum Reallocation:The FCC's 5G and 6G spectrum reallocation mandates in the United States compel laboratories to upgrade to higher-frequency measurement capabilities, accelerating instrument replacement demand.
- Defense Electronics Procurement:Expanding defense electronics procurement programs in the United States drive deployment of precision RF test equipment for radar and communications systems validation.
- Domestic Manufacturing Scale-Up:China's MIIT-enforced GB/T specifications for 5G base station deployments concentrate demand within domestic RF test equipment manufacturing corridors.
Market Restraints
- Precision Connector Supply Concentration:Millimeter-wave calibration systems depend on specialized precision connector suppliers concentrated in Germany and the United States, creating input bottleneck risks.
- Metrology-Grade Cost Structure:Benchtop configurations require extended calibration cycles and MIL-STD compliance certification, elevating total cost of ownership for aerospace end-users.
- Modular Architecture Substitution:Automated production lines increasingly favor modular VNA architectures over traditional benchtop form factors, compressing margins in legacy segments.
Strategic Opportunities
- O-RAN Conformance Testing:Evolving O-RAN conformance requirements create white space for instrument manufacturers to develop multi-port test solutions for open radio access network validation.
- Field Maintenance Channel Expansion:Asia-Pacific 5G infrastructure rollouts expand demand for handheld and portable analyzers distributed through direct field service channels rather than traditional laboratory sales.
- EU Green Deal Alignment:The EU Green Deal's energy efficiency mandates for telecommunications equipment create regulatory tailwind for RF component characterization services in France and Germany.
Industry Challenges
- Millimeter-Wave Calibration Expertise Gap:The specialized skill set required for terahertz-frequency calibration and uncertainty analysis remains scarce across metrology laboratories and manufacturing facilities.
- Multi-Standard Certification Complexity:Manufacturers must simultaneously satisfy FCC Part 15, ETSI EN 301, and China's MIIT GB/T specifications, extending product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vector Network Analyzer Market |
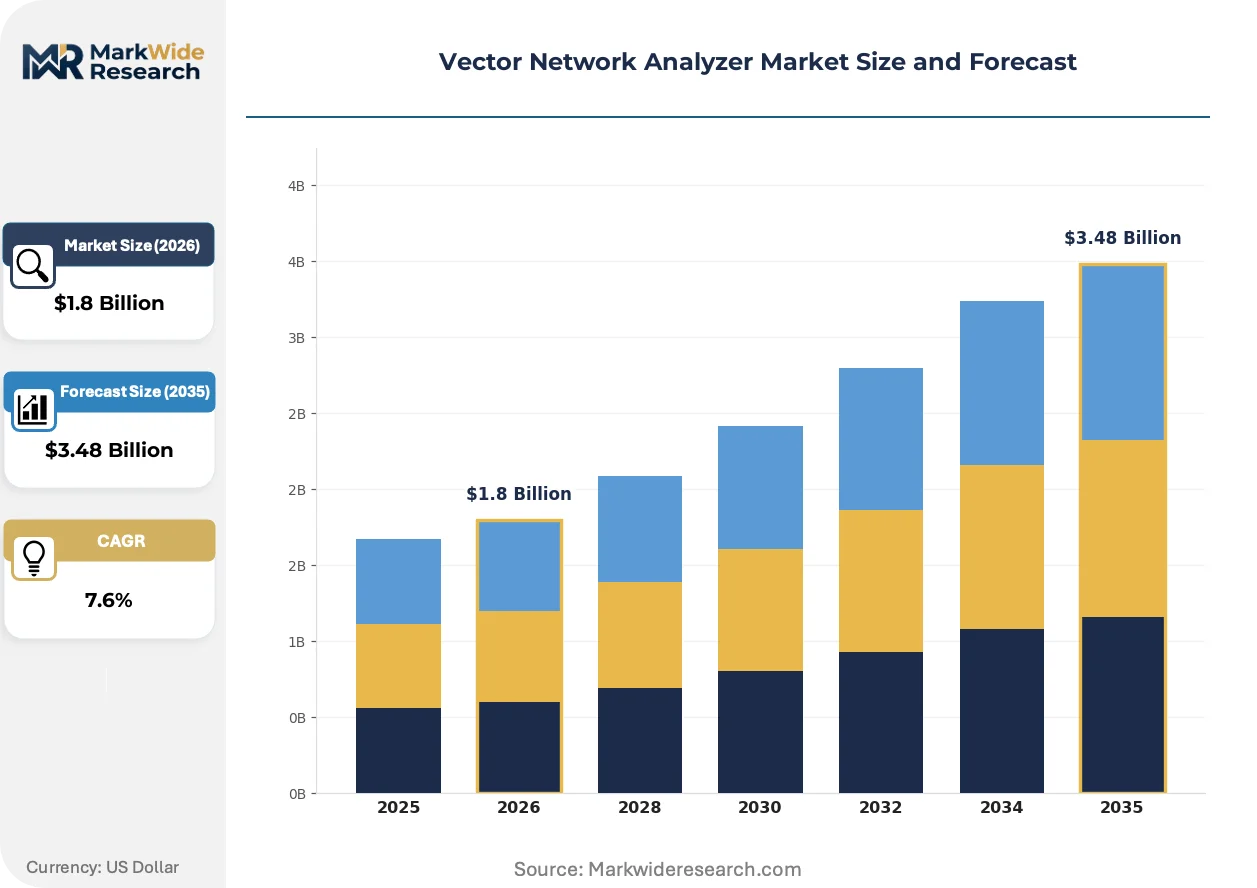
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Portable, Handheld, Modular End User: Telecommunications, Aerospace, Automotive, Education Technology: Scalar Network Analyzer, Vector Network Analyzer, Wi-Fi Testing, RF Testing Application: Measurement, Component Testing, Research, Production |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu Corporation, Tektronix, National Instruments, Copper Mountain Technologies, OMICRON Lab, Transcom Instruments, Chengdu Tianda Instrument Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vector Network Analyzer Market Strategic Shifts
Measurement architectures are fragmenting across application-specific configurations as frequency demands diverge between laboratory metrology and production-line automation. This fragmentation is compressing the addressable market for general-purpose platforms.
Cloud-native measurement software is migrating from traditional instrument-embedded operating systems to browser-based architectures accessible through standard computing hardware. Telecommunications manufacturers in South Korea and Japan are adopting these platforms for distributed R&D teams. This shift is enabling centralized test data management while reducing per-site instrument capital requirements.
ETSI's harmonization of electromagnetic compatibility test procedures through EN 301 standards is consolidating validation protocols across EU member states. Industrial consequence includes reduced redundant testing for RF component manufacturers serving multiple European markets. Automotive radar suppliers in Germany and France are restructuring compliance departments to align with these unified procedures.
Telecommunications operators are unbundling after-sales calibration services from initial instrument purchases, treating metrology as a recurring operational expense rather than capital equipment acquisition. This behavior shift disrupts traditional distributor models that bundled multi-year service contracts. The pattern is most visible in China's base station deployment programs, where domestic manufacturers now procure calibration services through separate MIIT-accredited laboratories.
Vector Network Analyzer Market Segmentation
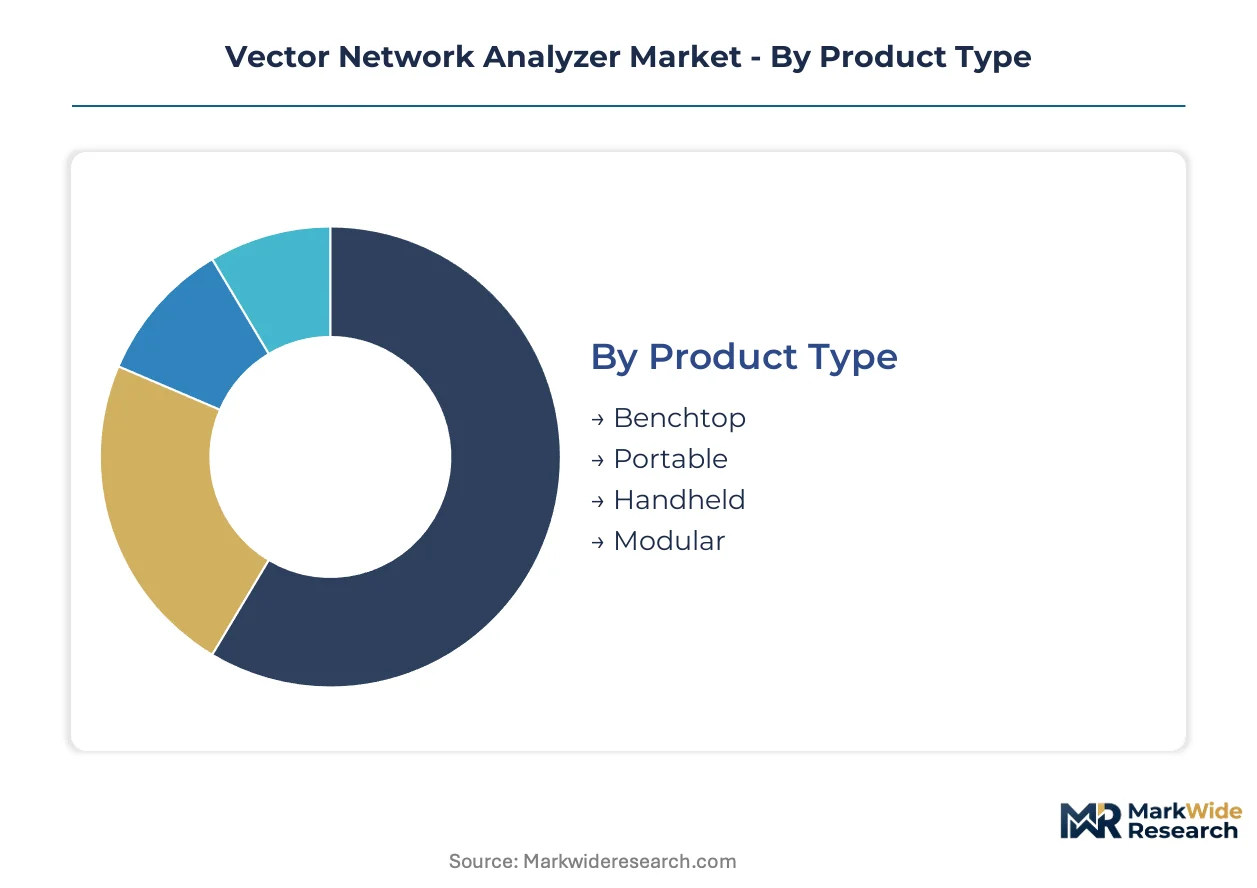
Vector network analyzer procurement patterns diverge sharply across deployment contexts, with capital-intensive laboratory configurations exhibiting multi-year refresh cycles while field-service instruments turn over rapidly alongside 5G infrastructure buildouts. Understanding these segment dynamics reveals where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Refresh cycles stretch from months in automated production to years in metrology laboratories, creating distinct investment rhythms across form factors.
- Benchtop:Stationary configurations with maximum dynamic range and port density serve aerospace qualification labs and semiconductor wafer probe stations. MIL-STD compliance requirements in United States defense programs sustain extended calibration intervals and premium pricing tiers.
- Portable:Reduced-form-factor units with battery operation and ruggedized enclosures target base station commissioning teams across China's MIIT-mandated 5G deployment corridors. Field maintenance contracts in Asia-Pacific telecommunications networks are displacing laboratory-bound procurement.
- Handheld:Single-port analyzers prioritize antenna matching and cable verification for installation crews.
- Modular:PXIe and AXIe-based architectures integrate into automated test systems for high-volume filter and amplifier production.
Benchtop dominates installed base. Modular is where expansion concentrates.
End User:
Customer sophistication and compliance burden separate price-insensitive aerospace buyers from cost-optimized education purchasers.
- Telecommunications:Equipment manufacturers and operators validate base station antennas, filters, and beamforming modules against FCC Part 15 and ETSI EN 301 emissions standards. China's three-tier carrier structure concentrates procurement volume among state-owned network builders.
- Aerospace:Radar cross-section measurements and satellite payload characterization demand phase uncertainty below 0.1 degrees. United States Department of Defense programs specify extended temperature ranges and shock resistance for deployed systems.
- Automotive:77 GHz and 79 GHz radar module suppliers in Germany and France require compact range and near-field scanning capabilities.
- Education:University laboratories prioritize cost over specification, accepting reduced dynamic range for undergraduate instruction.
Aerospace commands the highest unit economics. Telecommunications delivers the steepest expansion trajectory.
Technology:
Measurement architecture selection determines frequency ceiling, calibration complexity, and software ecosystem lock-in.
- Vector Network Analyzer:Full S-parameter acquisition with magnitude and phase information supports complete linear characterization of multi-port devices. Millimeter-wave extensions to 110 GHz and beyond are compressing price-performance ratios in 5G beamformer testing.
- Scalar Network Analyzer:Amplitude-only measurement suits simple insertion loss and return loss verification where phase data adds no diagnostic value.
- Wi-Fi Testing:Pre-configured test suites for IEEE 802.11ax/be compliance accelerate router and access point validation.
- RF Testing:General-purpose spectrum and power measurement functions overlap with dedicated VNA applications in lower-complexity environments.
Vector Network Analyzer anchors professional procurement. Wi-Fi Testing is climbing the fastest among consumer-facing segments.
Application:
Workflow integration separates offline research instruments from inline production verification systems.
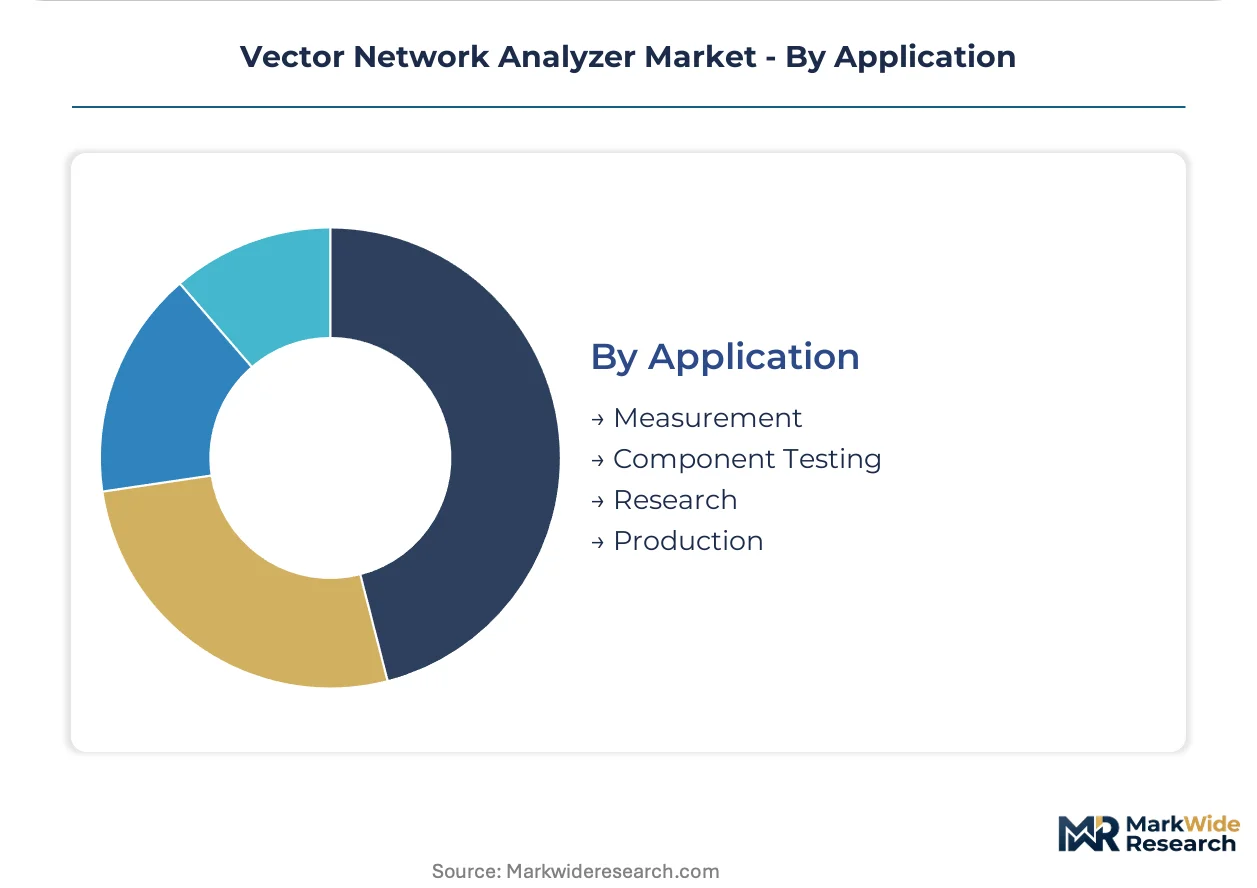
- Component Testing:Filter passband ripple, amplifier gain flatness, and antenna efficiency measurements dominate incoming quality control and final inspection stations. China's domestic base station component suppliers are scaling automated test cell deployment.
- Production:High-throughput configurations with handler interfaces and pass-fail binning reduce per-unit test time to seconds in surface-mount device manufacturing.
- Research:Novel materials and metamaterial characterization in university and government laboratories prioritizes measurement flexibility over speed.
- Measurement:General-purpose metrology services span calibration, troubleshooting, and compliance documentation.
Component Testing holds the largest active instrument population. Production is gaining share fastest as manufacturing automation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision connector suppliers in Germany and the United States control critical input flows for millimeter-wave calibration systems. This supply concentration shapes where instrument manufacturers locate final assembly and where laboratories source replacement components.
United States
Defense electronics procurement programs at the Department of Defense drive precision RF test equipment deployment for radar validation. FCC spectrum reallocation mandates for 5G and 6G compel commercial laboratories toward higher-frequency measurement platforms. Boston and Silicon Valley clusters concentrate aerospace qualification labs and semiconductor wafer probe stations.
Germany
Automotive radar module suppliers at 77 GHz and 79 GHz demand compact range and near-field scanning capabilities. ETSI harmonization of EN 301 electromagnetic compatibility standards consolidates validation protocols across EU member states. Stuttgart and Munich anchor automotive compliance testing laboratories serving German and French suppliers.
China
Domestic manufacturers scale cost-competitive RF test equipment production for base station deployment. MIIT enforces GB/T specifications for 5G infrastructure through state-owned carrier procurement. Shenzhen and Beijing manufacturing corridors narrow the cost gap with Western instrumentation.
Japan
Telecommunications equipment manufacturers adopt cloud-native measurement software for distributed R&D teams. METI industrial policy supports millimeter-wave research for next-generation wireless systems. Tokyo and Osaka metropolitan areas concentrate instrument development for Asia-Pacific field maintenance channels.
South Korea
Telecommunications operators unbundle after-sales calibration services from initial instrument purchases. MFDS-equivalent national standards bodies coordinate with ETSI and FCC on conformance testing alignment. Seoul Capital Area manufacturers integrate modular VNA architectures into automated production lines.
Vector Network Analyzer Market Competitive Environment
Full-spectrum instrument houses and modular architecture specialists split the market along application boundaries. The vendor base concentrates around three strategic archetypes: precision metrology incumbents with captive calibration ecosystems, modular platform developers optimized for production-line throughput, and cost-optimized challengers serving field maintenance channels. Dominant competitive moves include backward integration into precision connector manufacturing and geographic expansion through MIIT-accredited laboratory partnerships in China.
Within the precision metrology tier, Keysight Technologies and Rohde & Schwarz exemplify archetypes built around in-house component production and extended calibration service networks. Anritsu Corporation occupies a position emphasizing portable form factors for Asia-Pacific telecommunications infrastructure. These three entities represent contrasting strategic postures: one anchored in millimeter-wave calibration systems, one in European defense and automotive compliance, and one in handheld analyzers for field deployment.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu Corporation |
| Tektronix |
| National Instruments |
| Copper Mountain Technologies |
| OMICRON Lab |
| Transcom Instruments |
| Chengdu Tianda Instrument Equipment |
| Others |
Value Chain & Pricing Dynamics
Precision connector suppliers concentrated in Germany and the United States capture disproportionate margin pools upstream, forcing instrument manufacturers to defend pricing power through captive calibration service networks and extended warranty bundling downstream.
Pricing Analysis
FCC Part 15 and Part 18 certification mandates dictate the pricing tier structure across the United States market, separating MIL-STD-compliant aerospace configurations from cost-optimized education and field-service units. Three-tier pricing structure across premium metrology-grade, standard production-line, and economy handheld levels reflects calibration cycle length and port density differentiation. Pricing pressure stems from China's domestic manufacturers scaling cost-competitive alternatives for base station deployment. Education buyers exhibit highest price sensitivity, accepting reduced dynamic range, while aerospace procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing capacity for precision RF assemblies concentrates with specialized EMS providers in Germany, the United States, and Japan holding millimeter-wave test fixture expertise. Final instrument assembly draws from connector suppliers in Germany and the United States, receiver module fabricators in Japan, and software development centers in South Korea and India. Single-source vulnerability around sub-terahertz precision connectors creates input bottleneck risk for calibration system production. Distribution runs through direct field service channels for portable analyzers in Asia-Pacific and traditional laboratory equipment distributors for benchtop configurations in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration service unbundling from initial hardware purchases represents the fastest-expanding recurring-revenue layer, with telecommunications operators in China and South Korea now treating metrology as operational expenditure rather than capital acquisition.
For Market Incumbents: Build captive calibration ecosystem moats through MIIT-accredited laboratory partnerships in China and extended service contract penetration in United States defense programs. Defend against modular architecture substitution by integrating PXIe-compatible measurement modules alongside traditional benchtop platforms. Invest in precision connector backward integration to reduce German and United States supplier dependency. For New Entrants and Emerging Players: Build out handheld analyzer distribution through direct field service channels targeting Asia-Pacific 5G infrastructure maintenance contracts. Penetrate the education segment with cost-optimized single-port configurations accepting reduced dynamic range specifications. Pursue go-to-market partnerships with domestic Chinese base station component suppliers scaling automated test cell deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed precision metrology specialists holding extended calibration revenue streams and aerospace certification relationships. Long-term viability favors vendors with software-defined measurement architectures migrating from embedded operating systems to browser-based platforms. Monitor O-RAN conformance requirement evolution as inflection indicator for multi-port test solution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Connectors | Reduces German and United States supplier bottleneck risk for millimeter-wave calibration systems. |
| Cloud-Native Measurement Platform Launch | Enables centralized test data management for distributed South Korean and Japanese R&D teams. |
| MIIT-Accredited Laboratory Partnership | Secures recurring calibration service contracts within China's state-owned carrier procurement structure. |
| Modular PXIe Architecture Expansion | Captures automated production line share displacing traditional benchtop form factors. |
| Handheld Analyzer Channel Buildout | Targets Asia-Pacific field maintenance demand unbundled from laboratory distributor relationships. |
Study Parameters
A standing panel of RF test equipment procurement managers, aerospace qualification laboratory directors, telecommunications network deployment engineers, and precision connector manufacturing executives provided ongoing calibration against secondary data sources. Primary fieldwork combined structured interviews with instrument vendor product managers and aftermarket service heads alongside validation against FCC equipment authorization databases, ETSI harmonized standards publications, MIIT GB/T specification releases, and SEC filings from listed test and measurement companies. Bottom-up segment sizing triangulated against top-down market value reconstruction across product type, end user, and technology dimensions.
Scenario-bracketing around spectrum auction timelines and O-RAN deployment pace anchored the analytical framework across the projection horizon. Segmentation modeling incorporated form factor refresh cycle divergence, end-user compliance burden differentiation, and measurement architecture frequency ceiling constraints. CAGRs derived from instrument replacement demand elasticity to 5G and 6G infrastructure deployment waves and defense electronics procurement program visibility. Industry-specific inputs included millimeter-wave testing requirement evolution and cloud-native software adoption patterns among Asia-Pacific telecommunications manufacturers.
Sensitivities concentrate around FCC spectrum reallocation timing, Chinese domestic manufacturer cost competitiveness acceleration, and precision connector supply disruption events. Forecasts reflect documented assumptions regarding infrastructure deployment schedules and regulatory harmonization progress. Quarterly review of spectrum auction outcomes, O-RAN conformance specification releases, and MIIT accreditation expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Visualization Instruments for MIS Market