
 RF Microneedling Market | 2026-2036
RF Microneedling Market Size, Share, and Industry Trends Forecast 2026-2036
RF Microneedling Market Outlook
Subscription-based maintenance and software-defined treatment protocols is restructuring how RF microneedling vendors capture recurring revenue beyond hardware sales. Lumenis leverages its installed base across dermatology networks to sustain service contract attachment rates. Cutera anchors its commercial strategy through direct-to-clinic training programs that deepen practitioner loyalty. Candela Corporation differentiates via proprietary energy-delivery algorithms that lock clinics into branded consumable ecosystems.
RF microneedling combines insulated or non-insulated microneedle arrays with radiofrequency energy delivery at frequencies typically ranging from 1-6 MHz to create controlled thermal zones in the dermis for collagen remodeling and tissue tightening. Fractional RF technology leads device category revenue due to its established efficacy profile and broader clinical indication set, while pulsed RF configurations represent the fastest-expanding segment as practitioners seek reduced downtime protocols for patient retention. Combined devices that integrate microneedling with complementary modalities such as cryogen cooling or LED therapy command premium positioning and capture disproportionate margin pools in aesthetic center settings.
FDA 510(k) clearance requirements shape device development timelines and predicate selection strategies for manufacturers seeking US market access, while the EU Medical Device Regulation imposes strengthened clinical evidence standards that filter smaller competitors from European distribution. The country's national pharmaceutical regulator in Japan maintains distinct biocompatibility testing protocols that create additional compliance layers for needle array materials. Stakeholders must monitor evolving energy-based device classification precedents across major jurisdictions to anticipate reimbursement and prescribing pathway shifts.
Market Dynamics
Subscription-based maintenance contracts and software-defined treatment protocols are restructuring how RF microneedling vendors capture recurring revenue streams beyond initial hardware transactions. This shift from capital expenditure to operational expenditure models is compressing traditional sales cycles while locking clinics into branded consumable ecosystems and proprietary energy-delivery algorithms.
Growth Catalysts
- FDA 510(k) Clearance Streamlining:The FDA's expedited predicate device pathways for fractional RF systems are accelerating market entry timelines for manufacturers targeting dermatology networks in the United States.
- Aesthetic Center Chain Consolidation:Multi-site clinic operators in the United States are driving bulk procurement of combined device platforms, creating volume concentration that favors vendors with scalable service infrastructure.
- Pulsed RF Configuration Adoption:Practitioners seeking reduced downtime protocols for patient retention are expanding pulsed RF device deployment, broadening clinical indication sets beyond traditional fractional systems.
Market Restraints
- EU Medical Device Regulation Compliance Costs:The EU MDR's strengthened clinical evidence standards are filtering smaller competitors from European distribution, concentrating market access among capitalized manufacturers.
- Biocompatibility Testing Protocol Fragmentation:Japan's distinct needle array material requirements impose additional compliance layers that extend development timelines and raise certification expenditures.
- High Capital Intensity for Combined Platforms:Integrated devices incorporating cryogen cooling or LED therapy command premium positioning that limits accessibility for independent dermatology practices.
Strategic Opportunities
- Underpenetrated Japanese Aesthetic Markets:METI's support for medical device innovation creates regulatory tailwinds for RF microneedling expansion in Japan's growing cosmetic dermatology sector.
- LED Therapy Convergence:Combined platforms integrating radiofrequency microneedling with photobiomodulation are capturing disproportionate margin pools in high-end aesthetic center settings.
- Direct-to-Clinic Training Channel Development:Vendor-operated practitioner education programs are deepening loyalty and reducing switching behavior among dermatology network procurement officers.
Industry Challenges
- Practitioner Certification Complexity:Energy-based device operation requires specialized training that extends onboarding timelines and raises human capital costs for clinic operators.
- Consumable Supply Chain Reconfiguration:Branded needle array ecosystems create dependency risks for clinics when single-source suppliers experience manufacturing disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Microneedling Market |
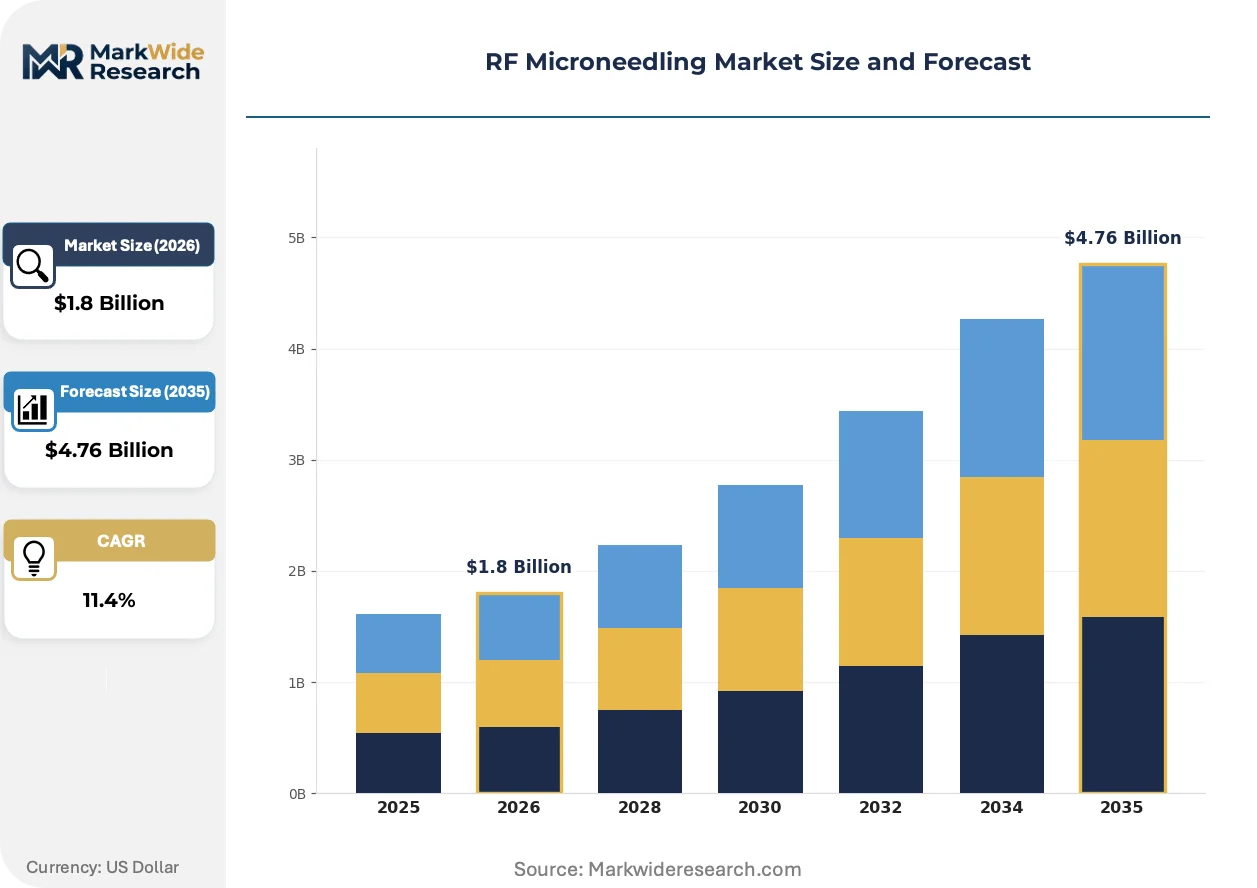
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Stand-Alone Devices, Combined Devices, Modular Devices, Handheld Devices Application Area: Facial Rejuvenation, Scar Treatment, Stretch Mark Reduction, Acne Treatment End User: Dermatology Clinics, Aesthetic Centers, Hospitals, Home Users Technology: Fractional RF, Continuous RF, Pulsed RF, Multi-Polar RF |
| Companies Covered | Endymed Medical, Aesthetics Biomedical, Lumenis, CONMED Corporation, Stryker Corporation, Cutera, Cynosure, Medtronic, Candela Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Microneedling Market Strategic Shifts
RF microneedling technology is experiencing rapid evolution across energy delivery mechanisms, regulatory frameworks, and commercial models. These developments are compressing product lifecycles while creating new competitive differentiation vectors for device manufacturers and service providers.
Insulated microneedle arrays with precise depth control are overtaking non-insulated configurations in premium device categories. Dermatology clinics in the United States are adopting these systems at accelerated rates to minimize epidermal thermal damage while maximizing dermal collagen remodeling efficacy. This technology is overtaking legacy fractional RF platforms in high-margin aesthetic center segments by enabling safer treatment protocols for darker skin phototypes.
The EU Medical Device Regulation's post-market surveillance requirements are reshaping clinical evidence obligations for RF microneedling manufacturers seeking CE marking. Device developers must now maintain systematic registries of real-world performance data, raising ongoing compliance expenditures. Fractional RF systems with established predicate histories are adapting through enhanced post-market clinical follow-up protocols, while novel pulsed RF entrants face extended evaluation periods.
Aesthetic center procurement officers are unbundling after-sales service contracts from hardware purchases, forcing vendors to compete on maintenance pricing transparency. Independent dermatology practices in the United States are driving this behavior through collective purchasing arrangements that separate device acquisition from training and software update commitments. This pattern is most visible in metropolitan markets where practice management consultants advise on capital expenditure optimization.
RF Microneedling Market Segmentation
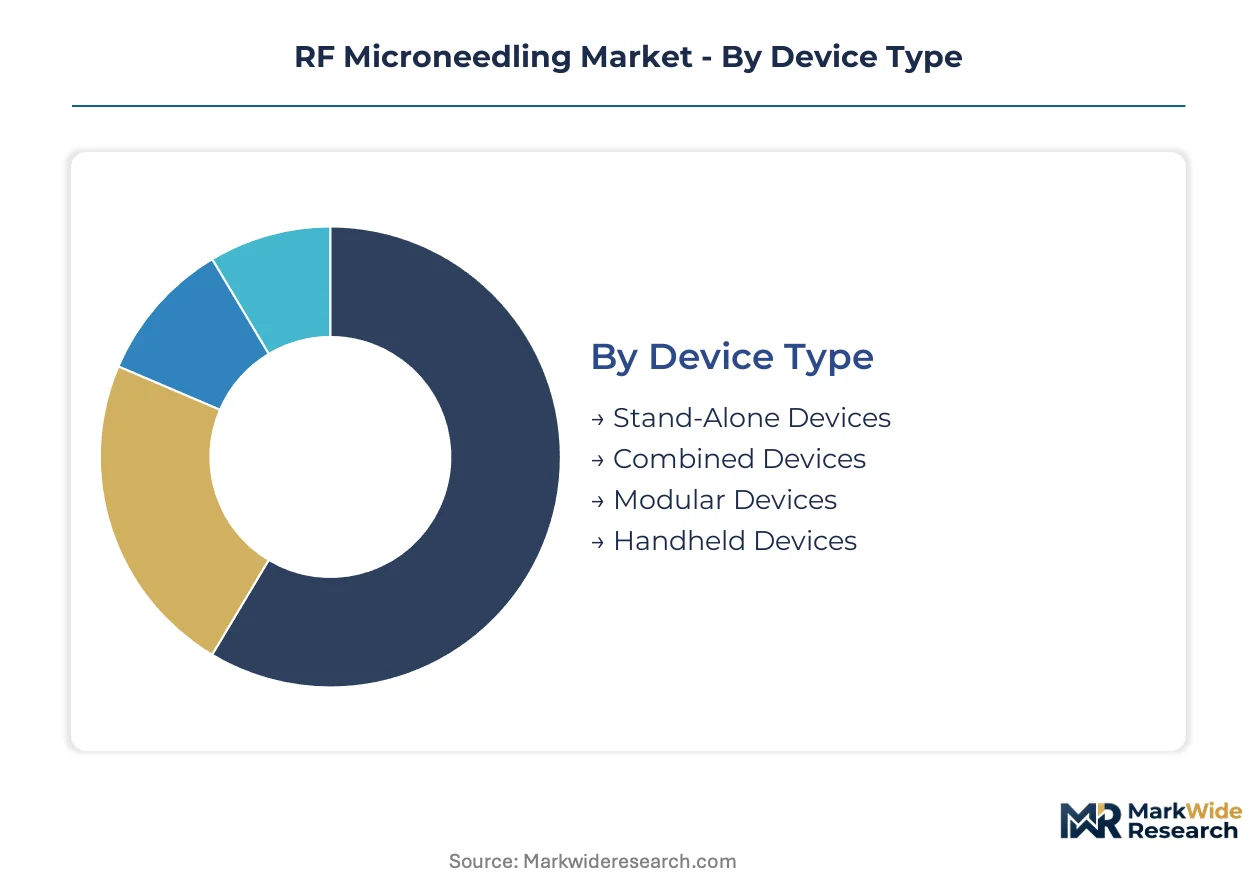
RF microneedling market segmentation reveals distinct procurement patterns across device configurations and clinical settings. Technology differentiation and end-user scale requirements create divergent margin structures that vendors must navigate through targeted platform development.
Device Type:
Supply concentration favors manufacturers with scalable production infrastructure for integrated platform architectures.
- Stand-Alone Devices:Dedicated RF microneedling systems with fixed energy parameters dominate independent dermatology practices seeking single-modality reliability. Demand concentrates in United States metropolitan markets where practice management consultants advise on capital expenditure optimization for mid-tier aesthetic centers.
- Combined Devices:Integrated platforms incorporating cryogen cooling, LED therapy, or suction mechanisms capture premium positioning in high-volume clinic chains. Aesthetic center procurement officers in California and Texas drive bulk purchasing of these multi-modal systems for operational efficiency.
- Modular Devices:Upgradeable hardware architectures with swappable handpiece configurations.
- Handheld Devices:Portable units targeting mobile practitioner services and limited-space installations.
Today's leader: Combined Devices. Tomorrow's challenger: Modular Devices.
Application Area:
Cost tier stratification separates premium indications requiring specialized training from standardized protocols.
- Facial Rejuvenation:Collagen induction and skin tightening procedures constitute the foundational revenue base for RF microneedling platforms. United States dermatology networks in Florida and New York prioritize these treatments for patient retention and recurring appointment scheduling.
- Scar Treatment:Post-surgical and traumatic scar revision applications command elevated pricing due to specialized technique requirements. Academic medical centers in Massachusetts and Pennsylvania drive protocol development for these complex indications.
- Stretch Mark Reduction:Abdominal and thigh applications expanding in postpartum aesthetic services.
- Acne Treatment:Active inflammatory and post-inflammatory hyperpigmentation protocols.
Volume concentrates in facial rejuvenation. Margin expansion potential sits with scar treatment.
End User:
Customer type determines service contract attachment rates and consumable ecosystem lock-in potential.
- Dermatology Clinics:Physician-supervised practices with established patient bases generate predictable recurring revenue for device vendors. Multi-site operators in Illinois and Ohio negotiate enterprise pricing for standardized platform deployments across regional networks.
- Aesthetic Centers:Non-physician supervised facilities with high patient throughput prioritize treatment speed and marketing differentiation. Texas and Arizona chains drive demand for pulsed RF configurations that enable reduced-downtime protocol advertising.
- Hospitals:Academic and community health systems with plastic surgery departments.
- Home Users:Consumer-directed devices with limited energy output for personal maintenance applications.
Dermatology clinics anchor current procurement. Aesthetic centers represent the steepest expansion trajectory.
Technology:
Maturity curves separate established predicate pathways from emerging configurations requiring extended clinical validation.
- Fractional RF:Established energy delivery through insulated microneedle arrays with precise depth control dominates FDA 510(k) clearance pathways. United States manufacturers leverage extensive predicate device histories to accelerate market entry for next-generation fractional systems.
- Pulsed RF:Burst-mode energy delivery minimizing thermal accumulation enables safer treatment protocols for darker skin phototypes. Aesthetic centers in Georgia and North Carolina adopt these systems to expand addressable patient demographics.
- Continuous RF:Sustained energy application with traditional thermal build-up profiles.
- Multi-Polar RF:Multiple electrode configurations for broader treatment area coverage.
Fractional RF holds installed base dominance. Pulsed RF is gaining share fastest among new platform acquisitions.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aesthetic center chains procure combined device platforms at scale, while Japanese clinics navigate distinct biocompatibility testing protocols for needle array materials. Regulatory fragmentation across major jurisdictions shapes manufacturer market entry strategies and predicate device selection.
United States
Dermatology networks in Florida and Texas drive bulk purchasing of fractional RF systems with established FDA 510(k) clearance pathways. The FDA's expedited predicate device review accelerates market entry timelines for manufacturers targeting multi-site clinic operators. California aesthetic center chains command premium positioning for integrated platforms incorporating cryogen cooling or LED therapy modalities.
Germany
Academic medical centers in Berlin and Munich prioritize scar treatment protocols requiring specialized technique certification for practitioners. The EU Medical Device Regulation imposes strengthened clinical evidence standards that filter smaller competitors from European distribution. Bavarian dermatology clinics adopt post-market surveillance registries to maintain systematic real-world performance documentation.
Japan
Cosmetic dermatology practices in Tokyo and Osaka expand pulsed RF deployment for reduced-downtime patient retention protocols. METI's support for medical device innovation creates regulatory tailwinds for RF microneedling platform adoption. The country's national pharmaceutical regulator maintains distinct needle array material requirements that extend development timelines for foreign manufacturers.
United Kingdom
Independent dermatology practices in London and Manchester negotiate collective purchasing arrangements that separate device acquisition from service contracts. Post-Brexit regulatory alignment with EU MDR standards preserves CE marking recognition while creating parallel compliance obligations. Scottish aesthetic centers prioritize modular device architectures with swappable handpiece configurations for operational flexibility.
South Korea
Seoul-based clinic chains adopt handheld portable units targeting mobile practitioner services and limited-space installations. The MFDS maintains rigorous energy-based device classification standards that shape predicate selection strategies for domestic manufacturers. Busan aesthetic centers drive demand for combined platforms integrating photobiomodulation with radiofrequency microneedling for premium service differentiation.
RF Microneedling Market Competitive Environment
Top-tier vendors anchor the premium integrated platform segment, while mid-tier specialists concentrate on stand-alone fractional RF systems. The vendor base stratifies across three archetypes: diversified medical device conglomerates with aesthetic portfolios, pure-play energy-based device manufacturers, and emerging modular platform specialists. Competitive moves center on direct-to-clinic training program expansion and proprietary consumable ecosystem lock-in through branded needle array supply arrangements.
Within the pure-play aesthetic device tier, Lumenis and Cutera exemplify contrasting commercial strategies for sustaining service contract attachment rates. Candela Corporation occupies a position emphasizing proprietary energy-delivery algorithms that deepen practitioner loyalty. CONMED Corporation and Stryker Corporation represent diversified medical technology conglomerates with aesthetic device exposure through broader surgical and interventional portfolios. Endymed Medical and Aesthetics Biomedical anchor the emerging specialist category with focused RF microneedling platform development.
| Leading Market Players |
|---|
| Endymed Medical |
| Aesthetics Biomedical |
| Lumenis |
| CONMED Corporation |
| Stryker Corporation |
| Cutera |
| Cynosure |
| Medtronic |
| Candela Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA 510(k)-cleared fractional RF systems and unvalidated offshore alternatives manifests in pricing spreads exceeding three-to-one, while supply chain configurations concentrate precision-manufactured needle array production in Germany and Japan to satisfy biocompatibility requirements for premium tier placement.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for handheld RF microneedling units, compressing margins for mid-tier stand-alone device vendors. Subscription-based service contracts with software-defined treatment protocols command premium positioning over transactional hardware sales, with FDA clearance tier and training bundling as primary price differentiation drivers. Pricing pressure stems from aesthetic center chains unbundling after-sales commitments to optimize capital expenditure. Independent dermatology practices exhibit highest price sensitivity, while multi-site operators prioritize total cost-of-ownership over acquisition price.
Supply Chain Analysis
Direct-to-clinic channels handle hyperscale buyer demand from United States aesthetic center chains, bypassing traditional medical device distributors. Precision-machined needle arrays draw from German and Japanese specialty metalworking suppliers, with insulated tip configurations resting on proprietary polymer coating capabilities concentrated in the United States and Switzerland. Single-source vulnerability pervades branded consumable ecosystems, where vendor-locked needle cartridges create dependency exposure. Distribution runs through manufacturer-operated training and service networks rather than independent logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's distinct biocompatibility testing protocols impose compliance cost premiums of roughly forty percent versus FDA pathways, creating arbitrage opportunities for domestic manufacturers with established PMDA relationships.
For Market Incumbents: Anchor service contract attachment rates through proprietary energy-delivery algorithm updates that deepen practitioner dependency. Defend against modular platform specialists by accelerating backward integration into precision needle array manufacturing. Prioritize certification investment in Japan's PMDA pathway to exploit regulatory friction that filters foreign competitors. For New Entrants and Emerging Players: Capture underpenetrated scar treatment segments in academic medical centers where specialized technique requirements limit incumbent focus. Target pulsed RF configurations for darker skin phototype protocols, the fastest-expanding indication with reduced competitive density. Pursue direct-to-clinic training channel development as primary go-to-market angle to bypass established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where service infrastructure scale determines enterprise contract capture among multi-site dermatology networks. Five-to-ten year viability favors vendors with installed base depth and consumable ecosystem lock-in rather than hardware-only positioning. Target acquisition archetype: modular platform specialists with swappable handpiece architectures. Monitor FDA 510(k) clearance backlog duration as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited predicate device review accelerates market entry for fractional RF systems targeting United States dermatology networks. |
| CE Marking Pathway | EU MDR compliance filters smaller competitors, concentrating European distribution among capitalized manufacturers with clinical evidence infrastructure. |
| Hospital System Partnership | Academic medical centers in Massachusetts and Pennsylvania drive protocol development for complex scar treatment applications. |
| Software Companion Development | Proprietary treatment algorithms lock clinics into branded consumable ecosystems and recurring service revenue streams. |
| Reimbursement Strategy | Energy-based device classification precedents across major jurisdictions shape prescribing pathway and patient access economics. |
Study Parameters
Multiple input streams — structured interviews with dermatology clinic procurement officers, aesthetic center chain operations directors, and biomedical engineers at device manufacturers — were reconciled against FDA 510(k) clearance databases, EU MDR notified body filings, and hospital procurement contract registries. Primary fieldwork with GPO contracts managers and training program directors supplemented secondary validation from patent filings and regulatory submission documents. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Segmentation dimensions spanning device configuration, application area, end-user type, and technology maturity were modeled across the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle analysis, and penetration trajectory modeling for pulsed RF configurations. Forecast inputs incorporated FDA review timeline variability, EU MDR transition completion rates, and aesthetic center chain consolidation patterns.
Regulatory pathway delays, supply chain disruptions in precision needle array manufacturing, and aesthetic center capital expenditure freezes are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding continued FDA predicate device pathway availability and stable biocompatibility testing protocol frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market