
 Axial and Mixed Flow Pumps Market | 2026-2036
Axial and Mixed Flow Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Axial and Mixed Flow Pumps Market Outlook
Chinese foundry capacity for large-cast pump housings is rebalancing toward specialty alloys as export controls on graphite electrodes tighten. Flowserve Corporation leverages its aftermarket service network across Latin American mining corridors to sustain recurring revenue from vertical turbine installations. Grundfos Holding A/S anchors its position in European district cooling through digital twin integration for HVAC-specified axial pumps. KSB SE & Co. KGaA differentiates via material science leadership in duplex stainless steel casings for seawater intake applications.
Axial and mixed flow pumps are dynamic fluid machines where the impeller imparts both pressure and kinetic energy to move large water volumes at relatively low heads, typically operating below 500 kW with specific speeds between 4,000 and 15,000 for axial designs. These configurations dominate flood control networks and raw water transfer systems where flow rates exceed 10,000 cubic meters per hour against minimal static lift. Stainless steel material grades command premium positioning in corrosive environments such as desalination pre-treatment and chemical process cooling, while cast iron retains volume leadership in agricultural drainage and municipal stormwater. Submersible pump architectures represent the fastest-growing product configuration as wet-pit installations eliminate suction piping and reduce civil works costs for irrigation districts.
EPA Clean Water Act discharge standards and EU F-Gas Regulation phase-down schedules shape product development cycles for cooling water and refrigeration-linked pump systems across North American and European installations. China's MEE wastewater discharge limits and India's CEA thermal power plant water-use mandates accelerate replacement demand for higher-efficiency mixed flow units in existing plant retrofits. Stakeholders must monitor how ISO 5198 hydraulic performance testing protocols and emerging carbon border adjustment mechanisms reshape supplier qualification criteria and sourcing geography for large-diameter pump castings.
Market Dynamics
China's dual carbon goals and MEE discharge standards are forcing wholesale replacement of conventional centrifugal pump fleets with higher-efficiency axial configurations, compressing supplier lead times and reshaping foundry capacity allocation toward specialty alloys.
Growth Catalysts
- India's CEA thermal power mandates:Water-use efficiency requirements at existing coal and gas plants accelerate retrofit procurement of mixed flow units designed for cooling tower circuits.
- Submersible wet-pit architectures:Irrigation districts across Southeast Asia eliminate suction piping infrastructure, cutting civil works costs by half and shortening project commissioning timelines.
- Desalination pre-treatment expansion:Stainless steel axial pumps with duplex casings capture volume from reverse osmosis intake systems in the Middle East and North Africa.
Market Restraints
- Graphite electrode export controls:Chinese foundry feedstock restrictions tighten supply of large-cast pump housings above 1,500 mm diameter, extending delivery schedules by 8-12 weeks.
- Cast iron price volatility:Scrap metal input costs for agricultural drainage pumps swing with commodity cycles, compressing margin stability for volume-tier manufacturers.
- Centrifugal incumbent lock-in:Municipal utilities face switching costs from legacy vertical turbine installations, slowing axial pump penetration in established water treatment networks.
Strategic Opportunities
- EU F-Gas Regulation phase-down:HVAC-linked cooling water systems require pump retrofits compatible with low-GWP refrigerants, opening specification windows for European district cooling contractors.
- Digital twin integration:Predictive maintenance platforms for axial pump fleets converge with SCADA systems, enabling performance-based service contracts in Latin American mining corridors.
- Indonesia's irrigation modernization:State-level lift station replacement programs target 40,000 aging units, creating concentrated demand for mixed flow configurations with variable frequency drives.
Industry Challenges
- Hydraulic engineer scarcity:Specialized computational fluid dynamics expertise for high-specific-speed impeller design concentrates at Tier-1 suppliers, constraining mid-tier product development cycles.
- ISO 5198 certification timelines:Third-party hydraulic performance testing protocols add 4-6 months to new product qualification, delaying market entry for redesigned axial pump lines.
- Legacy control system integration:New variable-speed drives must interface with 1980s-era SCADA architectures at US municipal water authorities, complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axial and Mixed Flow Pumps Market |
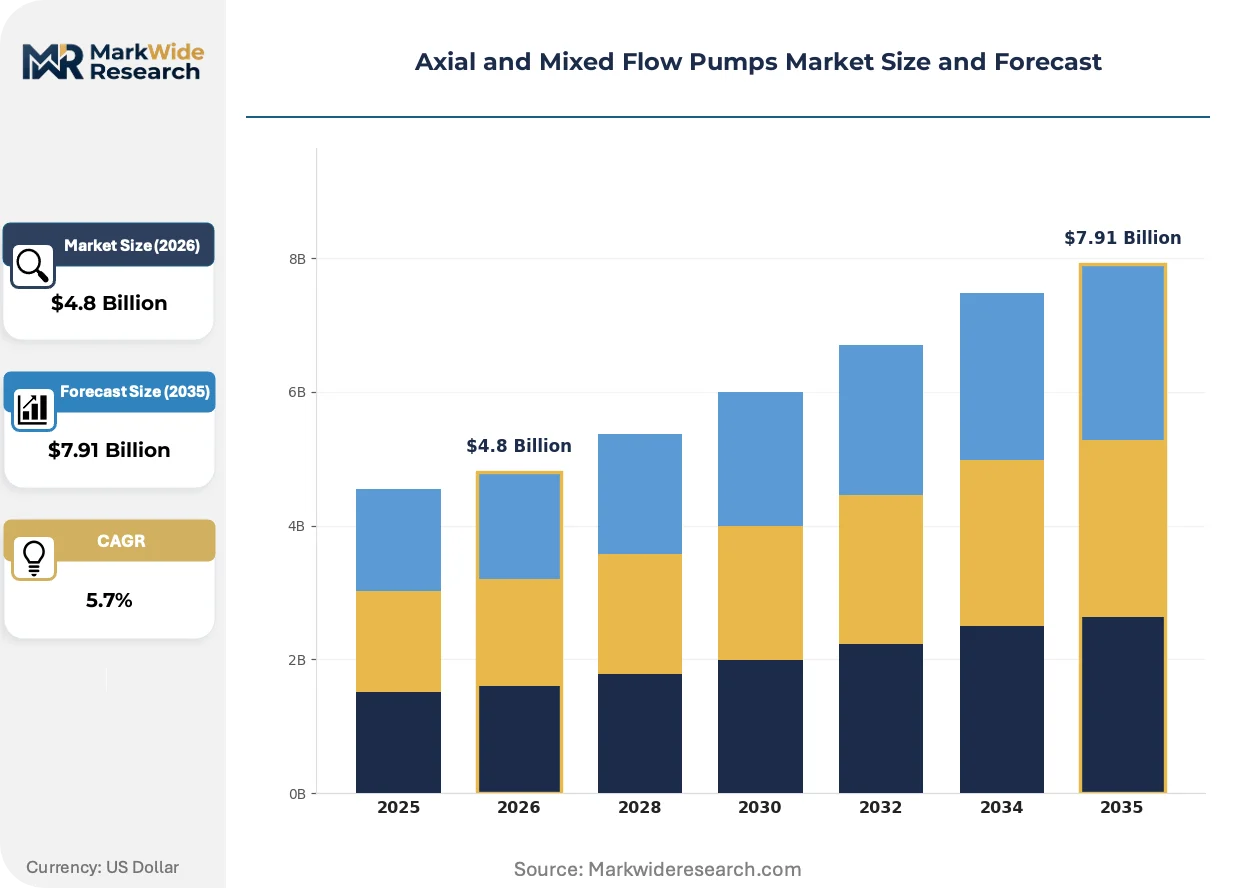
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Pumps, Mixed Flow Pumps, Submersible Pumps, Vertical Turbine Pumps End User: Agriculture, Water Treatment, Oil & Gas, Power Generation Material: Stainless Steel, Cast Iron, Plastic, Bronze Application: Irrigation, Flood Control, Fire Fighting, HVAC |
| Companies Covered | Kubota Corporation, Flowserve Corporation, Xylem Inc., Ebara Corporation, Grundfos Holding A/S, Franklin Electric Co., Inc., Pentair plc, KSB SE & Co. KGaA, Sulzer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axial and Mixed Flow Pumps Market Strategic Shifts
Digital instrumentation, advanced materials science, and regulatory compliance automation are converging to redefine pump system lifecycle economics. Equipment buyers now prioritize total cost of ownership metrics over upfront capital expenditure.
Computational fluid dynamics-optimized impeller geometries are converging with additive manufacturing prototyping to compress development cycles for high-specific-speed axial designs. European district cooling contractors adopt these tools to customize hydraulic profiles for building-specific HVAC loads. The technology is converging with real-time sensor feedback to enable continuous performance optimization without hardware replacement.
EPA Clean Water Act discharge standards are tightening enforcement of cooling water intake structure regulations at US thermal power plants. Facility operators must document impingement and entrainment reduction through velocity cap modifications. Mixed flow pumps with fish-friendly hydraulic designs capture specification share from conventional axial units in retrofit applications.
Service unbundling is separating aftermarket maintenance from original equipment procurement across Latin American mining operations. End-users now contract independent hydraulic service firms for vertical turbine overhauls, bypassing manufacturer captive service networks. Chilean copper concentrators lead this shift, negotiating parts-only supply agreements with foundries in Brazil and Mexico.
Axial and Mixed Flow Pumps Market Segmentation
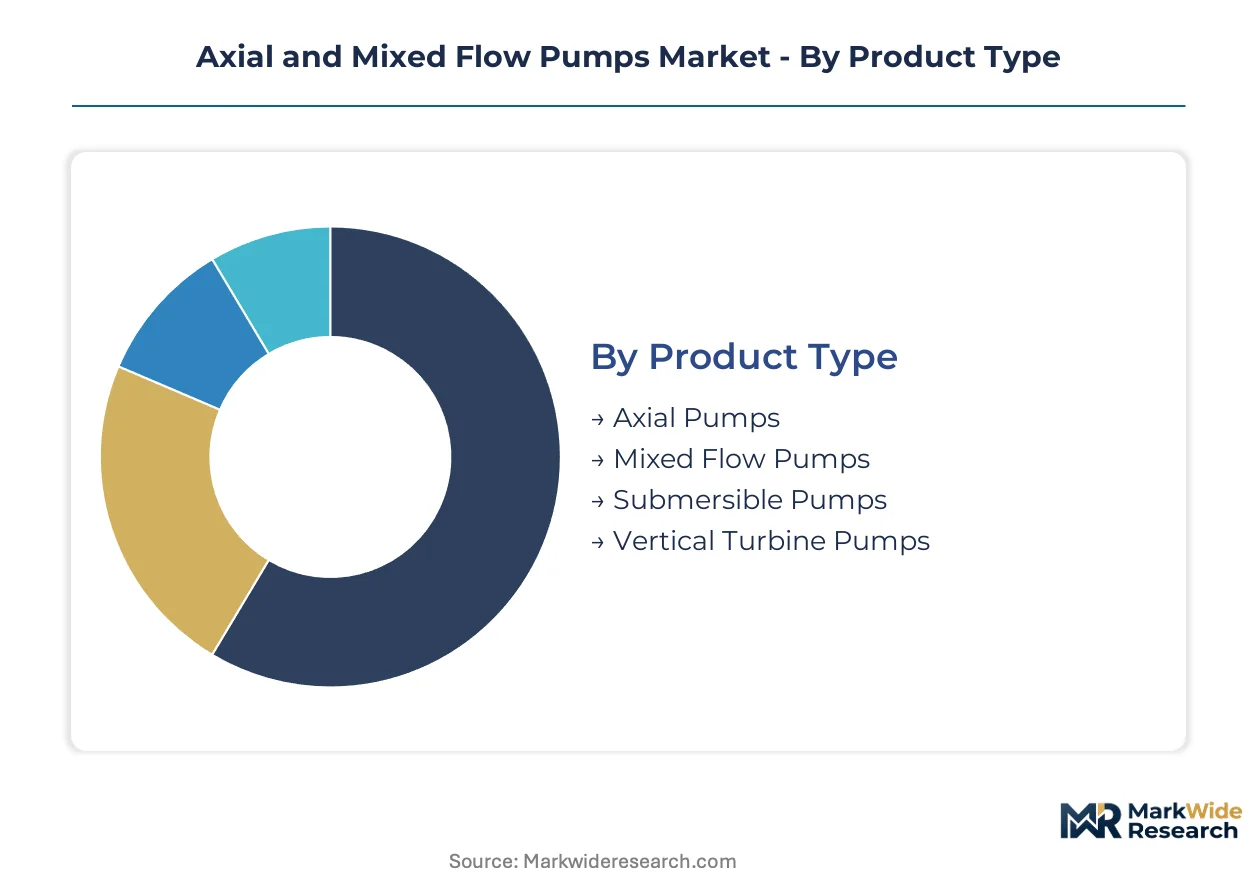
Axial and mixed flow pump procurement patterns diverge sharply across installation contexts, with standalone flood control networks demanding different hydraulic profiles than embedded HVAC cooling circuits. Material selection and product architecture choices cascade through lifecycle cost calculations, particularly in corrosive environments where duplex stainless steel commands premium positioning against cast iron volume alternatives.
Product Type:
Standalone installations dominate raw water transfer and agricultural drainage, while embedded configurations integrate into building HVAC and industrial process cooling systems.
- Axial Pumps:These high-specific-speed designs (4,000–15,000) generate flow rates exceeding 10,000 cubic meters per hour against minimal static heads below 20 meters. Municipal drainage authorities in Vietnam and Thailand specify these for urban flood control networks where low-head, high-volume performance is non-negotiable.
- Mixed Flow Pumps:Intermediate hydraulic geometry blends axial and radial flow characteristics to serve cooling tower circuits at Indian thermal power plants. CEA water-use mandates are accelerating retrofit procurement as older centrifugal units face efficiency compliance deadlines.
- Submersible Pumps:Wet-pit architectures eliminate suction piping and halve civil works costs for Southeast Asian irrigation districts.
- Vertical Turbine Pumps:Deep-well configurations serve raw water intake at Latin American mining operations.
Volume placements concentrate in Axial Pumps; the faster expansion belongs to Submersible Pumps.
End User:
Cost tier segmentation separates capital-intensive utility procurement from price-sensitive agricultural volume purchasing.
- Agriculture:State-level irrigation modernization programs in India and Indonesia drive replacement demand for aging lift stations. Procurement concentrates on cast iron configurations with variable frequency drives to cut operating expenditure across thousands of district-level installations.
- Water Treatment:Municipal utilities in China's Yangtze River basin upgrade to MEE-compliant discharge systems. Stainless steel axial pumps with duplex casings capture specification share for seawater intake at desalination pre-treatment facilities.
- Oil & Gas:Produced water handling and cooling water circuits at Middle Eastern refineries specify corrosion-resistant materials.
- Power Generation:Combined cycle plants require mixed flow units for closed-loop cooling tower service.
Revenue concentration sits with Water Treatment; Agriculture delivers the steepest expansion trajectory.
Material:
Application severity dictates material grade selection, with chloride exposure and abrasion resistance driving premium alloy adoption.
- Stainless Steel:Duplex and super-duplex grades dominate desalination pre-treatment intake systems across Saudi Arabia and UAE. These alloys withstand seawater corrosion where cast iron would fail within 18 months of commissioning.
- Cast Iron:Standard gray iron retains volume leadership in agricultural drainage and municipal stormwater where chemical exposure is minimal. Scrap metal input cost volatility compresses margin stability for tier-two manufacturers serving price-sensitive procurement.
- Plastic:Thermoplastic housings serve chemical process cooling with aggressive media.
- Bronze:Naval bronze impellers specify for marine applications and fire fighting systems.
Cast Iron captures the volume base; Stainless Steel is climbing the fastest on unit value expansion.
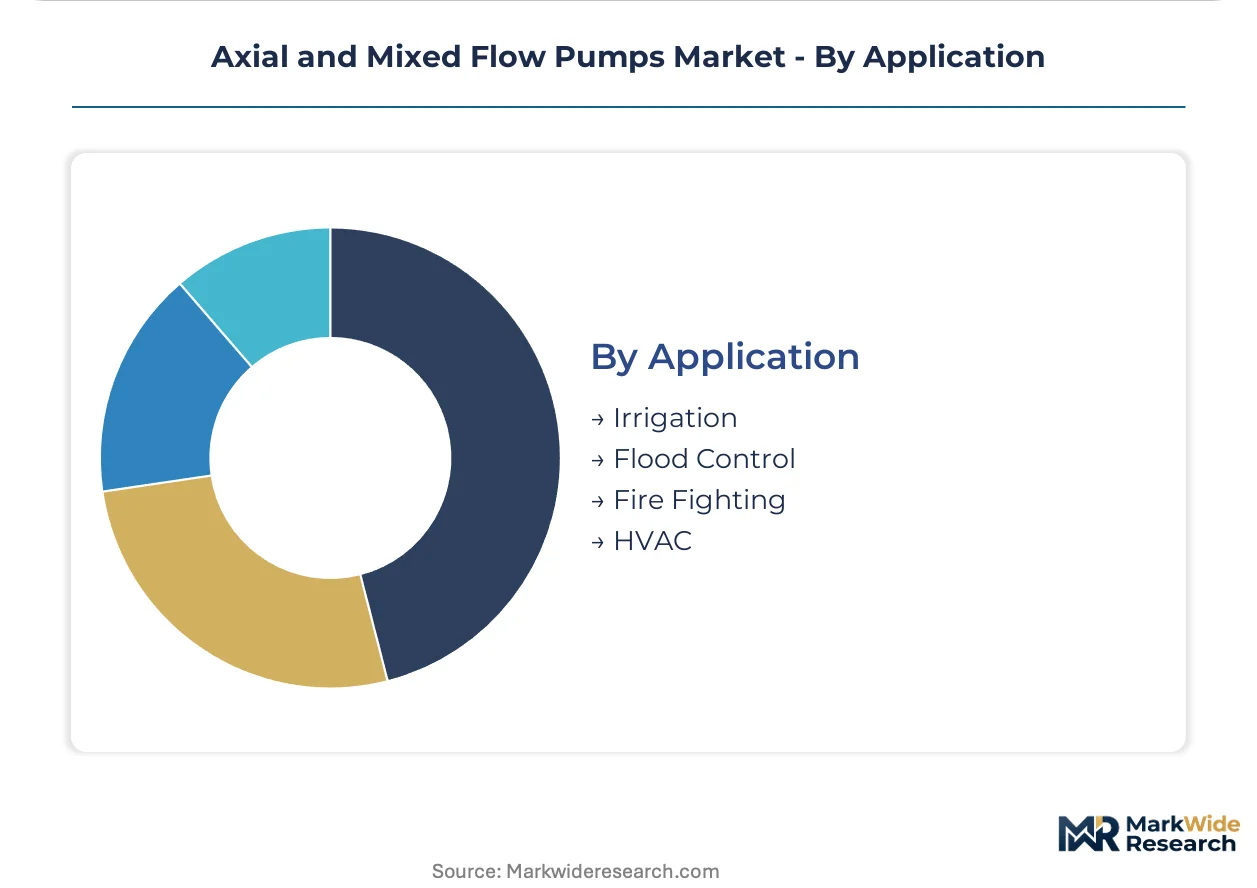
Application:
Customer type segmentation separates project-based infrastructure contractors from recurring maintenance procurement at operating facilities.
- Irrigation:Indonesia's target of 40,000 lift station replacements concentrates demand for mixed flow configurations with integrated VFD control. State procurement frameworks favor domestic assembly requirements, reshaping supplier qualification criteria.
- Flood Control:EPA Clean Water Act cooling water intake structure regulations at US thermal power plants mandate velocity cap modifications. Fish-friendly hydraulic designs in mixed flow pumps capture retrofit specification share from conventional axial units.
- Fire Fighting:NFPA-compliant vertical turbine installations serve industrial facility protection.
- HVAC:EU F-Gas Regulation phase-down schedules force pump compatibility verification with low-GWP refrigerant circuits.
Irrigation anchors volume demand; HVAC retrofits are gaining share fastest on regulatory compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphite electrode supply from Hebei Province foundries anchors procurement patterns for large-cast pump housings across Asia-Pacific. Regional demand clusters around coastal desalination corridors, inland irrigation modernization, and thermal power cooling retrofits.
China
Yangtze River basin municipal utilities upgrade discharge systems under MEE wastewater limits. Dual carbon goals force replacement of centrifugal fleets with axial configurations at steel and chemical complexes. Zhejiang and Jiangsu provinces concentrate wet-pit submersible installations for urban drainage expansion.
India
CEA water-use mandates accelerate mixed flow pump retrofits at coal and gas thermal plants. State-level irrigation programs in Maharashtra and Gujarat replace aging lift stations with variable frequency drive units. The National Thermal Power Corporation drives specification volumes for cooling tower circuits.
United States
EPA Clean Water Act cooling water intake regulations mandate velocity cap modifications at legacy thermal plants. Fish-friendly hydraulic designs capture retrofit share from conventional axial units. Municipal water authorities in California and Texas face legacy SCADA integration challenges for variable-speed drive upgrades.
Germany
EU F-Gas Regulation phase-down schedules force pump compatibility verification with low-GWP refrigerants in district cooling networks. Hamburg and Munich utility operators specify digital twin-integrated axial pumps for HVAC-linked systems. REACH compliance shapes duplex stainless steel sourcing for chemical process applications.
Saudi Arabia
Desalination pre-treatment expansion at Jubail and Yanbu industrial cities drives duplex stainless steel axial pump procurement. Seawater intake systems specify corrosion-resistant casings under MOHAP environmental discharge frameworks. The Saline Water Conversion Corporation anchors volume demand for reverse osmosis feed pumps.
Axial and Mixed Flow Pumps Market Competitive Environment
Global majors compete with regional champions across aftermarket service networks and foundry capacity allocation. The vendor base separates into three tiers: integrated multinational pump groups, mid-scale regional fabricators, and specialized submersible manufacturers. Strategic archetypes include full-lifecycle service providers, material science specialists, and digital-integrated system integrators. Dominant competitive moves encompass geographic expansion through distribution partnerships and backward integration into specialty alloy casting capacity.
Among Japanese industrial conglomerates, Kubota Corporation and Ebara Corporation occupy positions emphasizing agricultural and municipal water infrastructure. Flowserve Corporation exemplifies the aftermarket-centric archetype through service network density. Grundfos Holding A/S and KSB SE & Co. KGaA represent European engineering-led positioning with material science differentiation in corrosive environment applications.
| Leading Market Players |
|---|
| Kubota Corporation |
| Flowserve Corporation |
| Xylem Inc. |
| Ebara Corporation |
| Grundfos Holding A/S |
| Franklin Electric Co., Inc. |
| Pentair plc |
| KSB SE & Co. KGaA |
| Sulzer Ltd |
| Others |
Value Chain & Pricing Dynamics
Additive manufacturing prototyping for high-specific-speed impeller geometries is compressing development timelines while simultaneously concentrating production capability among Tier-1 suppliers with capital equipment access. This technological transition simultaneously raises upfront tooling costs for mid-tier fabricators and shifts bargaining power toward buyers with volume scale.
Pricing Analysis
Warranty and aftermarket service bundling separates premium supplier positioning from unbundled commodity transactions. Project-based pricing dominates municipal infrastructure procurement where lifecycle cost calculations override upfront capital expenditure. Price differentiation rests on ISO 5198 hydraulic certification tier and duplex stainless steel material grade. Cost compression in cast iron agricultural configurations is intensifying due to scrap metal input volatility, while stainless steel desalination units face inelastic demand from Middle Eastern utilities.
Supply Chain Analysis
Dual-sourcing requirements for large-diameter pump housings above 1,500 mm diameter are now standard among European and North American municipal utilities. Foundry capacity concentrates in China, India, and Germany for specialty alloy castings. Raw material dependencies include graphite electrodes, duplex stainless steel feedstock, and rare earth elements for magnetic drive submersible units. Single-source vulnerability persists around Chinese graphite electrode export controls. Distribution runs through manufacturer-direct channels for large infrastructure projects and regional distributor networks for agricultural replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration for predictive maintenance is displacing reactive service models across European district cooling and Latin American mining installations. This technology transition compresses margins for suppliers lacking software development capability while rewarding engineering-led vendors with full-lifecycle platforms.
For Market Incumbents: Lock in aftermarket revenue streams by extending service contracts to cover legacy vertical turbine installations at US municipal water authorities. Backward integration into specialty alloy casting capacity in India or Southeast Asia mitigates Chinese graphite electrode supply risk. Prioritize ISO 5198 certification investment to maintain specification access in EU public procurement frameworks.
For New Entrants and Emerging Players: Indonesian irrigation districts with 40,000 lift station replacement targets represent the most penetrable buyer archetype. State procurement frameworks favor domestic assembly partnerships, creating entry pathways for joint ventures with local fabricators. Target variable frequency drive integration as a differentiated go-to-market angle for agricultural modernization programs.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated multinational pump groups seeking regional service network density. The five-to-ten year viability window favors material science specialists with duplex stainless steel expertise for corrosive environment applications. Monitor CEA thermal power retrofit timelines in India as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Casting | Captive supply of duplex stainless steel housings insulates margin from Chinese graphite electrode restrictions. |
| Digital Twin Platform Development | Predictive maintenance integration with SCADA systems enables performance-based service contracts in Latin American mining. |
| ISO 5198 Certification Investment | Third-party hydraulic performance validation opens specification windows in EU public infrastructure procurement. |
| Joint Venture with Indonesian Fabricators | Domestic assembly qualification meets state procurement requirements for 40,000 lift station replacement program. |
| Fish-Friendly Hydraulic Design R&D | EPA Clean Water Act compliance for velocity cap modifications captures retrofit share from conventional axial units. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant engineers, municipal procurement officers, aftermarket service heads, and hydraulic design specialists combined with secondary validation from MEE discharge standard documentation, CEA thermal power mandates, and EPA Clean Water Act enforcement records. Bottom-up installation tracking and top-down foundry capacity assessment were triangulated to establish market sizing.
Reconciliation of shipment data, import-export flows, and project announcement pipelines shaped the analytical framework. Segmentation dimensions modeled include product architecture, material grade, end-use application, and regional regulatory cluster. CAGRs were derived from curve-fitting historical procurement patterns against policy-mandated replacement schedules. Desalination capacity expansion timelines and irrigation modernization program budgets served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when graphite electrode export restrictions tighten, MEE discharge standards accelerate, or CEA thermal power mandates shift. Deviation in Chinese foundry capacity allocation or Indian state-level procurement pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Mud Pumps Market