
 Retail Printers and Consumables Market | 2026-2036
Retail Printers and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Printers and Consumables Market Outlook
Vietnam's electronics manufacturing corridor is fragmenting as contract assemblers diversify from pure smartphone production into printer chassis and consumable molding. HP Inc. leverages its captive ink chemistry R&D to sustain margins on recurring cartridge revenue. Canon Inc. anchors production scale across Thailand and Vietnam while Brother Industries Ltd. competes aggressively in compact laser segments for small-format retail environments.
Retail printers and consumables encompass electrophotographic and inkjet imaging systems alongside replaceable supplies including pigment-based inks, polymer toner powders, thermal ribbons, and coated substrates engineered for barcode legibility, archival permanence, or photographic gamut. Laser printers and toner cartridges retain the dominant installed base in high-volume back-office retail settings where cost-per-page economics govern procurement. Inkjet systems and photo-grade ink cartridges represent the fastest-expanding margin pool, driven by on-demand color label production and personalized packaging workflows in direct-to-consumer fulfillment nodes.
The US EPA Energy Star program and the EU Ecodesign Directive together mandate standby power thresholds and cartridge recyclability benchmarks that OEMs must satisfy for market access across both jurisdictions. China's GB standards for electronic product pollution control and India's BIS compulsory registration scheme add parallel compliance layers for imported hardware. Stakeholders must monitor how regional right-to-repair legislation reshapes aftermarket consumable economics and authorized channel obligations.
Market Dynamics
E-commerce fulfillment networks are compressing hardware refresh cycles as warehouse operators replace aging laser fleets with color-capable inkjet systems for on-demand label and packaging personalization. This demand rotation is redrawing procurement priorities across retail back offices and logistics nodes.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power thresholds and cartridge recyclability benchmarks are forcing OEM design upgrades that lock in recurring consumable revenue streams through proprietary authentication chips.
- Fulfillment center densification:Parcel sortation hubs in Germany, the Netherlands, and Poland are installing high-speed thermal transfer printers for shipping label production, driving ribbon and substrate pull-through demand.
- Pigment ink chemistry advances:Water-resistant formulations now meet barcode permanence standards for outdoor retail signage and agricultural supply chain tracking, opening agricultural cooperatives and garden center networks as new install bases.
Market Restraints
- Polymer toner resin supply:Petrochemical feedstock volatility and Asian monomer concentration create input cost instability for laser cartridge remanufacturers in North American and European aftermarket channels.
- Right-to-repair legislative friction:France's repairability index mandates and pending EU-wide legislation threaten OEM cartridge authentication revenue models by mandating interoperability disclosures.
- Smartphone scanning substitution:Mobile device-based QR code validation is displacing fixed-mount barcode printer installations in smaller retail formats, compressing unit demand in convenience store and boutique segments.
Strategic Opportunities
- India BIS compulsory registration:The phased import control regime for electronic products creates first-mover advantage for OEMs establishing local assembly or certification partnerships ahead of full enforcement.
- Direct-to-garment convergence:Hybrid printer systems combining aqueous pigment ink with reactive dye sublimation are enabling micro-fulfillment of customized apparel from retail storefronts, merging consumable categories.
- Subscription-managed print services:Device-as-a-service contracts with automatic consumable replenishment are penetrating mid-market retail chains in Australia and South Korea, converting capital expenditure to recurring revenue relationships.
Industry Challenges
- Firmware engineering talent scarcity:OEMs and independent service organizations compete for embedded systems developers capable of integrating cloud-based print management with legacy point-of-sale architectures.
- Cross-border e-waste compliance:The Basel Convention's hazardous waste tracking requirements complicate reverse logistics for cartridge collection programs spanning multiple national jurisdictions.
- ISO 14001 environmental management certification:Extended timeline and documentation burden for consumables manufacturing facilities seeking certification to qualify for corporate sustainability procurement criteria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Printers and Consumables Market |
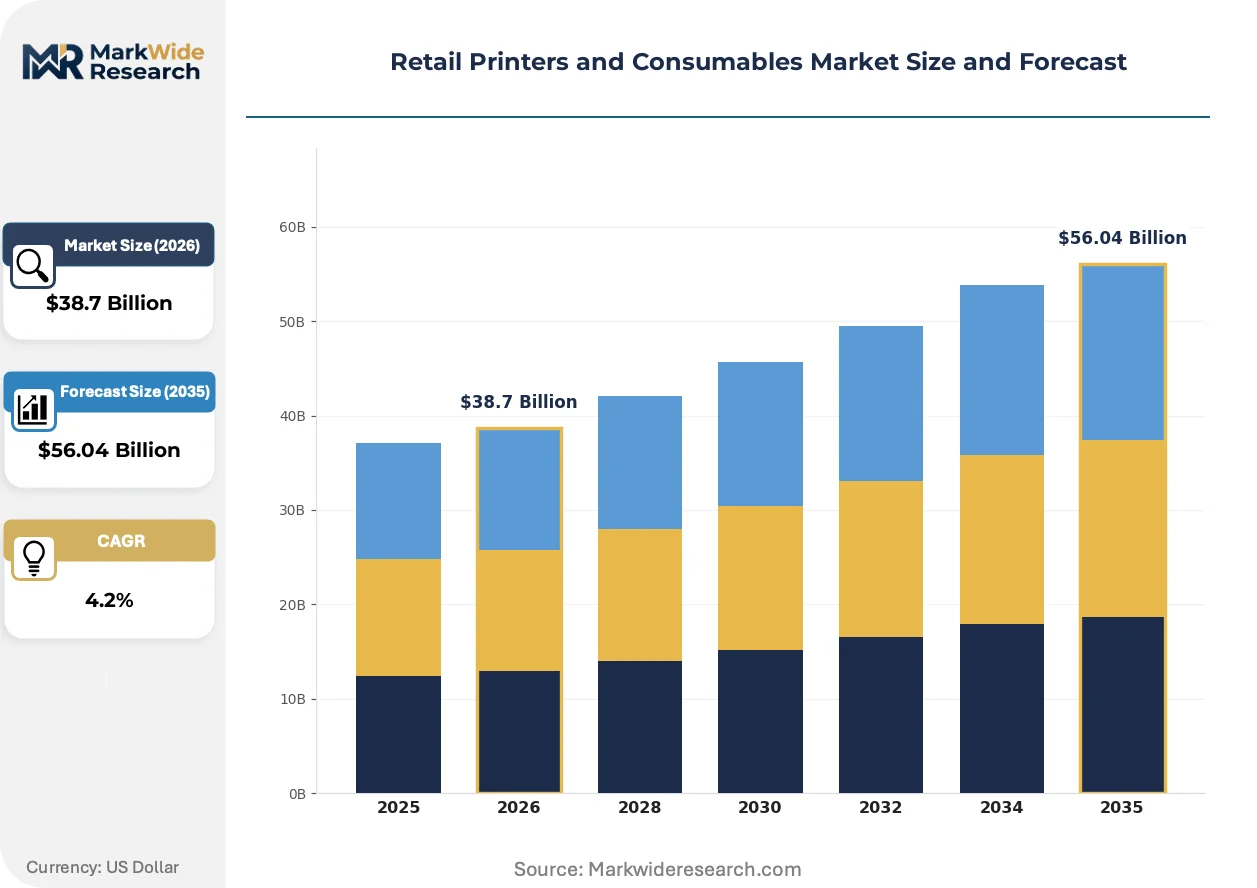
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, POS Printers, 3D Printers Consumable Type: Ink Cartridges, Toner Cartridges, Printing Paper, Ribbons End User: Retail Stores, E-commerce Businesses, Distribution Centers, Wholesalers Application: Label Printing, Receipt Printing, Document Printing, Photo Printing |
| Companies Covered | HP Inc., Canon Inc., Seiko Epson Corporation, Brother Industries Ltd., Xerox Corporation, Ricoh Company Ltd., Konica Minolta Inc., Kyocera Corporation, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Printers and Consumables Market Strategic Shifts
Hardware-software convergence and consumable chemistry advances are redefining value capture models across retail imaging, shifting margin pools from device sales toward authenticated supply contracts and managed print services.
Memjet-powered single-pass inkjet arrays are rendering obsolete multi-pass carriage systems in high-volume label production environments. Third-party logistics providers operating cross-border e-commerce hubs in Belgium and Singapore are adopting these systems for same-day personalization workflows. The technology is rendering obsolete traditional thermal transfer equipment in applications requiring photographic color gamut or variable data density.
The US EPA Energy Star Version 3.0 imaging equipment specification tightens operational and standby power thresholds for eligible products. OEM engineering teams must redesign power management firmware and thermal control systems to maintain certification access in federal and corporate procurement channels. Laser printer segments targeting government and healthcare verticals face the steepest compliance redesign costs and longest validation timelines.
Consolidated procurement through group purchasing organizations is concentrating buyer power among retail pharmacy and grocery cooperatives in North America. Independent regional distributors are losing shelf space to direct OEM relationships or national wholesaler contracts with guaranteed service level agreements. This concentration is most visible in the United States Midwest and Southeast where pharmacy benefit managers have unified imaging equipment standards across thousands of storefront locations.
Retail Printers and Consumables Market Segmentation
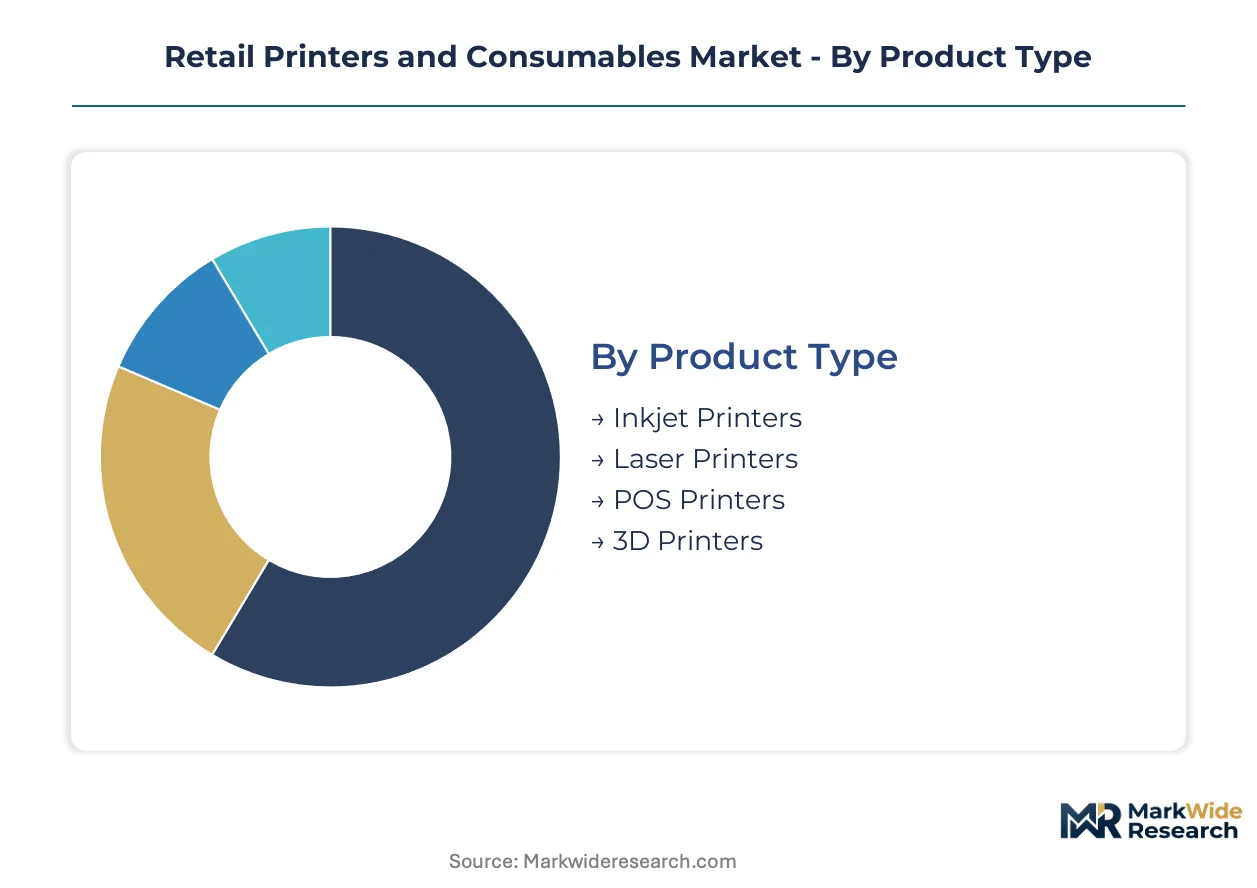
Segmentation in retail imaging equipment reveals how hardware specifications and consumable chemistries align with distinct operational workflows across fulfillment networks and storefront environments. Procurement patterns diverge sharply between high-volume back-office installations and customer-facing personalization nodes.
Product Type:
Retail operations deploy imaging hardware across a functional spectrum spanning customer-facing personalization, back-office documentation, transaction recording, and prototyping applications.
- Laser Printers:Electrophotographic systems utilizing polymer toner powders and organic photoconductor drums deliver cost-per-page economics below inkjet alternatives. Demand concentrates in Germany and Poland where distribution center operators refresh fleets for high-volume document and label production under EU Ecodesign standby power mandates.
- Inkjet Printers:Piezoelectric or thermal drop-on-demand systems deposit aqueous pigment or dye-based inks onto porous substrates. Adoption is climbing fastest in China's Zhejiang and Guangdong provinces where cross-border e-commerce exporters deploy color-capable systems for on-demand packaging personalization.
- POS Printers:Compact thermal or dot-matrix mechanisms engineered for receipt and coupon generation at transaction terminals. These units dominate convenience store installations across Japan's metropolitan retail corridors.
- 3D Printers:Fused filament fabrication and resin-based stereolithography systems producing prototype fixtures and custom retail displays. Deployment remains concentrated in flagship concept stores operated by multinational apparel brands.
Established volume favors laser printers; emerging adoption favors inkjet printers.
Consumable Type:
Recurring revenue models across retail imaging depend on chemistry-locked supplies that authenticate against host hardware, with formulation specifications governing print permanence and substrate compatibility.
- Toner Cartridges:Sealed units containing polymer resin particles, charge control agents, and release additives for electrophotographic transfer. Remanufacturing economics in North America face feedstock volatility from Asian monomer concentration.
- Ink Cartridges:Reservoir assemblies delivering pigment or dye formulations through precision nozzles. Water-resistant pigment chemistries are gaining traction fastest among agricultural cooperative networks requiring outdoor barcode permanence.
- Printing Paper:Calendered or coated substrates engineered for ink absorption, thermal sensitivity, or photographic gamut reproduction. Specialty label stocks command premium positioning in pharmaceutical serialization applications.
- Ribbons:Wax, resin, or wax-resin thermal transfer films depositing barcode images onto synthetic labels. Parcel sortation hubs in Belgium and the Netherlands drive ribbon pull-through from same-day fulfillment workflows.
Recurring margin concentrates in toner cartridges; formulation innovation accelerates fastest in ink cartridges.
End User:
Hardware procurement authority and consumable replenishment responsibility vary across organizational structures with differing capital expenditure cycles and managed service adoption rates.
- Distribution Centers:High-throughput logistics nodes operating multi-shift label production for parcel sortation and inventory management. These facilities in Germany and Poland are replacing thermal transfer equipment with single-pass inkjet arrays.
- E-commerce Businesses:Direct-to-consumer fulfillment operations requiring variable data printing for personalized packaging and return label generation. China's coastal exporters are modernizing fastest under domestic retail digitization mandates.
- Retail Stores:Brick-and-mortar locations deploying customer-facing receipt printers and back-office document systems. Consolidated procurement through pharmacy benefit managers is concentrating buyer power across United States Midwest installations.
- Wholesalers:Intermediate distributors managing inventory documentation and shipping label production for downstream retail accounts. These operators lag in hardware refresh cycles compared to direct e-commerce fulfillment nodes.
Procurement scale favors distribution centers; service contract penetration climbs fastest among e-commerce businesses.
Application:
Print job specifications determine hardware selection and consumable chemistry, with permanence requirements and color gamut needs driving technology differentiation.
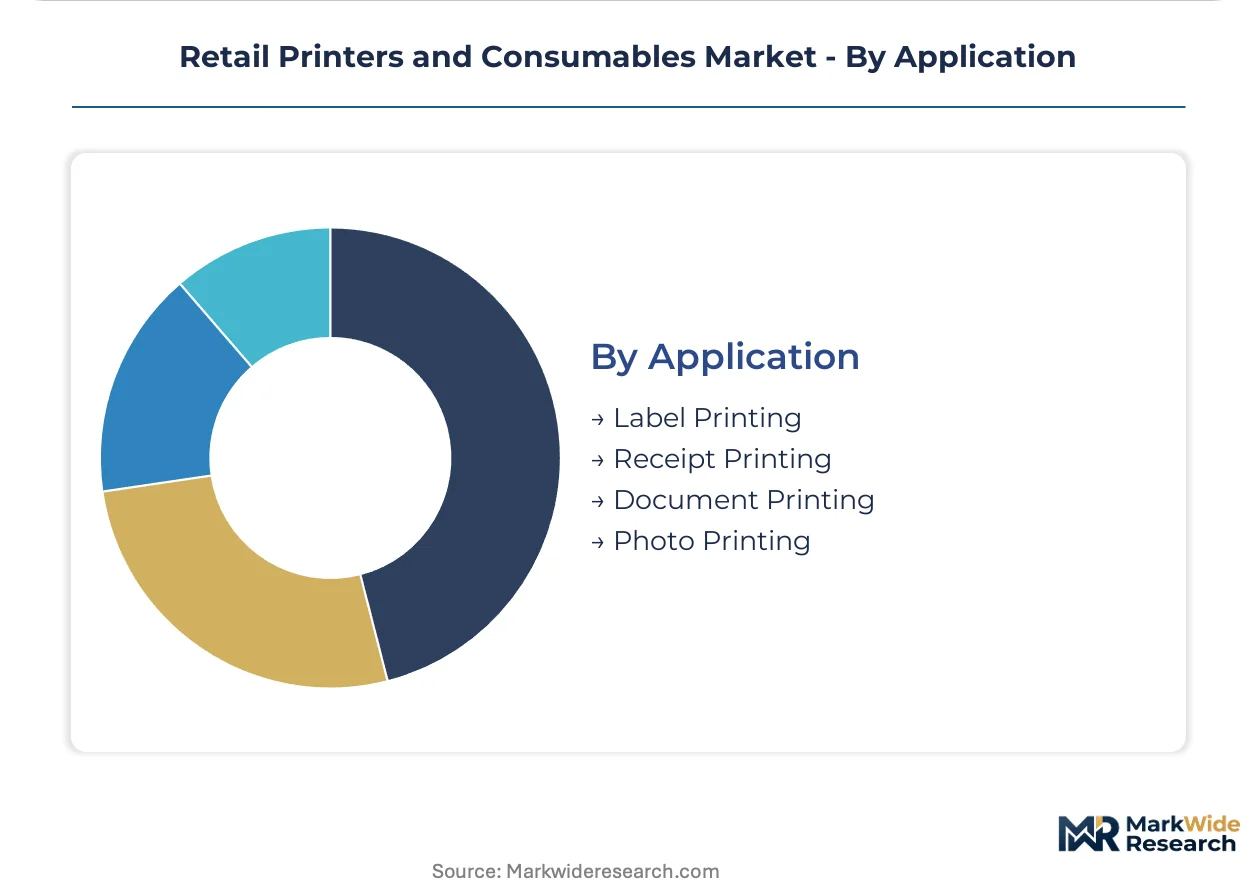
- Label Printing:Barcode, shipping, and product identification outputs requiring scannable precision and environmental resistance. Thermal transfer dominates parcel applications while inkjet gains ground in color variable-data packaging.
- Document Printing:Administrative, compliance, and archival outputs prioritizing cost efficiency over color capability. Laser electrophotography retains installed base dominance in back-office retail settings.
- Receipt Printing:Transaction records generated at point-of-sale terminals, typically via thermal paper without ink or ribbon. Mobile payment penetration is compressing unit demand in Japan's convenience store segment.
- Photo Printing:Photographic gamut outputs for customer personalization and retail display production. Dye sublimation and aqueous pigment systems are converging in hybrid direct-to-garment applications.
Operational necessity sustains document printing; margin expansion concentrates in label printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA Energy Star program anchors demand formation in the United States, where federal procurement channels and corporate sustainability mandates enforce standby power thresholds for imaging equipment. This regulatory architecture cascades through OECD markets and shapes OEM engineering priorities across hardware refresh cycles.
United States
E-commerce fulfillment densification drives hardware replacement across Pennsylvania and Ohio distribution corridors. The EPA Energy Star Version 3.0 specification tightens operational power thresholds for federal procurement eligibility. Dallas-Fort Worth logistics hubs are installing color-capable inkjet systems for on-demand packaging personalization workflows.
Germany
Parcel sortation infrastructure expansion accelerates thermal transfer printer deployment across Rhine-Ruhr logistics nodes. The EU Ecodesign Directive mandates cartridge recyclability benchmarks and standby power limits for imaging equipment. Bavarian industrial clusters host OEM engineering centers optimizing laser printer firmware for compliance redesign cycles.
China
Cross-border e-commerce exporters in Zhejiang and Guangdong provinces modernize fulfillment infrastructure under domestic retail digitization mandates. GB standards for electronic product pollution control impose parallel compliance layers for imported hardware assembly. Shenzhen manufacturing corridors concentrate OEM production scale serving both domestic modernization and export market demand.
Japan
Convenience store network consolidation compresses POS printer unit demand across Tokyo-Osaka metropolitan retail corridors. METI efficiency guidelines shape procurement standards for imaging equipment in commercial applications. Nagoya industrial clusters sustain precision manufacturing capabilities for compact thermal printer mechanisms.
India
Modern trade expansion drives back-office hardware procurement across Maharashtra and Karnataka retail chains. The BIS compulsory registration scheme for electronic products creates phased import control timelines requiring local assembly partnerships. Delhi-NCR distribution nodes are consolidating procurement authority through pharmacy and grocery cooperative structures.
Retail Printers and Consumables Market Competitive Environment
Vertically integrated OEMs and specialized component suppliers split the market into distinct capability tiers. Consolidation pressure concentrates around recurring consumable revenue models protected by authentication chip architectures. Two strategic archetypes dominate: captive chemistry developers leveraging R&D scale for margin capture, and contract assemblers diversifying from adjacent electronics manufacturing. Competitive moves center on geographic production diversification and firmware interoperability defenses against right-to-repair mandates.
Within the captive chemistry tier, HP Inc. and Canon Inc. exemplify integrated development models spanning ink formulation through hardware authentication systems. Brother Industries Ltd. occupies a compact laser specialization position targeting small-format retail environments. These three OEMs anchor the competitive structure through divergent approaches to consumable revenue protection and regional production configuration.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Seiko Epson Corporation |
| Brother Industries Ltd. |
| Xerox Corporation |
| Ricoh Company Ltd. |
| Konica Minolta Inc. |
| Kyocera Corporation |
| Zebra Technologies |
| Others |
Value Chain & Pricing Dynamics
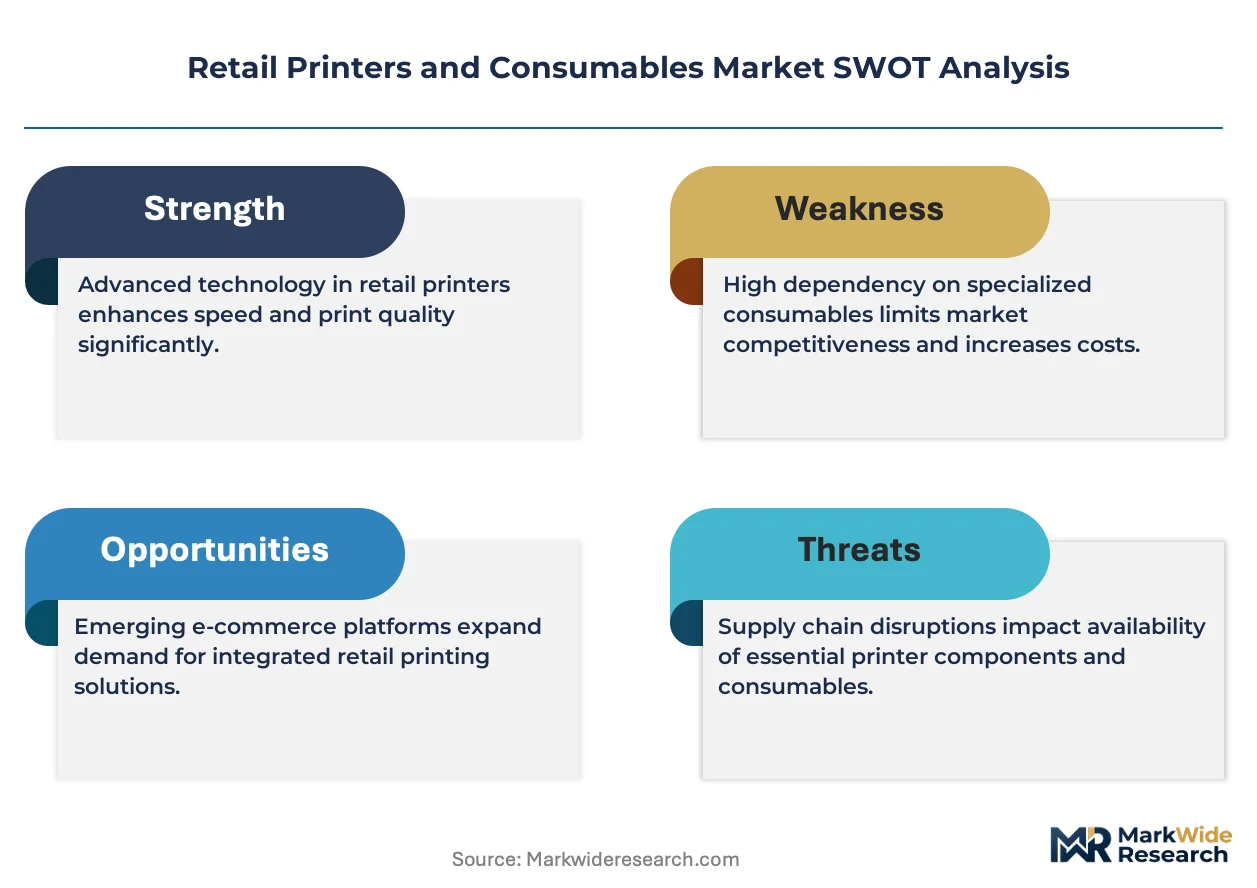
Asian monomer concentration for polymer toner resins feeds directly into margin compression for North American and European cartridge remanufacturers. OEMs with captive ink chemistry R&D capture recurring revenue through authenticated supply contracts that lock in downstream buyers.
Pricing Analysis
Geographic price spreads widen between OEM-authenticated cartridges and third-party alternatives across North American and European channels. Three-tier pricing structure across premium, standard, and economy levels separates enterprise service contracts from retail boxed goods and aftermarket refills. Pricing pressure stems from right-to-repair legislative momentum in France and pending EU-wide interoperability mandates. Small-format retail environments exhibit highest price sensitivity; government and healthcare verticals show lowest due to compliance-driven procurement.
Supply Chain Analysis
Polymer toner resin feedstocks draw from petrochemical complexes concentrated in China, South Korea, and Japan. Laser cartridge manufacturing relies on organic photoconductor drums, charge control agents, and release additives sourced from specialized chemical suppliers. Single-source vulnerability in Asian monomer supply creates input cost instability for Western remanufacturers. Distribution runs through direct OEM relationships and national wholesaler contracts with guaranteed service level agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against smartphone-based QR validation displacing fixed-mount barcode printer installations in smaller retail formats.
For Market Incumbents: Insulate consumable revenue streams by deepening firmware authentication defenses against right-to-repair interoperability disclosures. Prioritize captive ink chemistry R&D investments to sustain margin pools as hardware refresh cycles compress. Defend against mobile scanning substitution by embedding cloud-based print management into legacy point-of-sale architectures. For New Entrants and Emerging Players: Establish a beachhead in India's BIS compulsory registration phased timeline ahead of full enforcement. Target agricultural cooperative networks requiring water-resistant pigment formulations for outdoor barcode permanence. Pursue certification partnerships with local assemblers to bypass import control barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subscription-managed print services as device-as-a-service models convert capital expenditure to recurring revenue relationships. Over the medium-term horizon, acquisition targets should emphasize firms with ISO 14001 environmental management certification qualifying for corporate sustainability procurement criteria. Monitor EU Ecodesign Directive enforcement stringency as an inflection indicator for compliance-driven hardware redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Chip Architecture Investment | Protects recurring consumable revenue against right-to-repair interoperability mandates in EU member states. |
| Local Assembly Partnership | Secures BIS registration compliance for Indian market access ahead of phased import control enforcement. |
| Pigment Chemistry R&D Expansion | Captures agricultural cooperative demand for outdoor barcode permanence in garden center networks. |
| Subscription Service Platform Launch | Converts mid-market retail chain procurement from capital expenditure to recurring revenue relationships. |
| Single-Pass Inkjet Array Adoption | Replaces thermal transfer equipment in Belgium and Singapore cross-border e-commerce fulfillment hubs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of OEM financial disclosures, EPA Energy Star certification databases, EU Ecodesign regulatory filings, and trade customs records. Interviews with distribution center operations managers, retail procurement directors, aftermarket consumables distributors, and firmware engineering leads informed demand-side assumptions. Bottom-up hardware shipment estimates and top-down consumable revenue triangulation were cross-validated against channel inventory data.
Forecast inputs include hardware refresh cycle timing, regulatory compliance redesign costs, and consumable authentication technology adoption curves across the projection horizon. Segmentation dimensions span product type, consumable chemistry, end-user procurement authority, and application permanence requirements. CAGRs were derived from installed base evolution and replacement demand modeling. Industry-specific inputs incorporate EU Ecodesign standby power mandate timelines and India BIS registration phased enforcement.
Stress conditions across polymer resin feedstock volatility, right-to-repair legislative passage timelines, and smartphone scanning substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM authentication chip deployment and regional regulatory enforcement intensity. Cross-checking against EPA Energy Star Version 3.0 certification adoption rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Multi-Functional Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Laser Printer Market
Printers
Global Printer Market
Printers
Thermal Inkjet Printer Market
Printers
Portable Printer Market
Printers
Indonesia Thermal Printer Market
Printers
Inkjet Printers Market
Printers
Ink Tank Printer Market
Printers
Global Inkjet Coders Market
Printers
Photocopiers Market
Printers
Global Thermal Printing Market
Printers
Global UV LED Printers Market
Printers
Thermal Printer Market
Printers
Printer Ribbons Market
Printers
Inkjet Printing Market