
 Global UV LED Printers Market | 2026-2036
Global UV LED Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV LED Printers Market Outlook
Packaging is pivoting toward short-run customization and sustainable curing methods. HP Inc. leverages its thermal inkjet heritage to anchor industrial print service contracts. Durst Phototechnik specializes in high-throughput flatbed architectures for European signage networks. Mimaki Engineering competes through compact hybrid systems targeting Japanese commercial printers.
UV LED printers deploy semiconductor-emitting diodes at 365–405 nm wavelengths to polymerize UV-curable inks without mercury arc lamps, eliminating ozone emissions and reducing substrate heat exposure for sensitive materials. Flatbed printers dominate capital deployment among print service providers seeking rigid-media versatility, while hybrid configurations capture margin pools from commercial printers requiring both roll and sheet workflows. Inkjet technology underpins speed advances in labels and industrial printing, though UV curing subsystems determine total cost of ownership.
EPA emissions guidelines in the United States restrict volatile organic compound releases from conventional solvent printing, steering packaging manufacturers toward LED-cured workflows. REACH chemical registration in Europe governs photoinitiator composition in UV inks, shaping formulation R&D at ink suppliers serving Agfa-Gevaert Group and Roland DG Corporation. China's MEE enforces dual carbon targets that accelerate mercury-lamp phaseouts in Guangdong and Jiangsu print clusters. Stakeholders must monitor evolving photoinitiator toxicity classifications and regional energy-efficiency subsidies to align equipment procurement with compliance timelines.
Market Dynamics
Mercury-lamp phaseout mandates across Germany, China, and the United States are compressing replacement cycles for industrial curing equipment, forcing print service providers to reconfigure capital deployment around semiconductor-emitting diode architectures.
Growth Catalysts
- EU Green Deal emissions targets:Packaging manufacturers in Germany accelerate flatbed system procurement to eliminate ozone emissions from conventional solvent workflows.
- Electronics packaging demand:East Asian contract manufacturers deploy hybrid UV LED configurations for short-run smartphone component labeling.
- China's dual carbon goals:Guangdong and Jiangsu print clusters face MEE enforcement deadlines that mandate mercury-lamp retirement by 2025.
Market Restraints
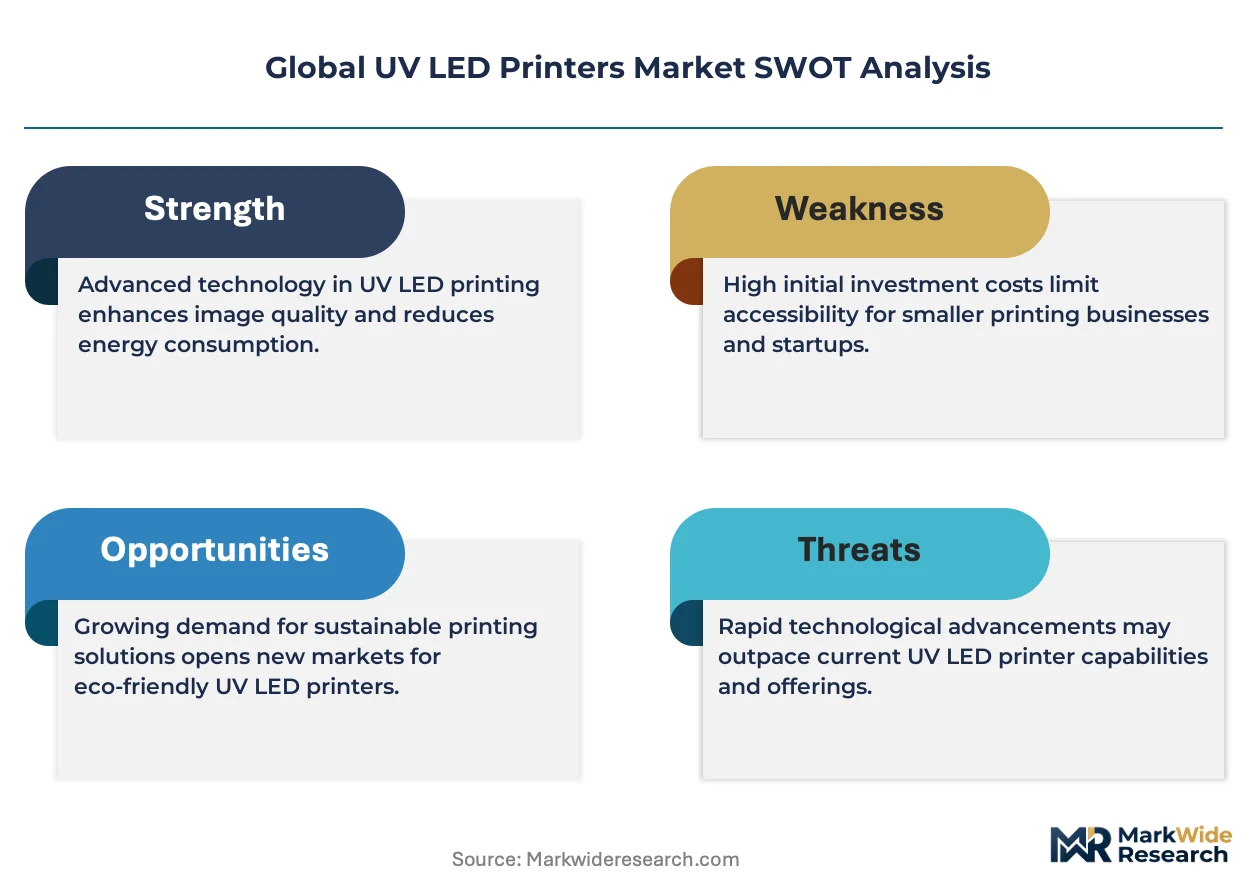
- Photoinitiator supply concentration:Specialty chemical production for 365–405 nm curing formulations clusters in German and Swiss supplier networks.
- Substrate compatibility limitations:Heat-sensitive bioplastics and thin-film electronics require modified LED intensity profiles that extend job setup times.
- REACH registration friction:ECHA chemical governance increases formulation R&D timelines for ink suppliers serving European print networks.
Strategic Opportunities
- Indian commercial print modernization:BIS energy-efficiency labeling creates subsidy pathways for LED-cured equipment adoption in Mumbai and Delhi NCR service corridors.
- Food-contact packaging extension:Low-migration photoinitiator development opens UV LED penetration into dairy and beverage label segments.
- North American industrial service bundling:EPA VOC restrictions drive print service providers toward integrated design-to-cure workflow contracts.
Industry Challenges
- Specialized technician scarcity:Semiconductor diode calibration and ink rheology optimization require skills concentrated in Japanese and German equipment vendor training programs.
- Legacy workflow integration:RIP software and color management systems from mercury-arc installations demand middleware development for LED spectral output profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV LED Printers Market |
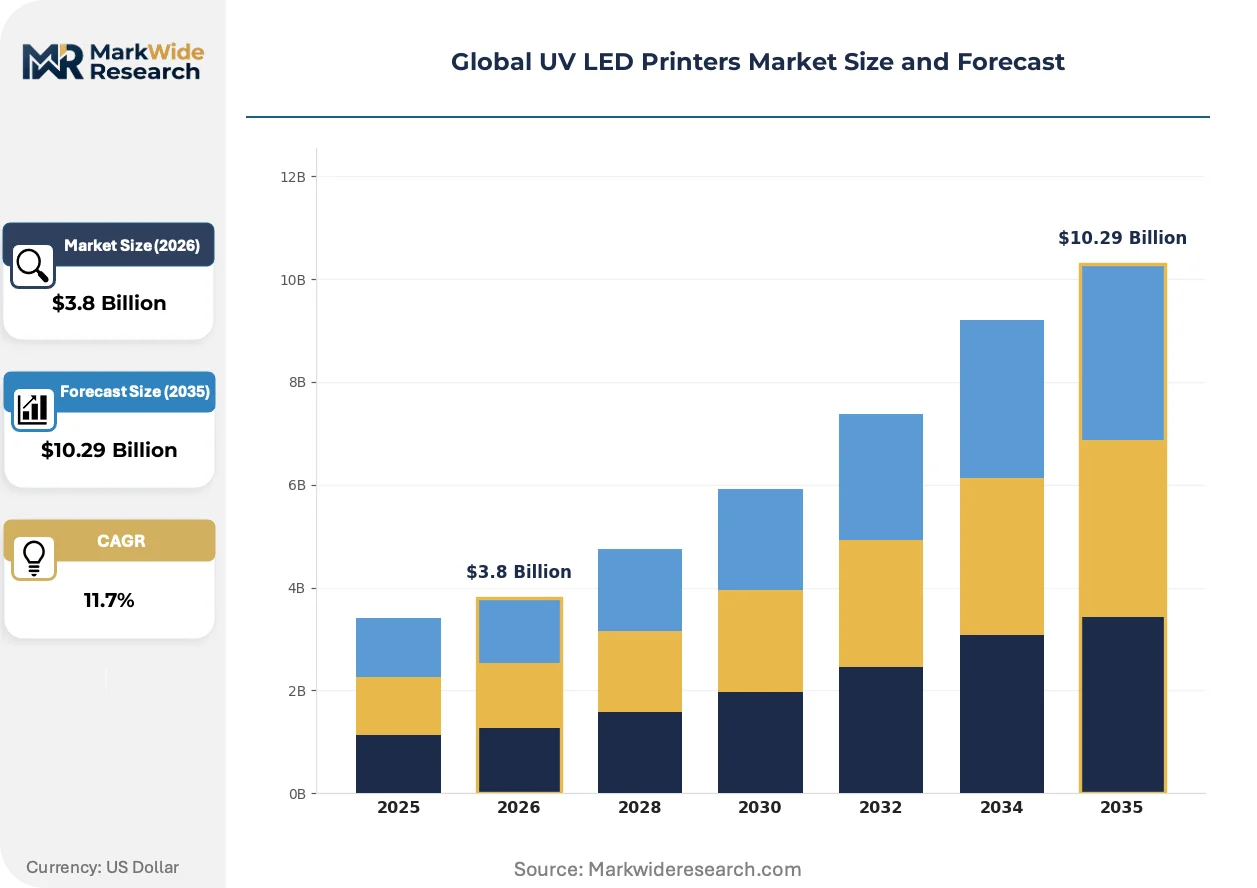
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Printers, Roll-to-Roll Printers, Hybrid Printers, Label Printers Application: Packaging, Signage, Labels, Industrial Printing End User: Print Service Providers, Commercial Printers, Packaging Manufacturers, Sign Makers Technology: Digital Printing, Setup Printing, UV Curing, Inkjet Technology |
| Companies Covered | HP Inc., Mutoh Industries, Mimaki Engineering, Agfa-Gevaert Group, Durst Phototechnik, Epson Corporation, Canon Inc., Xerox Corporation, Roland DG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV LED Printers Market Strategic Shifts
Semiconductor curing architectures are compressing equipment replacement timelines while regulatory chemistry governance and procurement model evolution reshape competitive positioning across print service networks.
Multi-wavelength LED arrays spanning 365–395 nm are electrifying substrate versatility for rigid-media print service providers. North American industrial signage contractors adopt these systems within 18-month replacement cycles. The technology is electrifying margin pools previously captured by thermal drying ovens in wood and ceramic decoration segments.
REACH Annex XVII restrictions on specific photoinitiator compounds are forcing ink reformulation across European packaging supply chains. German and Italian label manufacturers face 24-month compliance windows for food-contact applications. The regulation is compressing supplier consolidation as specialty chemical vendors acquire formulation expertise.
Subscription-based equipment access models are displacing outright purchase in mid-cap print service networks. Japanese commercial printers now prioritize per-page costing structures over capital expenditure approval cycles. This shift concentrates most visibly in Osaka and Nagoya hybrid-system deployments.
Global UV LED Printers Market Segmentation
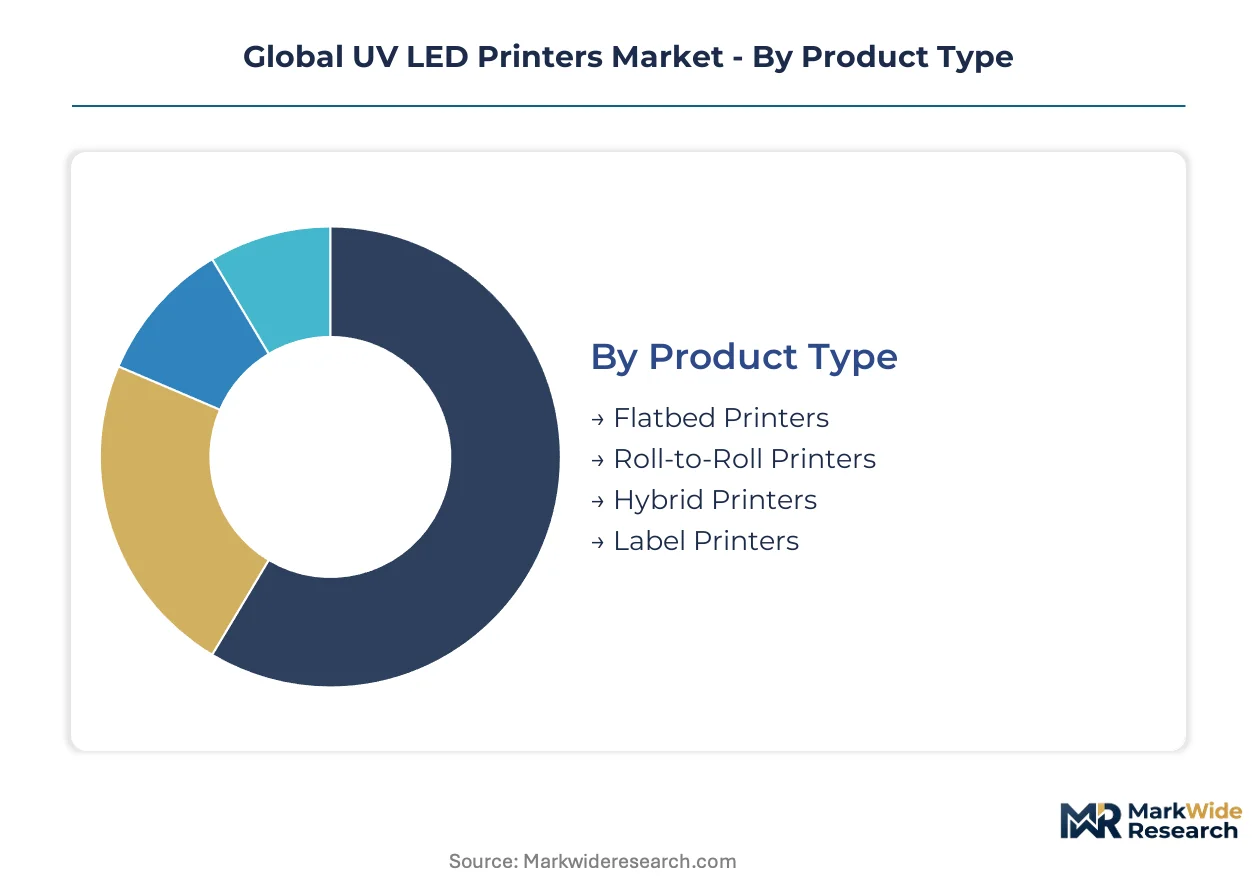
UV LED printer procurement decisions pivot on substrate versatility, regulatory compliance, and workflow integration requirements. Equipment configurations cluster around rigid-media handling, roll-fed flexibility, or hybrid architectures that span both modalities.
Product Type:
Capital deployment intensity varies sharply by equipment architecture, with print service providers weighing floor space constraints against media versatility premiums.
- Flatbed Printers:Rigid-media systems accommodate wood, glass, metal, and acrylic substrates up to 10cm thickness through vacuum table fixation. German signage contractors and Guangdong furniture decorators dominate procurement, driven by EU Green Deal mercury-lamp phaseout deadlines and MEE enforcement in Jiangsu province.
- Hybrid Printers:Dual-mode architectures switch between flatbed and roll-fed configurations without mechanical changeover, capturing margin pools from commercial printers serving mixed short-run jobs. Japanese commercial printers in Osaka and Nagoya prioritize these systems for per-page costing structures under emerging subscription access models.
- Roll-to-Roll Printers:Continuous-feed systems process flexible media including vinyl, banner material, and textiles through tension-controlled web transport.
- Label Printers:Narrow-web configurations target high-speed adhesive substrate production for beverage and pharmaceutical packaging lines.
Flatbed printers lead on scale; hybrid printers lead on momentum.
Application:
End-use demand concentrates where regulatory pressure intersects with customization requirements and substrate sensitivity.
- Packaging:Folding carton, corrugated, and flexible film applications require low-heat curing for heat-sensitive bioplastics and thin-film electronics. REACH Annex XVII photoinitiator restrictions compress formulation R&D timelines for food-contact applications in German and Italian label manufacturing.
- Signage:Large-format rigid and flexible displays for retail, construction, and event markets leverage UV LED's instant curing for same-day turnaround. North American industrial signage contractors in Chicago and Toronto corridors adopt multi-wavelength arrays within compressed 18-month replacement cycles.
- Labels:Pressure-sensitive and shrink-sleeve applications for consumer goods and logistics tracking demand high-resolution variable data printing.
- Industrial Printing:Direct-to-object decoration for ceramics, wood, and promotional products replaces thermal drying ovens with semiconductor curing subsystems.
Signage leads on installed base; packaging leads on regulatory tailwinds.
End User:
Buyer sophistication and capital access determine equipment specification tiers across service provider networks.
- Print Service Providers:Industrial-scale operations serving brand owners and agencies prioritize throughput and substrate range over unit economics. EPA VOC restrictions in US industrial corridors steer these buyers toward integrated design-to-cure workflow contracts.
- Packaging Manufacturers:In-house production facilities for food, beverage, and electronics OEMs demand low-migration photoinitiator compatibility and traceability documentation. BIS energy-efficiency labeling in India creates subsidy pathways for Mumbai and Delhi NCR modernization.
- Commercial Printers:Mid-cap operations serving local business and institutional clients balance equipment versatility against per-job setup burden.
- Sign Makers:Specialized contractors focus on dimensional and illuminated display fabrication with emphasis on white ink opacity and varnish effects.
Print service providers lead on capital deployment; packaging manufacturers lead on compliance-driven replacement.
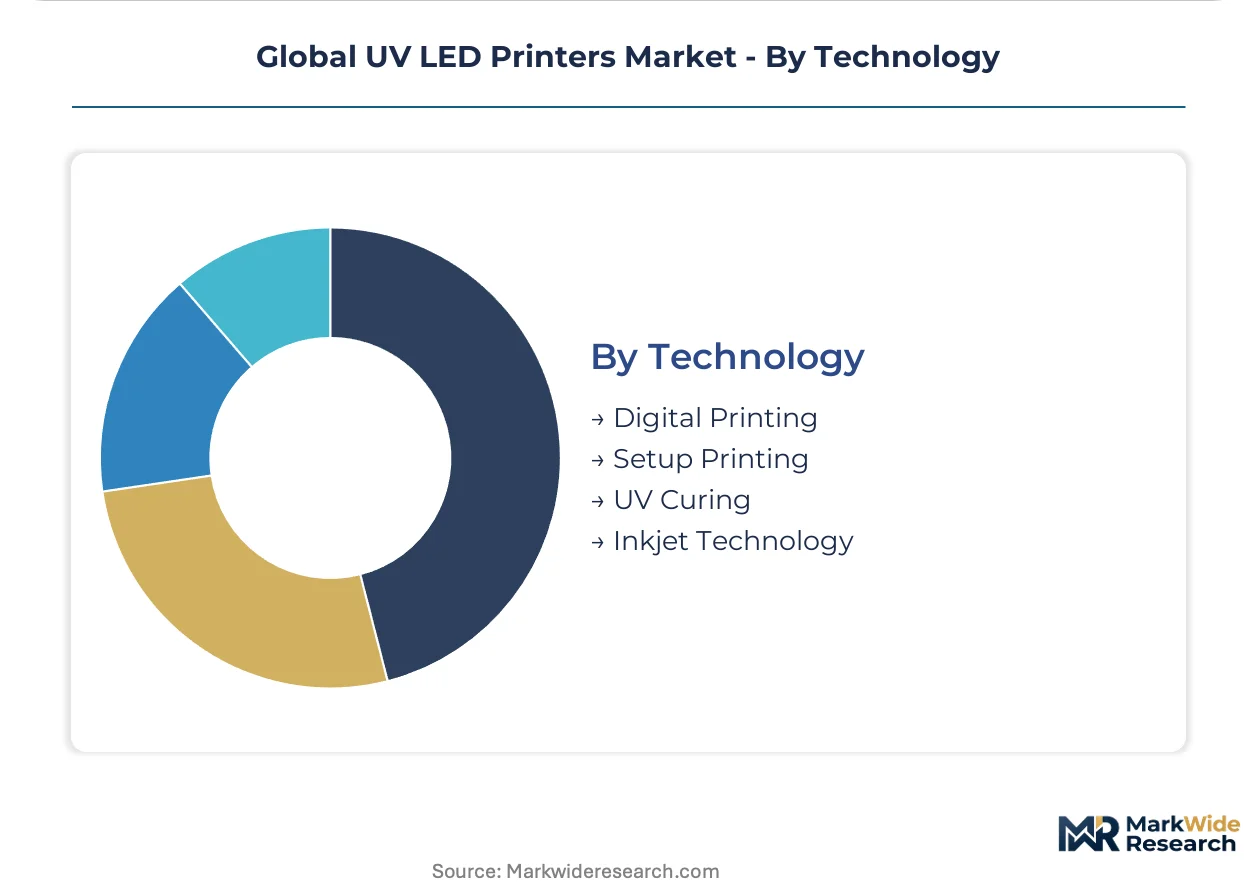
Technology:
Curing subsystem architecture determines total cost of ownership more than imaging engine selection.
- UV Curing:Semiconductor-emitting diode arrays at 365–405 nm wavelengths polymerize inks without mercury arc lamps, eliminating ozone emissions and reducing energy consumption. China's dual carbon goals mandate MEE-enforced mercury-lamp retirement in Guangdong print clusters.
- Inkjet Technology:Piezoelectric drop-on-demand systems deliver variable droplet sizes for resolution-versus-speed tradeoffs in labels and industrial decoration.
- Digital Printing:File-to-output workflows eliminate platemaking and reduce job changeover times for short-run production.
- Setup Printing:Conventional analog preparation methods persist in legacy installations requiring middleware integration for LED spectral profiles.
UV curing leads on regulatory substitution; inkjet technology leads on speed advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Print equipment procurement migrates toward jurisdictions where regulatory enforcement compresses mercury-lamp replacement timelines and energy-efficiency subsidies offset capital costs. Compliance-cost arbitrage steers investment flows across German, Chinese, and North American industrial corridors.
United States
EPA VOC restrictions steer packaging manufacturers toward LED-cured workflows in Chicago and Toronto industrial print corridors. Industrial signage contractors adopt multi-wavelength arrays within compressed replacement cycles. Midwest print service providers bundle design-to-cure contracts to capture margin pools from brand owners.
Germany
EU Green Deal emissions targets accelerate flatbed system procurement among Bavarian and North Rhine-Westphalia signage contractors. REACH Annex XVII governs photoinitiator composition in UV inks, compressing formulation R&D timelines. Stuttgart and Düsseldorf print clusters face mercury-lamp phaseout deadlines by 2025.
China
Dual carbon goals enforced by MEE mandate mercury-lamp retirement in Guangdong and Jiangsu province print clusters. Electronics packaging demand from Shenzhen and Dongguan contract manufacturers drives hybrid UV LED configurations. Shanghai industrial zones prioritize semiconductor curing architectures for smartphone component labeling.
Japan
METI energy-efficiency standards steer commercial printers in Osaka and Nagoya toward subscription-based equipment access models. Compact hybrid systems capture per-page costing structures over capital expenditure approval cycles. Tokyo metropolitan print service networks prioritize substrate versatility premiums.
India
BIS energy-efficiency labeling creates subsidy pathways for LED-cured equipment adoption in Mumbai and Delhi NCR service corridors. Packaging manufacturers modernize in-house production facilities to meet traceability documentation requirements. Commercial print networks in Maharashtra and Gujarat accelerate procurement of rigid-media handling systems.
Global UV LED Printers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in industrial-scale equipment and fragmented competition in mid-cap commercial configurations. Three archetypes dominate: diversified imaging conglomerates leveraging thermal inkjet heritage, precision optics specialists commanding high-throughput flatbed architectures, and compact system fabricators targeting hybrid workflow versatility. Competitive moves concentrate on strategic partnerships for ink formulation R&D and geographic expansion into subsidy-enabled emerging markets.
Within the diversified imaging tier, HP Inc. and Canon Inc. anchor positions through industrial print service contract penetration. Among precision-oriented specialists, Durst Phototechnik and Mimaki Engineering exemplify contrasting geographic emphases—European high-throughput networks versus Japanese commercial printer ecosystems. Roland DG Corporation occupies a position bridging mid-cap versatility requirements with substrate range premiums.
| Leading Market Players |
|---|
| HP Inc. |
| Mutoh Industries |
| Mimaki Engineering |
| Agfa-Gevaert Group |
| Durst Phototechnik |
| Epson Corporation |
| Canon Inc. |
| Xerox Corporation |
| Roland DG Corporation |
| Others |
Value Chain & Pricing Dynamics
Semiconductor diode calibration specialists concentrated in Stuttgart and Osaka command wage premiums that compress margin spreads between premium flatbed systems and economy-tier roll-fed configurations. Labor-cost differentials between German precision-optics clusters and Japanese compact-system fabricators translate directly into pricing-tier stratification across equipment portfolios.
Pricing Analysis
Distributor margin layers absorb 12-18 points of equipment value before reaching print service providers, with direct-to-OEM procurement discounts compressing this spread for volume packaging manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates high-throughput flatbed architectures from compact hybrid systems and entry-level roll-to-roll units. Cost compression in economy tiers is intensifying because ink formulation suppliers consolidate photoinitiator R&D under REACH compliance pressure. Commercial printers in mid-cap networks exhibit highest price sensitivity, while industrial print service providers prioritize substrate versatility over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for 365–405 nm LED arrays compel equipment vendors to qualify suppliers in both Taiwan and South Korea alongside Japanese diode fabricators. Photoinitiator chemistry draws from German and Swiss specialty chemical networks, while precision-optics components hinge on Japanese glass-molding clusters. Single-source vulnerability concentrates in mercury-arc lamp replacement cycles where MEE enforcement deadlines synchronize demand spikes. Distribution runs through authorized dealer networks in industrial print corridors, with direct technical service contracts penetrating large-format signage contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal mercury-lamp phaseout deadlines and China's MEE enforcement timelines create synchronized replacement demand across German and Guangdong print clusters.
For Market Incumbents: Extend flatbed architecture dominance by acquiring photoinitiator formulation expertise ahead of REACH Annex XVII compliance windows. Capacity addition in Stuttgart and Osaka training centers addresses technician scarcity threatening service contract renewals. Vertical integration into low-migration ink development defends margin pools from specialty chemical supplier consolidation. For New Entrants and Emerging Players: Regional ink distributors present partnership pathways into Indian commercial print networks where BIS subsidy eligibility creates procurement leverage. Food-contact packaging applications remain the most penetrable segment given 24-month compliance windows forcing German label manufacturer modernization. Per-page costing structures offer go-to-market differentiation against capital-intensive incumbent sales models. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap hybrid-system fabricators lacking subscription-service infrastructure. Long-term viability centers on recurring revenue attachment rates rather than equipment shipment volumes. Watch LED array sourcing diversification as the inflection indicator separating sustainable platform operators from component-cost exposed assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Photoinitiator Formulation Acquisition | REACH Annex XVII compliance secures food-contact packaging penetration for European label manufacturers. |
| Subscription Service Infrastructure | Per-page costing structures displace capital expenditure cycles among Osaka and Nagoya commercial printers. |
| Multi-wavelength LED Array Development | 365–395 nm substrate versatility captures margin pools from thermal drying ovens in wood decoration segments. |
| Regional Training Center Expansion | Stuttgart and Osaka technician certification programs address scarcity constraining service contract growth. |
| Low-migration Ink R&D Partnership | Dairy and beverage label applications open UV LED penetration beyond industrial signage corridors. |
Study Parameters
Direct dialogue with equipment procurement directors at packaging manufacturers, technical service heads at print service providers, photoinitiator R&D leads at specialty chemical suppliers, and regulatory affairs managers at ink formulation companies grounded qualitative findings. Secondary validation drew from EPA VOC enforcement records, ECHA REACH registration databases, MEE mercury-lamp phaseout notifications, and METI energy-efficiency standard filings. Bottom-up equipment shipment triangulation against top-down print industry capex surveys anchored market sizing.
Installed base projections and revenue forecasts across the analysis window segmented by equipment architecture, end-use application, and regional regulatory cluster. CAGRs derived from replacement cycle compression analysis tied to mercury-lamp retirement mandates and dual carbon enforcement timelines. Industry-specific inputs included photoinitiator toxicity reclassification schedules and BIS subsidy eligibility criteria for energy-efficiency labeling.
Revisions become necessary when REACH Annex XVII expands restricted compound lists, MEE enforcement timelines accelerate, or LED array supply disruptions materialize beyond current dual-sourcing qualifications. Forecasts reflect assumptions regarding regulatory compliance cost pass-through rates and technician training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
NCR Printers Market
Printers
Mobile Printer Market
Printers
Photocopiers Market
Printers
Indonesia Thermal Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
India Inkjet Printer Market
Printers
Inkjet Printers Market
Printers
Copier, MFP and Printer Market
Printers
Mobile Photo Printer Market
Printers
Single Function Printer Market
Printers
Retail Printers and Consumables Market
Printers
Dot Matrix Printer Market
Printers
Continuous Inkjet Printers Market
Printers
Global Ticket Printers Production Market
Printers
Production Printer Market