
 Ink Tank Printer Market | 2026-2036
Ink Tank Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Ink Tank Printer Market Foresight
Subscription-based ink replenishment services is realigning how hardware vendors monetize installed bases. Epson leverages its EcoTank refill program to lock in recurring revenue and reduce customer churn. Canon anchors its competitive stance through backward integration into printhead manufacturing, controlling core component supply. Brother specializes in compact all-in-one configurations for space-constrained small business environments.
An ink tank printer stores liquid ink in large, refillable reservoirs rather than disposable cartridges, typically yielding thousands of pages per refill through continuous ink supply systems with piezoelectric or thermal ejection mechanisms. These devices serve commercial and institutional users requiring high-volume, low-cost-per-page output for documents, marketing materials, and educational resources. All-in-one configurations lead unit shipments by combining print, scan, and copy functions that small businesses and home offices prioritize for capital efficiency. Micro Piezo technology captures margin concentration due to its precision droplet control and compatibility with diverse ink chemistries, while portable segments remain niche with limited industrial application.
EPA Energy Star certification and EU RoHS substance restrictions shape product design requirements for power consumption and material composition across major export destinations. India's BIS mandatory registration scheme for electronic products creates compliance gates that filter non-conforming imports. Stakeholders must monitor how refillable ink standards evolve under Ecodesign regulations in Europe and whether regional e-waste directives extend producer responsibility to tank components and depleted ink bottles.
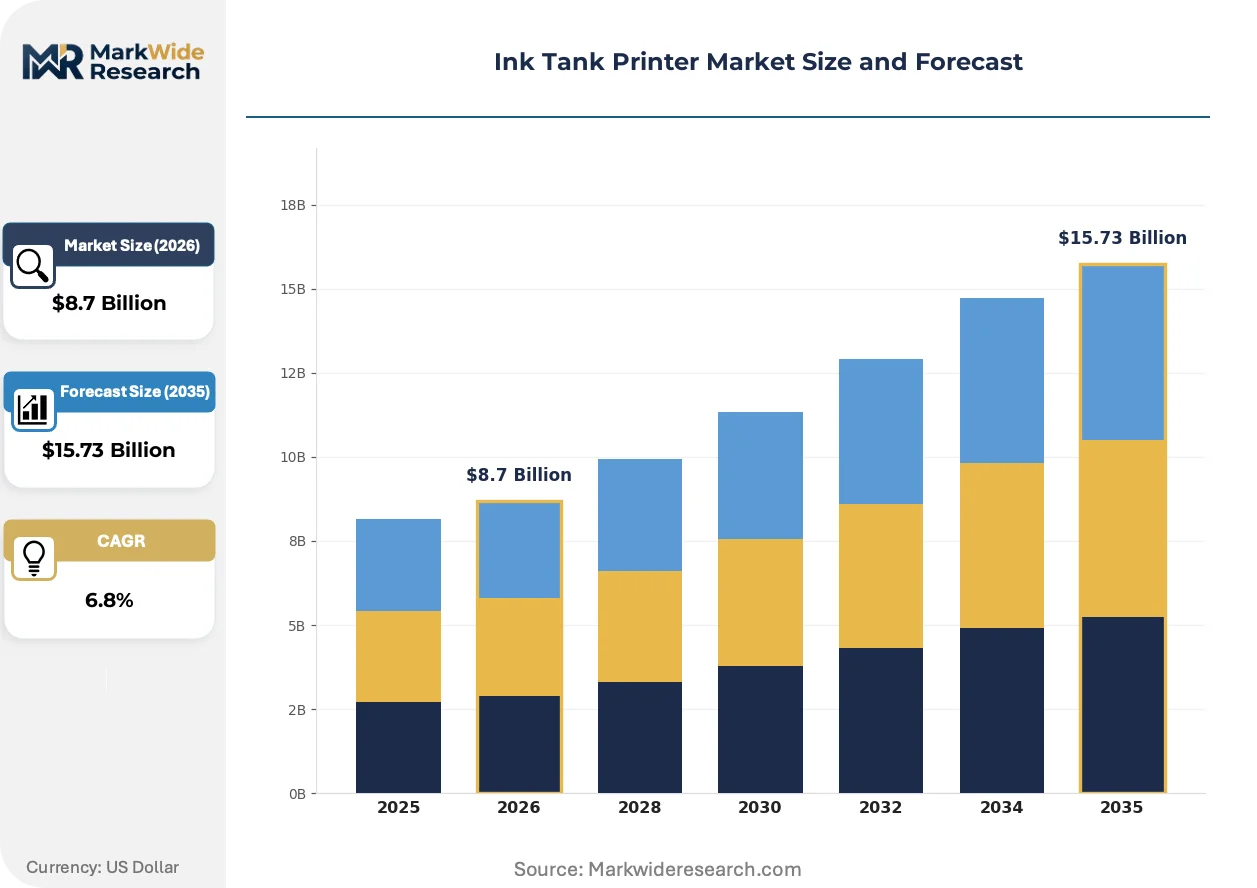
Market Dynamics
Micro Piezo printhead architecture is consolidating technical leadership across ink tank printer portfolios as manufacturers abandon thermal ejection systems to meet India's BIS energy-efficiency mandates and extend printhead longevity. This technology transition is compressing development cycles and forcing component sourcing reconfigurations throughout the supply base.
Growth Catalysts
- India BIS Mandatory Registration:The Bureau of Indian Standards energy-efficiency scheme filters non-conforming imports, creating compliance-driven replacement cycles among institutional buyers upgrading legacy thermal systems.
- Southeast Asian Small Business Expansion:Vietnam and Indonesia home office formations are accelerating hardware procurement as entrepreneurs prioritize capital-efficient all-in-one configurations with low per-page economics.
- Micro Piezo Precision Control:Droplet modulation capabilities enable diverse ink chemistry compatibility, opening textile and packaging applications previously served by industrial printing systems.
Market Restraints
- Piezoelectric Actuator Supply Concentration:Japanese and German precision ceramics manufacturers control high-tolerance piezo element production, creating single-source vulnerability for printhead assembly.
- Silicon Wafer Input Volatility:MEMS fabrication for thermal printhead alternatives faces foundry capacity constraints and commodity pricing swings that compress hardware margins.
- Smartphone Document Scanning Substitution:Mobile OCR applications and cloud storage integration reduce small-volume scanning demand among individual consumers.
Strategic Opportunities
- Vietnam Educational Institution Procurement:Government digitization initiatives and classroom technology budgets are creating concentrated demand for high-volume printing infrastructure in secondary and tertiary institutions.
- Subscription Refill Convergence:Hardware vendors are bundling IoT-enabled tank monitoring with automatic replenishment logistics, transforming transactional hardware sales into recurring revenue relationships.
- EU Ecodesign Refillable Standards:Anticipated regulatory extensions to ink bottle and tank component producer responsibility will favor modular, repairable designs over sealed disposable architectures.
Industry Challenges
- Firmware Security Certification Complexity:Network-connected tank printers require continuous patch validation against evolving cybersecurity frameworks, extending product launch timelines.
- Legacy Thermal Printhead Inventory Stranding:Manufacturers face write-down pressure on thermal ejection component stockpiles as BIS and EPA Energy Star specifications tighten efficiency thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ink Tank Printer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Function, All-in-One, Portable, Large Format Installation: On-premises, Cloud-based, Hybrid, Mobile Technology: Inkjet, Thermal, Micro Piezo, Continuous End User: Home Office, Small Business, Educational Institution, Enterprises |
| Companies Covered | Epson, HP, Canon, Brother, Pantum, Ricoh, Xerox, Lexmark, Sharp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ink Tank Printer Market Shifts & Advancements
Hardware monetization logic is inverting as vendors prioritize installed base lock-in over upfront equipment margins. Three concurrent developments are restructuring competitive positioning and technical roadmaps across the ink tank printer category.
Micro Piezo printhead technology is absorbing the functional requirements previously served by separate thermal subsystems in entry-level hardware. Educational procurement departments in Vietnam and Indonesia are specifying piezo-based units exclusively to reduce classroom downtime from printhead replacement. This absorption is compressing the addressable market for thermal printhead component suppliers and redirecting R&D investment toward piezo material science.
EPA Energy Star certification requirements are tightening standby power consumption thresholds for imaging equipment sold into North American commercial channels. Manufacturers must redesign power management firmware and power supply architectures to maintain retail placement eligibility. Small business-focused product lines face the steepest redesign burden as these SKUs historically prioritized cost minimization over idle-state efficiency.
Subscription-based ink replenishment services are displacing traditional cartridge and bottle retail purchasing among high-volume small business users. Brother and Canon direct-to-customer logistics platforms are capturing recurring revenue streams that previously flowed through office supply distributors. This behavioral shift concentrates most visibly in Indonesia's urban centers where e-commerce penetration and delivery infrastructure density enable reliable automatic replenishment fulfillment.
Ink Tank Printer Market Segmentation
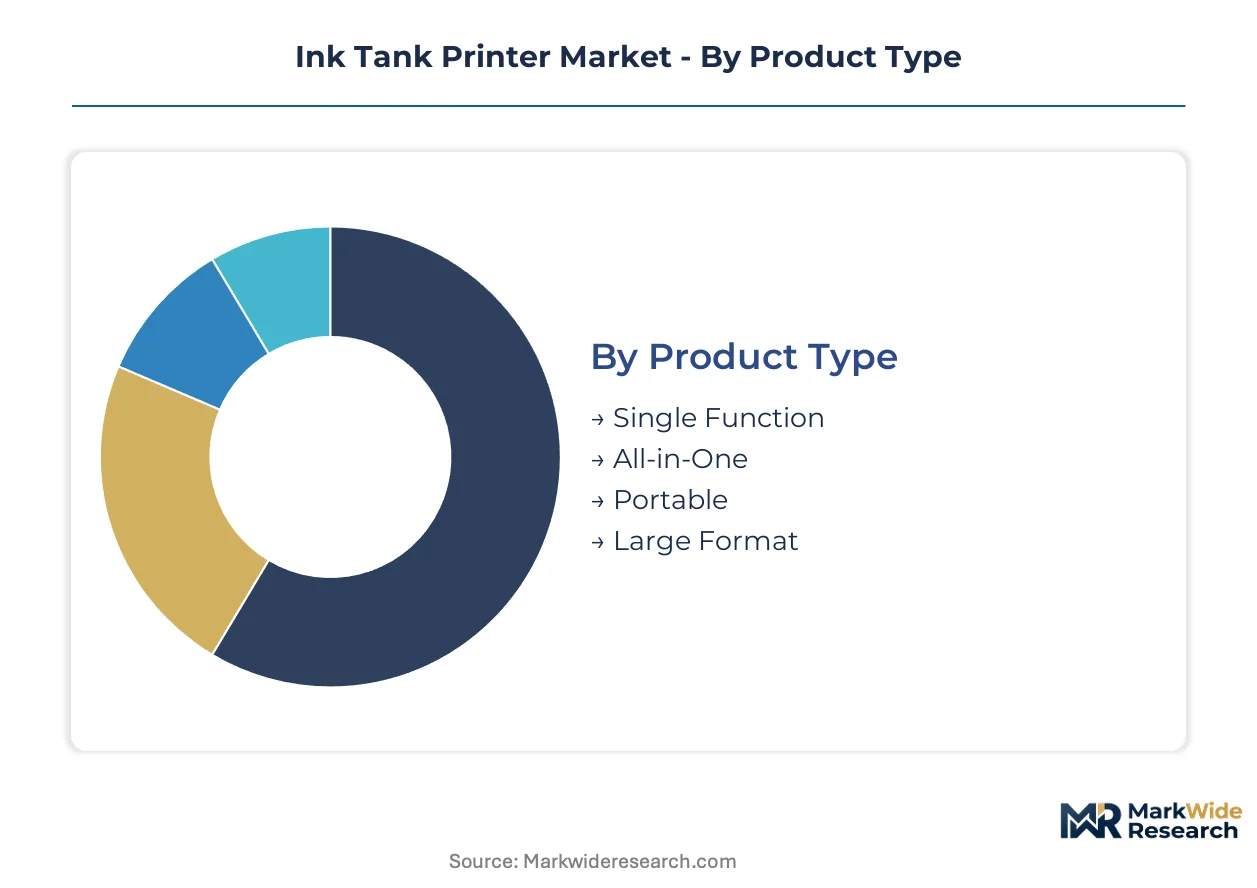
Ink tank printer segmentation reveals how hardware configurations align with distinct operational intensity levels and infrastructure requirements. Product architecture choices determine whether units serve intermittent home use or continuous commercial production environments.
Product Type:
Standalone single-function units address discrete printing workflows, while embedded all-in-one configurations dominate space-constrained deployments where capital efficiency overrides specialized performance.
- All-in-One:Combines print, scan, and copy functions within a single chassis, eliminating separate device procurement for small businesses in Vietnam and Indonesia where floor space commands premium lease rates. Educational institutions specify these configurations to reduce classroom equipment counts and simplify IT support overhead.
- Single Function:Dedicated printing hardware optimized for high-volume document output without scanning or copying subsystems. Enterprises deploy these units in centralized print rooms where specialized MFP fleets handle imaging tasks separately.
- Portable:Battery-powered compact units designed for field documentation and mobile workforce deployment.
- Large Format:Wide-carriage systems accommodating architectural drawings, marketing banners, and technical schematics up to 44-inch widths.
Volume placements concentrate in All-in-One configurations; the faster expansion belongs to Large Format as marketing agencies and construction firms upgrade from outsourced printing.
Installation:
Deployment architecture determines how ink monitoring, job queuing, and replenishment logistics integrate with customer IT infrastructure and vendor service platforms.
- On-premises:Local server-managed print infrastructure with direct network attachment, preferred by enterprises maintaining air-gapped security environments. Financial institutions in India mandate on-premises control to satisfy BIS data localization expectations for audit trail retention.
- Cloud-based:Internet-connected devices transmitting usage telemetry to vendor-managed platforms for predictive replenishment. Small businesses in Indonesia's urban centers adopt these configurations to enable automatic ink delivery without inventory management overhead.
- Hybrid:Mixed architecture combining local job processing with cloud-based analytics and supply chain integration.
- Mobile:Direct smartphone or tablet pairing via Bluetooth or Wi-Fi Direct, bypassing traditional network infrastructure.
Cloud-based installations are gaining share fastest in Southeast Asian small business channels; on-premises retains dominance in regulated enterprise environments.
Technology:
Printhead ejection mechanisms differentiate hardware along precision, speed, and ink chemistry compatibility vectors, with energy efficiency mandates accelerating architectural transitions.
- Micro Piezo:Piezoelectric actuator-driven droplet ejection enabling variable droplet sizes and diverse ink formulations including textile and UV-curable chemistries. India's BIS energy-efficiency mandates are institutionalizing this technology across government and educational procurement specifications, displacing thermal alternatives.
- Thermal:Resistive heating element bubble-jet ejection, historically dominant in entry-level hardware due to lower manufacturing cost. Inventory stranding risk is mounting as EPA Energy Star standby power thresholds tighten and BIS registration schemes filter non-conforming imports.
- Inkjet:General category encompassing both piezo and thermal implementations with continuous ink supply system integration.
- Continuous:Industrial-grade continuous inkjet systems for high-speed production line marking and coding applications.
Micro Piezo captures the dominant placement volume; Thermal is contracting fastest under regulatory pressure.
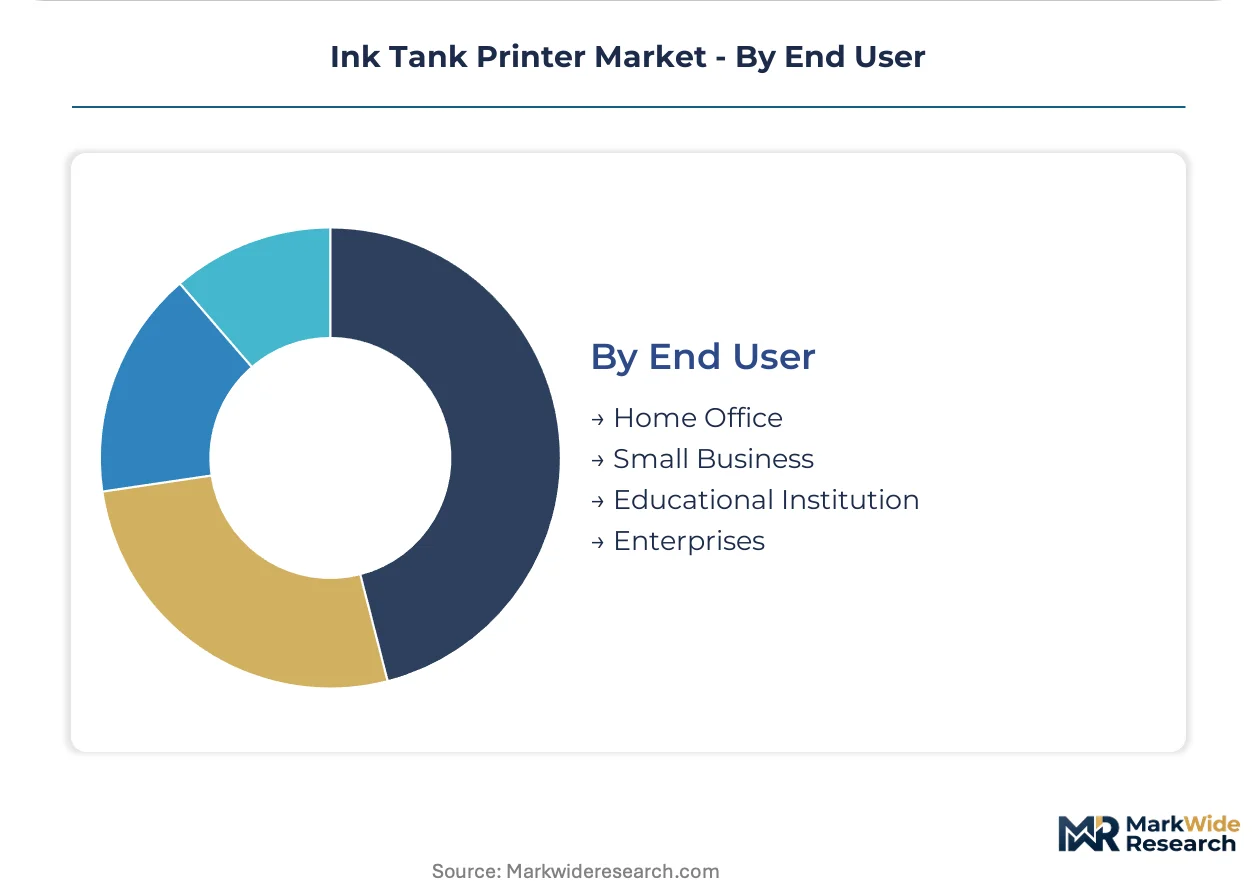
End User:
Customer scale and usage intensity shape hardware specifications, with procurement authority residing differently across consumer, institutional, and corporate buying centers.
- Small Business:Owner-operated entities prioritizing per-page economics over acquisition cost, typically selecting all-in-one configurations with subscription replenishment services. Vietnam's home office formations and Indonesia's entrepreneurial expansion are concentrating demand in this segment.
- Educational Institution:K-12 schools and universities requiring high-volume, low-downtime infrastructure for administrative documents and classroom materials. Government digitization budgets in Vietnam and Indonesia are creating concentrated procurement waves for secondary and tertiary institutions.
- Home Office:Individual remote workers and freelancers with intermittent printing needs and space constraints.
- Enterprises:Large organizations with centralized IT management, security compliance requirements, and managed print service contracts.
Small Business generates the highest unit placement volume; Educational Institution is climbing the fastest as government technology budgets expand across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Japan and China contrasts with consumption acceleration across Southeast Asian markets. India's regulatory mandates are redirecting procurement flows toward energy-efficient hardware configurations. Vietnam and Indonesia dominate emerging demand formation.
India
Government digitization programs and educational infrastructure upgrades drive institutional procurement volumes. BIS mandatory registration schemes filter thermal printhead imports, accelerating Micro Piezo adoption across public sector tenders. Maharashtra and Karnataka host concentrated distribution networks serving SME clusters in Mumbai and Bangalore.
Vietnam
Home office formations and entrepreneurial expansion create sustained small business hardware demand. Government classroom technology budgets channel investment toward secondary and tertiary educational institutions. Ho Chi Minh City and Hanoi anchor procurement concentration for all-in-one configurations with subscription replenishment services.
Indonesia
E-commerce penetration enables automatic ink replenishment fulfillment across urban centers. Educational digitization initiatives expand hardware deployment in Jakarta and Surabaya metropolitan areas. Javan manufacturing zones supply regional assembly operations for Southeast Asian distribution.
United States
EPA Energy Star standby power thresholds tighten eligibility for commercial channel placement. Small business cost sensitivity sustains demand for capital-efficient all-in-one configurations. Texas and California host concentrated reseller networks serving distributed home office formations.
Germany
EU Ecodesign regulations anticipate extended producer responsibility for refillable ink components. Precision engineering clusters in Baden-Württemberg supply piezoelectric actuator components to Asian printhead manufacturers. Bavarian industrial users specify high-durability hardware for continuous production environments.
Ink Tank Printer Market Competitive Landscape
Capital-heavy producers with captive printhead manufacturing compete with asset-light assemblers sourcing components through merchant markets. Market structure tilts toward consolidated leadership among vertically integrated imaging specialists. Three archetypes dominate: precision printhead manufacturers controlling core component supply, subscription-platform operators monetizing installed bases through recurring replenishment, and compact-configuration specialists targeting space-constrained environments. Dominant competitive moves include backward integration into MEMS fabrication and geographic expansion through direct-to-customer logistics platforms.
Within the precision-component tier, Epson exemplifies captive printhead manufacturing with proprietary Micro Piezo architecture. Canon occupies a position as an integrated imaging systems producer with backward control over optical and mechanical subsystems. Brother represents the compact-configuration archetype, specializing in all-in-one formats for small business deployment. These three anchors demonstrate how technical differentiation and service-model innovation reshape competitive positioning.
| Leading Market Players |
|---|
| Epson |
| HP |
| Canon |
| Brother |
| Pantum |
| Ricoh |
| Xerox |
| Lexmark |
| Sharp |
| Others |
Supply & Pricing Matrix
Micro Piezo printhead technology adoption across Indian educational procurement is simultaneously compressing thermal printhead residual value and concentrating component sourcing among Japanese and German precision ceramics manufacturers. This dual restructuring elevates captive printhead producers' pricing power while forcing merchant-market assemblers into cost-down negotiations for piezoelectric actuator supply.
Pricing Analysis
Cost-down pressure on entry-level thermal hardware accelerates as BIS registration schemes and EPA Energy Star standby thresholds filter non-conforming imports from institutional tenders. Pricing stratifies across Micro Piezo premium tiers, standard all-in-one configurations, and economy single-function units, with certification grade and volume scale as primary differentiation drivers. Margin tightening in thermal segments reflects inventory stranding risk among component suppliers. Small business buyers in Vietnam and Indonesia exhibit highest price sensitivity, prioritizing per-page economics over acquisition cost, while Indian government tenders show lowest sensitivity due to total-cost-of-ownership procurement mandates.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong anchor hub-and-spoke fulfillment patterns across Southeast Asian small business channels. Manufacturing concentrates in Japan, China, and Vietnam, with precision piezoelectric actuators drawing from German and Japanese ceramics specialists. Silicon wafer inputs for MEMS fabrication and specialty ink chemistries represent critical dependencies. Single-source vulnerability in piezoelectric actuator supply creates structural risk for printhead assembly operations. Distribution runs through direct-to-customer logistics platforms and traditional office supply resellers, with subscription-enabled automatic replenishment gaining fastest in Indonesian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in precision piezoelectric actuator manufacturing prop hardware pricing, with Japanese and German component specialists operating at effective capacity limits.
For Market Incumbents: Deepen backward integration into MEMS fabrication and piezoelectric material science to secure captive actuator supply against merchant-market shortage. Prioritize certification investment for BIS registration and EPA Energy Star compliance to defend institutional tender eligibility. Consolidate channel control through direct-to-customer subscription platforms, displacing traditional distributor relationships in Indonesian and Vietnamese urban markets. For New Entrants and Emerging Players: Launch via cloud-based installation and automatic replenishment bundling to bypass established reseller infrastructure. Target Vietnamese educational institution procurement as the most penetrable segment, where government digitization budgets concentrate demand and specification standards remain fluid. Emphasize compact all-in-one configurations with localized firmware and regional language support as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in precision component specialists with captive piezoelectric actuator technology and established Asian OEM relationships. Long-term viability favors vertically integrated producers controlling printhead architecture and ink chemistry compatibility. Watch BIS registration scheme expansion to additional product categories as the signal indicating accelerated Micro Piezo adoption and thermal asset obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Epson and Canon secure captive piezoelectric actuator supply against Japanese and German component concentration. |
| Subscription Refill Platform Expansion | Brother and Canon transform transactional hardware sales into recurring revenue through IoT-enabled tank monitoring. |
| BIS Certification Investment | Hardware vendors maintain Indian institutional tender eligibility as energy-efficiency mandates tighten. |
| Compact All-in-One Configuration Development | Brother targets Vietnamese and Indonesian small business space constraints with capital-efficient multifunction designs. |
| Direct-to-Customer Logistics Buildout | Canon and Brother bypass traditional distributors in Indonesian urban centers with automatic replenishment fulfillment. |
Research Methodology
Document review covered regulatory filings from EPA Energy Star and India's BIS, trade data from customs authorities, and component supplier disclosures, complemented by interviews with printhead engineering directors, procurement leads at educational institutions, channel sales managers, and aftermarket service heads. Primary fieldwork across Vietnam, Indonesia, and India validated secondary estimates. Bottom-up unit shipment analysis triangulated against top-down market value reconstruction.
Cross-referencing historical adoption curves with expert panel input on technology transition timing informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, installation architecture, printhead technology, and end-user scale, with regional regulatory cluster as an additional ink tank printer-specific dimension. CAGRs derived from installed base growth and replacement cycle compression. Forecast inputs incorporated BIS registration scheme expansion probability and Micro Piezo yield improvement trajectories.
Regulatory enforcement variance, piezoelectric actuator supply disruption, and smartphone document scanning substitution acceleration are the dominant revision risks to shipment and value projections. Forecasts reflect documented assumptions on technology transition speed and institutional procurement budget continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Inkjet Printing Market
Printers
Thermal Printer Market
Printers
India Inkjet Printer Market
Printers
Indonesia Thermal Printer Market
Printers
Retail Printers and Consumables Market
Printers
Nanographic Printing Market
Printers
Global UV LED Printers Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Global Inkjet Coders Market
Printers
Refurbished Printers Market
Printers
Multi-Functional Printer Market
Printers
Portable Printer Market
Printers
Continuous Inkjet Printers Market
Printers
Printer Ribbons Market
Printers
Inkjet Printers Market
Printers
Thermal Inkjet Printer Market