
 Electrophotographic Printing Market | 2026-2036
Electrophotographic Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophotographic Printing Market Intelligence
Commercial packaging converters is bifurcating from traditional document production houses as the dominant buyer archetype in electrophotographic equipment procurement. HP Inc. leverages its Indigo platform to dominate narrow-web label and flexible packaging segments with liquid electrophotography. Canon Inc. anchors its position in high-volume transactional and direct-mail applications through imagePRESS and varioPRINT lines. Landa Corporation competes at the premium tier with nanographic technology that bridges offset quality and digital turnaround times.
Electrophotographic printing employs a photoconductive drum or belt that receives a latent electrostatic image from a laser or LED array, attracts oppositely charged toner particles, and transfers the developed image to paper or substrate under heat and pressure, typically operating at resolutions between 600 and 2400 dots per inch with fusing temperatures ranging from 120°C to 180°C depending on toner chemistry. Its primary commercial purpose is to enable variable-data, short-to-medium-run printing with minimal makeready compared to analog lithographic processes. Laser technology leads installed base volumes but LED arrays are gaining share in entry-level and mid-production systems due to fewer moving optical components and lower energy draw. Toners represent the largest recurring revenue pool as polymerized and chemically produced formulations displace conventional ground powders. Packaging applications are expanding fastest among application segments as brand owners seek versioned carton and label runs for regional marketing campaigns.
REACH registration requirements govern toner resin and pigment chemistries across European manufacturing and import channels, while EPA New Source Performance Standards shape emissions profiles for U.S.-based production facilities. The EU F-Gas Regulation and evolving Ecodesign requirements for imaging equipment are accelerating hardware redesign cycles toward lower-energy fusing and reduced standby consumption. Stakeholders must monitor how pending per- and polyfluoroalkyl substance restrictions in toner additives reshape formulation roadmaps and supplier qualification timelines.
Market Dynamics
Polymerized toner chemistry is displacing conventional ground-powder formulations as REACH chemical restrictions and EU Green Deal decarbonization mandates force hardware redesigns toward lower-fusing-temperature systems across European manufacturing corridors.
Growth Catalysts
- EU Green Deal industrial decarbonization:German print service providers are retrofitting electrophotographic fleets to meet binding emissions targets, creating replacement demand for energy-efficient fusing systems.
- Short-run packaging versioning:Brand owners in consumer goods are demanding regionally customized carton and label runs that analog lithography cannot economically fulfill.
- LED array technology:Entry-level and mid-production system manufacturers are adopting solid-state imaging engines for reduced energy draw and fewer moving optical components.
Market Restraints
- Petrochemical input volatility:Toner resin formulations depend on styrene-acrylic feedstocks subject to crude oil price swings and European naphtha supply disruptions.
- F-Gas Regulation compliance costs:EU-imposed restrictions on fluorinated greenhouse gases in fusing subsystems are extending hardware redesign cycles and qualification timelines.
- Offset quality substitution ceiling:Premium commercial print buyers in publishing and luxury packaging still specify sheet-fed offset for runs exceeding ten thousand impressions.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Domestic production-linked incentives are attracting electrophotographic component assembly for export to Middle East and Southeast Asian markets.
- Nanographic-inkjet convergence:Hybrid systems combining electrophotographic precision with aqueous inkjet substrate flexibility are opening corrugated board applications previously closed to digital.
- CSRD supply-chain disclosure mandates:Large EU corporates must now report Scope 3 emissions from printed materials, accelerating outsourcing to certified sustainable print service providers.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation laboratories lack sufficient expertise in chemically produced toner particle engineering to meet accelerated OEM roadmaps.
- Per- and polyfluoroalkyl substance transition timelines:Pending restrictions on PFAS additives in toner formulations are forcing emergency supplier qualification processes with incomplete regulatory clarity.
- Legacy fleet integration friction:Print service providers operating mixed-vendor environments face workflow automation gaps when connecting new low-temperature fusing systems to existing finishing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophotographic Printing Market |
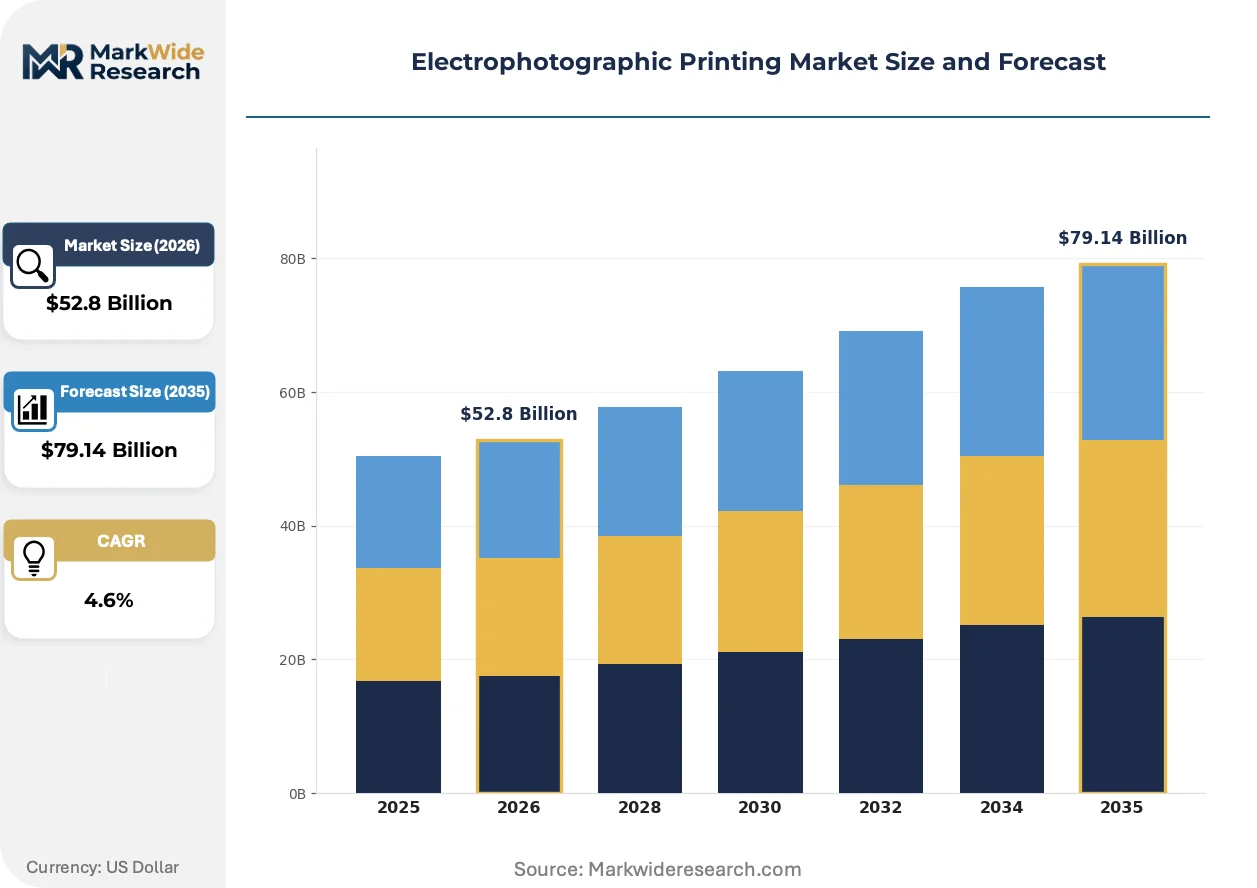
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printers, Toners, Imaging Drums, Printing Plates Application: Commercial Printing, Labeling, Packaging, Document Production End User: Publishing, Retail, Healthcare, Education Technology: Laser, LED, Hybrid, Digital |
| Companies Covered | Landa Corporation, Eastman Kodak Company, HP Inc., Flint Group, Fuji Xerox Co. Ltd., A B Graphic International Ltd., Canon Inc., Xerox, Xeikon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophotographic Printing Market Strategic Shifts & Innovations
Electrophotographic technology trajectories are diverging between high-volume transactional document systems and specialized packaging production platforms as environmental compliance and substrate versatility reshape hardware development priorities.
Liquid electrophotography is bifurcating narrow-web label production from conventional dry-toner flexible packaging applications. Premium brand owners in cosmetics and pharmaceuticals are specifying liquid toner systems for metallic and security substrates that dry formulations cannot reliably image. This technology division is compressing equipment procurement cycles as converters maintain parallel capabilities for different contract types.
REACH registration requirements for toner resin and pigment chemistries are tightening cross-border manufacturing and import channels across European Economic Area member states. ECHA substance evaluation processes are extending formulation lock-down periods by eight to fourteen months for new polymerized chemistries. German and Dutch chemical suppliers are accelerating in-house toxicology testing to preserve qualification pipelines for imaging equipment OEMs.
Versioned campaign procurement is consolidating print buying authority from decentralized marketing departments to centralized procurement functions with sustainability mandates. Consumer packaged goods corporations are unbundling creative production from manufacturing execution, awarding electrophotographic contracts based on verified carbon footprint per thousand impressions. This behavioral shift is most visible in Nordic markets where corporate disclosure requirements under CSRD have advanced ahead of continental implementation timelines.
Electrophotographic Printing Market Segmentation
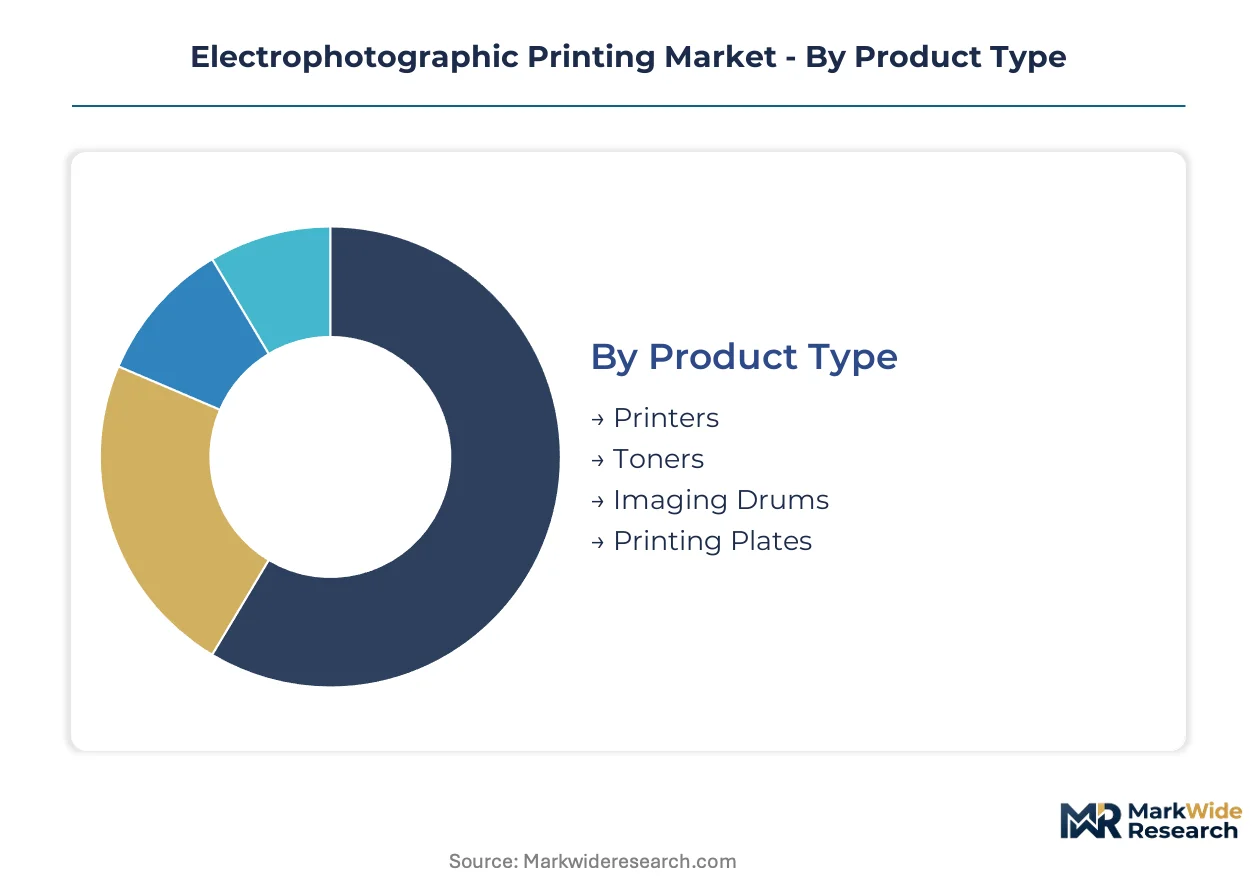
Electrophotographic printing equipment and consumables fragment across hardware generations, substrate requirements, and regulatory compliance tiers. Understanding these divisions reveals where OEMs capture recurring revenue versus one-time equipment sales.
Product Type:
Margin pools concentrate in consumables and replacement cycles rather than initial hardware sales.
- Printers:Hardware platforms span entry-level desktop units to industrial web-fed systems with automated finishing integration. German print service providers are retrofitting fleets to meet EU Green Deal decarbonization targets, accelerating replacement demand for lower-fusing-temperature configurations.
- Toners:Polymerized and chemically produced formulations now displace conventional ground powders as REACH chemical restrictions tighten resin and pigment chemistries. This segment captures the largest recurring revenue pool through volume-based supply contracts with commercial converters.
- Imaging Drums:Photoconductive components require periodic replacement based on impression counts and environmental operating conditions.
- Printing Plates:Specialty plates enable electrophotographic imaging on non-paper substrates for flexible packaging applications.
Printers hold installed capacity. Toners are rotating up the share rankings.
Application:
Application mix determines fusing temperature requirements, substrate handling complexity, and regulatory exposure.
- Commercial Printing:Transactional documents, direct mail, and marketing collateral dominate impression volumes. Retail brand owners are demanding versioned campaign materials with verified carbon footprints per thousand impressions, shifting procurement toward certified sustainable print service providers.
- Packaging:Short-run corrugated and flexible packaging jobs are expanding fastest as analog lithography cannot economically fulfill regional marketing campaigns. REACH restrictions on toner formulations and volatile organic compound limits are pushing converters toward polymerized chemistries for food-contact applications.
- Labeling:Narrow-web production for pharmaceuticals and cosmetics requires metallic and security substrate compatibility.
- Document Production:High-volume transactional printing for financial and government sectors emphasizes reliability and archival permanence standards.
Commercial Printing anchors current volume. Packaging is gaining share fastest.
End User:
End-user concentration varies by compliance maturity and outsourcing propensity.
- Publishing:Book and periodical producers balance run-length economics against digital distribution substitution.
- Retail:Brand owners unbundle creative production from manufacturing execution, awarding contracts based on sustainability verification.
- Healthcare:Pharmaceutical labeling demands traceability serialization and tamper-evident features.
- Education:Institutional procurement emphasizes total cost of ownership over specialized substrate capabilities.
Publishing retains legacy infrastructure. Retail is climbing the fastest.
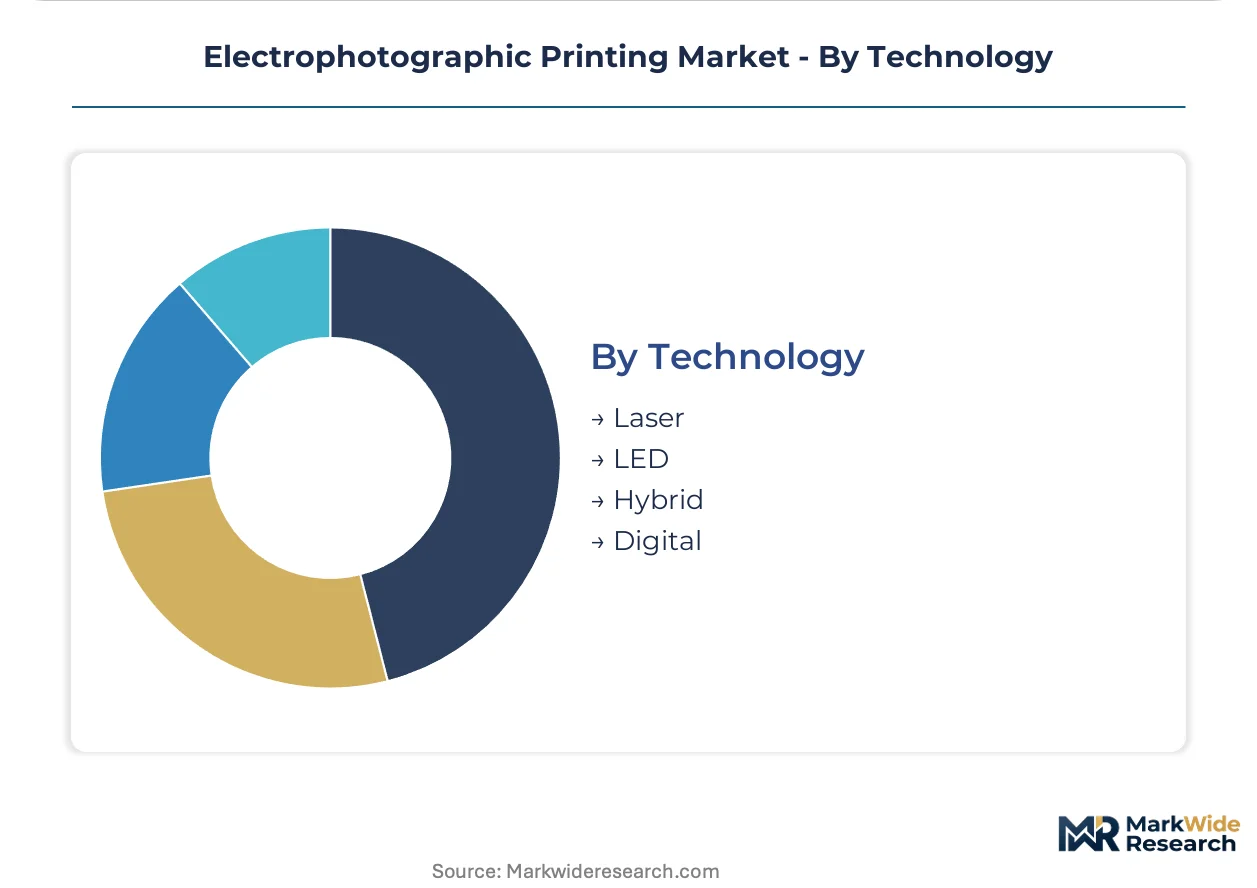
Technology:
Technology selection determines energy draw, optical component count, and integration flexibility.
- Laser:Traditional laser scanning systems dominate high-speed transactional and direct-mail applications through established reliability profiles.
- LED:Solid-state imaging arrays are gaining share in entry-level and mid-production systems due to reduced energy consumption and fewer moving optical components.
- Hybrid:Converged platforms combine electrophotographic precision with aqueous inkjet substrate flexibility for corrugated board applications.
- Digital:Pure digital workflows integrate variable-data capabilities with automated prepress elimination.
Laser maintains installed base dominance. LED is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites the Netherlands' position as a European toner resin distribution hub, with specialized tanker terminals feeding polymerization plants across the Rhine corridor.
Germany
Print service providers in Bavaria and North Rhine-Westphalia are retrofitting electrophotographic fleets to meet binding EU Green Deal industrial decarbonization targets. The F-Gas Regulation is extending hardware redesign cycles for fusing subsystems manufactured in Stuttgart and Dresden industrial clusters. Chemical suppliers in Leverkusen and Ludwigshafen are accelerating in-house toxicology testing to preserve REACH qualification pipelines for imaging equipment OEMs.
United States
Commercial packaging converters in the Midwest and Southeast are expanding electrophotographic capacity for short-run corrugated jobs serving regional brand owner campaigns. EPA New Source Performance Standards shape emissions profiles for toner production facilities along the Gulf Coast petrochemical corridor. The Chicago and Dallas-Fort Worth metro areas concentrate print service provider consolidation activity as procurement functions centralize sustainability verification requirements.
China
Domestic OEMs are scaling polymerized toner manufacturing for export to Southeast Asian packaging converters. MIIT energy efficiency standards for imaging equipment are accelerating LED array adoption in mid-production systems manufactured in the Yangtze River Delta. Shenzhen and Dongguan industrial parks host component assembly operations supplying Middle East and African markets.
India
The PLI scheme for electronics manufacturing is attracting electrophotographic component assembly for re-export to Gulf Cooperation Council countries. BIS certification requirements for imaging equipment are extending qualification timelines for imported hardware platforms. Tamil Nadu and Karnataka industrial corridors concentrate domestic production capacity for toner cartridge remanufacturing operations.
Japan
Precision imaging component manufacturers in the Nagoya and Osaka industrial zones supply photoconductive drum assemblies to global OEMs. METI carbon neutrality roadmaps for industrial equipment are driving fusing subsystem innovation toward lower-temperature operation. Yokohama and Kobe port infrastructure supports specialized chemical import channels for polymerized toner resin formulations.
Electrophotographic Printing Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base concentrates around three to five integrated imaging equipment platforms with substantial recurring consumables revenue streams. Strategic archetypes span full-stack OEMs controlling hardware and chemistry, component specialists supplying photoconductive assemblies, and chemical formulators licensing polymerized toner IP. Competitive moves center on portfolio diversification into packaging substrates and geographic expansion through regional assembly partnerships.
Within the premium technology tier, Landa Corporation and HP Inc. occupy positions bridging offset quality benchmarks with digital workflow flexibility. Canon Inc. anchors the high-volume transactional segment through established reliability profiles in direct-mail and document production. Eastman Kodak Company and Xerox represent legacy platform specialists navigating transitions toward lower-fusing-temperature configurations and polymer chemistry roadmaps. Fuji Xerox Co. Ltd. exemplifies the regional joint-venture structure common in Japanese imaging equipment markets.
| Leading Market Players |
|---|
| Landa Corporation |
| Eastman Kodak Company |
| HP Inc. |
| Flint Group |
| Fuji Xerox Co. Ltd. |
| A B Graphic International Ltd. |
| Canon Inc. |
| Xerox |
| Xeikon |
| Others |
Cost & Logistics Intelligence
Polymerized toner chemistry displacing conventional ground-powder formulations simultaneously redraws supply geography toward German and Dutch chemical corridors and compresses pricing power for legacy resin suppliers locked into higher-fusing-temperature product lines. This substitution dynamic concentrates procurement leverage among converters qualifying lower-temperature systems under EU Green Deal mandates.
Pricing Analysis
Volume-discount tiering structures dominate consumables contracting, with polymerized toner formulations commanding premium positioning against commodity ground powders. Price differentiation hinges on REACH compliance certification and fusing-temperature performance grade, with certified low-temperature chemistries capturing margin premiums. Cost compression in standard-grade toners is intensifying as Chinese resin production scales for Southeast Asian export markets. Mid-volume print service providers exhibit highest price sensitivity, while premium packaging converters prioritize verified carbon footprint metrics over unit cost.
Supply Chain Analysis
Strategic stockpiling of styrene-acrylic feedstocks characterizes converter procurement behavior amid petrochemical price volatility, contrasting with just-in-time imaging drum replenishment. Manufacturing concentrates in Germany, the Netherlands, and China, with polymerization plants clustering along the Rhine corridor fed by Rotterdam chemical terminals. The supply chain draws from crude oil derivatives and specialized pigment imports, exposing participants to naphtha supply disruptions and single-source vulnerabilities in photoconductive coating chemicals. Distribution runs through authorized OEM channels and independent remanufacturing networks serving price-sensitive education and government segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion opportunity as short-run packaging versioning penetrates brand owner procurement functions previously captive to analog lithography economics.
For Market Incumbents: Secure polymer chemistry talent pools in Leverkusen and Ludwigshafen industrial clusters to defend formulation roadmaps against REACH qualification delays. Lock in long-term resin supply agreements with Rotterdam-terminal suppliers to mitigate petrochemical input volatility threatening margin stability in toner consumables.
For New Entrants and Emerging Players: Lead with LED array imaging engines targeting mid-production packaging converters in India PLI scheme corridors, where domestic assembly incentives reduce capital barriers. Emphasize aqueous substrate compatibility as the go-to-market wedge against established dry-toner incumbents in corrugated board applications.
For Investors and Strategic Acquirers: Capital is best deployed toward component specialists controlling photoconductive drum assembly capabilities in Nagoya industrial zones, where precision manufacturing expertise creates durable competitive moats. Monitor PFAS regulatory clarity from ECHA as the critical inflection signal for emergency supplier qualification timelines and stranded chemistry asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymerized Toner Capacity Expansion | REACH-compliant resin production in German chemical corridors secures qualification pipelines for EU OEMs. |
| LED Array Platform Integration | Solid-state imaging reduces energy draw for print service providers retrofitting under EU Green Deal mandates. |
| Backward Integration into Styrene-Acrylic Feedstocks | Captive resin supply insulates margin stability from naphtha price volatility in European petrochemical markets. |
| Long-term Supply Agreement with Rotterdam Terminals | Specialized chemical handling infrastructure underwrites just-in-time polymerization feedstock security. |
| Joint Venture for India PLI Assembly | Domestic component production accesses re-export channels to Gulf Cooperation Council packaging converters. |
Research Approach
Initial hypotheses were tested against primary input from electrophotographic equipment procurement managers, polymer chemistry R&D directors, commercial packaging converter operations heads, and sustainability compliance officers at brand owner corporations, then refined through secondary validation against SEC 10-K filings from listed imaging equipment OEMs, ECHA substance registration databases, EU customs trade statistics for toner resin categories, and MIIT energy efficiency standard disclosures. Bottom-up impression volume modeling and top-down equipment installed base estimates were triangulated to constrain variance boundaries.
Variance decomposition across the projection horizon isolates volume drivers by hardware generation, substrate requirement tier, and regulatory compliance category, with segmentation dimensions spanning laser versus LED versus hybrid imaging technology, commercial printing versus packaging versus labeling application mix, and polymerized versus conventional toner chemistry grade. CAGRs were derived from logistic adoption curves fitted to replacement cycle data and fusing-temperature configuration transition rates, incorporating EU F-Gas Regulation compliance cost trajectories and CSRD supply-chain disclosure mandate adoption timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or abrupt PFAS restriction acceleration would require recalibration. Forecasts reflect documented assumptions regarding polymer chemistry qualification timelines and LED array cost reduction curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Inkjet Printing Market
Printers
Inkjet Printers Market
Printers
Production Printer Market
Printers
Thermal Inkjet Printer Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Multi-Functional Printer Market
Printers
Continuous Inkjet Printers Market
Printers
Global Ticket Printers Production Market
Printers
Copier, MFP and Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Dot Matrix Printer Market
Printers
Ink Tank Printer Market
Printers
NCR Printers Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Aerosol Printing and Graphics Market
Printers
Portable Printer Market