
 Global Inkjet Coders Market | 2026-2036
Global Inkjet Coders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inkjet Coders Market Outlook
Pharmaceutical packaging is recalibrating demand composition as serialization deadlines tighten across major economies. Videojet Technologies Inc. leverages its North American service infrastructure to anchor pharmaceutical contracts. Domino Printing Sciences plc. competes through ink chemistry R&D intensity in solvent-based formulations. Markem-Imaje dominates European dairy and beverage installations with integrated print-and-apply systems.
Inkjet coders are non-contact digital printing devices that propel electrically charged ink droplets through precision nozzles at velocities exceeding 50 m/s to imprint batch codes, expiration dates, and traceability data onto substrates ranging from porous cardboard to glossy plastics. Continuous inkjet technology leads unit shipments due to its tolerance of high-speed production lines and harsh industrial environments. Thermal inkjet is displacing legacy systems in electronics manufacturing where 300+ dpi resolution supports miniature component marking. Piezoelectric inkjet occupies premium niches in specialty pharmaceutical packaging requiring UV-curable and edible ink compatibility.
The US FDA enforces traceability requirements that mandate machine-readable codes on pharmaceutical packaging, directly shaping equipment procurement specifications. The EU Falsified Medicines Directive and REACH chemical compliance force ink reformulation investments that filter down to coder hardware compatibility. China's NMPA serialization rules and GB standards for food contact materials add parallel compliance layers for multinational suppliers. Stakeholders must monitor divergence between regional ink chemistry approvals and printhead durability claims when configuring global product platforms.
Market Dynamics
Pharmaceutical serialization mandates are compressing equipment replacement cycles and forcing hardware-ink compatibility investments across three continents. The EU Falsified Medicines Directive and US Drug Supply Chain Security Act have created synchronized compliance deadlines that override typical capital expenditure planning.
Growth Catalysts
- Serialization mandates:The EU Falsified Medicines Directive and US Drug Supply Chain Security Act mandate machine-readable traceability codes on pharmaceutical packaging. These regulations force packaging line retrofits and accelerate replacement of legacy marking equipment.
- Food contact material rules:China's GB standards and EU REACH compliance requirements are driving ink reformulation investments. Edible and UV-curable ink compatibility is expanding coder deployment into dairy and confectionery segments.
- Electronics miniaturization:Thermal inkjet systems achieving 300+ dpi resolution are penetrating semiconductor and component marking applications. This technology shift opens displacement opportunities in precision manufacturing clusters.
Market Restraints
- Printhead supply concentration:Precision nozzle manufacturing concentrates among Japanese and German component suppliers. Geographic concentration creates vulnerability to regional logistics disruptions and extended lead times.
- Solvent ink chemistry costs:Volatile organic compound formulations face escalating raw material price pressure. MEK and acetone feedstock volatility directly impacts operational expenditure planning for high-volume users.
- Laser marking substitution:Fiber laser systems are capturing permanent marking applications in metals and rigid plastics. This substitute technology erodes addressable market in automotive component traceability.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO serialization implementation and PLI scheme incentives are expanding domestic packaging capacity. Equipment suppliers can anchor contracts with emerging contract manufacturing organizations.
- Service unbundling models:Predictive maintenance subscriptions and printhead-as-a-service offerings are displacing traditional capital sales. This channel innovation captures recurring revenue from price-sensitive mid-tier manufacturers.
- AI-vision integration:Convergence between inkjet coders and machine vision verification systems is creating premium system bundles. Real-time code validation addresses pharmaceutical quality audit requirements.
Industry Challenges
- Multi-regional certification timelines:Simultaneous FDA 21 CFR Part 11, EU MDR, and NMPA approvals extend product launch cycles. Documentation burden strains regulatory affairs capacity at equipment manufacturers.
- Legacy line integration complexity:Retrofitting continuous inkjet systems into 1990s-era packaging machinery requires custom mounting and synchronization engineering. Project execution risk elevates total cost of ownership estimates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inkjet Coders Market |
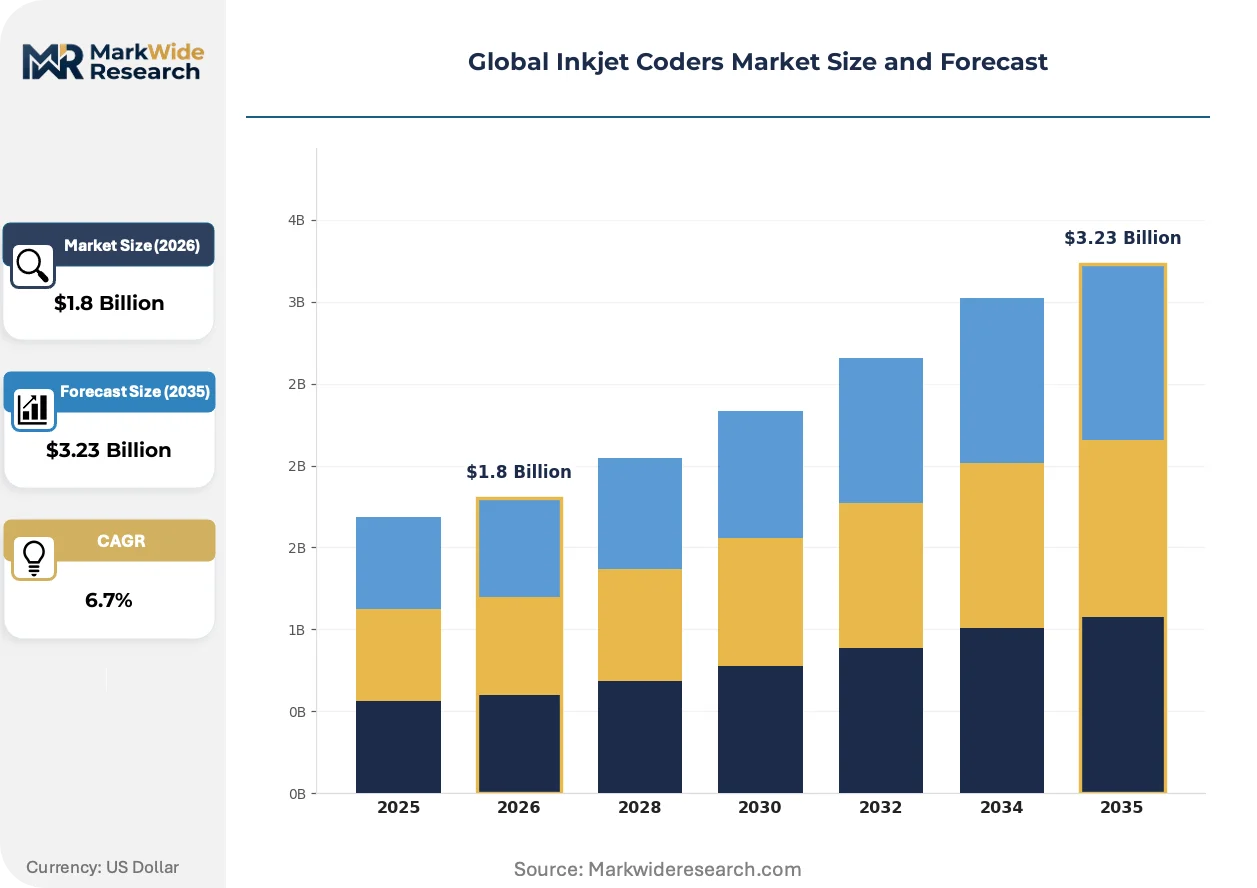
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Continuous Inkjet, Thermal Inkjet, Piezoelectric Inkjet, Drop-On-Demand Industry Vertical: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Application: Labeling, Marking, Packaging, Printing Codes End User: Manufacturers, Retailers, Distributors, Packaging Companies |
| Companies Covered | Videojet Technologies Inc., Markem-Imaje, Domino Printing Sciences plc., ANSER CODING INC., Linx Printing Technologies, Hitachi Industrial Equipment Systems Co., Ltd., ITW Diagraph, Xaar plc., KGK Jet India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inkjet Coders Market Strategic Shifts
Digital printing architectures are converging with industrial IoT platforms to enable real-time production monitoring and predictive maintenance. This integration is compressing the traditional separation between marking equipment and line control systems.
Thermal inkjet printhead technology is electrifying adoption in electronics manufacturing. Miniaturized droplet control enables 300+ dpi marking on semiconductor wafers and miniature components. Korean and Taiwanese contract manufacturers are standardizing this technology for traceability compliance. The shift is electrifying displacement of pad printing and laser etching in high-mix, low-volume production environments.
REACH chemical compliance is forcing systematic ink chemistry reformulation across European installations. ECHA substance restrictions are phasing out specific solvent carriers and pigment compounds. Pharmaceutical packaging lines in Germany and Switzerland are responding with hardware upgrades to accommodate UV-curable and water-based alternatives. Equipment procurement specifications now mandate chemical compatibility roadmaps extending ten years.
Buyer consolidation among multinational consumer goods corporations is centralizing procurement decisions at regional headquarters. Unilever and Nestlé category managers are negotiating enterprise-wide service contracts spanning multiple production sites. This concentration is visible most acutely in Western Europe, where shared service centers in the Netherlands and Switzerland aggregate equipment standardization decisions across dairy, beverage, and home care divisions.
Global Inkjet Coders Market Segmentation
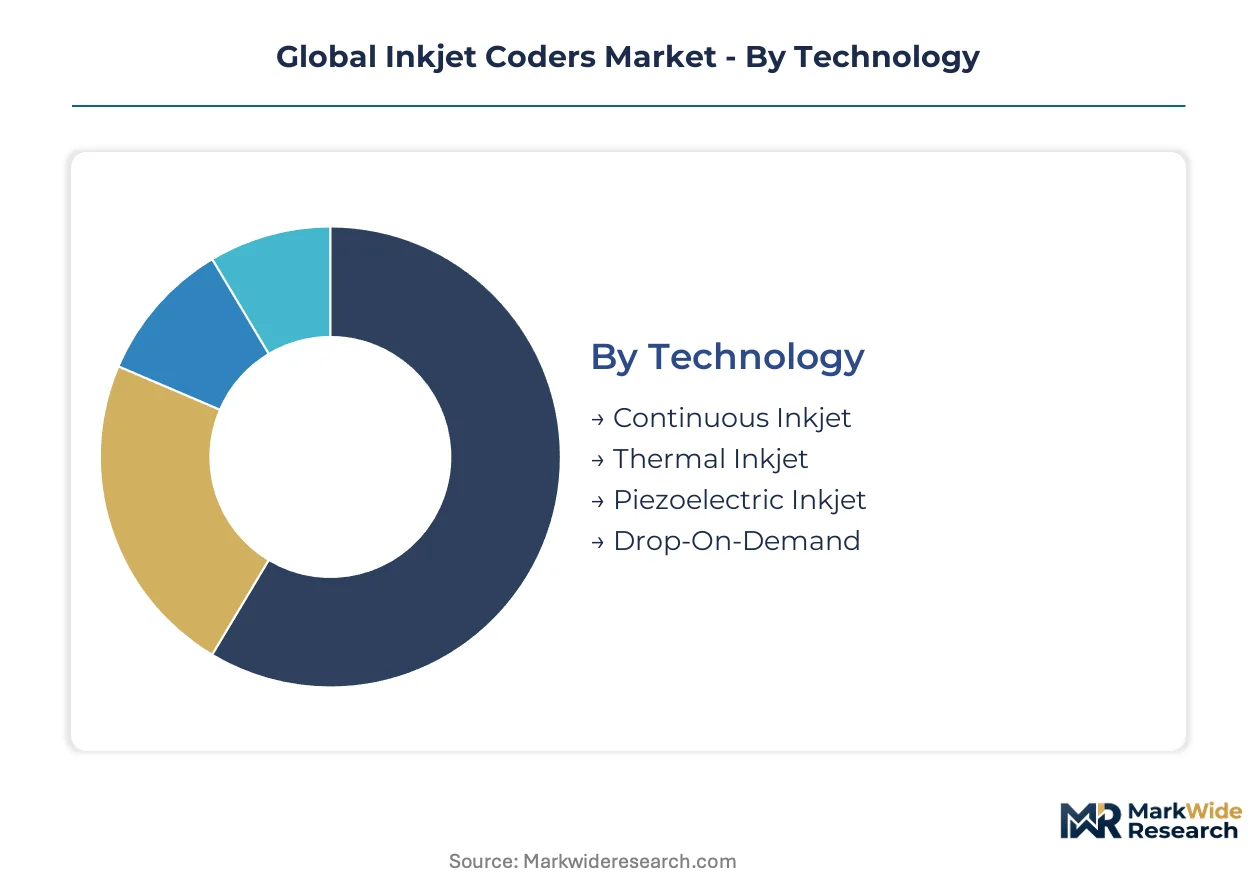
Technology architecture determines equipment selection across pharmaceutical serialization, food-grade marking, and electronics traceability. End-use requirements for ink chemistry compatibility, resolution specifications, and line speed tolerance fragment procurement patterns across industry verticals.
Technology:
Continuous inkjet dominates high-speed packaging lines where substrate variability and harsh environments demand robust droplet propulsion systems.
- Continuous Inkjet:Pressurized ink recirculation enables uninterrupted operation at velocities exceeding 50 m/s. Pharmaceutical manufacturers in Germany and the United States deploy these systems for vial and blister pack serialization under FDA and EU Falsified Medicines Directive mandates.
- Thermal Inkjet:Resistive heating generates vapor bubbles that eject precise droplet volumes. Semiconductor fabs in South Korea and Taiwan standardize this technology for 300+ dpi wafer marking where miniature component traceability is non-negotiable.
- Piezoelectric Inkjet:Ceramic actuators deform to control droplet formation with exceptional precision. Specialty pharmaceutical packaging requiring UV-curable and edible ink compatibility drives niche adoption.
- Drop-On-Demand:Valve-based or thermal mechanisms deposit ink only when required. Lower total cost of ownership attracts mid-tier consumer goods manufacturers with intermittent production schedules.
Mature deployment sits with Continuous Inkjet. Newer deployment is concentrated in Thermal Inkjet.
Industry Vertical:
Regulatory compliance intensity varies sharply across verticals, with pharmaceutical serialization deadlines compressing equipment replacement cycles most aggressively.
- Food & Beverage:Edible ink compatibility and washdown-rated enclosures dominate procurement specifications. Dairy processors in Switzerland and confectionery manufacturers in Belgium prioritize EU REACH-compliant formulations.
- Pharmaceuticals:Machine-readable 2D codes and aggregation requirements define system architecture. The US Drug Supply Chain Security Act and EU Falsified Medicines Directive synchronize compliance investments across three continents.
- Electronics:Miniaturization trends demand 300+ dpi resolution for semiconductor wafer and PCB component marking. Contract manufacturers in Taiwan and South Korea drive thermal inkjet standardization.
- Consumer Goods:Batch coding and expiration dating on flexible packaging requires solvent-based ink tolerance. Personal care manufacturers in France and Germany balance cost sensitivity with brand protection requirements.
Compliance-driven replacement concentrates in Pharmaceuticals. Volume expansion is climbing fastest in Electronics.
Application:
Functional purpose determines hardware configuration, with real-time code verification integration becoming standard in pharmaceutical deployments.
- Labeling:Print-and-apply systems integrate coders with automated label dispensers. Beverage bottlers in Germany's Stuttgart packaging machinery cluster demand synchronized throughput.
- Marking:Direct substrate imprinting eliminates label material costs. Metal component manufacturers in the United States face fiber laser substitution pressure in permanent traceability applications.
- Packaging:Primary and secondary packaging lines require multi-lane coding coordination. Food contact material rules in China's GB standards and EU REACH force ink reformulation investments.
- Printing Codes:Variable data including serialization, lot numbers, and expiration dates. Pharmaceutical contract manufacturers in India anchor demand as CDSCO serialization implementation accelerates.
Established penetration characterizes Packaging. Steepest expansion trajectory is visible in Printing Codes.
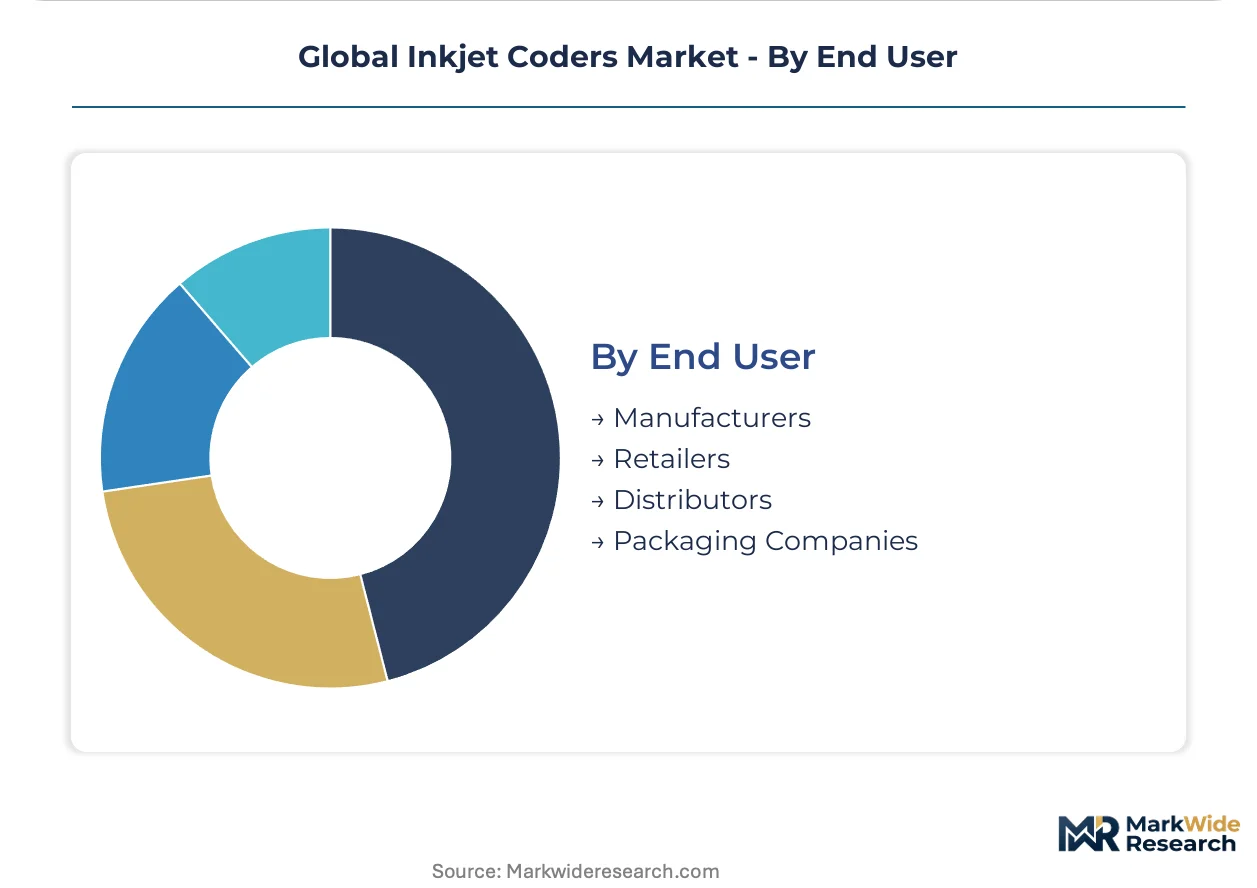
End User:
Procurement centralization among multinational corporations is reshaping vendor relationships, with enterprise-wide service contracts displacing site-by-site equipment purchases.
- Manufacturers:In-house production lines integrate coders into turnkey packaging systems. OEMs around Stuttgart, Germany, specify compatible marking equipment for dairy and beverage exports.
- Retailers:Private label packaging operations require flexible coding for seasonal SKU proliferation. European retail consolidation in the Netherlands and Switzerland drives standardization demands.
- Distributors:Repackaging and relabeling operations need portable or intermittent-use systems. Third-party logistics providers in the United States prioritize rapid changeover capabilities.
- Packaging Companies:Contract packagers serve multiple clients with divergent substrate and ink requirements. Indian pharmaceutical contract manufacturing organizations expand capacity under PLI scheme incentives.
Traditional dominance rests with Manufacturers. Contractual expansion is gaining share fastest in Packaging Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's packaging machinery corridor while consumption disperses across pharmaceutical manufacturing clusters in the United States, Switzerland, and India. Regulatory deadlines in multiple jurisdictions are synchronizing equipment procurement cycles.
United States
Pharmaceutical contract manufacturers drive coder deployment as the FDA enforces Drug Supply Chain Security Act serialization deadlines. Videojet Technologies leverages its North American service infrastructure to anchor enterprise contracts. Chicago-area packaging OEMs integrate marking systems into turnkey lines for food and beverage exporters.
Germany
The EU Falsified Medicines Directive compresses replacement cycles for pharmaceutical packaging equipment. ECHA REACH compliance forces ink reformulation investments that cascade to hardware compatibility requirements. Stuttgart's packaging machinery cluster dominates European dairy and beverage coder installations with integrated print-and-apply systems.
China
NMPA serialization rules and GB standards for food contact materials create parallel compliance layers for multinational suppliers. Domestic pharmaceutical manufacturing expansion under health security priorities drives coder procurement. Yangtze River Delta electronics contract manufacturers adopt thermal inkjet for semiconductor wafer marking.
Switzerland
Swissmedic pharmaceutical packaging standards mandate machine-readable traceability codes that shape equipment specifications. Nestlé's Vevey headquarters centralizes procurement decisions for global dairy and confectionery operations. Basel-area pharmaceutical packaging lines prioritize UV-curable and edible ink compatibility.
India
CDSCO serialization implementation accelerates equipment replacement at contract manufacturing organizations. PLI scheme incentives expand domestic pharmaceutical packaging capacity. Gujarat and Maharashtra pharmaceutical clusters anchor demand as multinational suppliers establish local service presence.
Global Inkjet Coders Market Competitive Environment
Top-tier vendors anchor pharmaceutical and food-grade serialization contracts, while mid-tier specialists compete on price-sensitive consumer goods applications. The vendor base stratifies across three tiers: integrated multinational platforms, regional service-intensive operators, and component-focused technology licensors. Two strategic archetypes dominate: chemistry-led ink formulation specialists and hardware-integrated systems providers. Competitive moves concentrate on predictive maintenance subscriptions and AI-vision system bundling.
Among US-based industrial marking platforms, Videojet Technologies Inc. exemplifies the service-intensive archetype through its North American infrastructure density. Domino Printing Sciences plc., a UK-registered limited company, occupies a chemistry-specialist position. Markem-Imaje, the French-origin entity, anchors European dairy and beverage installations. These three represent distinct competitive vectors: geographic service coverage, ink R&D intensity, and integrated print-and-apply system design.
| Leading Market Players |
|---|
| Videojet Technologies Inc. |
| Markem-Imaje |
| Domino Printing Sciences plc. |
| ANSER CODING INC. |
| Linx Printing Technologies |
| Hitachi Industrial Equipment Systems Co., Ltd. |
| ITW Diagraph |
| Xaar plc. |
| KGK Jet India |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up service networks in North America and Europe concentrate aftermarket pricing power while fragmenting equipment procurement negotiations across pharmaceutical and food-packaging buyers. This ownership pattern tightens margin discipline on recurring consumables even as hardware pricing faces displacement pressure from thermal inkjet alternatives.
Pricing Analysis
Margin tightening in continuous inkjet hardware reflects thermal inkjet substitution in electronics manufacturing and pharmaceutical serialization bundling. Three-tier pricing structure across premium pharmaceutical-grade, standard industrial, and economy intermittent-use levels separates FDA-validated systems from washdown-rated food equipment and entry-level valve-jet alternatives. Price differentiation hinges on GAMP5 validation documentation and geographic service density. Cost-down pressure on solvent-based consumables accelerates because MEK feedstock volatility and REACH compliance investments compound formulation expenses. Mid-tier consumer goods manufacturers exhibit highest price sensitivity; validated pharmaceutical contract manufacturers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision nozzle manufacturers, where Kyocera and Konica Minolta anchor piezoelectric actuator supply and Epson dominates thermal inkjet microfluidics. Geographic concentration in Japan, Germany, and Taiwan creates exposure to regional logistics disruptions and extended lead times for replacement printheads. Raw material dependencies include ceramic substrates for actuators, silicon wafers for thermal elements, and specialty solvent carriers for MEK-based formulations. Distribution runs through OEM packaging machinery integrators in Germany's Stuttgart cluster and direct service branches for pharmaceutical accounts in the United States and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase where thermal inkjet displacement of continuous inkjet in electronics and pharmaceutical serialization bundling are restructuring competitive economics.
For Market Incumbents: Extend predictive maintenance subscriptions and AI-vision integration to lock in pharmaceutical contract manufacturers against thermal inkjet entrants. Anchor chemistry R&D investments in UV-curable and edible ink compatibility to defend against solvent formulation cost pressure. Deepen backward integration into printhead refurbishment capabilities to offset Japanese component supply concentration. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-validated systems and economy intermittent-use equipment opens white-space in mid-tier food and beverage contract packaging. Target Indian pharmaceutical contract manufacturing organizations under CDSCO serialization implementation with localized service partnerships. Penetrate through portable drop-on-demand systems for third-party logistics repackaging operations requiring rapid changeover. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional service-intensive operators in Western Europe with established pharmaceutical validation credentials and recurring consumables revenue. Long-term viability centers on chemistry-software-hardware convergence rather than pure hardware manufacturing. Watch thermal inkjet standardization signals in Korean and Taiwanese semiconductor fabs as inflection indicator for continuous inkjet displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Vision System Integration | Real-time code validation addresses FDA 21 CFR Part 11 pharmaceutical audit requirements. |
| UV-Curable Ink Chemistry Investment | REACH compliance in Germany and Switzerland forces hardware compatibility roadmaps extending ten years. |
| Printhead-as-a-Service Offering | Recurring revenue capture from price-sensitive mid-tier manufacturers displaces capital sales cycles. |
| India Service Infrastructure Buildout | CDSCO serialization and PLI scheme incentives expand pharmaceutical packaging capacity in Gujarat and Maharashtra. |
| Thermal Inkjet Platform Launch | 300+ dpi resolution penetrates semiconductor wafer marking in South Korean and Taiwanese contract manufacturing. |
Study Parameters
Multi-period observation of pharmaceutical serialization compliance deadlines, ink chemistry regulatory filings, and packaging machinery procurement patterns anchored the trend analysis, supplemented by interviews with plant engineers at dairy and beverage manufacturers, regulatory affairs leads at pharmaceutical packaging operations, aftermarket service heads at industrial marking distributors, and procurement teams at contract manufacturing organizations. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA REACH substance restriction updates, CDSCO serialization notifications, customs trade data for printing machinery, and SEC filings of listed equipment manufacturers. Bottom-up equipment shipment estimates and top-down packaging line investment analysis were triangulated against regional regulatory implementation timelines.
Segment-weighting across technology architecture, industry vertical compliance intensity, and geographic regulatory cluster density structured the analytical framework. Continuous inkjet, thermal inkjet, piezoelectric, and drop-on-demand technologies were modeled against pharmaceutical serialization, food-grade marking, electronics traceability, and consumer goods batch coding applications. CAGRs were derived from replacement cycle compression under EU Falsified Medicines Directive and US Drug Supply Chain Security Act deadlines, cross-referenced with electronics miniaturization resolution requirements and food contact material rule implementations.
Underlying measurement precision varies by segment; pharmaceutical serialization-driven replacement carries tighter precision than discretionary consumer goods capital expenditure timing. Forecasts reflect assumptions about regulatory deadline adherence, thermal inkjet resolution advancement, and solvent ink chemistry cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
India Inkjet Printer Market
Printers
Thermal Inkjet Printer Market
Printers
Mobile Printer Market
Printers
Single Function Printer Market
Printers
Portable Printer Market
Printers
NCR Printers Market
Printers
Aerosol Printing and Graphics Market
Printers
Laser Printer Market
Printers
Printer Ribbons Market
Printers
Mobile Photo Printer Market
Printers
Retail Printers and Consumables Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Global Ticket Printers Production Market
Printers
Thermal Printer Market
Printers
Global Printer Market
Printers
Ink Tank Printer Market