
 A3 and A4 Multi-Function Printer Market | 2026-2036
A3 and A4 Multi-Function Printer Market Size, Share, and Industry Trends Forecast 2026-2036
A3 and A4 Multi-Function Printer Market Insights
Multi-source component procurement is restructuring supply economics for A3 and A4 multi-function printer manufacturers. Canon Inc. leverages its captive imaging sensor production to control cost volatility across laser engine lines. HP Inc. sustains margin resilience through backward integration into toner chemistry and firmware ecosystems. Ricoh Company, Ltd. anchors its competitive stance with service-led contracts that bundle hardware, consumables, and managed print services into single-account structures.
An A3 and A4 multi-function printer integrates printing, scanning, copying, and faxing into a single chassis, with A3 models handling tabloid-size media up to 297 by 420 millimeters and A4 models optimized for standard letter and legal formats; laser variants dominate corporate environments due to page-per-minute throughput exceeding forty monochrome sheets and duty cycles rated above one hundred thousand pages monthly. Laser product types command the largest installed base among corporate office end users, where total cost of ownership calculations favor cartridge yield over inkjet page economics. All-in-One configurations are capturing share in home office segments as remote workers consolidate desktop equipment into single-footprint devices with Wi-Fi and cloud-printing connectivity.
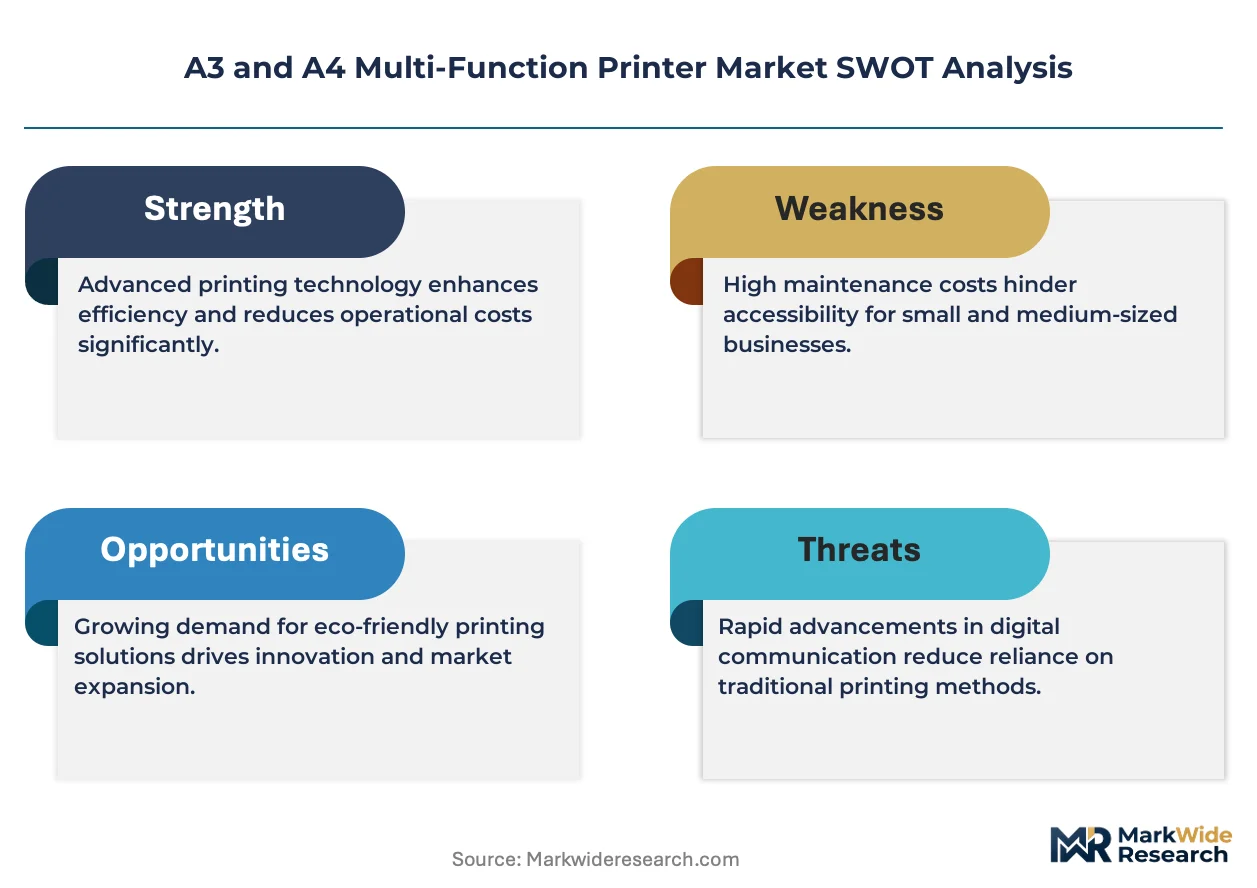
The EPA Energy Star program and EU Ecodesign regulations enforce standby power thresholds and automatic duplexing mandates that shape hardware development roadmaps for OEMs selling into North America and Europe. Japan's METI Top Runner program accelerates efficiency benchmarks for office equipment sold domestically, pushing Kyocera Document Solutions Inc. and Sharp Corporation to prioritize low-melt toner technologies. Stakeholders must monitor how firmware-based subscription models and regulatory compliance costs redistribute profitability between hardware sales and recurring service revenue streams.
Market Dynamics
Fleet refresh cycles at large enterprises are lengthening as hybrid work policies reduce page volumes per device, while EU Ecodesign standby power mandates force hardware redesigns that compress OEM development timelines.
Growth Catalysts
- Hybrid Work Infrastructure:Distributed workforces require secure cloud-printing capabilities and mobile device management integration. Corporate IT departments prioritize A4 all-in-one units for home office deployments.
- EU Ecodesign Regulations:Mandatory automatic duplexing and standby power thresholds below one watt accelerate replacement of legacy single-function devices. German and French public sector tenders now exclude non-compliant hardware.
- Low-Melt Toner Chemistry:Energy consumption reductions of twenty-five to thirty percent per printed page drive adoption in sustainability-focused enterprises. Japanese OEMs lead process development for polymerized toner formulations.
Market Restraints
- Semiconductor Component Concentration:Controller chip and imaging sensor supply concentrates among Taiwanese and South Korean foundries. Lead times for laser engine ASICs extend to thirty-six weeks during capacity constraints.
- Substitution by Pure Digital Workflows:Electronic signature platforms and document management systems reduce hardcopy requirements in financial services and legal sectors. Page volumes per knowledge worker decline three to five percent annually.
- REACH Chemical Compliance:Registration requirements for toner resin feedstocks and photoconductor drum coatings increase formulation costs. European manufacturers face dual compliance burdens with RoHS substance restrictions.
Strategic Opportunities
- India SME Penetration:Small and medium enterprises in Maharashtra and Karnataka remain underpenetrated relative to installed base density in Japan and Germany. Local assembly partnerships circumvent import duty structures.
- Managed Print Service Bundling:Device-as-a-service contracts consolidate hardware, consumables, and remote monitoring into per-page pricing. This model captures recurring revenue streams and extends customer lock-in duration.
- ISO 14001 Certification Alignment:Environmental management system certification requirements in corporate procurement RFPs create preference for hardware with verified lifecycle carbon footprints. Certified devices command placement in sustainability-led accounts.
Industry Challenges
- Firmware Security Engineering Talent:Embedded systems security expertise for print controller hardening remains scarce relative to demand. OEMs compete with automotive and industrial control sectors for qualified engineers.
- Legacy Fleet Integration Complexity:Heterogeneous device populations spanning fifteen-plus years of manufacture strain unified fleet management platform deployments. IT administrators face driver compatibility and security patch fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A3 and A4 Multi-Function Printer Market |
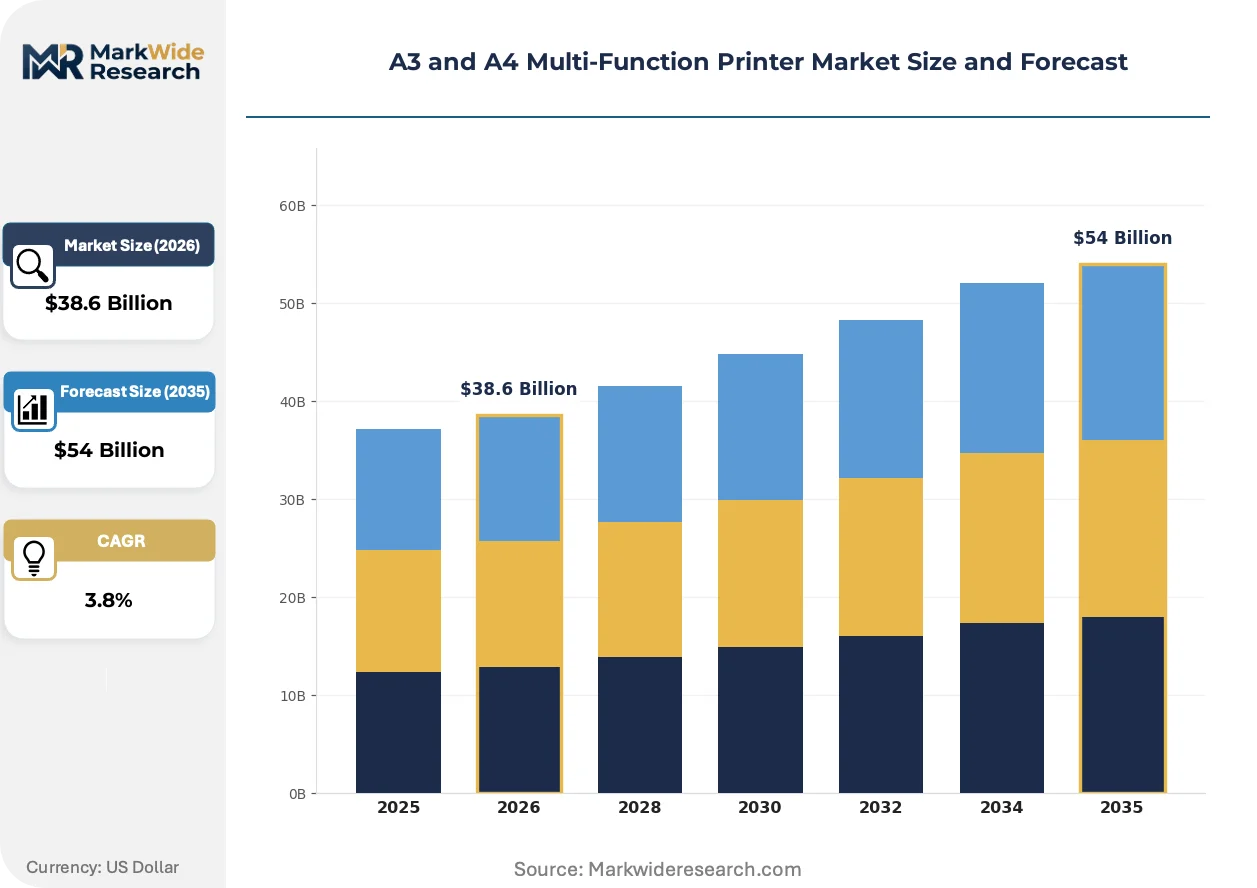
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, LED, All-in-One End User: Small Business, Corporate Office, Educational Institution, Home Office Functionality: Printing, Scanning, Copying, Faxing Connectivity: USB, Wi-Fi, Ethernet, Bluetooth |
| Companies Covered | Canon Inc., HP Inc., Xerox Corporation, Ricoh Company, Ltd., Konica Minolta, Inc., Brother Industries, Ltd., Sharp Corporation, Kyocera Document Solutions Inc., Lexmark International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A3 and A4 Multi-Function Printer Market Trends and Innovations
Hardware architectures are fragmenting into componentized subsystems that enable field upgradability, while regulatory pressure on embodied carbon intensifies material science investment and procurement patterns shift toward consumption-based commercial models.
Print controller architecture is modularizing into discrete processing units for image rendering, network security, and user interface functions. Enterprise IT departments specify field-upgradable security modules to extend hardware lifecycles without full device replacement. This modularity compresses refresh revenue timing while expanding service attachment rates for firmware subscription tiers.
The EU Ecodesign Directive's 2023 standby power amendments enforce sub-one-watt thresholds for networked multi-function devices. OEMs redesign power management firmware and low-energy system-on-chip controllers to maintain market access. German and Dutch corporate buyers now mandate compliance documentation in competitive tenders, shifting procurement evaluation weighting toward energy efficiency metrics.
Enterprise sourcing departments are consolidating vendor relationships through single-account managed print contracts that unbundle capital expenditure from operational budgets. Channel partners and independent dealers face margin compression as direct OEM engagement captures large enterprise accounts. This concentration is most visible in United States healthcare and financial services verticals where procurement centralization has eliminated multi-vendor fleet strategies.
A3 and A4 Multi-Function Printer Market Segmentation
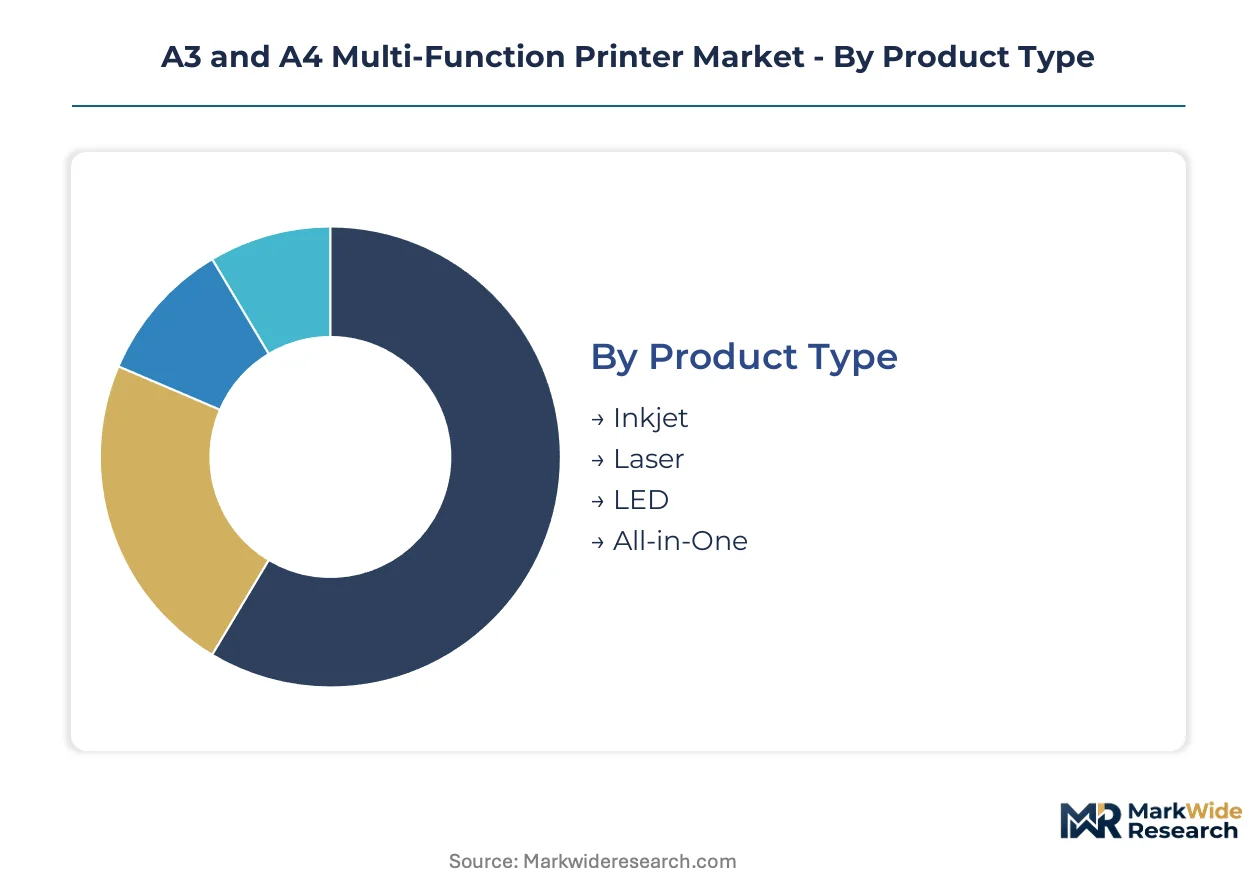
Segmentation in the A3 and A4 multi-function printer market reveals divergent hardware economics between high-volume corporate installations and distributed home office deployments. Procurement patterns split sharply across product type and end user dimensions, with laser engines commanding enterprise accounts while inkjet and all-in-one configurations penetrate price-sensitive segments.
Product Type:
Laser variants dominate volume shipments while inkjet and LED technologies carve distinct premium and efficiency niches.
- Laser:Electrophotographic imaging engines utilizing dry toner fusion achieve page-per-minute throughput exceeding forty monochrome sheets. Corporate offices in Germany and Japan specify laser hardware for duty cycles above one hundred thousand pages monthly, driven by total cost of ownership calculations favoring high-yield cartridge economics over inkjet page costs.
- All-in-One:Integrated chassis designs consolidate printing, scanning, copying, and faxing into single-footprint devices with Wi-Fi and cloud-printing connectivity. Home office segments across the United States capture this configuration fastest, as remote workers replace multiple desktop peripherals with space-efficient units.
- Inkjet:Piezoelectric or thermal printhead technologies deposit liquid ink onto media, offering lower acquisition cost at the expense of per-page economics. Small business installations in cost-constrained markets favor inkjet for intermittent print volumes below five hundred pages monthly.
- LED:Solid-state imaging arrays replace laser scanning assemblies, reducing mechanical complexity and enabling compact chassis designs. Japanese OEMs lead LED engine development for energy-efficient deployments in sustainability-focused enterprise accounts.
Today's leader: Laser. Tomorrow's challenger: All-in-One.
End User:
Customer type determines pricing architecture and service attachment rates across hardware procurement cycles.
- Corporate Office:Fleet deployments exceeding fifty devices per location require managed print service contracts with remote monitoring and automated consumables replenishment. United States healthcare and financial services verticals centralize procurement through single-account structures that unbundle capital expenditure from operational budgets.
- Home Office:Individual knowledge workers operating from residential locations prioritize compact A4 all-in-one units with mobile device management integration. Hybrid work policies at large enterprises accelerate refresh cycles for distributed employee hardware stipends.
- Small Business:Organizations with fewer than fifty employees purchase through channel partners and independent dealers, facing margin compression as direct OEM engagement captures adjacent mid-market accounts.
- Educational Institution:K-12 districts and university systems specify durability-rated hardware for high-utilization library and administrative deployments, with procurement timelines tied to fiscal year budget cycles.
Corporate Office commands current revenue concentration. Home Office exhibits the steepest expansion trajectory as hybrid work infrastructure investments persist.
Functionality:
Capability bundling shifts hardware specification toward integrated document workflows rather than single-purpose devices.
- Printing:Core output function with monochrome and color variants, where duplexing speed and resolution specifications differentiate enterprise-grade from consumer-grade hardware.
- Scanning:Document digitization capabilities with automatic document feeders and optical character recognition integration, critical for financial services compliance workflows.
- Copying:Standalone reproduction without host computer dependency, retaining relevance in legal and government sectors with persistent hardcopy requirements.
- Faxing:Analog transmission capability declining in adoption except for healthcare HIPAA-compliant document exchange and legal affidavit transmission.
Printing and Scanning anchor current procurement specifications. Faxing faces accelerating displacement by secure electronic signature platforms.
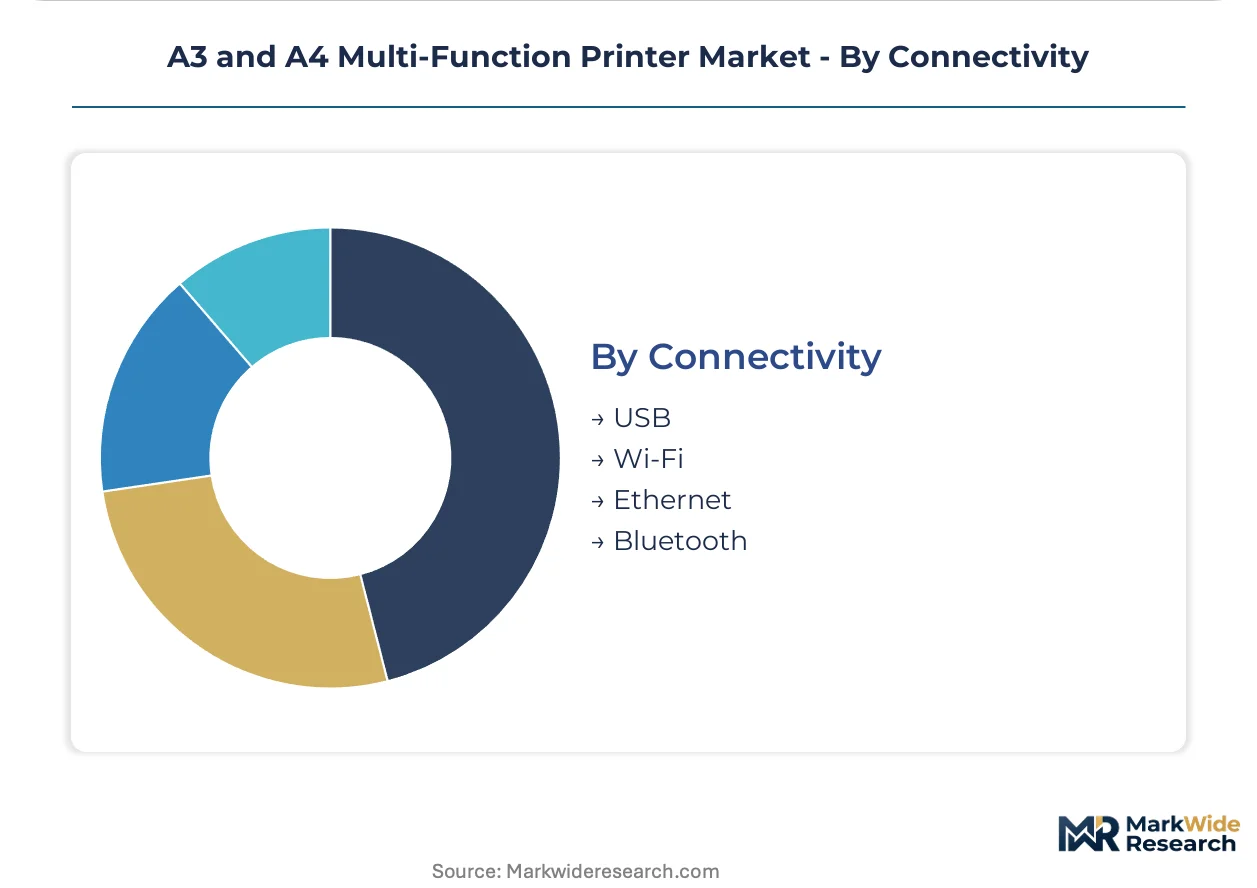
Connectivity:
Network integration requirements reshape controller architecture and security hardening investments.
- Wi-Fi:Wireless LAN connectivity essential for home office and flexible workspace deployments, with WPA3 encryption now mandatory in enterprise security policies.
- Ethernet:Wired network connectivity dominating corporate fleet installations, enabling centralized print server management and VLAN segmentation.
- USB:Direct host connection for single-user configurations and driver installation, persisting as fallback for network outage scenarios.
- Bluetooth:Short-range pairing for mobile device printing from smartphones and tablets, gaining traction in hospitality and retail point-of-sale environments.
Ethernet and Wi-Fi constitute the present standard. Bluetooth is climbing fastest as mobile-first document workflows proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as OEMs relocate assembly to jurisdictions with lower compliance burdens while maintaining R&D in established markets. Cost-of-compliance gaps between the European Union and Southeast Asian manufacturing hubs are accelerating this geographic unbundling.
United States
Corporate fleet modernization and healthcare digitization drive hardware refresh cycles. The EPA Energy Star program enforces standby power thresholds that disqualify legacy devices from federal procurement. Dallas-Fort Worth and Chicago host major distribution hubs where channel partners consolidate enterprise accounts.
Germany
Public sector tenders and Mittelstand manufacturing automation sustain institutional demand. EU Ecodesign regulations mandate automatic duplexing and sub-one-watt standby consumption. The Rhine-Ruhr industrial corridor concentrates service-led contract negotiations for managed print deployments.
Japan
Office infrastructure density and METI Top Runner efficiency benchmarks sustain replacement demand. Domestic OEMs prioritize low-melt toner chemistry to meet escalating energy standards. Osaka and Nagoya anchor polymerized toner formulation development for export markets.
India
SME formalization and government digitization initiatives expand addressable market scope. Bureau of Indian Standards certification requirements structure import competition. Maharashtra and Karnataka host emerging assembly partnerships that circumvent duty structures on finished hardware.
China
Domestic enterprise fleet expansion and state-owned enterprise procurement sustain volume demand. MIIT energy efficiency labeling shapes local product specifications. The Yangtze River Delta concentrates controller chip sourcing and imaging sensor foundry relationships.
A3 and A4 Multi-Function Printer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subscription-based service models and circular hardware economics. The vendor base stratifies across three maturity tiers: integrated imaging conglomerates with captive component supply, specialist document solution providers with service-led contracts, and regional assemblers competing on acquisition cost. Dominant competitive moves include backward integration into toner chemistry and firmware ecosystems, plus consolidation of channel partnerships into direct enterprise engagement.
Among Japanese imaging specialists, Canon Inc., Ricoh Company, Ltd., and Kyocera Document Solutions Inc. exemplify the integrated conglomerate archetype with captive sensor and engine production. These entities anchor competitive positioning through control over critical imaging subsystems. HP Inc. represents the North American technology platform model, leveraging software and consumables ecosystems to sustain margin structures independent of hardware cycles.
| Leading Market Players |
|---|
| Canon Inc. |
| HP Inc. |
| Xerox Corporation |
| Ricoh Company, Ltd. |
| Konica Minolta, Inc. |
| Brother Industries, Ltd. |
| Sharp Corporation |
| Kyocera Document Solutions Inc. |
| Lexmark International, Inc. |
| Others |
Pricing and Supply Chain Analysis
Low-melt toner chemistry adoption simultaneously compresses per-page energy costs and concentrates polymerized formulation expertise among Japanese OEMs, redistributing margin capture from hardware assembly toward captive consumables production. This technology shift tightens supply-side control while enabling subscription-based pricing architectures that extend customer lifetime value beyond initial device placement.
Pricing Analysis
Distributor margins on A4 all-in-one hardware compress as direct OEM engagement captures enterprise accounts through managed print service bundling. Three-tier pricing structure across premium, standard, and economy levels separates certified energy-efficient devices from baseline configurations, with ISO 14001 alignment commanding placement premiums in sustainability-led procurement. Cost compression in entry-level laser segments intensifies as Indian assembly partnerships circumvent import duty structures. Small business purchasers through channel partners exhibit highest price sensitivity, while corporate fleet buyers prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Refurbishment flows for imaging sensors and controller chips extend component lifecycles while creating secondary supply channels that moderate new-part pricing volatility. Controller ASIC fabrication concentrates in Taiwan and South Korea, with laser engine optics sourcing from Japan and Germany. Toner resin feedstocks and photoconductor drum coatings draw from specialized chemical suppliers subject to REACH compliance burdens. Single-source vulnerability in imaging sensor foundries poses structural risk during capacity constraints. Distribution runs through Dallas-Fort Worth and Chicago hubs for North American enterprise accounts, with Rhine-Ruhr corridor concentration for European service-led contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on firmware subscription attachment and low-melt toner chemistry adoption, both shifting revenue toward recurring consumables and away from transactional hardware cycles.
For Market Incumbents: To counter direct OEM disintermediation of channel partners, incumbents should deepen backward integration into toner chemistry to protect consumables margins and deploy field-upgradable security modules that extend hardware lifecycles without full device replacement. For New Entrants and Emerging Players: Capture underpenetrated SME segments in Maharashtra and Karnataka through local assembly partnerships that circumvent import duty structures, leveraging managed print service bundling as the primary go-to-market mechanism to displace fragmented dealer relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers lacking captive consumables production, presenting acquisition targets for vertical integration plays. Long-term viability favors entities controlling firmware ecosystems and polymerized toner formulation. Monitor EU Ecodesign standby power threshold enforcement as the signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Print Service Bundling | Consolidates hardware, consumables, and remote monitoring into per-page pricing for corporate accounts. |
| Low-Melt Toner Chemistry Investment | Reduces energy consumption per page while meeting METI Top Runner and EU Ecodesign efficiency mandates. |
| Firmware Security Module Development | Enables field-upgradable security hardening that extends hardware lifecycles without full device replacement. |
| Local Assembly Partnership Formation | Circumvents Indian import duty structures while positioning for SME penetration in underpenetrated states. |
| ISO 14001 Certification Alignment | Captures placement in sustainability-led procurement RFPs requiring verified lifecycle carbon footprints. |
Research Methodology
Direct dialogue with OEM product managers, managed print service operations directors, enterprise IT procurement leads, and channel partner principals anchored qualitative assessment, cross-referenced with SEC 10-K filings, EPA Energy Star certification databases, EU Ecodesign compliance registries, and Japanese METI efficiency benchmark publications. Bottom-up shipment estimates by product type and end user triangulated against top-down market sizing derived from installed base analysis and replacement cycle modeling.
Segment-level value outputs across the analysis window reflect discrete modeling of laser, inkjet, LED, and all-in-one hardware categories, with corporate office, home office, small business, and educational institution end-user splits. CAGRs were derived from regression analysis of historical refresh cycles, hybrid work policy adoption curves, and regulatory compliance deadline impacts. Forecast inputs incorporated duty cycle utilization rates, page-per-minute throughput specifications, and firmware subscription attachment trajectories.
Semiconductor component concentration, REACH chemical compliance cost escalation, and substitution acceleration by pure digital workflows are the dominant revision risks to modeled outcomes. Practitioners should monitor foundry capacity utilization, EU Ecodesign amendment timelines, and electronic signature platform adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Mobile Photo Printer Market
Printers
Photocopiers Market
Printers
Thermal Printer Market
Printers
Laser Printer Market
Printers
Global UV LED Printers Market
Printers
Dot Matrix Printer Market
Printers
Indonesia Thermal Printer Market
Printers
Production Printer Market
Printers
Multi-Functional Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Single Function Printer Market
Printers
India Inkjet Printer Market
Printers
Continuous Inkjet Printers Market
Printers
NCR Printers Market
Printers
Global Thermal Printing Market
Printers
Copier, MFP and Printer Market