
 Global Thermal Printing Market | 2026-2036
Global Thermal Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Printing Market Foresight
Logistics providers are redrawing procurement priorities for thermal printing hardware as warehouse automation accelerates. Zebra Technologies dominates enterprise-grade mobile printer deployments through captive supply of ruggedized fleet units. SATO Holdings anchors Japanese precision manufacturing with specialized thermal transfer systems for food traceability compliance. Brother Industries competes on compact desktop units that sustain margin pools in small-format retail labeling across Asia-Pacific distribution channels.
Thermal printing generates images by selectively heating coated thermochromic paper or transferring ink from a ribbon onto a substrate using a thermal printhead with resolution typically ranging from 200 to 600 dots per inch. Its primary commercial purpose spans high-speed barcode labeling, receipt generation, and variable-data packaging where mechanical impact or liquid ink would compromise operational speed or substrate compatibility. Direct thermal printers occupy the largest installed base due to minimal consumable requirements in short-lifecycle applications like shipping labels and event tickets. Thermal transfer printers capture higher-margin positions in textile printing and durable goods marking where wax resin and resin-based ribbon formulations resist abrasion, chemicals, and UV exposure.
FDA food contact material rules in the United States and EU REACH chemical restrictions jointly constrain ribbon coating chemistries and direct thermal paper formulations, compelling suppliers to reformulate for compliance or surrender market access. Japan's METI energy efficiency standards for office equipment shape product development roadmaps for printhead heating elements and standby power consumption. Stakeholders must monitor evolving chemical disclosure requirements under CSRD corporate sustainability reporting and assess whether hybrid thermal architectures that bridge direct and transfer modalities warrant accelerated R&D commitment.
Market Dynamics
Warehouse automation is compressing hardware replacement cycles as logistics operators standardize on fleet-managed thermal printers with cloud-connected printhead monitoring and predictive maintenance algorithms.
Growth Catalysts
- E-commerce fulfillment density:Chinese distribution centers are deploying high-volume barcode stations to match same-day delivery SLAs from JD.com and Alibaba logistics networks.
- EU chemical compliance:REACH restrictions on bisphenol-A thermal paper are accelerating resin ribbon adoption for food-contact labeling in European grocery retail chains.
- Printhead resolution advances:600 dpi micro-thermal arrays are enabling textile transfer printing for on-demand apparel production in Vietnamese and Bangladeshi garment hubs.
Market Restraints
- Raw material concentration:Japan and South Korea control 70% of ceramic thin-film printhead substrate supply, creating single-source vulnerability for OEMs.
- Substitution by inkjet:Piezoelectric inkjet systems are capturing variable-data packaging applications previously served by thermal transfer in European pharmaceutical serialization.
- Energy cost volatility:German and Italian converter operations face margin compression from natural gas-driven electricity pricing affecting ribbon coating oven throughput.
Strategic Opportunities
- Indian cold chain expansion:FSSAI-mandated food traceability is creating first-time demand for thermal transfer systems in refrigerated logistics corridors between Mumbai and Delhi.
- Hybrid architecture development:Dual-mode printers switching between direct and transfer modalities are capturing contract packaging houses serving multiple end-use verticals.
- CSRD reporting tailwind:EU corporate sustainability disclosure rules are favoring thermal over laser printing for lower embodied carbon in enterprise document workflows.
Industry Challenges
- Embedded systems integration:Warehouse operators struggle to synchronize legacy WMS platforms with IoT-enabled printer fleets requiring real-time API connectivity.
- Formulation chemist scarcity:EU REACH expertise shortages are delaying ribbon coating reformulation timelines for converters seeking market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Printing Market |
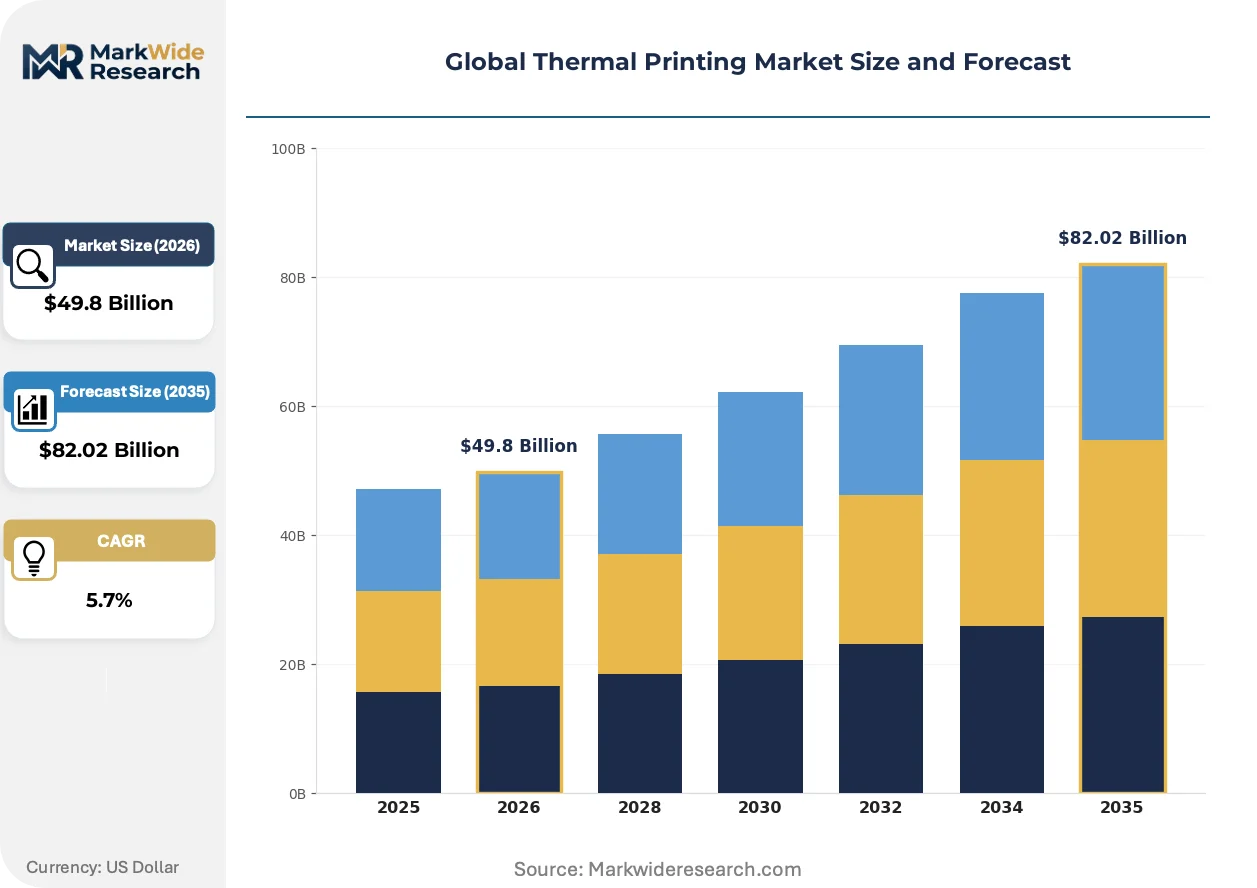
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $82.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal Printers, Thermal Transfer Printers, Hybrid Thermal Printers, Mobile Thermal Printers Technology: Thermal Printhead, Ink Ribbon, Wax Resin, Resin-Based, Dye Sublimation Application: Barcode Labeling, Ticketing, Packaging, Textile Printing, Food Traceability End User: Logistics Providers, Retail Chains, Manufacturing Facilities, Healthcare Providers, Event Management |
| Companies Covered | Zebra Technologies Corporation, SATO Holdings Corporation, Brother Industries, Ltd., Seiko Epson Corporation, Honeywell International Inc., BIXOLON Co., Ltd., Toshiba Tec Corporation, TSC Auto ID Technology Co., Ltd., Star Micronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Printing Market Shifts & Advancements
Silicon carbide thermal printhead substrates and resin ribbon nanocoatings are converging to extend printhead life and expand substrate compatibility across industrial marking applications.
Ceramic thin-film heating elements with embedded temperature feedback loops are supplanting traditional metal-alloy printheads in high-duty-cycle logistics deployments. Amazon and DHL supply chain operators are specifying these units for 24-hour continuous operation in automated sortation facilities. The shift is compressing maintenance intervals from quarterly to annual while enabling thinner, more flexible label substrates.
Japan's METI energy efficiency standards for office equipment are mandating sub-1-watt standby power consumption for thermal printers deployed in corporate environments. Manufacturers are redesigning heating element control circuits and sleep-state firmware to comply. The regulation is accelerating obsolescence of legacy desktop units in Tokyo and Osaka enterprise refresh cycles.
Equipment-as-a-service contracts with bundled consumable replenishment are displacing capital purchase models among mid-market logistics providers. Third-party lessors are capturing fleet management contracts previously held by distributor sales channels. The transition is most visible in German and Dutch contract logistics where operating lease structures align with automation capex constraints.
Global Thermal Printing Market Segmentation
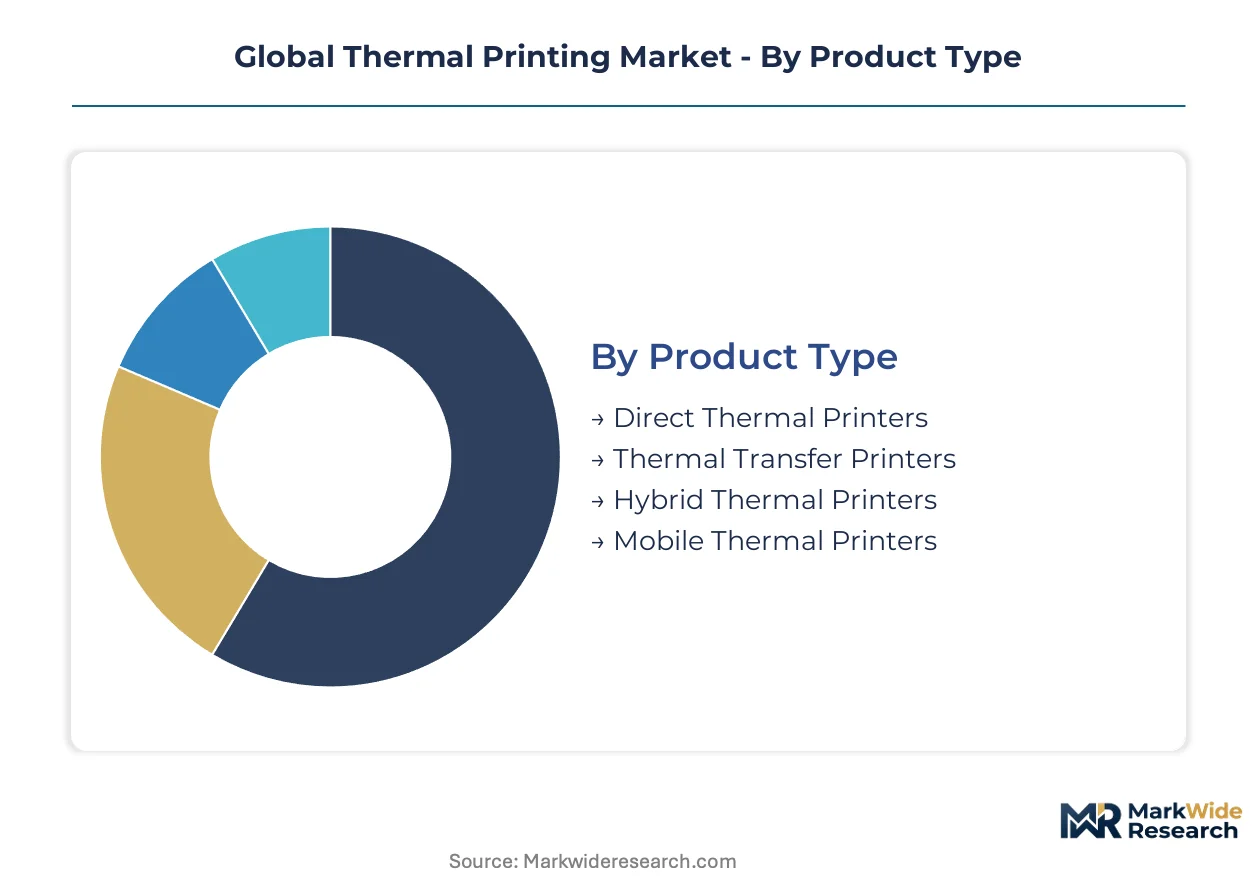
Thermal printing segments diverge sharply between domestic fulfillment infrastructure and export-oriented manufacturing demand. Understanding these geographic demand patterns shapes procurement strategy for hardware OEMs and consumable suppliers.
Product Type:
Domestic logistics networks favor mobile and direct thermal units, while export manufacturing corridors drive thermal transfer and hybrid system deployments.
- Direct Thermal Printers:These units apply heat directly to thermochromic paper without ribbon consumables, minimizing operational complexity for short-lifecycle applications. Chinese e-commerce fulfillment centers in Shanghai and Shenzhen deploy these for same-day delivery label throughput, though their output fades under heat exposure limiting archival use.
- Thermal Transfer Printers:Wax resin or resin ribbon formulations transfer durable images onto synthetic substrates. Vietnamese and Bangladeshi garment exporters specify these for care label compliance with EU and US import standards, where abrasion resistance determines customs acceptance.
- Hybrid Thermal Printers:Dual-mode architecture switches between direct and transfer modalities based on job requirements. Contract packaging houses in Germany and the Netherlands adopt these for multi-vertical flexibility.
- Mobile Thermal Printers:Battery-powered ruggedized units with Bluetooth and WiFi connectivity. Last-mile delivery fleets in Brazil and India equip drivers for on-route label generation.
Direct thermal printers command the established base. The steepest expansion runs through hybrid thermal printers.
Technology:
Cost tier stratification separates commodity ribbon formulations from precision-engineered printhead substrates and nanocoated resin systems.
- Thermal Printhead:Ceramic thin-film heating elements with embedded temperature feedback loops dominate high-duty-cycle logistics. Amazon sortation facilities specify these for 24-hour continuous operation, compressing maintenance intervals from quarterly to annual cycles.
- Ink Ribbon:Wax-based formulations serve cost-sensitive retail receipt applications. Japanese and South Korean substrate suppliers control 70% of ceramic thin-film supply, creating single-source vulnerability for OEMs.
- Wax Resin:Intermediate durability grade balances cost and performance for general-purpose barcode labeling. European grocery retail chains accelerate adoption under REACH bisphenol-A restrictions on direct thermal paper.
- Resin-Based:Maximum chemical and UV resistance for harsh-environment industrial marking. FDA food contact material rules and EU REACH jointly constrain coating chemistries, compelling reformulation for market access.
- Dye Sublimation:Continuous-tone photographic output for ID badge and textile transfer applications. On-demand apparel production in Vietnamese garment hubs adopts 600 dpi micro-thermal arrays for this process.
Wax resin anchors volume production. Resin-based formulations are climbing the fastest as compliance requirements tighten.
Application:
Volume concentration in logistics-driven labeling contrasts with emerging specialty applications in regulated food and textile sectors.
- Barcode Labeling:High-speed variable-data output for automated sortation and inventory tracking. JD.com and Alibaba logistics networks in China drive fleet-scale deployments across automated distribution hubs.
- Ticketing:Event admission and transport passes with short validity periods. Direct thermal dominates due to minimal consumable requirements and rapid print speed.
- Packaging:Variable-data carton and case marking for pharmaceutical serialization. Piezoelectric inkjet systems capture share in European pharmaceutical applications previously served by thermal transfer.
- Textile Printing:Care label and on-demand garment decoration. Bangladeshi and Vietnamese exporters invest in transfer systems to meet EU and US import compliance.
- Food Traceability:FSSAI-mandated cold chain documentation in India creates first-time demand. Refrigerated logistics corridors between Mumbai and Delhi require thermal transfer durability for moisture-exposed labels.
Barcode labeling commands the established base. Food traceability is gaining share fastest as regulatory mandates proliferate.
End User:
Customer type determines margin structure, with logistics providers driving hardware-as-a-service adoption while healthcare and retail sustain consumable revenue pools.
- Logistics Providers:Fleet-managed printer deployments with cloud-connected monitoring and predictive maintenance algorithms. German and Dutch contract logistics favor operating lease structures aligning with automation capex constraints.
- Retail Chains:Point-of-sale receipt generation and shelf-label printing. Japanese METI energy efficiency standards mandate sub-1-watt standby power, accelerating obsolescence of legacy desktop units in Tokyo and Osaka.
- Manufacturing Facilities:Work-in-process tracking and finished goods marking. Warehouse operators struggle to synchronize legacy WMS platforms with IoT-enabled printer fleets requiring real-time API connectivity.
- Healthcare Providers:Patient wristband and specimen label printing with antimicrobial substrate requirements. HIPAA compliance shapes data handling protocols for networked devices.
- Event Management:On-site badge printing and admission control. Mobile thermal units enable rapid deployment for temporary venues without fixed infrastructure.
Logistics providers command the established base. Healthcare providers are expanding most quickly as patient safety regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese garment exporters ship thermal-printed care labels to EU and US buyers, while Chinese e-commerce fulfillment networks consume direct thermal hardware for domestic same-day delivery infrastructure.
China
JD.com and Alibaba logistics networks drive fleet-scale barcode station deployments across automated distribution hubs in Shanghai and Shenzhen. MIIT industrial standards shape printhead efficiency requirements for domestic equipment procurement. Yangtze River Delta manufacturing clusters supply ceramic thin-film substrates to regional OEMs.
Germany
Contract logistics operators in the Ruhr region favor equipment-as-a-service contracts with bundled consumable replenishment under operating lease structures. REACH chemical restrictions on bisphenol-A thermal paper accelerate resin ribbon adoption in grocery retail chains. KBA transport regulations mandate durable goods labeling for automotive component exports.
United States
FDA food contact material rules constrain ribbon coating chemistries for packaged food labeling applications. Amazon sortation facilities specify ceramic thin-film printheads for 24-hour continuous operation. Midwest distribution corridors between Chicago and Detroit standardize on cloud-connected printer fleets with predictive maintenance algorithms.
Japan
METI energy efficiency standards mandate sub-1-watt standby power consumption for corporate thermal printer deployments. SATO Holdings anchors precision manufacturing of specialized thermal transfer systems in Tokyo and Osaka enterprise refresh cycles. Nagoya industrial clusters supply ceramic heating elements with embedded temperature feedback loops.
India
FSSAI-mandated food traceability creates first-time demand for thermal transfer systems in refrigerated logistics corridors between Mumbai and Delhi. BIS certification requirements shape hardware import standards for warehouse automation projects. Gujarat pharmaceutical exporters invest in variable-data packaging equipment for serialization compliance.
Global Thermal Printing Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive printing divisions alongside specialized industrial marking firms. Market structure concentrates around three to five dominant hardware OEMs controlling premium-tier enterprise deployments, with mid-market fragmentation among regional ribbon converters and desktop unit assemblers. Strategic archetypes include ruggedized mobile printer specialists, resin formulation chemists, and cloud-enabled fleet management platforms. Competitive moves center on backward integration into ceramic substrate manufacturing and geographic expansion through distributor acquisition in Southeast Asian garment hubs.
Among Japan-based fabricators, SATO Holdings Corporation and Brother Industries, Ltd. exemplify divergent positioning archetypes within the thermal printing sector. SATO Holdings occupies a position emphasizing industrial-grade transfer systems for regulated compliance applications, while Brother Industries sits within the compact desktop segment serving small-format retail labeling. Zebra Technologies Corporation anchors the diversified technology conglomerate tier with captive supply of ruggedized fleet units for logistics automation. These three entities collectively represent the geographic and structural breadth of competitive positioning across the hardware OEM landscape.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| SATO Holdings Corporation |
| Brother Industries, Ltd. |
| Seiko Epson Corporation |
| Honeywell International Inc. |
| BIXOLON Co., Ltd. |
| Toshiba Tec Corporation |
| TSC Auto ID Technology Co., Ltd. |
| Star Micronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ceramic thin-film printhead substrate manufacturing exhibits extreme scale economies, with Japan and South Korea controlling 70% of global capacity. This concentration creates asymmetric pricing power for upstream suppliers while forcing downstream OEMs into long-term offtake commitments that set effective price floors for enterprise-grade hardware.
Pricing Analysis
Next-generation 600 dpi micro-thermal arrays command 40-60% premiums over legacy 200-300 dpi metal-alloy printheads, while prior-generation desktop units face accelerated obsolescence under Japan METI standby power regulations. Three-tier pricing structure across premium ceramic-substrate systems, standard wax-resin configurations, and economy direct-thermal hardware dominates procurement. Price differentiation rests on REACH compliance certification and printhead duty-cycle ratings. Cost compression in economy desktop segments is intensifying because Chinese OEMs are flooding Asia-Pacific distribution channels. Small-format retail operators in India and Brazil exhibit highest price sensitivity, while Amazon and DHL logistics operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Inventory buffers for ceramic heating elements have compressed from 12 weeks to 6 weeks as Yangtze River Delta manufacturing clusters struggle with energy rationing. Supply concentrates in Japan, South Korea, and China for printhead substrates, with Germany and the Netherlands anchoring ribbon coating and conversion. Raw material flows draw from rare-earth ceramics, polyimide films, and resin formulation chemicals. Single-source vulnerability in ceramic thin-film supply creates structural risk for OEMs dependent on Kyocera or Rohm substrate supply. Distribution runs through authorized distributor networks in developed markets and direct OEM relationships in emerging Asia-Pacific corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal printing exhibits durable defensive moats through regulatory entrenchment: REACH and FDA compliance requirements create certification barriers that lock out unqualified suppliers and embed incumbents within customer workflows.
For Market Incumbents: Shield market position by deepening backward integration into ceramic substrate manufacturing to neutralize Japan-South Korea supply concentration risk. Prioritize hybrid architecture R&D to capture contract packaging houses serving multiple verticals. Resin formulation chemist scarcity in Europe threatens ribbon coating timelines—invest in captive formulation capabilities or risk surrendering EU grocery retail chain contracts to competitors with REACH-ready product lines. For New Entrants and Emerging Players: Anchor in Indian cold chain infrastructure where FSSAI-mandated food traceability is creating first-time thermal transfer demand without entrenched supplier relationships. Target refrigerated logistics corridors between Mumbai and Delhi with localized service capabilities that multinational OEMs underserve. Pursue equipment-as-a-service contracts with bundled consumable replenishment to bypass capital purchase barriers among mid-market logistics providers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-enabled fleet management platforms with predictive maintenance algorithms that embed printers within customer operations. Long-term viability favors hybrid-architecture specialists with dual-mode patent portfolios over pure-play direct thermal assemblers facing inkjet substitution. Watch for inflection when CSRD corporate sustainability reporting mandates accelerate thermal-over-laser displacement in enterprise document workflows—this signal indicates consumable revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Kyocera and Rohm supply concentration creates margin vulnerability for hardware OEMs without captive substrate production. |
| Hybrid Architecture Development | Dual-mode direct-transfer flexibility captures contract packaging houses serving pharmaceutical, food, and textile verticals simultaneously. |
| REACH-Compliant Resin Formulation | Bisphenol-A restrictions on direct thermal paper are accelerating ribbon-based system adoption in European grocery retail. |
| Cloud-Enabled Fleet Management Platform | Amazon and DHL operators specify predictive maintenance algorithms that compress replacement cycles and embed vendor relationships. |
| Geographic Expansion through Distributor Acquisition | Vietnamese and Bangladeshi garment hubs require localized thermal transfer support for EU and US care label compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork. Logistics fleet managers at JD.com, Amazon, and DHL facilities, ribbon coating chemists at European converters, and procurement officers at German contract logistics operators provided operational data. Secondary validation drew from MIIT equipment efficiency filings, ECHA REACH substance registrations, FDA food contact material guidance, and customs trade data for ceramic substrate flows. Bottom-up unit economics for printer deployments were triangulated against top-down market sizing from hardware OEM revenue disclosures.
Across the analysis window, volume and value outputs reflect segmented modeling across product type (direct thermal, thermal transfer, hybrid, mobile), technology tier (wax, wax-resin, resin-based, dye sublimation), application vertical, and end-user category. CAGRs were derived from logistic curve fitting to historical replacement cycle data and projected e-commerce fulfillment density trajectories. Key inputs included warehouse automation capex forecasts, REACH chemical restriction implementation timelines, and METI energy efficiency standard phase-in schedules.
Material uncertainties — tariff escalation on Chinese-manufactured hardware, ceramic substrate supply disruptions, and accelerated inkjet substitution in pharmaceutical serialization — sit outside the modeled envelope. Forecasts reflect documented assumptions about replacement cycle compression and hybrid architecture adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Global Inkjet Coders Market
Printers
Global Ticket Printers Production Market
Printers
Portable Printer Market
Printers
Dot Matrix Printer Market
Printers
Mobile Photo Printer Market
Printers
Ink Tank Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Photocopiers Market
Printers
Laser Printer Market
Printers
Continuous Inkjet Printers Market
Printers
Printer Ribbons Market
Printers
Mobile Printer Market
Printers
Aerosol Printing and Graphics Market
Printers
Inkjet Printing Market
Printers
Copier, MFP and Printer Market
Printers
Global Thermal Inkjet Print-Heads Market