
 India Inkjet Printer Market | 2026-2036
India Inkjet Printer Market Size, Share, and Industry Trends Forecast 2026-2036
India Inkjet Printer Market Foresight
Subscription-based ink replenishment and managed print services is realigning how vendors monetize hardware placements in India. HP Inc. leverages its Instant Ink program to lock in recurring revenue from home and small office segments. Canon India Pvt. Ltd. anchors its position through extensive service center networks that reduce downtime for commercial users. Brother International India Pvt. Ltd. specializes in compact all-in-one units tailored to space-constrained urban small offices.
An inkjet printer propels droplets of liquid ink onto substrates using thermal or piezoelectric actuation, achieving resolutions up to 9600 x 2400 dots per inch for photographic and fine-detail commercial output. The technology serves document production, marketing collateral, and textile prototyping across Indian enterprises. All-in-One configurations lead volume shipments as Small Office and Educational Institutions consolidate scanning, copying, and printing into single footprints. UV Inkjet systems represent the fastest-expanding technology segment, driven by signage and packaging converters in Gujarat and Tamil Nadu seeking instant-cure durability on non-porous media. Single Function units remain mature, occupying price-sensitive entry tiers where home users prioritize capital outlay over feature breadth.
BIS mandatory registration schemes for electronic products constrain import pathways and force compliance investments from overseas manufacturers. CDSCO and FSSAI frameworks indirectly shape demand by governing label and packaging standards in pharmaceutical and food sectors that rely on coded inkjet output. The CEA's energy efficiency labeling program nudges procurement toward qualified models in government and institutional tenders. Stakeholders must monitor how PLI scheme extensions for electronics manufacturing alter domestic assembly economics and vendor sourcing strategies.
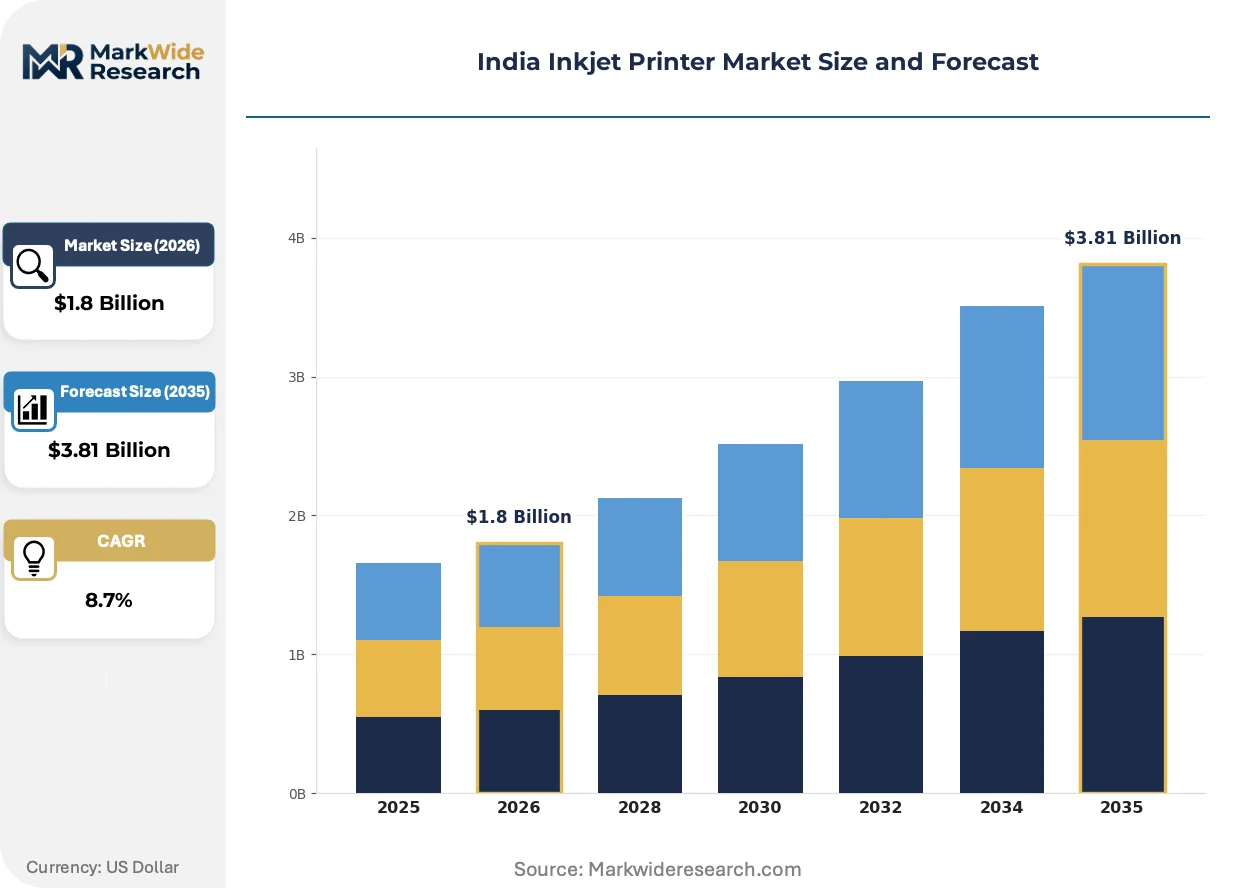
Market Dynamics
Subscription-based ink replenishment and managed print services are restructuring vendor revenue models across India, locking hardware placements into recurring revenue streams and reducing upfront capital barriers for SME buyers.
Growth Catalysts
- BIS Mandatory Registration Scheme:Tightened import standards for electronic products are accelerating domestic assembly investments and reshaping vendor qualification pathways.
- Educational digitization:State government hybrid learning mandates in Maharashtra and Karnataka are sustaining multi-function device procurement cycles across public institutions.
- UV Inkjet technology:Instant-cure durability on non-porous media is displacing solvent-based systems in Gujarat and Tamil Nadu packaging converters.
Market Restraints
- Import dependency for printheads:Concentrated supply from Japanese and German precision manufacturers exposes assemblers to currency volatility and shipping delays.
- BIS compliance timelines:Extended product registration cycles for new models compress launch windows and strain working capital.
- Laser printer substitution:Lower per-page costs in high-volume office environments limit inkjet penetration above 5,000 monthly impressions.
Strategic Opportunities
- Tier-2 city underpenetration:Indore, Lucknow, and Kochi present whitespace for compact all-in-one distribution as SME density rises.
- PLI scheme extensions:Electronics manufacturing incentives are reducing landed cost disadvantages for domestic assembly versus imports.
- Textile prototyping convergence:Direct-to-garment inkjet systems are capturing sampling workflows from screen-printing in Surat and Tiruppur clusters.
Industry Challenges
- Service technician scarcity:Shortage of trained personnel for piezoelectric printhead calibration and UV curing system maintenance extends resolution times.
- Legacy ERP integration:Fleet management software deployment encounters friction with state government procurement platforms and educational institution accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Inkjet Printer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Function, All-in-One, Commercial, Industrial Technology: Thermal Inkjet, Piezoelectric, Continuous Inkjet, UV Inkjet End User: Home, Small Office, Large Enterprise, Educational Institutions Print Media: Photo Paper, Plain Paper, Glossy Paper, Others |
| Companies Covered | Brother International India Pvt. Ltd., Ricoh India Limited, HP Inc., Konica Minolta Business Solutions India Pvt. Ltd., Xerox India Ltd., Canon India Pvt. Ltd., ColorJet India Limited, Pantum International Ltd (India Operations), Seiko Epson Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Inkjet Printer Market Shifts & Advancements
Hardware monetization models and substrate versatility are converging to redefine competitive positioning, with durability requirements and subscription economics displacing traditional ownership structures.
UV-curable inkjet systems achieve instant polymerization through LED exposure, eliminating volatile solvent emissions and reducing drying infrastructure. Packaging converters in Gujarat and Tamil Nadu are adopting these systems at accelerating rates for corrugated and flexible film applications. The technology is expanding into industrial label production and rigid container decorating, compressing lead times from design to finished goods.
BIS mandatory registration schemes for electronic imports now require factory audits and local representative appointments for overseas manufacturers. The industrial consequence is a filtering of vendor participation toward entities with compliance infrastructure and capital reserves. Commercial and institutional segments are responding by consolidating procurement around qualified suppliers with demonstrated certification continuity.
Managed print service contracts are displacing equipment ownership in SME and educational segments, bundling hardware, consumables, and maintenance into per-page fees. Channel partners in Pune and Bangalore are restructuring sales compensation around contract lifetime value rather than upfront margin. State government digitization tenders increasingly specify service-level agreements over capital purchase frameworks.
India Inkjet Printer Market Segmentation
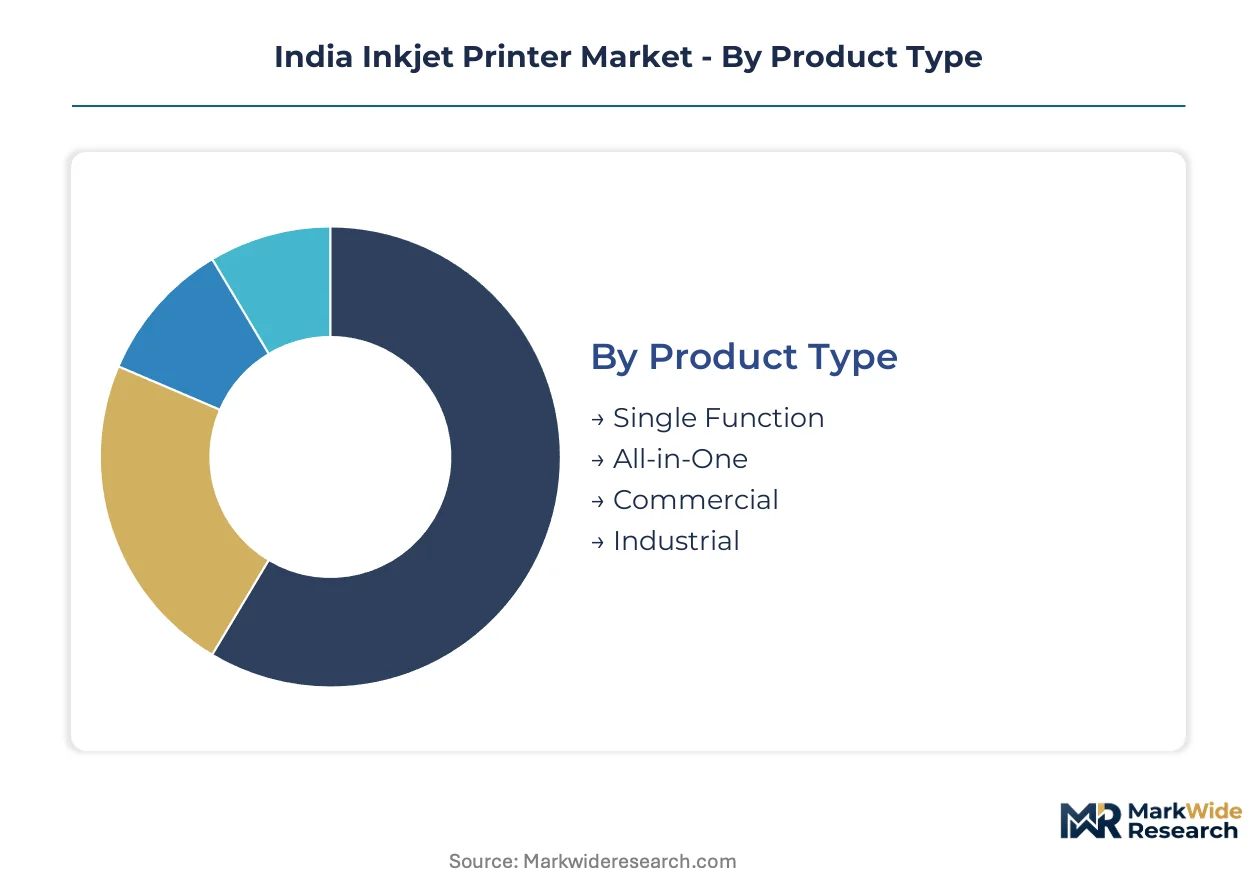
Hardware refresh cycles in India vary sharply across user profiles and technology tiers. Segmentation reveals where replacement demand concentrates versus where first-time adoption is still expanding.
Product Type:
Upgrade urgency differs by installed base age and feature integration requirements across Indian households and enterprises.
- All-in-One:Combines printing, scanning, and copying in single footprints with automatic document feeders and wireless connectivity. Small offices in Pune and Bangalore are replacing standalone units to consolidate desk space and reduce multiple vendor relationships.
- Single Function:Dedicated printing hardware without scanning or copying capabilities. Home users in price-sensitive tiers prioritize capital outlay minimization over feature breadth.
- Commercial:High-duty-cycle hardware engineered for 2,000-10,000 monthly impressions with reinforced paper handling mechanisms. Marketing agencies in Mumbai deploy these for client collateral production.
- Industrial:Production-scale systems with continuous feed mechanisms and specialized ink chemistry for manufacturing environments. Textile converters in Surat sample direct-to-garment workflows on these platforms.
Volume placements concentrate in All-in-One configurations; the faster expansion belongs to Industrial systems.
Technology:
Actuation method determines resolution ceiling, substrate compatibility, and total cost of ownership for Indian buyers.
- UV Inkjet:LED-triggered instant polymerization enables printing on non-porous corrugated and flexible films without solvent emissions. Packaging converters in Gujarat and Tamil Nadu are displacing thermal drying infrastructure with these systems.
- Thermal Inkjet:Resistive heating creates vapor bubbles that eject ink droplets through precision nozzles. Home and small office segments in Maharashtra favor these for photographic output quality at accessible price points.
- Piezoelectric:Ceramic crystals deform under voltage to mechanically propel ink without thermal stress on formulation chemistry. Commercial users requiring pigment-based archival stability specify these systems.
- Continuous Inkjet:Pressurized ink streams with electrostatic deflection enable high-speed marking on production lines. Pharmaceutical packagers deploy these for batch coding under CDSCO labeling mandates.
Shipment value clusters in Thermal Inkjet; the steepest expansion trajectory is UV Inkjet.
End User:
Procurement authority and budget cycles shape how vendors structure pricing and service attachments.
- Small Office:5-50 employee establishments with centralized printing needs and limited IT support. Brother and Canon channel partners in tier-2 cities target these with compact all-in-one bundles.
- Educational Institutions:State government and private universities with hybrid learning mandates. Karnataka's public school digitization program sustains multi-function device tenders with service-level specifications.
- Home:Individual consumers with intermittent printing requirements and high price elasticity. HP's Instant Ink subscription reduces upfront cartridge costs for this segment.
- Large Enterprise:Corporate headquarters and shared service centers with centralized fleet management. These buyers negotiate managed print contracts with per-page pricing and uptime guarantees.
Unit volume leadership sits with Home users; margin capture concentrates in Large Enterprise.
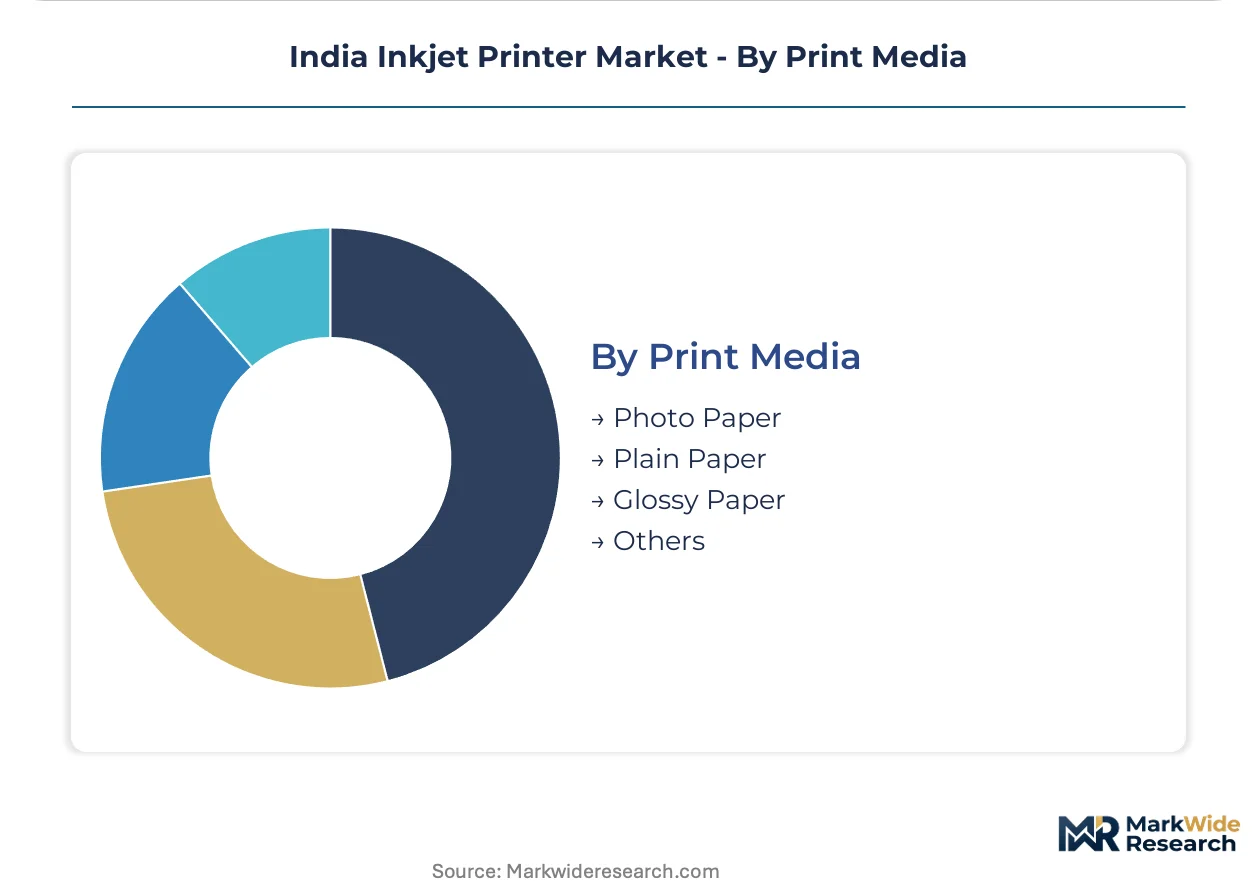
Print Media:
Surface chemistry and coating specifications determine ink absorption profiles and output durability.
- Plain Paper:Uncoated cellulose stock for everyday document production with rapid absorption and minimal smearing. Government offices and educational institutions procure this in bulk for administrative output.
- Photo Paper:Resin-coated or microporous surfaces engineered for dye and pigment ink retention with gloss or matte finishes. Wedding photography studios in Delhi and Chennai specify premium grades for album production.
- Glossy Paper:High-reflectivity coated stock for marketing collateral requiring visual impact. Real estate developers in Bangalore use these for property brochures.
- Others:Textile substrates, synthetic films, and specialty media for prototyping and industrial applications. Surat textile clusters experiment with cotton-polyester blends on direct-to-garment systems.
Consumption tonnage dominates Plain Paper; value per sheet climbs fastest in Photo Paper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly capacity concentrates in western and southern manufacturing corridors, while consumption spreads across state capitals and tier-2 urban clusters. The production-consumption divide creates logistics arbitrage opportunities for regional distributors. State-level digitization programs and SME clustering patterns shape hardware refresh cycles.
Maharashtra
Mumbai-Pune corridor drives commercial inkjet demand from marketing agencies and financial services. The state's public procurement framework mandates BIS-certified equipment in government tenders. SME clusters in Pimpri-Chinchwad sustain multi-function device replacement cycles.
Karnataka
Bangalore's technology parks and startup ecosystem generate concentrated demand for compact all-in-one units. State government hybrid learning directives sustain educational institution procurement. Mysuru and Mangalore emerge as secondary distribution nodes.
Gujarat
Packaging converters in Ahmedabad and Vadodara adopt UV inkjet systems for corrugated and flexible film applications. The state's electronics manufacturing incentives under PLI schemes attract domestic assembly investments. Surat textile clusters experiment with direct-to-garment sampling workflows.
Tamil Nadu
Chennai's automotive and electronics manufacturing base drives industrial inkjet marking applications. Coimbatore's SME density supports compact printer distribution networks. Tiruppur garment exporters deploy inkjet systems for rapid prototyping.
Delhi-NCR
Government headquarters and corporate shared service centers sustain managed print contract demand. Noida and Gurgaon warehousing infrastructure enables northern region distribution. Educational institutions across the capital refresh hardware under central government digitization schemes.
India Inkjet Printer Market Competitive Landscape
Top-tier vendors anchor premium commercial and industrial segments, while mid-tier specialists capture SME and educational procurement through service network density. The market structure reflects tiered certification requirements and working capital constraints that filter vendor participation. Three strategic archetypes dominate: multinational hardware manufacturers with subscription monetization models, domestic assemblers leveraging PLI scheme incentives, and regional service integrators bundling maintenance contracts. Competitive moves concentrate on BIS compliance infrastructure investments and channel partner compensation restructuring around recurring revenue metrics.
Among Japan-origin manufacturers, Brother International India Pvt. Ltd., Seiko Epson Corporation, and Canon India Pvt. Ltd. exemplify the premium hardware archetype with established service center networks. HP Inc. occupies a distinct position through subscription-based ink replenishment programs targeting home and small office segments. Domestic specialists ColorJet India Limited and Pantum International Ltd anchor the cost-optimized tier for price-sensitive entry markets.
| Leading Market Players |
|---|
| Brother International India Pvt. Ltd. |
| Ricoh India Limited |
| HP Inc. |
| Konica Minolta Business Solutions India Pvt. Ltd. |
| Xerox India Ltd. |
| Canon India Pvt. Ltd. |
| ColorJet India Limited |
| Pantum International Ltd (India Operations) |
| Seiko Epson Corporation |
| Others |
Supply & Pricing Matrix
Government tender concentration in Maharashtra and Karnataka anchors contract-based pricing for institutional procurement, with BIS certification tiers separating qualified vendors from price-only competitors. Subscription models for home users run parallel, creating divergent pricing architectures across buyer archetypes.
Pricing Analysis
Cost-down pressure on entry-tier hardware accelerates because PLI scheme incentives are compressing domestic assembly premiums against landed imports. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification status and bundled service attachments. Price differentiation hinges on after-sales network density and printhead warranty terms. Home users in tier-3 cities exhibit highest price sensitivity; large enterprises negotiating managed print contracts show lowest elasticity due to uptime guarantees.
Supply Chain Analysis
Dual-sourcing mandates from large enterprise buyers force qualification of multiple printhead suppliers, extending vendor onboarding timelines. Precision printhead manufacturing concentrates in Japan, Germany, and South Korea, with piezoelectric ceramic substrates and thermal actuator arrays as critical inputs. Single-source vulnerability in piezoelectric crystal supply exposes assemblers to allocation constraints. Distribution runs through authorized service integrators in Pune, Bangalore, and Chennai who bundle installation with maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS compliance infrastructure requirements are filtering vendor participation toward capitalized entities, consolidating market structure around qualified suppliers with certification continuity.
For Market Incumbents: Cement service network density in tier-2 cities before domestic specialists exploit PLI scheme assembly cost advantages. Lock educational institutions into multi-year managed print contracts with uptime SLAs to preempt laser substitution above 5,000 monthly impressions. Deepen backward integration into printhead refurbishment capabilities to reduce import dependency exposure. For New Entrants and Emerging Players: PLI scheme extensions in India open a window for cost-optimized assembly targeting price-sensitive home segments in Indore, Lucknow, and Kochi. White-space exists in compact all-in-one distribution where Brother and Canon coverage remains thin. Pursue channel partnerships with regional IT integrators rather than building direct service infrastructure. For Investors and Strategic Acquirers: The window for entry favors domestic assemblers with BIS certification infrastructure and working capital to absorb extended product registration cycles. Acquisition targets should demonstrate demonstrated compliance continuity and state government tender participation. Watch for PLI scheme benefit exhaustion as inflection signal for margin compression in the cost-optimized tier.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Factory audit infrastructure qualifies vendors for Maharashtra and Karnataka government tenders. |
| Managed Print Service Expansion | Per-page pricing models displace capital purchase frameworks in educational digitization programs. |
| UV Inkjet Technology Licensing | Instant-cure systems capture packaging converters in Gujarat and Tamil Nadu from solvent-based alternatives. |
| Backward Integration into Printhead Refurbishment | In-house remanufacturing reduces currency exposure on Japanese and German precision component imports. |
| Tier-2 City Distribution Partnership | Channel alliances in Indore and Lucknow exploit SME density growth with compact all-in-one bundles. |
Research Methodology
Multi-period observation of hardware refresh cycles, BIS registration timelines, and state government procurement volumes anchored the trend analysis, supplemented by interviews with vendor product managers, channel distribution heads, educational institution procurement officers, and packaging converter operations managers. Secondary validation drew from BIS registration databases, DGFT import statistics, state government tender portals, and CEA energy efficiency listings. Bottom-up shipment estimates by product tier were triangulated against top-down value projections.
Input-output matrices modeled unit placements and average selling prices across product type, technology, end user, and regional adoption intensity dimensions. CAGRs were derived from regression analysis of historical replacement patterns and projected digitization program spending. Forecast inputs incorporated PLI scheme incentive schedules, BIS compliance cost trajectories, and UV inkjet technology substitution curves in packaging applications.
The model assumes a particular technology adoption path; alternative pathways for UV curing system penetration in textile prototyping would alter the outlook. Deviation in BIS registration processing timelines or PLI scheme extension decisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
A3 and A4 Multi-Function Printer Market
Printers
NCR Printers Market
Printers
Thermal Inkjet Printer Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
Laser Printer Market
Printers
Nanographic Printing Market
Printers
Continuous Inkjet Printers Market
Printers
Aerosol Printing and Graphics Market
Printers
Mobile Printer Market
Printers
Multi-Functional Printer Market
Printers
Production Printer Market
Printers
Global Printer Market
Printers
Global Thermal Printing Market
Printers
Global UV LED Printers Market
Printers
Portable Printer Market
Printers
Inkjet Printers Market