
 Global Printer Market | 2026-2036
Global Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printer Market Outlook
Aftermarket service revenue is narrowing as a margin pool relative to hardware sales across the installed base. HP Inc. leverages its Instant Ink subscription platform to lock in recurring consumables revenue. Canon Inc. anchors its position through in-house production of printheads and imaging drums. Brother Industries Ltd. competes aggressively in the compact laser segment for home offices and micro-businesses.
A printer is an electromechanical device that deposits ink, toner, or build material onto substrates through controlled nozzle arrays, fuser assemblies, or additive layering heads, typically achieving resolutions from 300 to 2400 dots per inch depending on the technology. Its primary commercial purpose is to transform digital files into physical documents, labels, packaging prototypes, or functional parts across administrative, manufacturing, and creative workflows. Laser printers still command the largest share of enterprise procurement budgets due to lower per-page costs and higher duty cycles, while inkjet systems are gaining ground in industrial printing for corrugated packaging and textile dyeing where piezoelectric heads enable variable droplet sizing. 3D printers represent the fastest-growing product category as manufacturers adopt fused deposition modeling and selective laser sintering for jigs, fixtures, and end-use components in aerospace supply chains.
The EPA regulates volatile organic compound emissions from solvent-based ink formulations in the United States, pushing vendors toward water-based and UV-curable alternatives. REACH restricts phthalates and heavy metals in toner polymers across Europe, while China's SAMR enforces GB standards for electromagnetic compatibility and energy efficiency in office equipment. The EU Green Deal's ecodesign requirements are tightening standby power limits and mandating modular repairability disclosures. Stakeholders must track how regulatory divergence on material bans and right-to-repair mandates fragments compliance costs across manufacturing footprints.
Market Dynamics
Subscription-based consumables models are restructuring revenue capture across the installed base, pulling margin forward from transactional hardware sales into recurring ink and toner streams.
Growth Catalysts
- Managed Print Services (MPS) Penetration:SMBs across the United States and Germany are consolidating fragmented printer fleets under single-vendor service agreements. This reduces total cost of ownership while locking in long-term supply contracts.
- REACH Substance Mandates:European restrictions on phthalates and heavy metals in toner polymers are accelerating R&D investment in bio-based binder resins. OEMs with advanced material science capabilities are capturing specification advantages.
- Industrial Inkjet Expansion:Piezoelectric printhead advances are displacing analog flexography in corrugated packaging converters serving e-commerce fulfillment networks.
Market Restraints
- Toner Feedstock Concentration:Specialty polyester resins and carbon black supply chains concentrate in East Asian chemical complexes, exposing European and North American OEMs to shipping cost volatility and tariff exposure.
- Page Volume Compression:Enterprise digitization of workflows and electronic signature adoption are structurally reducing printed page volumes per employee across administrative functions.
- Right-to-Repair Friction:EU Green Deal modular repairability disclosures are forcing redesign of sealed cartridge architectures, compressing margin on entry-level hardware SKUs.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme benefits for electronics hardware assembly are attracting contract manufacturers to establish printer and component production near Mumbai and Chennai industrial corridors.
- 3D Printing Jigs and Fixtures:Fused deposition modeling adoption in aerospace tier-2 suppliers is creating demand for industrial-grade systems with heated build chambers and soluble support materials.
- UV-Curable Ink Transition:EPA volatile organic compound restrictions on solvent-based formulations are creating specification windows for water-based and UV-curable alternatives in wide-format signage.
Industry Challenges
- Printhead Engineering Talent Scarcity:Piezoelectric actuator design and microfluidic nozzle plate fabrication require specialized electromechanical expertise concentrated in Japan and Germany.
- Legacy Fleet Integration Complexity:Enterprise MPS rollouts must bridge decades of heterogeneous device generations with disparate network protocols and security architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printer Market |
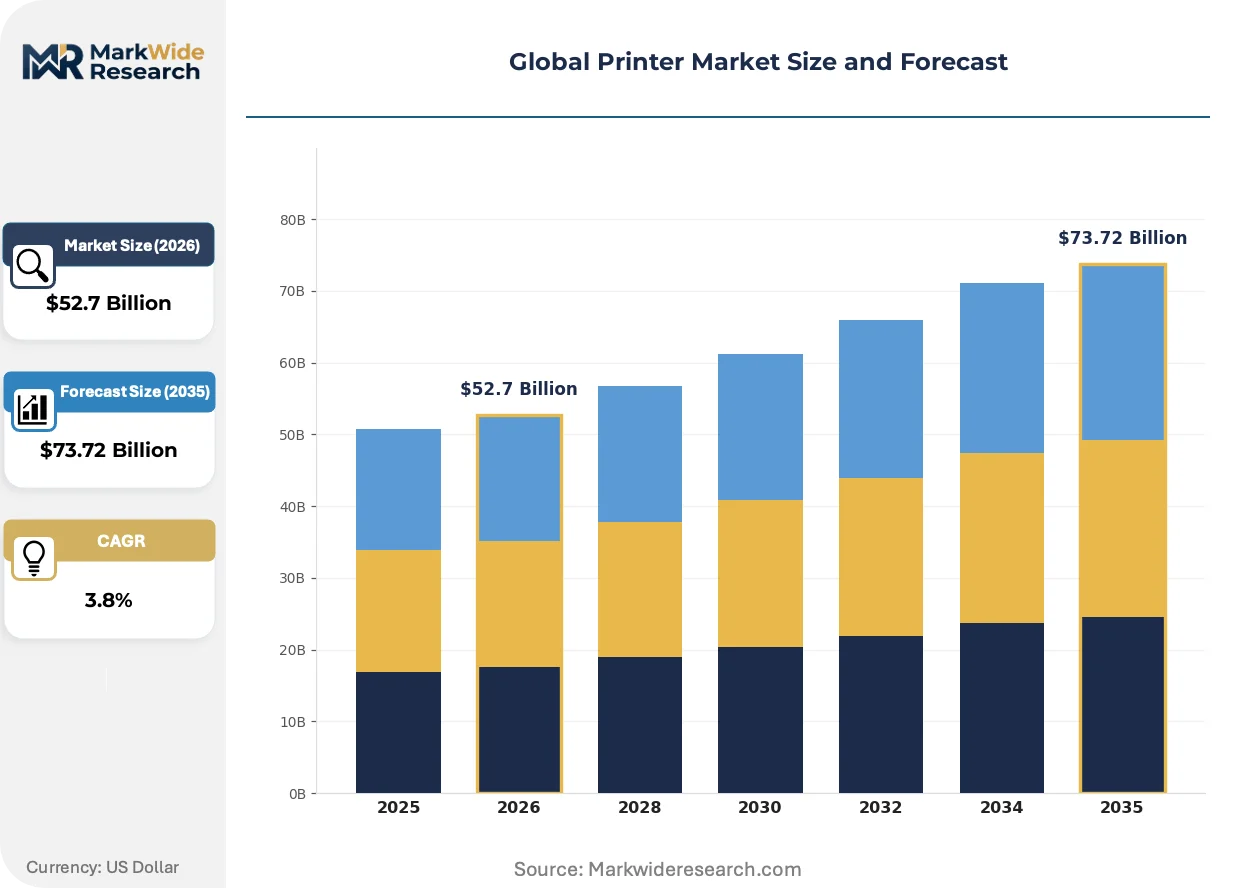
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $73.72 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, Dot Matrix Printers, 3D Printers End User: SMBs, Large Enterprises, Educational Institutions, Government Technology: Thermal, Piezoelectric, LED, Electrostatic Application: Commercial Printing, Home Printing, Industrial Printing, Photo Printing |
| Companies Covered | Xerox Holdings Corporation, Brother Industries Ltd., HP Inc., Kyocera Corporation, Konica Minolta Inc., Canon Inc., Ricoh Company, Ltd., Ninestar Corporation, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printer Market Strategic Shifts
Hardware commoditization is forcing vendors to differentiate through software-locked consumables, predictive maintenance algorithms, and vertical-specific ink formulations rather than mechanical specifications alone.
Continuous inkjet systems for high-speed addressing and direct-to-package marking are migrating from pharmaceutical serialization lines into food and beverage coding applications. Nestlé and PepsiCo bottling facilities are piloting single-pass systems at 300 meters per minute. This migration from pharma to CPG is compressing the addressable market for slower drop-on-demand alternatives in high-volume lines.
China's GB standards for electromagnetic compatibility and energy efficiency in office equipment are tightening standby power limits and mandating disclosure of modular repairability. SAMR enforcement is accelerating local OEM redesign cycles. Domestic brands including Pantum and Lenovo Image are capturing share in government and education procurement by pre-certifying to these standards ahead of multinational competitors.
Consolidated print management platforms are displacing decentralized departmental purchasing across Fortune 500 enterprises. IT procurement teams are mandating cloud-based device monitoring and automated supply replenishment. This shift is most visible in United States healthcare systems where HIPAA-compliant print audit trails have become a non-negotiable selection criterion.
Global Printer Market Segmentation
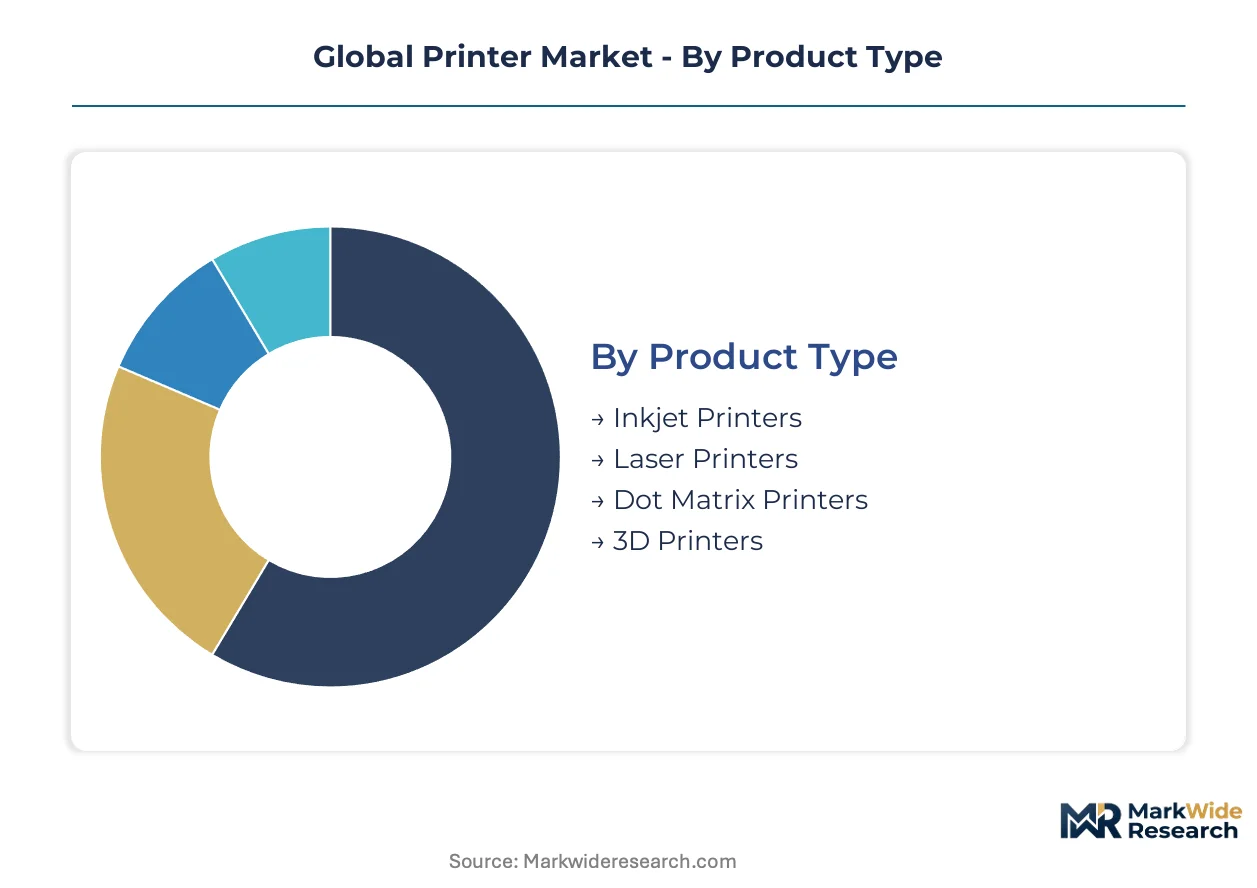
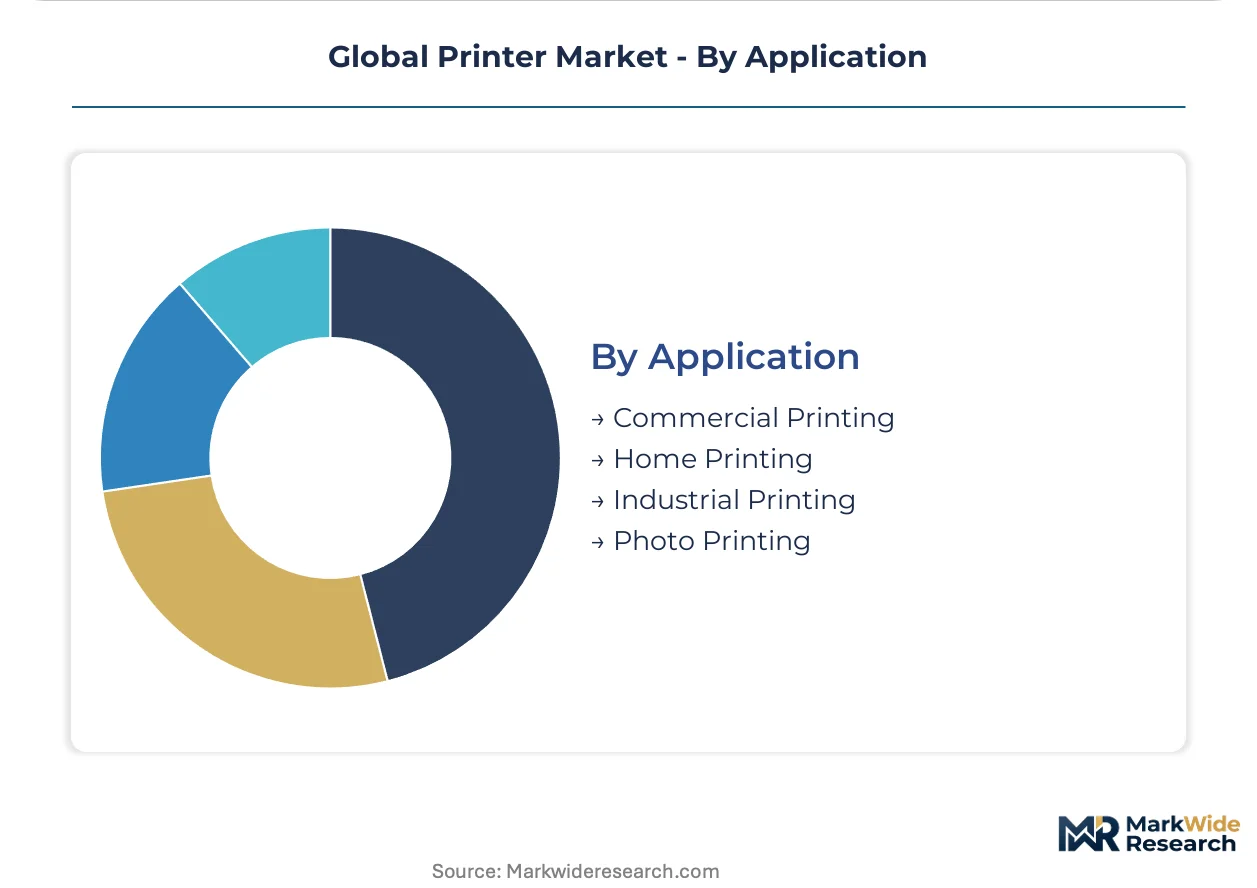
Segmentation reveals how printer vendors allocate R&D resources across diverging performance requirements and duty cycles. Each dimension—product architecture, customer scale, deposition physics, and use case—creates distinct margin profiles and competitive moats.
Product Type:
Mature laser systems dominate enterprise procurement budgets while emerging 3D architectures capture specification premiums in aerospace tooling.
- Inkjet Printers:Piezoelectric and thermal heads deposit aqueous or solvent-based inks through precision nozzle arrays, achieving 1200-4800 DPI resolution. Demand concentrates in Germany and Japan where packaging converters serving e-commerce fulfillment networks require variable data printing on corrugated substrates.
- Laser Printers:Electrophotographic engines fuse toner to paper through heated rollers, delivering 20-70 pages per minute with lower per-page costs than liquid ink alternatives. Large enterprises in the United States consolidate departmental fleets under managed print service agreements to reduce total cost of ownership.
- Dot Matrix Printers:Impact pins strike inked ribbons for multi-part form generation in logistics and banking applications requiring physical document durability.
- 3D Printers:Fused deposition modeling and selective laser sintering build functional jigs, fixtures, and end-use components layer-by-layer from thermoplastics or metal powders.
Laser systems handle the majority of throughput; 3D printers are expanding most quickly on specification premiums in manufacturing supply chains.
End User:
Cost tier segmentation separates volume-committed enterprise contracts from transactional SMB purchases with diverging service expectations.
- SMBs:Micro-businesses and small offices prioritize compact footprints and low acquisition cost over duty cycle ratings. Subscription ink models from HP Inc. and Brother Industries Ltd. lock in recurring revenue across fragmented purchasing decisions in home offices.
- Large Enterprises:Fortune 500 procurement teams mandate cloud-based device monitoring, automated supply replenishment, and HIPAA-compliant audit trails in United States healthcare systems. Consolidated print management platforms displace decentralized departmental purchasing.
- Educational Institutions:K-12 districts and universities balance acquisition budgets against high-volume semester peaks and multi-user network security requirements.
- Government:Federal, state, and municipal agencies enforce Buy American provisions and energy efficiency certifications in public sector tenders.
Large enterprises commit the highest annual contract values; SMBs represent the broadest addressable account base.
Technology:
Application focus determines whether thermal efficiency or droplet precision governs head architecture selection.
- Thermal:Resistive heating elements vaporize ink to eject microdroplets through silicon nozzles, enabling low-cost cartridge manufacturing for consumer photo and document output.
- Piezoelectric:Ceramic actuators deform to pressurize ink chambers, allowing variable droplet sizing and compatibility with UV-curable, solvent, and aqueous formulations in industrial wide-format systems.
- LED:Solid-state light arrays expose photoconductive drums with lower energy consumption and fewer moving parts than laser scanning assemblies in entry-level office equipment.
- Electrostatic:Corona wires or charge rollers deposit uniform surface potentials for toner adhesion in high-speed production printing exceeding 100 pages per minute.
Piezoelectric systems command specification premiums in packaging; LED architectures gain share fastest on energy efficiency mandates.
Application:
Volume concentration separates high-frequency administrative output from intermittent creative and manufacturing use cases.
- Commercial Printing:Print service providers operate cut-sheet and continuous-feed production systems for marketing collateral, transactional documents, and book manufacturing with 24/7 duty cycles.
- Home Printing:Consumer households prioritize wireless connectivity, mobile app integration, and low upfront hardware cost for intermittent document and photo output under 500 pages monthly.
- Industrial Printing:Direct-to-object, textile dyeing, and additive manufacturing systems integrate into automotive and aerospace supply chains for functional part production.
- Photo Printing:Dye-sublimation and pigment ink systems deliver archival-quality output for professional photographers and retail kiosk operations.
Commercial printing absorbs the highest installed base capacity; industrial printing climbs fastest on manufacturing reshoring initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Printer demand concentrates in industrialized economies with dense manufacturing bases, though consumption patterns diverge sharply between document-heavy administrative workflows in Western offices and packaging-intensive production environments across East Asian export hubs.
United States
Fortune 500 healthcare systems and federal agencies drive managed print services consolidation under HIPAA-compliant audit trails. EPA volatile organic compound restrictions on solvent-based inks push wide-format signage vendors toward UV-curable alternatives. Industrial printing clusters in Chicago and Detroit serve automotive supply chains with direct-to-object marking systems.
Germany
Packaging converters in the Rhine-Ruhr corridor deploy piezoelectric inkjet systems for e-commerce corrugated fulfillment. REACH substance mandates on phthalates and heavy metals in toner polymers accelerate bio-based binder R&D at specialty chemical firms. Bavarian industrial zones host precision printhead engineering talent concentrated around Munich automation clusters.
China
Domestic brands capture government and education procurement through pre-certification to SAMR GB standards for electromagnetic compatibility and energy efficiency. Yangtze River Delta manufacturing hubs produce specialty polyester resins and carbon black feedstocks for global toner supply chains. Shenzhen-based contract manufacturers assemble compact laser systems for Southeast Asian export markets.
Japan
Piezoelectric actuator design expertise concentrates in Nagoya and Tokyo metropolitan engineering centers. METI industrial policy supports additive manufacturing adoption for aerospace jigs and fixtures among tier-2 suppliers. Kyushu semiconductor fabrication corridors supply microfluidic nozzle plates for next-generation inkjet architectures.
India
PLI scheme incentives for electronics hardware assembly attract printer component production to Mumbai and Chennai industrial corridors. Educational institutions and state government offices drive demand for low-acquisition-cost inkjet systems with high-volume semester peaks. Karnataka's technology parks incubate cloud-based print management platforms for SMB fleet consolidation.
Global Printer Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The installed base segments between integrated OEMs controlling printhead fabrication and consumables chemistry, and contract assemblers competing on manufacturing cost. Strategic archetypes include subscription-platform operators capturing recurring ink revenue, precision component specialists defending specification premiums, and volume manufacturers exploiting PLI incentives in emerging production hubs. Competitive moves center on vertical integration into consumables supply and cloud-based fleet management software deployment.
Among diversified technology conglomerates, HP Inc., Canon Inc., and Brother Industries Ltd. exemplify contrasting strategic postures. HP Inc. anchors the subscription-model archetype through locked consumables platforms. Canon Inc. represents integrated manufacturing with in-house production of imaging drums and deposition hardware. Brother Industries Ltd. occupies the compact-system specialist tier targeting home office and micro-business procurement decisions with aggressive hardware pricing.
| Leading Market Players |
|---|
| Xerox Holdings Corporation |
| Brother Industries Ltd. |
| HP Inc. |
| Kyocera Corporation |
| Konica Minolta Inc. |
| Canon Inc. |
| Ricoh Company, Ltd. |
| Ninestar Corporation |
| Seiko Epson Corporation |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on specialty polyester resins and carbon black feedstocks determines both the spread between enterprise and entry-level hardware tiers and the geographic configuration of toner manufacturing footprints. OEMs absorb upstream volatility through long-term offtake agreements with East Asian chemical complexes while pushing margin pressure downstream into sealed cartridge architectures.
Pricing Analysis
Long-term managed print service contracts anchor enterprise pricing, locking in recurring consumables revenue through subscription-locked ink and toner platforms. Price differentiation rests on duty cycle ratings and HIPAA compliance certification tiers for United States healthcare procurement. Cost compression in entry-level laser hardware intensifies because right-to-repair mandates force modular redesign of sealed cartridges. SMB buyers exhibit highest price sensitivity, prioritizing acquisition cost over per-page economics, while Fortune 500 procurement teams prioritize total cost of ownership and audit trail compliance.
Supply Chain Analysis
Extended payment terms from Chinese and Japanese chemical suppliers finance working capital for European and North American OEMs assembling hardware in Mexico and Southeast Asia. Raw material dependencies center on specialty polyester resins, piezoelectric ceramics, and microfluidic nozzle plates. Single-source vulnerability concentrates in Kyushu semiconductor corridors supplying actuator fabrication. Distribution runs through authorized dealer networks for enterprise fleets and direct e-commerce channels for compact home office systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
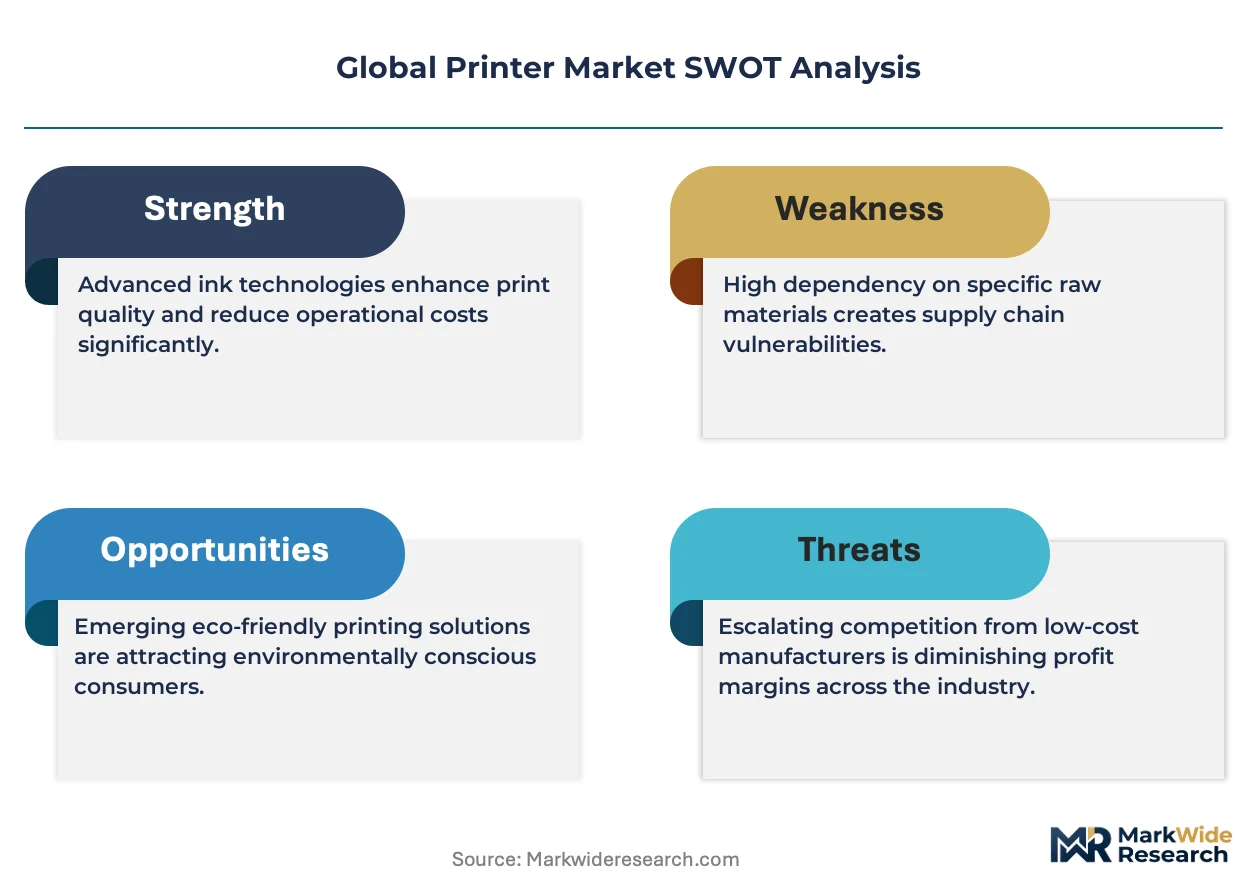
Digital workflow substitution threatens page volume economics, forcing incumbents to defend recurring revenue streams against enterprise digitization and electronic signature adoption.
For Market Incumbents: Build consumables-lock moats through cloud-based fleet management platforms that automate supply replenishment and device monitoring. Capture specification premiums in piezoelectric printhead engineering by deepening in-house production of microfluidic nozzle plates. Defend against REACH substance mandates by accelerating bio-based binder R&D ahead of European regulatory deadlines.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI scheme corridors near Mumbai and Chennai, where government and education procurement favors pre-certified domestic brands. Target compact laser segments for home offices and micro-businesses with aggressive hardware pricing offset by subscription ink revenue. Leverage cloud-based print management platforms as the primary go-to-market angle for SMB fleet consolidation.
For Investors and Strategic Acquirers: The market sits at a substitution-defense phase that favors integrated OEMs with captive consumables chemistry and printhead fabrication capabilities. Long-term viability over the coming decade hinges on recurring revenue attachment rates rather than transactional hardware margins. Watch industrial inkjet penetration in corrugated packaging converters as the signal indicating whether piezoelectric specification premiums can offset administrative page volume compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Expansion | HP Inc.'s Instant Ink model locks recurring revenue across fragmented SMB purchasing decisions. |
| Backward Integration into Printheads | Canon Inc.'s in-house imaging drum production defends margin against commodity hardware competition. |
| PLI Scheme Manufacturing Localization | India's electronics incentives attract component production away from East Asian chemical complexes. |
| UV-Curable Ink Transition | EPA volatile organic compound restrictions create specification windows for water-based alternatives. |
| Cloud Fleet Management Deployment | Consolidated platforms displace decentralized purchasing across United States healthcare systems. |
Study Parameters
Initial hypotheses were tested against primary input from OEM product strategy directors, managed print service operations heads, packaging converter procurement managers, and specialty chemical R&D leads and refined through secondary validation. Primary fieldwork drew from SEC 10-K filings, ECHA REACH substance registrations, Japanese METI industrial policy briefings, and Indian PLI scheme disclosure documents. Bottom-up unit economics from toner resin consumption models were triangulated against top-down market sizing from hardware shipment databases.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, modeling segmentation across product architecture, end-user scale, deposition physics, and geographic regulatory clusters. CAGRs were derived from installed base attrition rates and replacement cycle compression. Industry-specific inputs included piezoelectric printhead adoption curves in corrugated packaging and REACH substance mandate compliance timelines for bio-based binder resins.
Sensitivities concentrate around enterprise digitization velocity, tariff exposure on East Asian chemical feedstocks, and right-to-repair regulatory divergence between European and North American jurisdictions. Forecasts reflect documented assumptions on page volume compression rates and industrial inkjet displacement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Retail Printers and Consumables Market
Printers
Continuous Inkjet Printers Market
Printers
Photocopiers Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Refurbished Printers Market
Printers
Mobile Printer Market
Printers
Global Thermal Printing Market
Printers
Aerosol Printing and Graphics Market
Printers
Production Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Nanographic Printing Market
Printers
Mobile Photo Printer Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
Indonesia Thermal Printer Market
Printers
Inkjet Printers Market
Printers
Electrophotographic Printing Market