
 Photocopiers Market | 2026-2036
Photocopiers Market Size, Share, and Industry Trends Forecast 2026-2036
Photocopiers Market Outlook
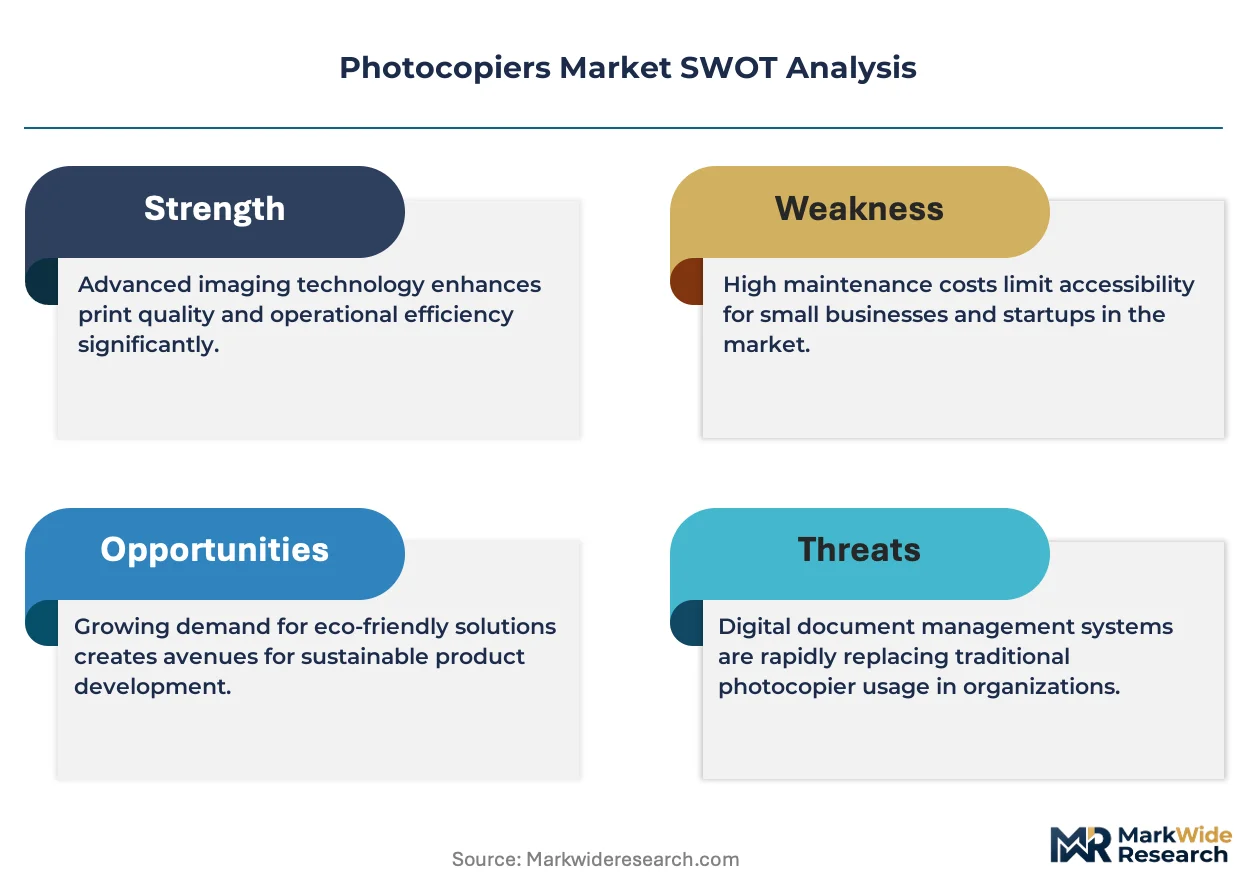
A widening capital-intensity gap between installed-base servicers and full-stack manufacturers is bifurcating competitive returns. Canon Inc. leverages its in-house optical engine production to control component costs across mid-volume segments. Xerox Holdings Corp. sustains a service-led model that anchors recurring revenue through managed print contracts in North American corporate accounts. Ricoh Co. Ltd. differentiates through cloud-integrated document platforms that extend hardware utility beyond standalone copying functions.
A photocopier is an electrostatic reproduction device that transfers toner or ink onto paper through either laser-induced photoconductive drum imaging or liquid inkjet deposition, typically operating at resolutions between 600 and 2400 dots per inch for commercial document output. Its primary purpose is high-speed, cost-efficient duplication of text and graphics in office, educational, and production environments. Multifunction Devices now capture the dominant margin pool as buyers consolidate printing, scanning, and fax capabilities into single footprints. Digital Copiers continue displacing residual analog installations, though replacement cycles have lengthened as document digitization reduces page volumes. Laser technology leads the technology segment for monochrome corporate deployment, while LED engines gain traction in compact desktop units where thermal efficiency matters.
EPA Energy Star certification and EU Ecodesign regulations mandate standby power thresholds and toner cartridge recyclability standards that reshape product development priorities for manufacturers selling across North America and Europe. Japan's METI administers Top Runner efficiency standards that push domestic producers toward lower-melting-point toner formulations and sleep-mode power draw below one watt. Stakeholders must weigh whether to prioritize hardware refresh cycles in developed markets against extended service contracts in regions where regulatory pressure on e-waste recovery intensifies.
Market Dynamics
Hybrid work models have permanently altered page-volume economics, forcing manufacturers to pivot from per-page revenue models toward managed service platforms that monetize workflow integration rather than toner consumption.
Growth Catalysts
- India's manufacturing digitization:Small and medium enterprises in Gujarat and Tamil Nadu are replacing manual documentation with networked multifunction devices, creating fresh hardware demand in a previously underserved segment.
- EU Ecodesign standby mandates:Sub-one-watt sleep-mode requirements are accelerating replacement of installed base units manufactured before 2019, particularly in German and French corporate fleets.
- LED engine thermal efficiency:Compact desktop units utilizing LED arrays instead of laser scanning assemblies now penetrate home office segments where heat dissipation constraints previously excluded copier-class devices.
Market Restraints
- Rare earth magnet supply concentration:Neodymium-dependent brushless motors in high-speed fuser assemblies face input cost volatility tied to Chinese export quota policies.
- Analog residual lock-in:Southeast Asian public sector procurement rules in Indonesia and Vietnam still specify repairable mechanical components, delaying full digital transition.
- Document digitization substitution:Native digital workflows in financial services and legal verticals now bypass print reproduction entirely for internal document circulation.
Strategic Opportunities
- Vietnam's industrial zone expansion:Foreign direct investment in electronics assembly is creating demand for high-volume production copiers in Ho Chi Minh City and Bac Ninh industrial corridors.
- Cloud-integrated document platforms:Convergence of optical character recognition with blockchain notarization enables new revenue streams in contract-heavy industries.
- South Korea's green procurement incentives:Public sector tenders now award technical points for devices meeting MFDS-aligned e-waste recovery standards, favoring modular designs with replaceable subassemblies.
Industry Challenges
- Firmware cybersecurity certification:ISO 27001-aligned device hardening requirements extend product development timelines by eight to fourteen months for networked multifunction units.
- Legacy fleet integration complexity:Corporate IT departments struggle to unify authentication protocols across fifteen-plus year installed base equipment from multiple OEM generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photocopiers Market |
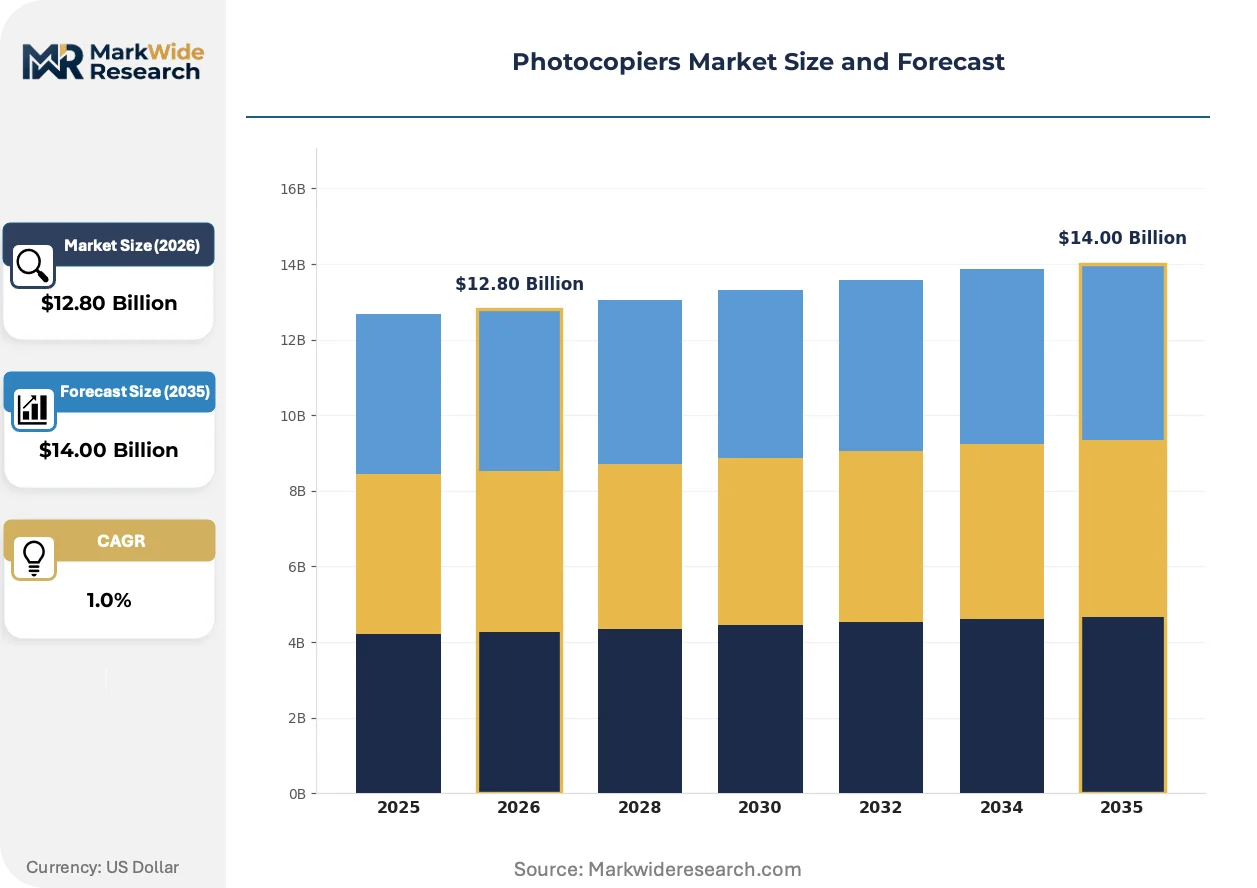
| Market Size in 2026 | $12.80 Billion |
| Market Size in 2035 | $14.00 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Copiers, Digital Copiers, Multifunction Devices, Production Copiers Technology: Laser, Inkjet, Solid Ink, LED End User: Corporate Offices, Educational Institutions, Government Agencies, Print Shops Capacity: Low Volume, Medium Volume, High Volume, Continuous Feed |
| Companies Covered | Canon Inc., Ricoh Co. Ltd., HP Inc., Xerox Holdings Corp., Konica Minolta Inc., Brother Industries Ltd., Sharp Corp., Kyocera Document Solutions, Seiko Epson Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photocopiers Market Strategic Shifts
Electrophotographic hardware is converging with software-defined workflow tools, transforming standalone reproduction equipment into networked document infrastructure nodes that capture metadata and automate compliance routing.
LED-based imaging arrays are displacing traditional laser scanning units in compact monochrome devices. Japanese and Taiwanese component suppliers now dominate this subassembly category. Small law practices and accounting partnerships in Australia and Canada adopt these units for desktop deployment where space constraints previously mandated centralized floor models.
Japan's METI Top Runner program mandates annual efficiency improvements in commercial imaging equipment. Domestic manufacturers must demonstrate lower-melting-point toner formulations and reduced warm-up energy draw to maintain market access. This regulatory pressure cascades through supply chains, requiring reformulation of polyester resin binders and wax release agents across all production destined for Japanese corporate accounts.
Corporate buyers now unbundle hardware acquisition from service contracts, negotiating separate vendors for device supply and managed print services. This procurement fragmentation pressures traditional full-stack manufacturers while creating openings for independent service organizations in North American and Western European markets. Financial services verticals in London and New York lead this disaggregation pattern, driven by procurement department mandates for supplier diversity and cost transparency.
Photocopiers Market Segmentation
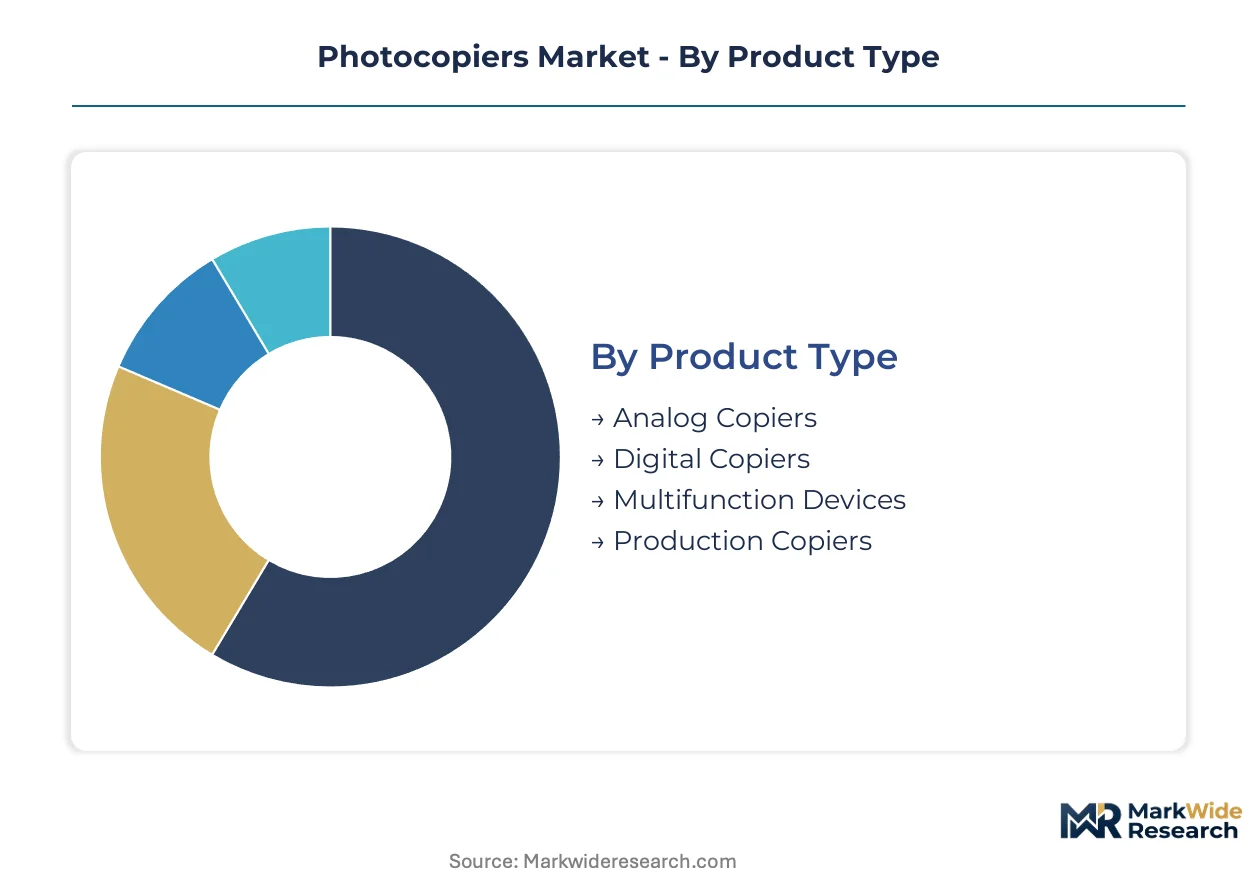
Photocopier segmentation reveals how substitution pressures from digital workflows concentrate differently across hardware categories. Buyers now unbundle acquisition decisions, forcing manufacturers to defend position in specific tiers rather than across entire product lines.
Product Type:
Digital workflows exert uneven substitution pressure across product categories, with standalone single-function hardware facing the steepest demand erosion while integrated platforms capture displaced value.
- Multifunction Devices:Integrated platforms combining printing, scanning, fax, and copying in single footprints now dominate procurement specifications for corporate and SME accounts. Buyers in India and Southeast Asia concentrate orders here as they digitize paper-based processes and consolidate device counts.
- Digital Copiers:Standalone digital reproduction hardware continues displacing analog installations through superior resolution and network connectivity, though replacement cycles lengthen as page volumes decline. German and French corporate fleets accelerate refresh under EU Ecodesign standby mandates.
- Analog Copiers:Mechanical imaging systems persist in Indonesian and Vietnamese public sector procurement where repairability requirements delay full digital transition.
- Production Copiers:High-speed continuous-feed systems serve commercial print shops and in-plant operations requiring 100+ pages per minute throughput.
Multifunction Devices anchor the volume base while Production Copiers gain share at the steepest rate in Vietnam's expanding industrial corridors.
Technology:
Cost tier differentiation separates premium laser engines from compact LED alternatives, with thermal efficiency becoming the decisive specification for space-constrained deployments.
- Laser:Laser-induced photoconductive drum imaging delivers 600-2400 DPI resolution for monochrome corporate deployment. North American corporate accounts specify these engines for high-volume floor models where speed and toner economy outweigh acquisition cost.
- LED:Solid-state LED imaging arrays eliminate scanning mirror assemblies, reducing thermal output and enabling desktop-class form factors. Australian and Canadian professional practices adopt these units where heat dissipation constraints previously excluded copier-class hardware.
- Inkjet:Liquid deposition systems serve low-volume color applications in educational and home office segments.
- Solid Ink:Wax-based color technology persists in niche graphic arts applications requiring substrate flexibility.
Laser technology commands the installed base while LED engines expand most quickly in compact desktop segments.
End User:
Application-specific workflow requirements segment demand by document security protocols, volume profiles, and compliance routing needs.
- Corporate Offices:Hybrid work models have permanently altered page-volume economics for enterprise accounts, forcing pivot from per-page revenue toward managed service platforms. North American corporate buyers now unbundle hardware from service contracts.
- Educational Institutions:K-12 and university procurement concentrates on networked multifunction units with authentication protocols for student billing. Budget constraints favor extended service contracts over hardware refresh.
- Government Agencies:Public sector tenders in South Korea award technical points for MFDS-aligned e-waste recovery standards, favoring modular designs with replaceable subassemblies.
- Print Shops:Commercial reproduction services demand production-class continuous-feed systems for high-margin variable data printing.
Corporate Offices anchor the volume base while Government Agencies gain share at the steepest rate under green procurement incentives.
Capacity:
Customer type and volume scale determine specification tiers, with mid-range segments facing the most intense competitive pressure from adjacent categories.
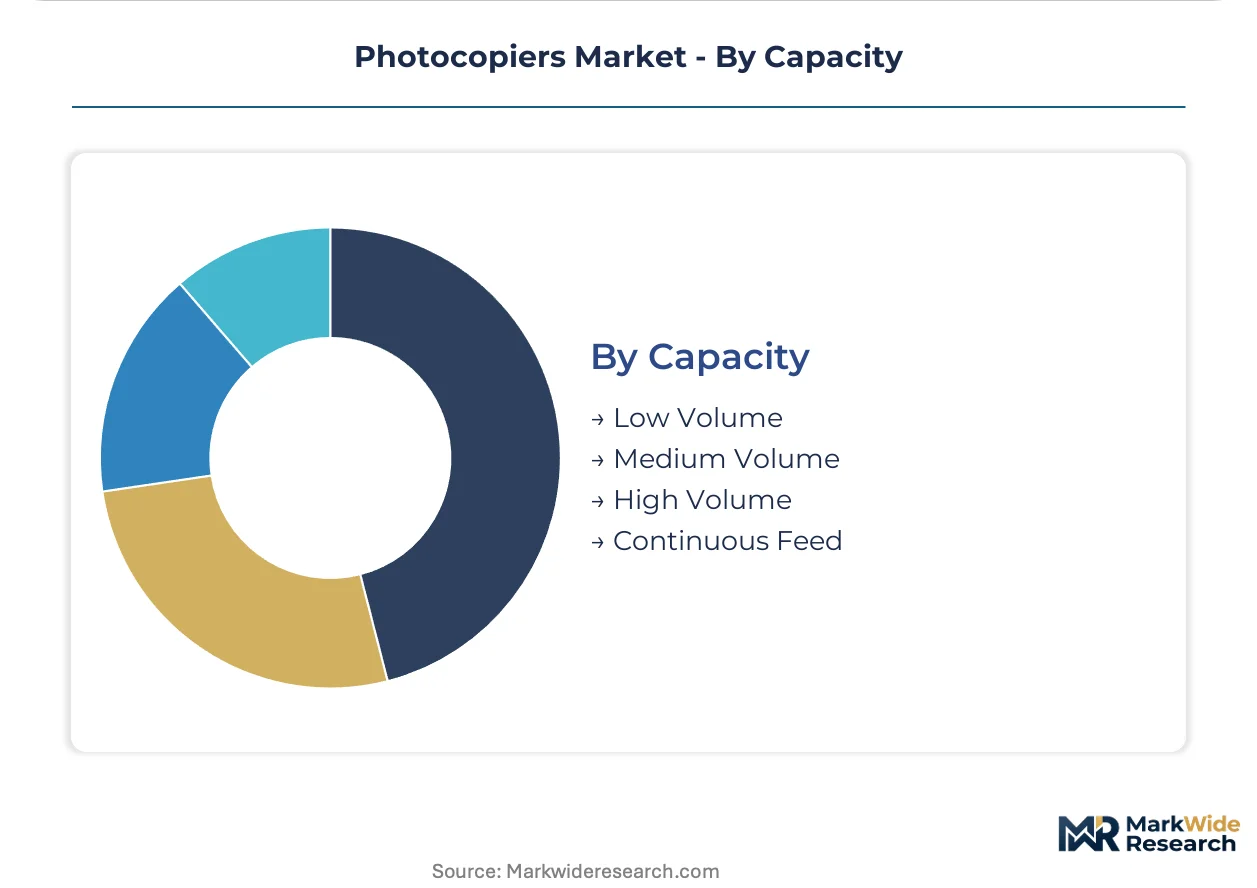
- Medium Volume:20-50 pages per minute devices serve departmental deployments in mid-sized enterprises. This segment faces squeeze from low-volume multifunction units below and high-volume production systems above.
- High Volume:50-100 pages per minute systems anchor managed print service contracts in corporate accounts where manufacturers monetize workflow integration rather than toner consumption.
- Low Volume:Desktop units under 20 pages per minute serve home offices and small professional practices.
- Continuous Feed:Roll-fed production systems serve commercial print and in-plant operations requiring uninterrupted long-run output.
Medium Volume devices anchor the volume base while Continuous Feed systems gain share at the steepest rate in Vietnam's electronics assembly zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German corporate fleets command pricing premiums through managed print service contracts, while Indian SME clusters negotiate hardware-only procurement that compresses manufacturer margins. This asymmetry reflects divergent workflow maturity and regulatory enforcement intensity across developed and emerging demand centers.
Germany
Corporate fleet refresh cycles accelerate under EU Ecodesign standby mandates requiring sub-one-watt sleep modes. The Federal Environment Agency enforces compliance through procurement technical specifications. Manufacturing documentation digitization in Baden-Württemberg automotive supplier parks drives multifunction device deployment.
United States
North American corporate accounts unbundle hardware acquisition from managed print services, fragmenting traditional vendor relationships. EPA Energy Star certification thresholds shape product qualification for federal procurement. Financial services verticals in Manhattan and Chicago lead disaggregation patterns through procurement department mandates.
Japan
METI Top Runner efficiency standards cascade through domestic supply chains, mandating lower-melting-point toner formulations. The program requires annual demonstrated improvements in warm-up energy draw. Nagoya-area precision manufacturing clusters anchor domestic demand for high-resolution production systems.
India
SME digitization in Gujarat and Tamil Nadu manufacturing corridors creates first-time hardware demand from paper-based workflows. Bureau of Indian Standards certification requirements shape import qualification for networked devices. Pune and Bengaluru IT services campuses concentrate managed service contract growth.
South Korea
Public sector tenders award technical points for MFDS-aligned e-waste recovery standards favoring modular designs. Green procurement incentives reshape competitive scoring in government RFPs. Busan-Ulsan industrial zone electronics assembly operations demand high-volume continuous-feed production systems.
Photocopiers Market Competitive Environment
Concentration sits with full-stack manufacturers controlling optical engine production and service infrastructure. The vendor base stratifies between integrated hardware-service platforms and component-dependent assemblers. Three archetypes dominate: captive optical engine producers, service-led contract anchors, and cloud-integrated workflow platform operators. Competitive moves center on backward integration into precision subassemblies and geographic expansion through local assembly partnerships.
Within the integrated manufacturer tier, Canon Inc. and Ricoh Co. Ltd. exemplify divergent strategic positioning. Canon's in-house optical engine production represents captive supply chain control over critical imaging subsystems. Ricoh occupies a position emphasizing cloud-integrated document platforms that extend hardware utility. Xerox Holdings Corp. anchors the service-led archetype through recurring revenue structures. These three entities collectively illustrate how competitive returns bifurcate between installed-base servicers and full-stack manufacturers.
| Leading Market Players |
|---|
| Canon Inc. |
| Ricoh Co. Ltd. |
| HP Inc. |
| Xerox Holdings Corp. |
| Konica Minolta Inc. |
| Brother Industries Ltd. |
| Sharp Corp. |
| Kyocera Document Solutions |
| Seiko Epson Corp. |
| Others |
Value Chain & Pricing Dynamics
EU Ecodesign standby mandates and EPA Energy Star certification simultaneously gate supply qualification and stratify price tiers, forcing manufacturers to absorb compliance costs in entry segments while capturing premiums in configured corporate fleets.
Pricing Analysis
Configured-to-order pricing for enterprise multifunction platforms commands spreads of 40-60% above standard SKUs, with ISO 27001-aligned firmware hardening and modular e-waste recovery architectures as the primary differentiation drivers. Contract-based long-term managed print services dominate corporate procurement, compressing transactional hardware margins while expanding recurring revenue pools. Price erosion runs through low-volume desktop segments as LED engine commoditization intensifies competition among Taiwanese and Japanese component suppliers. Small and medium enterprises in Indian manufacturing corridors exhibit highest price sensitivity, while German automotive supplier parks prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Inventory cycles for optical engine subassemblies now stretch 16-22 weeks, with Japanese and Taiwanese suppliers controlling LED array and photoconductive drum production. Neodymium-dependent brushless motors for high-speed fuser assemblies draw from Chinese rare earth processing, creating single-source vulnerability tied to export quota volatility. Polyester resin binders and wax release agents for low-melting-point toner formulations rest on South Korean and German chemical suppliers. Distribution runs through authorized dealer networks in developed markets and direct OEM partnerships in emerging manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across hardware and service contracts is fragmenting vendor relationships, creating white-space openings for independent service organizations and component specialists.
For Market Incumbents: Consolidate backward integration into precision optical subassemblies to defend margin pools against LED engine commoditization. Canon's captive supply chain model offers template for controlling critical imaging components. Prioritize certification investment in ISO 27001-aligned firmware hardening to extend product development timelines as competitive moat against component-dependent assemblers.
For New Entrants and Emerging Players: MFDS-aligned e-waste recovery certification fast-tracks access to South Korean public sector tenders where green procurement incentives reshape competitive scoring. Target Vietnam's Bac Ninh and Ho Chi Minh City industrial corridors for high-volume continuous-feed production copier deployment. Pursue cloud-integrated document platform partnerships with financial services verticals in London and New York where procurement departments mandate supplier diversity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compact LED desktop segments as solid-state imaging arrays displace laser scanning assemblies. Five-to-ten year viability favors acquisition of independent service organizations with installed-base servicing capabilities in North American corporate accounts. Monitor unbundling velocity in financial services procurement as signal for managed print service margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Engines | Canon and Ricoh control critical imaging subsystems through in-house production of photoconductive drums. |
| Cloud-Integrated Document Platform Launch | Ricoh's workflow infrastructure extends hardware utility beyond standalone copying for contract-heavy industries. |
| Modular E-Waste Recovery Design | Replaceable subassemblies capture technical points in South Korean MFDS-aligned public sector tenders. |
| LED Engine Thermal Efficiency Transition | Solid-state arrays penetrate home office segments where heat dissipation previously excluded copier-class devices. |
| Managed Print Service Contract Expansion | Xerox anchors recurring revenue through workflow integration rather than per-page toner consumption models. |
Study Parameters
Initial hypotheses were tested against primary input from OEM product managers, managed print service operations directors, corporate procurement officers, and aftermarket service technicians, then refined through secondary validation against SEC 10-K filings, EU Ecodesign regulatory databases, Japanese METI efficiency standard submissions, and Indian BIS certification records. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Variance decomposition separated volume drivers from price-mix effects across product type, technology, end user, and capacity segmentation dimensions. CAGRs derived from fitted growth curves applied to replacement cycle modeling and page-volume elasticity assumptions. Forecast inputs incorporated hybrid work permanence, EU standby mandate compliance deadlines, and rare earth magnet supply volatility scenarios.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement and no severe trade disruption; material deviation would warrant model refresh. Specific risk factors include accelerated document digitization in financial services, Chinese export quota shocks on neodymium supply, and cybersecurity certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Continuous Inkjet Printers Market
Printers
Portable Printer Market
Printers
Aerosol Printing and Graphics Market
Printers
Retail Printers and Consumables Market
Printers
Single Function Printer Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Thermal Inkjet Printer Market
Printers
Global Thermal Printing Market
Printers
Laser Printer Market
Printers
Inkjet Printers Market
Printers
NCR Printers Market
Printers
Global Ticket Printers Production Market
Printers
Multi-Functional Printer Market
Printers
Copier, MFP and Printer Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
Mobile Photo Printer Market