
 Multi-Functional Printer Market | 2026-2036
Multi-Functional Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Functional Printer Market Outlook
China is tilting toward domestic production of high-speed laser engines and precision toner cartridges. HP Inc. leverages its global supply chain to sustain cost leadership in enterprise fleet contracts. Canon Inc. anchors its position through in-house imaging sensor manufacturing. Ricoh Company, Ltd. differentiates with managed print services that bundle hardware, software, and remote monitoring.
A multi-functional printer integrates printing, scanning, copying, and faxing within a single chassis, typically employing laser or inkjet imaging engines with resolutions from 600 to 2400 dpi and processing speeds between 20 and 75 pages per minute for A4 document workflows. Laser configurations dominate enterprise installations where volume throughput and per-page cost control matter most, while inkjet systems capture home and small business segments through lower acquisition prices and compact footprints. Wi-Fi connectivity now leads new installations as organizations prioritize cable-free office layouts and mobile device pairing.
The EPA's ENERGY STAR program and the EU Ecodesign Directive enforce standby power limits and toner cartridge recyclability standards that reshape product design cycles. BIS certification requirements in India and China's GB standards for electromagnetic compatibility add compliance layers for manufacturers seeking market access across major economies. Stakeholders must weigh regional certification timelines against platform standardization strategies to avoid SKU proliferation that erodes margin pools.
Market Dynamics
Enterprise fleet refresh cycles are lengthening as hybrid work stabilizes, compressing hardware replacement velocity while redirecting capital toward managed print services and remote monitoring infrastructure.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Government incentives attract assembly investment for toner cartridges and precision imaging components, reducing import dependency for domestic brands.
- EU Ecodesign Directive standby power limits:Manufacturers redesign power management circuits to meet sub-watt standby thresholds, accelerating semiconductor integration in control boards.
- Small business formation in tier-2 Indian cities:New commercial registrations drive demand for compact A4 MFPs with Wi-Fi connectivity and mobile pairing capabilities.
Market Restraints
- Precision toner chemistry concentration:Polymerization-grade toner particle production clusters in Japan and Germany, creating input cost volatility for non-integrated assemblers.
- China's GB electromagnetic compatibility certification:Extended testing timelines for laser engines delay product launches by 4-6 months for foreign manufacturers.
- Document digitization substitution:Cloud-native workflow platforms reduce page volumes in legal and financial services, eroding per-device utilization rates.
Strategic Opportunities
- Managed print services bundling:Remote monitoring software and predictive maintenance contracts capture recurring revenue streams from enterprise accounts.
- BIS certification acceleration in India:Streamlined safety testing procedures enable faster market entry for inkjet systems targeting educational institutions.
- Edge computing convergence with MFPs:On-device document processing reduces cloud latency for healthcare and government sectors with data sovereignty requirements.
Industry Challenges
- Firmware security certification complexity:ISO 27001 and IEC 62443 compliance for networked devices demands specialized embedded systems engineering talent.
- Legacy fleet integration friction:Enterprise IT departments struggle to unify monitoring protocols across 5-7 year hardware refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Functional Printer Market |
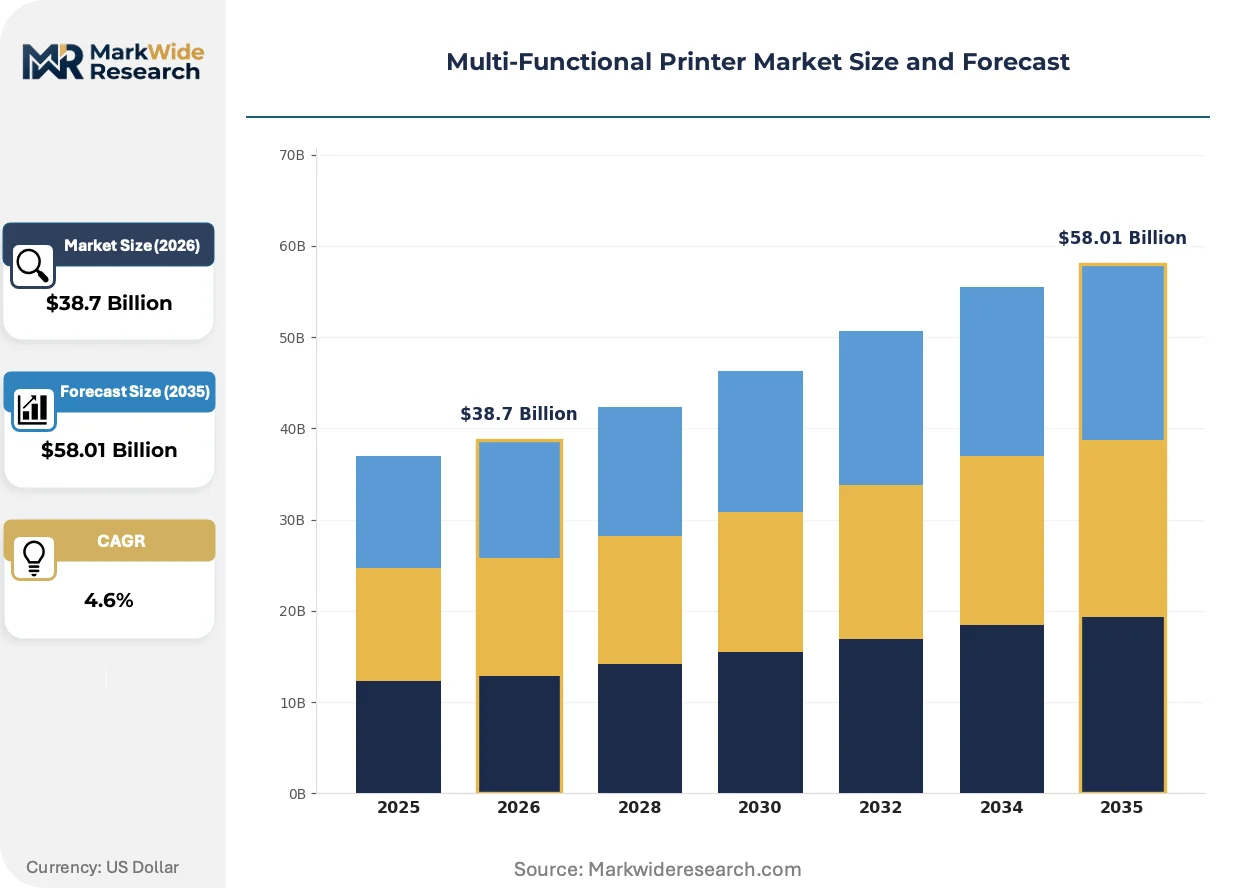
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Thermal, Dot Matrix Application: Office, Home, Industrial, Retail Connectivity: USB, Wi-Fi, Ethernet, Bluetooth End User: Small Businesses, Enterprises, Educational Institutions, Government |
| Companies Covered | Brother Industries, Ltd., Konica Minolta, Inc., HP Inc., Kyocera Document Solutions Inc., Xerox Holdings Corporation, Canon Inc., Ricoh Company, Ltd., Fujifilm Business Innovation Corp., Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Functional Printer Market Strategic Shifts
Hardware commoditization is redirecting competitive investment toward software-defined service layers and predictive maintenance algorithms that extend equipment lifecycles.
Memjet water-based inkjet arrays are rendering obsolete thermal inkjet heads in high-speed office segments. Commercial print departments at insurance and logistics firms are adopting these systems for transaction document bursts. The technology is compressing per-page cost structures previously dominated by entry-level laser engines.
REACH restrictions on persistent organic pollutants in toner formulations are forcing reformulation of styrene-acrylic polymer binders. European manufacturers face 18-month transition windows to secure alternative chemistries. Color laser MFPs above 40 ppm face the steepest compliance cost increases.
Enterprise purchasing departments now unbundle hardware acquisition from service contracts, fragmenting vendor relationships. Direct procurement from manufacturer e-commerce portals displaces traditional distributor markups in North American mid-market accounts. This pattern is most pronounced in technology and professional services verticals with centralized spend analytics.
Multi-Functional Printer Market Segmentation
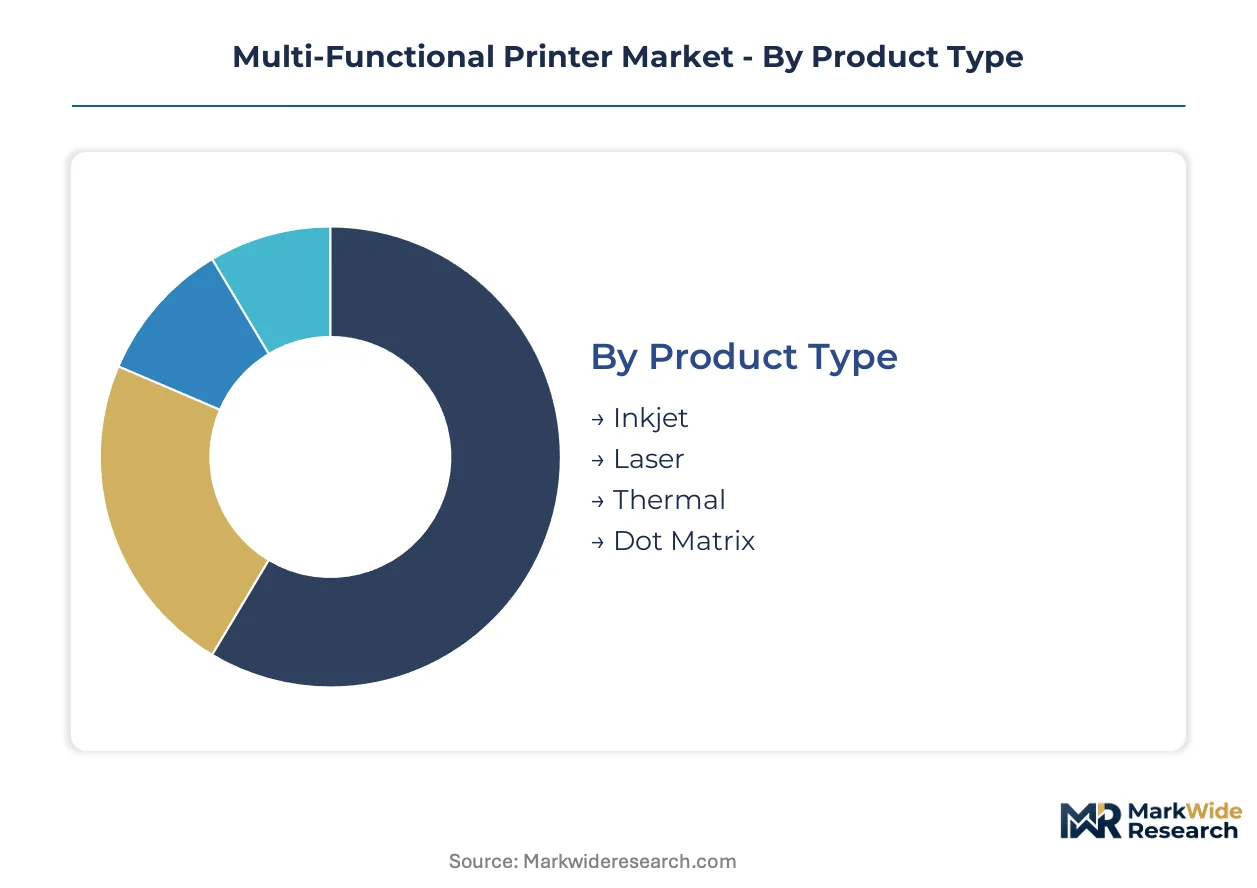
Segmentation in the Multi-Functional Printer Market reveals divergent technology preferences across deployment contexts. Cost-per-page economics, volume throughput requirements, and connectivity infrastructure shape purchasing decisions more than brand loyalty.
Product Type:
Cost tier differentiation separates acquisition price from lifetime operating expense across imaging engine technologies.
- Laser:Electrophotographic imaging with dry toner fusion delivers 20-75 ppm throughput and sub-cent per-page economics at volume. Enterprise fleet contracts in India and Germany concentrate procurement here as hybrid work stabilizes and refresh cycles extend.
- Inkjet:Piezoelectric or thermal printhead deposition achieves 2400 dpi color resolution with lower chassis cost. Small business formation in tier-2 Indian cities and home office segments drive Wi-Fi-enabled compact system demand.
- Thermal:Direct heat imaging for receipt and label output without consumable ink. Logistics and retail transaction environments deploy these for 2-4 inch format durability.
- Dot Matrix:Impact printing through inked ribbon for multi-part forms and industrial documentation. Manufacturing floor and warehouse settings retain these for carbon-copy compliance requirements.
Laser commands the established base. The steepest expansion runs through inkjet as water-based arrays compress per-page costs in mid-volume segments.
Application:
Deployment environment dictates duty cycle specifications, form factor constraints, and software integration requirements.
- Office:A4/A3 duplex handling with document feeder and stapling accessories for 5,000-50,000 monthly page volumes. Managed print service bundling redirects capital from hardware purchase to per-page subscription models.
- Home:Compact footprint systems under 15 kg with smartphone pairing and cloud printing protocols. India's educational digitization initiatives and remote work persistence sustain replacement demand.
- Industrial:Ruggedized chassis with metal construction for 24/7 operation in factory and warehouse conditions. Barcode, RFID, and GHS label compliance drive specialized configuration requirements.
- Retail:Point-of-sale integration with POS software and payment terminal connectivity. Receipt printing, coupon generation, and customer-facing display functions consolidate into single peripheral units.
Office installations retain the largest installed base. Home applications are climbing the fastest as distributed work arrangements persist.
Connectivity:
Network architecture preferences are shifting installation patterns away from cabled infrastructure toward wireless and mobile-first pairing.
- Wi-Fi:IEEE 802.11ac/ax protocols enable cable-free office layouts and direct smartphone printing without router intermediation. New commercial construction and renovation projects specify this as default infrastructure.
- Ethernet:Wired gigabit LAN for enterprise fleet management, centralized driver deployment, and security policy enforcement. Financial services and healthcare sectors mandate this for network segmentation compliance.
- USB:Direct host connection for single-user workstations and legacy system compatibility. Cost-sensitive educational procurement and replacement of aged parallel-port devices sustain residual demand.
- Bluetooth:Short-range pairing for field service, mobile payment, and temporary event deployments. Battery-powered portable printers in logistics and hospitality leverage this for untethered operation.
Ethernet retains dominance in regulated enterprise environments. Wi-Fi is gaining share fastest as facility redesigns prioritize flexible workspace configurations.
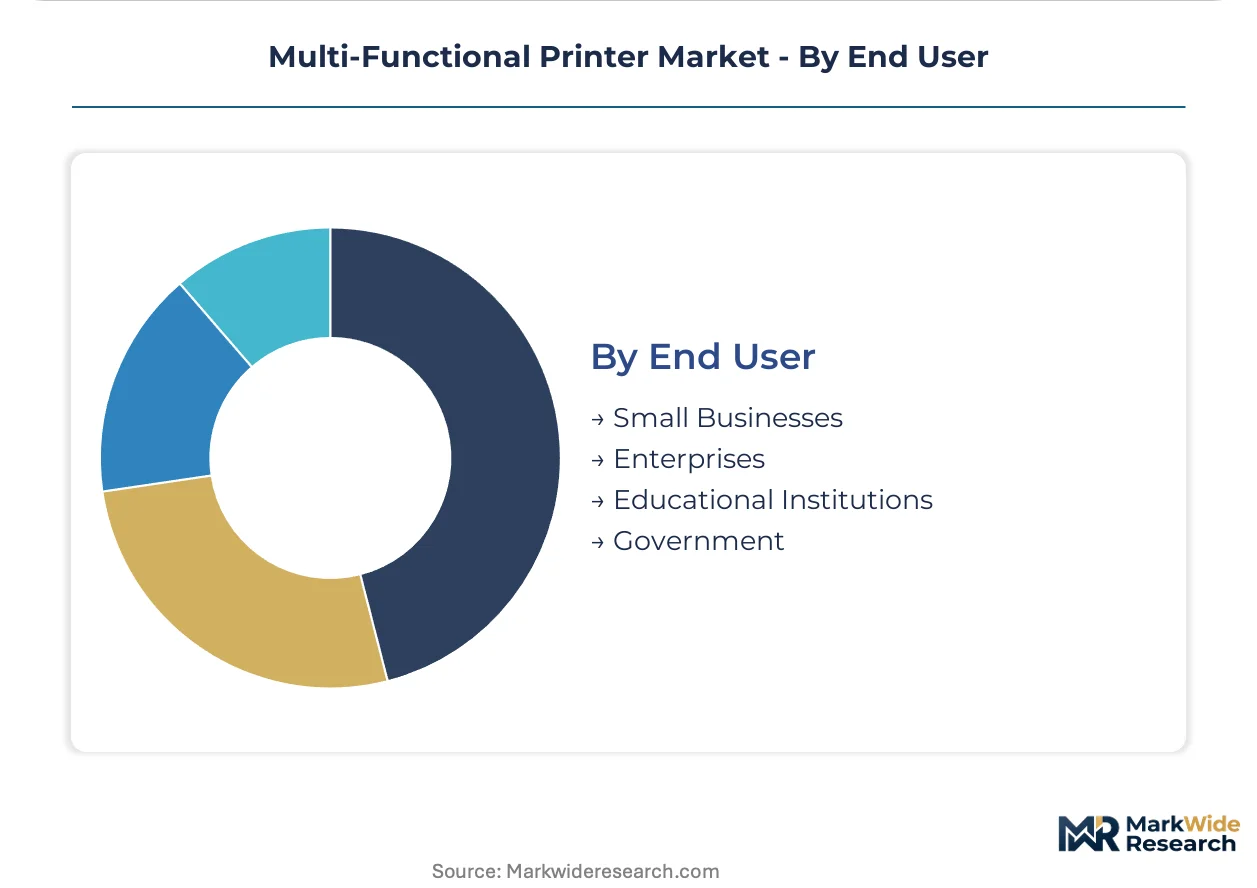
End User:
Customer scale determines purchasing process complexity, service contract structure, and compliance certification requirements.
- Enterprises:Centralized procurement through purchasing departments with 3-5 year total cost of ownership analysis. ISO 27001 firmware security certification and predictive maintenance APIs figure prominently in vendor selection.
- Small Businesses:Owner-operated acquisition through e-commerce portals with emphasis on acquisition price and mobile app functionality. India's PLI scheme for electronics manufacturing reduces import dependency for domestic brand alternatives.
- Educational Institutions:Volume discounts through consortium purchasing with emphasis on duplex efficiency and curriculum software integration. BIS certification acceleration streamlines safety testing for inkjet systems in this segment.
- Government:Tender-based procurement with domestic content requirements and data sovereignty specifications. Edge computing convergence interests healthcare and government sectors for on-device document processing.
Enterprise accounts anchor vendor revenue stability. Small business formation is expanding most quickly as commercial registration accelerates in emerging urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision toner chemistry production clusters in Japan and Germany, creating input cost volatility that ripples through assembly operations in lower-cost manufacturing zones. Manufacturers seeking market access navigate layered certification timelines across major economies, with regional standards shaping platform standardization strategies.
United States
Enterprise fleet contracts dominate procurement as hybrid work stabilizes and refresh cycles extend toward five-year intervals. The EPA's ENERGY STAR program enforces standby power limits below one watt, pushing semiconductor integration in control board redesigns. Dallas-Fort Worth and Atlanta host major distribution hubs for managed print service providers serving mid-market accounts.
Germany
Industrial documentation requirements sustain demand for ruggedized systems in manufacturing floor environments. REACH restrictions on persistent organic pollutants force 18-month reformulation windows for styrene-acrylic polymer binders in toner production. The Baden-Württemberg cluster anchors precision imaging component engineering for European market supply.
China
Domestic production of high-speed laser engines and precision toner cartridges accelerates through state-supported manufacturing initiatives. GB standards for electromagnetic compatibility extend testing timelines by 4-6 months for foreign manufacturers seeking market entry. The Yangtze River Delta concentrates final assembly operations for both domestic brands and contract manufacturing.
India
Government digitization initiatives and small business formation in tier-2 cities drive hardware procurement for compact A4 systems with Wi-Fi connectivity. The PLI scheme for electronics manufacturing attracts assembly investment for toner cartridges and imaging components, reducing import dependency. Bangalore and Hyderabad emerge as testing centers for BIS certification acceleration targeting educational institutions.
Japan
Polymerization-grade toner particle production maintains concentration here, supplying precision chemistry to non-integrated assemblers across Asia. METI efficiency standards shape power management circuit design for export-oriented manufacturers. The Kanto region hosts headquarters operations for vertically integrated imaging sensor and printhead technology developers.
Multi-Functional Printer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in imaging sensors, printheads, and precision toner chemistry. The vendor base organizes around three archetypes: diversified electronics conglomerates with captive imaging technology, pure-play document solutions providers bundling hardware with managed services, and specialized component suppliers selling into third-party assembly. Consolidation pressure runs highest at the system level where scale economies in firmware development and certification compliance favor broad portfolios. Geographic expansion through localized assembly partnerships and technology licensing agreements represent the dominant competitive vectors.
Within the diversified electronics tier, HP Inc., Canon Inc., and Ricoh Company, Ltd. occupy positions shaped by distinct capability anchors. HP exemplifies supply chain leverage through global procurement networks serving enterprise fleet contracts. Canon represents vertical integration advantages through in-house imaging sensor manufacturing. Ricoh sits within the managed print services archetype, bundling hardware with software-defined monitoring and predictive maintenance contracts. These three patterns illustrate how competitive positioning derives from structural choices in technology ownership versus service layer investment rather than product differentiation alone.
| Leading Market Players |
|---|
| Brother Industries, Ltd. |
| Konica Minolta, Inc. |
| HP Inc. |
| Kyocera Document Solutions Inc. |
| Xerox Holdings Corporation |
| Canon Inc. |
| Ricoh Company, Ltd. |
| Fujifilm Business Innovation Corp. |
| Seiko Epson Corporation |
| Others |
Value Chain & Pricing Dynamics
Polymerization-grade toner particle production in Japan and Germany anchors input cost structures for non-integrated assemblers across Asia. This upstream concentration funnels margin capture toward precision chemistry specialists while system integrators compete on service-layer bundling rather than hardware markup.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure through sub-watt standby power mandates that force semiconductor redesign in control boards. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified enterprise fleets from uncertified entry systems. Pricing pressure stems from document digitization substitution eroding per-device utilization in legal and financial services. Small business owner-operators exhibit highest price sensitivity through e-commerce portal procurement, while enterprise purchasing departments prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Extended payment terms from Japanese and German precision chemistry suppliers stretch working capital requirements for assembly operations in China and India. Imaging sensor fabrication draws from Japan's Kanto region, precision toner chemistry from Germany's Baden-Württemberg cluster, and final assembly from China's Yangtze River Delta. Single-source vulnerability concentrates in polymerization-grade toner particle supply. Distribution runs through managed print service providers capturing recurring revenue from enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a switching-cost fortress: enterprise fleet contracts lock customers into 3-5 year refresh cycles with predictive maintenance APIs that raise replacement friction.
For Market Incumbents: Insulate enterprise relationships by embedding predictive maintenance algorithms deeper into remote monitoring infrastructure. Extend backward integration into precision toner chemistry to offset input cost volatility from Japanese and German suppliers. Managed print service contracts represent the critical defensive perimeter against Memjet water-based inkjet displacement in mid-volume segments.
For New Entrants and Emerging Players: Build out BIS certification acceleration services for inkjet systems targeting India's educational institutions, where streamlined safety testing creates faster market entry than enterprise fleet competition. Tier-2 Indian cities with small business formation offer the most penetrable geography. Direct e-commerce portal procurement bypasses traditional distributor markups in North American mid-market accounts.
For Investors and Strategic Acquirers: Capital is best deployed toward managed print service providers with installed base density and recurring revenue visibility across the 5-10 year horizon. Edge computing convergence capabilities for healthcare and government data sovereignty requirements represent the most defensible acquisition archetype. Watch for firmware security certification complexity creating capability scarcity that consolidates vendor relationships toward ISO 27001-compliant platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed Print Service Bundling | Predictive maintenance contracts capture recurring revenue from enterprise accounts with 3-5 year refresh cycles. |
| Backward Integration into Toner Chemistry | In-house polymerization-grade particle production reduces dependency on Japanese and German input suppliers. |
| Edge Computing Convergence | On-device document processing addresses healthcare and government data sovereignty requirements with reduced cloud latency. |
| BIS Certification Acceleration | Streamlined safety testing enables faster market entry for inkjet systems in India's educational procurement channels. |
| Memjet Water-Based Inkjet Adoption | High-speed arrays compress per-page costs in insurance and logistics transaction document segments. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with MFP procurement managers, managed print service operations directors, and imaging component R&D leads; and secondary validation through EPA ENERGY STAR certification databases, EU Ecodesign Directive compliance filings, BIS safety testing records, and customs trade data for toner cartridge imports. Bottom-up triangulation across hardware shipment volumes and top-down reconciliation against service contract values anchored market sizing.
Forecast inputs span laser and inkjet technology segments, enterprise and small business end-user categories, and Wi-Fi versus Ethernet connectivity configurations across the projection horizon. CAGRs derive from fitted growth curves applied to installed base refresh patterns and page volume elasticity assumptions. Hybrid work stabilization timelines and India's PLI scheme uptake rates served as scenario-dependent inputs.
Stress conditions across toner chemistry price volatility, BIS certification timeline compression, and document digitization substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet refresh cycle extension and managed print service penetration. Macroeconomic contraction, accelerated REACH reformulation deadlines, or breakthrough inkjet cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Mobile Photo Printer Market
Printers
Electrophotographic Printing Market
Printers
Copier, MFP and Printer Market
Printers
Printer Ribbons Market
Printers
Retail Printers and Consumables Market
Printers
India Inkjet Printer Market
Printers
Global Ticket Printers Production Market
Printers
Single Function Printer Market
Printers
Global Printer Market
Printers
Indonesia Thermal Printer Market
Printers
Ink Tank Printer Market
Printers
Portable Printer Market
Printers
Production Printer Market
Printers
Aerosol Printing and Graphics Market
Printers
Dot Matrix Printer Market
Printers
Photocopiers Market