
 Thermal Inkjet Printer Market | 2026-2036
Thermal Inkjet Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Inkjet Printer Market Analytics
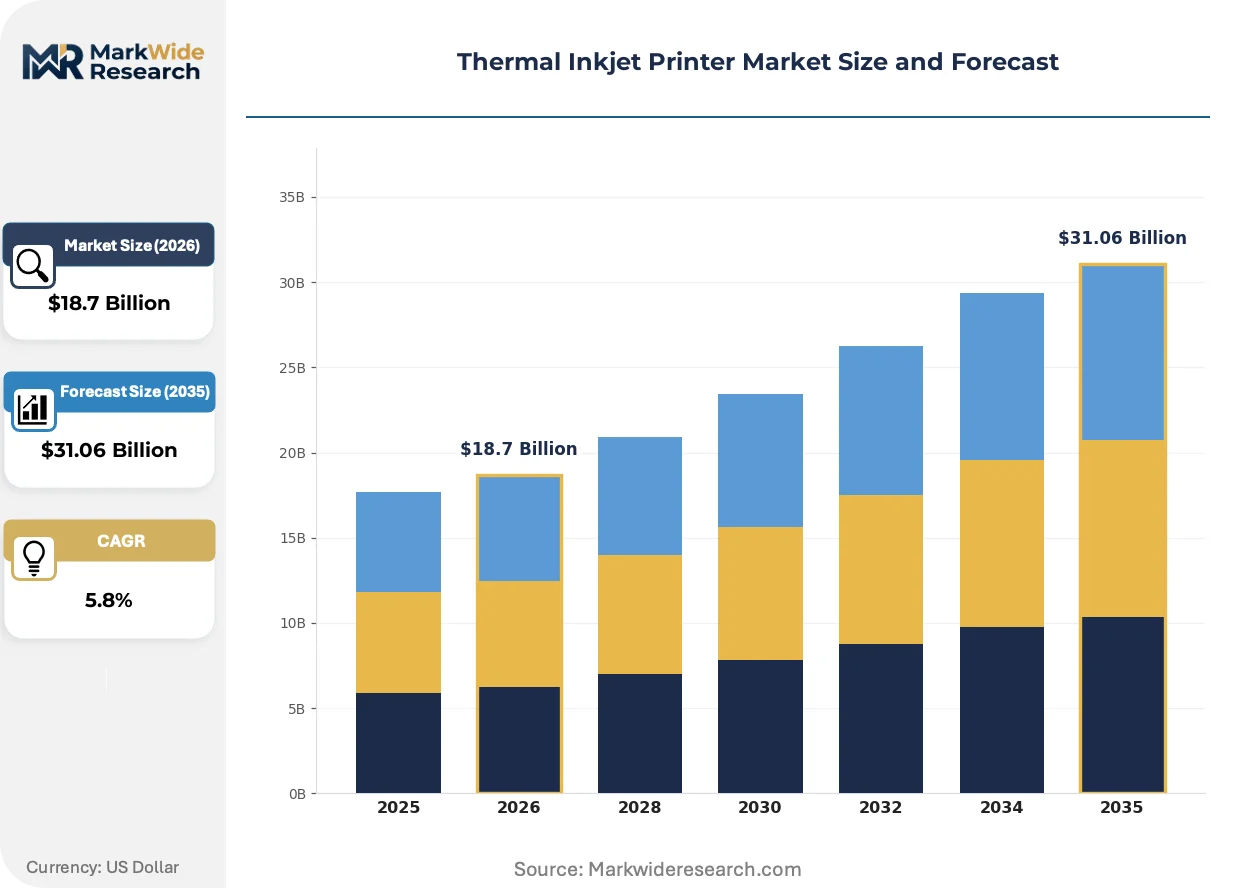
EU MDR serialization requirements is expanding compliance costs for pharmaceutical packaging lines across Europe. HP Inc. leverages its thermal inkjet patent portfolio to dominate high-throughput industrial coding installations. Canon Inc. anchors its position through precision MEMS printhead fabrication, while Seiko Epson Corporation differentiates via piezoelectric alternatives that compete directly with thermal bubble architectures in select industrial niches.
A thermal inkjet printer ejects ink through microscopic nozzles by vaporizing a fluid bubble with a resistive heating element, achieving drop volumes as small as one picoliter at frequencies exceeding thirty kilohertz for photographic and barcode applications. The technology serves commercial documentation, pharmaceutical serialization, and consumer photo reproduction where resolution and speed must coexist. Multifunction systems lead installed base value by combining print, scan, and copy utilities for home office and educational procurement channels. Industrial end users represent the fastest-growing demand pool as thermal bubble printheads displace continuous inkjet in secondary packaging lines where solvent-based formulations face tightening volatile organic compound scrutiny.
FDA track-and-trace mandates for pharmaceutical distribution reshape hardware specifications in the United States, while REACH compliance in Europe restricts certain ink chemistries and drives reformulation investments. China's GB standards for electronic product labeling and India's BIS certification for imported printing equipment add parallel compliance layers for manufacturers serving Asia-Pacific assembly chains. Stakeholders must monitor evolving substrate compatibility requirements as sustainable packaging materials disrupt established ink adhesion protocols without warning.
Market Dynamics
Pharmaceutical serialization mandates across Europe and the United States are forcing wholesale hardware replacement cycles, compressing printer upgrade timelines from five-year cycles to eighteen-month compliance windows as manufacturers race against enforcement deadlines.
Growth Catalysts
- EU MDR serialization:European pharmaceutical packaging lines face mandatory track-and-trace equipment installation by national health regulators, creating immediate replacement demand for legacy continuous inkjet systems.
- E-commerce fulfillment concentration:China and India's warehouse automation buildouts require high-speed label printers capable of variable data encoding at throughput rates exceeding ten thousand packages hourly.
- Solvent-based formulation restrictions:REACH compliance in Europe and EPA volatile organic compound scrutiny in the United States accelerate thermal bubble displacement of solvent-dependent continuous inkjet architectures.
Market Restraints
- MEMS printhead supply concentration:Precision micro-electromechanical fabrication capacity clusters in East Asian foundry networks, creating single-source vulnerability for high-resolution nozzle arrays.
- Substrate compatibility gaps:Sustainable packaging materials including molded fiber and bio-based films exhibit unpredictable ink adhesion, forcing costly reformulation cycles without guaranteed performance.
- Piezoelectric substitution pressure:Seiko Epson's piezoelectric alternatives compete for industrial niches requiring broader ink viscosity tolerance, eroding thermal bubble's addressable market in chemical-resistant coding applications.
Strategic Opportunities
- Secondary packaging line automation:Food and beverage manufacturers in Brazil and Mexico are retrofitting bottling facilities with compact thermal inkjet modules to replace legacy hot-stamp coders.
- Photographic reproduction revival:Consumer photo kiosks and on-demand printing services integrate picoliter-precision thermal heads for premium output, countering digital-only consumption patterns.
- GB standard alignment:China's electronic product labeling requirements create certified-printer procurement channels for equipment meeting MIIT electromagnetic compatibility and SAMR safety protocols.
Industry Challenges
- Multi-jurisdictional certification timelines:Manufacturers must sequence BIS approval for India, NMPA registration for China, and FDA qualification for the United States, stretching product launch windows across eighteen to twenty-four months.
- Legacy system integration friction:Pharmaceutical packaging lines running SCADA architectures from the 1990s require custom middleware development to interface with modern thermal inkjet controllers, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Inkjet Printer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Function, Multifunction, Portable, Large Format Technology: Piezoelectric, Thermal Bubble, MEMS, Continuous Inkjet End User: Commercial, Industrial, Home Office, Educational Application: Label Printing, Packaging, Documentation, Photo Printing |
| Companies Covered | HP Inc., Canon Inc., Seiko Epson Corporation, Brother Industries, Lexmark International, Videojet, Markem-Imaje, Ricoh Company, Xerox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Inkjet Printer Market Evolving Landscape
Printhead architecture is converging with semiconductor manufacturing methods, enabling nozzle densities that redefine resolution benchmarks while compressing unit economics for industrial-scale deployment.
Drop-on-demand thermal bubble technology is unifying variable data printing with inline quality inspection through embedded machine vision feedback loops. Pharmaceutical contract packagers in Germany and Switzerland are adopting these integrated modules to eliminate offline verification stations. The convergence is compressing line footprint requirements by forty percent while raising capital efficiency thresholds for facility expansion decisions.
REACH authorization procedures for pigment and dye substances are restricting ink formulation palettes available to European manufacturers. ECHA's candidate list expansion forces reformulation investments that disproportionately burden small-batch specialty ink producers. Industrial end-users respond by consolidating supplier relationships toward vertically integrated chemical houses with captive toxicology testing capabilities.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized contract packaging organizations. Third-party logistics providers in the Netherlands and Belgium now specify throughput-based pricing with bundled maintenance and consumable replenishment. This shift transfers technology obsolescence risk from end-users to OEM finance arms, reshaping balance sheet structures across the European pharmaceutical packaging sector.
Thermal Inkjet Printer Market Segmentation
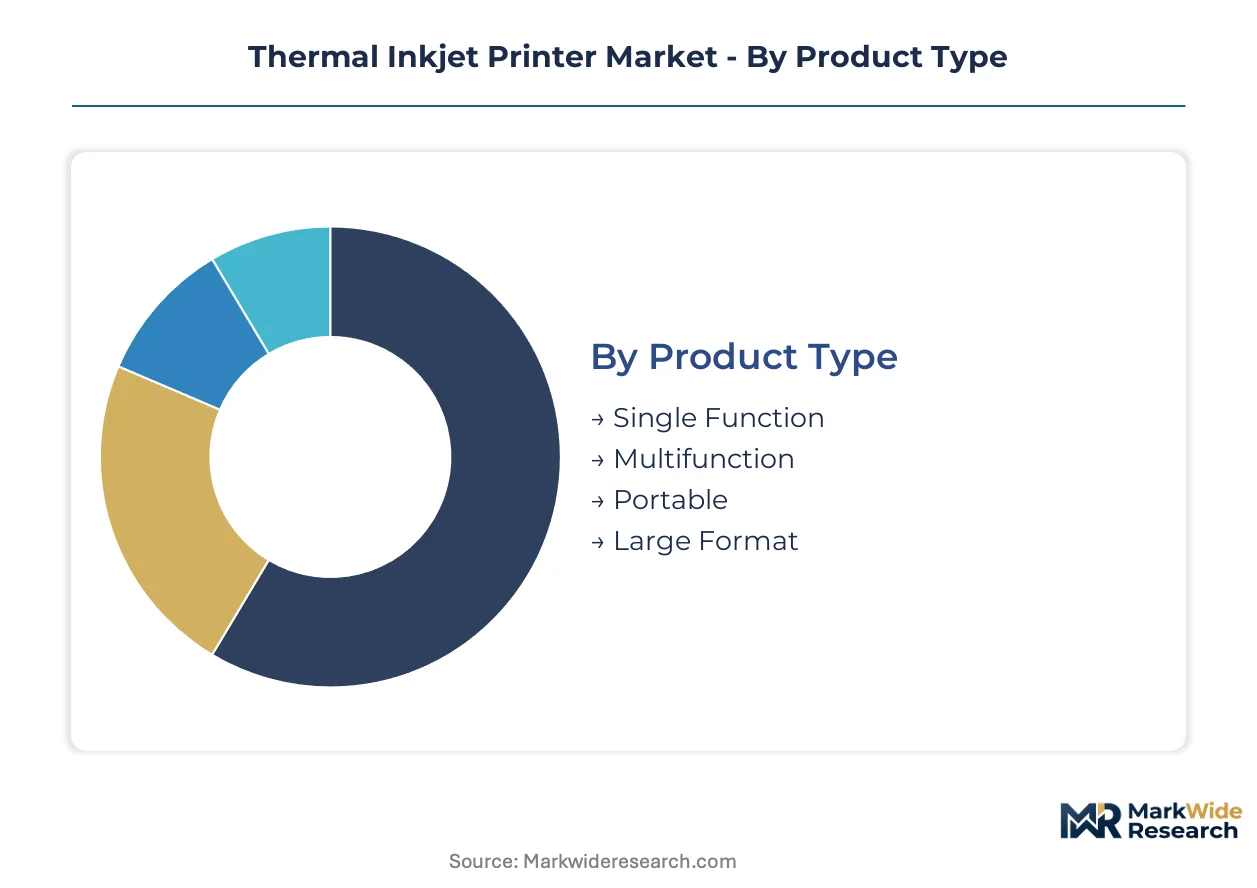
Thermal inkjet printer segmentation reveals how printhead architecture, use environment, and output requirements fragment procurement patterns. Equipment specifications diverge sharply between pharmaceutical serialization lines demanding picoliter precision and home office systems prioritizing consumable cost efficiency.
Product Type:
Supply concentration in MEMS fabrication favors manufacturers with captive semiconductor foundry relationships, compressing margins for assembly-only competitors.
- Multifunction:Combines thermal printing with scanning and copying utilities through shared controller architecture. Educational procurement channels in Germany and institutional buyers in Japan concentrate demand for fleet-deployable units with centralized toner management.
- Single Function:Dedicated printing hardware optimized for throughput density in space-constrained environments. Pharmaceutical contract packagers in Switzerland specify these units for serialization stations where scanning integration is handled upstream.
- Portable:Battery-operated compact units with reduced nozzle arrays for field documentation. Field service technicians across logistics networks in India deploy these for on-site label generation.
- Large Format:Extended print width architectures for architectural and engineering output. Technical reproduction houses in Brazil anchor regional demand for poster and blueprint applications.
Multifunction systems absorb the bulk of installed capacity; portable units are expanding most quickly.
Technology:
Cost tier stratification separates precision fabrication investments from commodity nozzle assembly, with MEMS commanding premium positioning.
- Thermal Bubble:Resistive heating elements vaporize fluid to eject picoliter droplets at frequencies exceeding thirty kilohertz. Secondary packaging lines across Europe's food and beverage sector favor this architecture for solvent-free compliance with REACH volatile organic compound restrictions.
- MEMS:Micro-electromechanical systems fabrication achieves nozzle densities above three hundred per millimeter through semiconductor lithography. High-resolution pharmaceutical coding in Germany and Switzerland requires this precision for 2D Data Matrix readability at two millimeter sizes.
- Piezoelectric:Crystal deformation drives droplet ejection without thermal stress, tolerating broader ink viscosity ranges. Chemical-resistant coding applications in industrial France select this alternative for aggressive solvent formulations.
- Continuous Inkjet:Pressurized recirculating ink systems predating drop-on-demand architectures. Legacy installations in Mexico's beverage bottling sector persist where capital replacement cycles lag regulatory deadlines.
Thermal bubble architectures dominate current shipment volumes; MEMS fabrication is gaining share fastest.
End User:
Application maturity divides segments between established documentation markets and emerging industrial automation deployments.
- Industrial:Hardened printhead modules integrated into packaging line PLCs with SCADA connectivity. E-commerce fulfillment centers in China and India specify these for variable data encoding at throughput rates exceeding ten thousand packages hourly.
- Commercial:Office-document systems with duty cycles calibrated for intermittent use patterns. Small and medium enterprises across Italy and Spain procure through managed print service contracts.
- Home Office:Consumer-grade hardware with simplified maintenance protocols. Remote work expansion in the United Kingdom and France sustained demand for entry-level color systems.
- Educational:Institutional procurement through centralized technology budgets with multi-year service agreements. Public school districts in Japan and South Korea specify these for classroom and administrative deployment.
Commercial installations retain the largest installed base; industrial end use shows the steepest expansion trajectory.
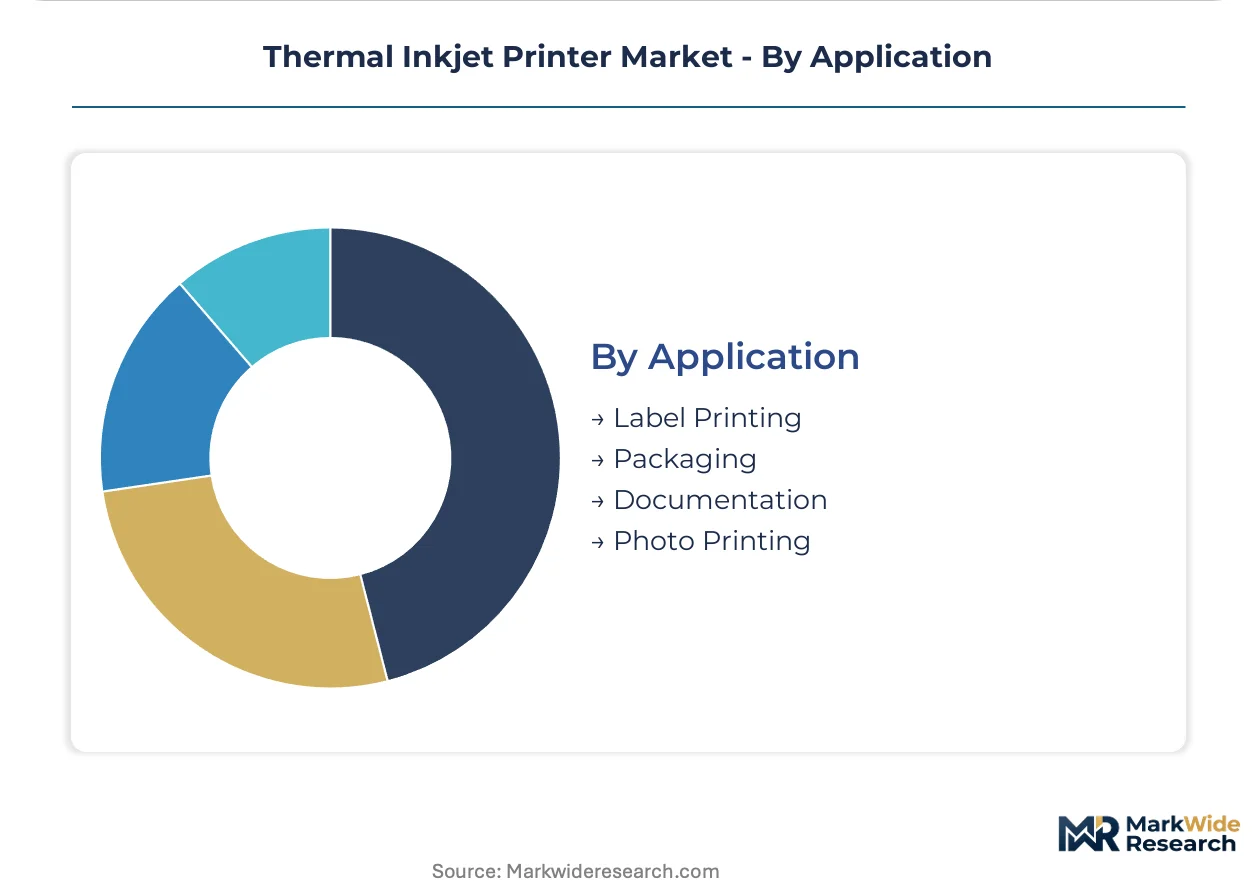
Application:
Customer type differentiation separates compliance-driven pharmaceutical procurement from discretionary consumer spending.
- Packaging:Inline coding of cartons, flexible films, and rigid containers with real-time variable data. Secondary packaging automation in Brazil and Mexico drives retrofit demand replacing legacy hot-stamp equipment.
- Label Printing:Adhesive substrate processing with optimized ink adhesion chemistry. Third-party logistics providers in the Netherlands specify high-speed units for warehouse automation integration.
- Documentation:General office output on uncoated paper stocks. Government administrative offices in India anchor regional demand for routine record generation.
- Photo Printing:Premium pigment or dye-based output on coated media. Consumer photo kiosks in Japan and on-demand services in the United States sustain niche demand despite digital consumption dominance.
Packaging applications command the majority of capital deployment; label printing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Free-Trade Zone incentives are concentrating thermal inkjet printer distribution hubs serving Asia-Pacific assembly chains. Pharmaceutical serialization mandates and e-commerce fulfillment buildouts are reshaping procurement patterns across manufacturing corridors.
United States
FDA track-and-trace mandates for pharmaceutical distribution are forcing hardware replacement cycles in packaging facilities. EPA volatile organic compound scrutiny accelerates thermal bubble displacement of solvent-dependent continuous inkjet systems. Chicago-area contract packagers are retrofitting secondary packaging lines with compact thermal inkjet modules to meet compressed compliance deadlines.
Germany
EU MDR serialization requirements are expanding compliance costs for pharmaceutical packaging lines across industrial zones. REACH authorization procedures for pigment and dye substances are restricting ink formulation palettes available to domestic manufacturers. Bavarian pharmaceutical contract packagers are adopting integrated thermal inkjet modules with embedded machine vision to eliminate offline verification stations.
China
GB standards for electronic product labeling are creating certified-printer procurement channels for equipment meeting MIIT electromagnetic compatibility protocols. Warehouse automation buildouts in the Yangtze River Delta require high-speed label printers capable of variable data encoding at throughput rates exceeding ten thousand packages hourly. Shenzhen-based fulfillment centers are specifying hardened printhead modules for e-commerce operations.
India
BIS certification for imported printing equipment adds compliance layers for manufacturers serving domestic assembly chains. Expanding e-commerce fulfillment sectors are concentrating demand for high-speed label and packaging printers. Mumbai and Bangalore logistics hubs are deploying portable thermal inkjet units for field service technicians requiring on-site label generation.
Switzerland
Swissmedic pharmaceutical serialization enforcement is compressing printer upgrade timelines from five-year cycles to eighteen-month compliance windows. Precision MEMS printhead fabrication requirements align with domestic semiconductor manufacturing capabilities. Basel-area pharmaceutical packaging facilities are specifying high-resolution thermal bubble architectures for 2D Data Matrix readability at two millimeter sizes.
Thermal Inkjet Printer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: diversified electronics conglomerates leveraging patent portfolios, precision fabrication specialists controlling MEMS foundry capacity, and industrial coding pure-plays serving pharmaceutical serialization niches. Dominant competitive moves include portfolio diversification into adjacent printing technologies and geographic expansion through certified-printer procurement channels in regulated Asian markets.
Within the diversified conglomerate tier, HP Inc. and Canon Inc. exemplify scale-driven positioning through captive intellectual property and semiconductor manufacturing relationships. Seiko Epson Corporation occupies a distinct position representing piezoelectric alternative architectures that compete directly with thermal bubble systems in select industrial niches requiring broader ink viscosity tolerance. These three anchors demonstrate how technology differentiation and vertical integration depth separate premium-tier positioning from assembly-only competitors.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Seiko Epson Corporation |
| Brother Industries |
| Lexmark International |
| Videojet |
| Markem-Imaje |
| Ricoh Company |
| Xerox |
| Others |
Value Network & Pricing Analysis
Captive MEMS foundry relationships anchor both supply security and pricing power for precision printhead manufacturers, while assembly-only competitors absorb margin compression from East Asian fabrication capacity constraints. Equipment-as-a-service contracting now transfers technology obsolescence risk from end-users to OEM finance arms, reshaping balance sheet structures across pharmaceutical packaging procurement channels.
Pricing Analysis
Short lead-time premiums command pricing power for pharmaceutical serialization compliance windows, while spot inventory discounts attract cost-sensitive educational procurement channels. Three-tier pricing structure across premium MEMS, standard thermal bubble, and economy portable levels separates certification-grade pharmaceutical units from consumer home office systems. Cost compression in the mid-tier standard segment is intensifying because REACH-compliant ink reformulation investments disproportionately burden small-batch specialty producers. Contract packaging organizations in the Netherlands and Belgium exhibit the highest price sensitivity due to throughput-based contracting models, while Swiss pharmaceutical facilities prioritize precision certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from e-commerce fulfillment centers in China and India, while distributor networks serve fragmented commercial and educational procurement. Precision micro-electromechanical fabrication capacity clusters in Taiwan, South Korea, and Japan, creating single-source vulnerability for high-resolution nozzle arrays. Raw material dependencies include silicon wafers for MEMS lithography, specialized pigment formulations for REACH-compliant inks, and rare earth elements for precision heating elements. Distribution runs through certified-printer procurement channels for regulated Asian markets, with tariff exposure on semiconductor components representing the primary structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around MEMS fabrication capabilities and regulatory certification depth, with multi-jurisdictional approval timelines forcing weaker assembly-only competitors toward exit or acquisition. Pharmaceutical serialization mandates compress hardware replacement cycles, eliminating players lacking captive foundry relationships or vertical chemical integration.
For Market Incumbents: Deepen backward integration into precision MEMS foundry capacity to secure nozzle array supply against East Asian concentration risk. Acquire specialty ink formulation capabilities with captive toxicology testing to absorb REACH compliance burdens that disproportionately crush small-batch competitors. Control certified-printer procurement channels in China and India before regulatory alignment investments by mid-tier rivals mature. For New Entrants and Emerging Players: EU MDR serialization in Europe opens a window for modular thermal inkjet retrofit kits targeting legacy continuous inkjet displacement in secondary packaging lines. Brazil and Mexico food and beverage bottling facilities represent the most penetrable geography, with compact thermal modules replacing hot-stamp coders in space-constrained environments. Pursue equipment-as-a-service contracting models with third-party logistics providers to bypass capital purchase barriers among mid-sized contract packagers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electronics conglomerates seeking MEMS fabrication depth or pharmaceutical pure-plays requiring regulatory certification infrastructure. Long-term viability hinges on captive semiconductor manufacturing relationships and multi-jurisdictional approval track records across FDA, NMPA, and BIS frameworks. Watch for inflection in substrate compatibility breakthroughs for sustainable packaging materials, as unpredictable ink adhesion currently blocks margin expansion in premium pharmaceutical segments.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Taiwanese and South Korean fabrication investments secure nozzle array supply for pharmaceutical serialization compliance. |
| REACH-Compliant Ink Formulation | Captive toxicology testing capabilities absorb ECHA authorization burdens that crush small-batch specialty producers. |
| Equipment-as-a-Service Contracting | Throughput-based pricing with bundled maintenance transfers technology obsolescence risk to OEM finance arms in Europe. |
| Multi-Jurisdictional Certification Investment | Sequenced BIS, NMPA, and FDA approvals compress eighteen-month product launch windows for regulated Asian markets. |
| Machine Vision Integration | Embedded quality inspection modules eliminate offline verification stations, compressing pharmaceutical line footprints by forty percent. |
Research Methodology
Multi-period observation of pharmaceutical serialization compliance deadlines, e-commerce fulfillment automation buildouts, and MEMS fabrication capacity utilization anchored the trend analysis, supplemented by interviews with packaging line engineers, pharmaceutical contract manufacturing executives, specialty ink formulation chemists, and semiconductor foundry operations managers. Secondary validation drew from FDA track-and-trace guidance documents, ECHA REACH authorization procedures, MIIT electromagnetic compatibility protocols, SEC filings from diversified printing equipment manufacturers, and customs data on printing equipment imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across industrial automation and pharmaceutical packaging end-use sectors.
Input-output matrices mapped printhead architecture adoption against regulatory compliance timelines and substrate compatibility requirements over the projection horizon. Segmentation dimensions modeled included product type, technology tier, end-user industry vertical, application use case, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, penetration rate assumptions for thermal bubble displacement of continuous inkjet, and equipment-as-a-service contract expansion trajectories. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate enforcement calendars and warehouse automation capex disclosures from third-party logistics providers.
The model assumes a particular technology adoption path; alternative pathways for piezoelectric printhead architectures in chemical-resistant coding applications would alter the outlook for thermal bubble market share. Forecasts reflect base-case assumptions regarding REACH authorization timelines, BIS certification processing durations, and substrate adhesion performance for sustainable packaging materials. Periodic stress-testing of base assumptions against regulatory enforcement delays and MEMS foundry capacity shocks is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Thermal and Inkjet Disc Printers Market
Printers
Production Printer Market
Printers
Inkjet Printing Market
Printers
Global Ticket Printers Production Market
Printers
Global UV LED Printers Market
Printers
Laser Printer Market
Printers
NCR Printers Market
Printers
Multi-Functional Printer Market
Printers
Global Inkjet Coders Market
Printers
Continuous Inkjet Printers Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Mobile Photo Printer Market
Printers
Copier, MFP and Printer Market
Printers
Ink Tank Printer Market
Printers
Refurbished Printers Market
Printers
Global Thermal Printing Market