
 Laser Printer Market | 2026-2036
Laser Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Printer Market Intelligence
Equipment leasing and managed print services are narrowing the competitive field for capital-constrained buyers. HP leverages its global service infrastructure to anchor long-term contracts with enterprise clients. Brother Industries specializes in compact monochrome systems for small enterprises, while Canon extends its imaging portfolio into high-volume production environments. Kyocera competes on ceramic drum durability, reducing total cost of ownership for heavy-use segments.
A laser printer is an electrophotographic device that transfers toner powder onto paper through a laser beam scanning a photosensitive drum, producing resolutions typically ranging from 600 to 2400 dots per inch for commercial and industrial document output. The technology relies on precise fuser assemblies that bond thermoplastic toner particles to substrates at temperatures between 180 and 200 degrees Celsius, enabling rapid, high-volume reproduction. Multifunction configurations now dominate corporate procurement as organizations consolidate scanning, copying, and printing into single-footprint devices. LED-based systems are gaining share in design studios and call centers where space constraints and color accuracy requirements intersect, while monochrome electrophotographic units sustain margin pools in high-speed transactional printing.
The US EPA ENERGY STAR program and EU Ecodesign Directive set mandatory efficiency thresholds for standby power and page-per-watt performance, forcing manufacturers to redesign fuser and power management subsystems. China's SAMR enforces GB standards for electromagnetic compatibility and safety certification, creating separate compliance pathways for products entering that market. India's BIS mandatory registration scheme for electronic goods adds testing timelines that influence regional product launch sequencing. Stakeholders must monitor how tightening circular economy mandates in Europe and Asia reshape cartridge recovery programs and remanufacturing economics.
Market Dynamics
Corporate fleet refresh cycles are compressing as hybrid work stabilization forces IT departments to consolidate distributed print infrastructure into centrally managed multifunction devices with embedded security and cloud connectivity.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power thresholds are accelerating replacement of legacy equipment across German and French corporate campuses, creating pull-through demand for compliant hardware.
- India's educational infrastructure:Government digitization initiatives and state-level smart classroom deployments are expanding hardware procurement cycles for institutional buyers in secondary and tertiary segments.
- LED exposure arrays:Solid-state imaging engines are penetrating design studios and call centers where space constraints intersect with color accuracy requirements, expanding addressable market beyond traditional electrophotography.
Market Restraints
- Fuser assembly input costs:Ceramic heater elements and thermistor arrays face supply concentration from Japanese component specialists, creating margin pressure during commodity cycles.
- China SAMR compliance pathways:Separate GB standards for electromagnetic compatibility and safety certification extend product launch timelines and fragment development resources.
- Digital workflow substitution:Cloud-native document management and electronic signature platforms are displacing transactional print volumes in financial services and legal verticals.
Strategic Opportunities
- India BIS registration acceleration:Mandatory electronic goods registration creates first-mover advantage for vendors who pre-position testing infrastructure and local partnerships ahead of enforcement tightening.
- Circular economy mandates:EU cartridge recovery and remanufacturing economics are creating service revenue pools for vendors with closed-loop logistics capabilities.
- Edge computing convergence:On-device processing for secure print release and document analytics is opening premium positioning for hardware with embedded compute modules.
Industry Challenges
- Firmware security certification:Common Criteria and FIPS 140-2 validation timelines for enterprise-grade devices extend 12-18 months, compressing effective product lifecycles.
- Legacy MFP integration:Hybrid fleets mixing 5-7 year-old devices with current-generation cloud-native systems create patch management complexity and security exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Printer Market |
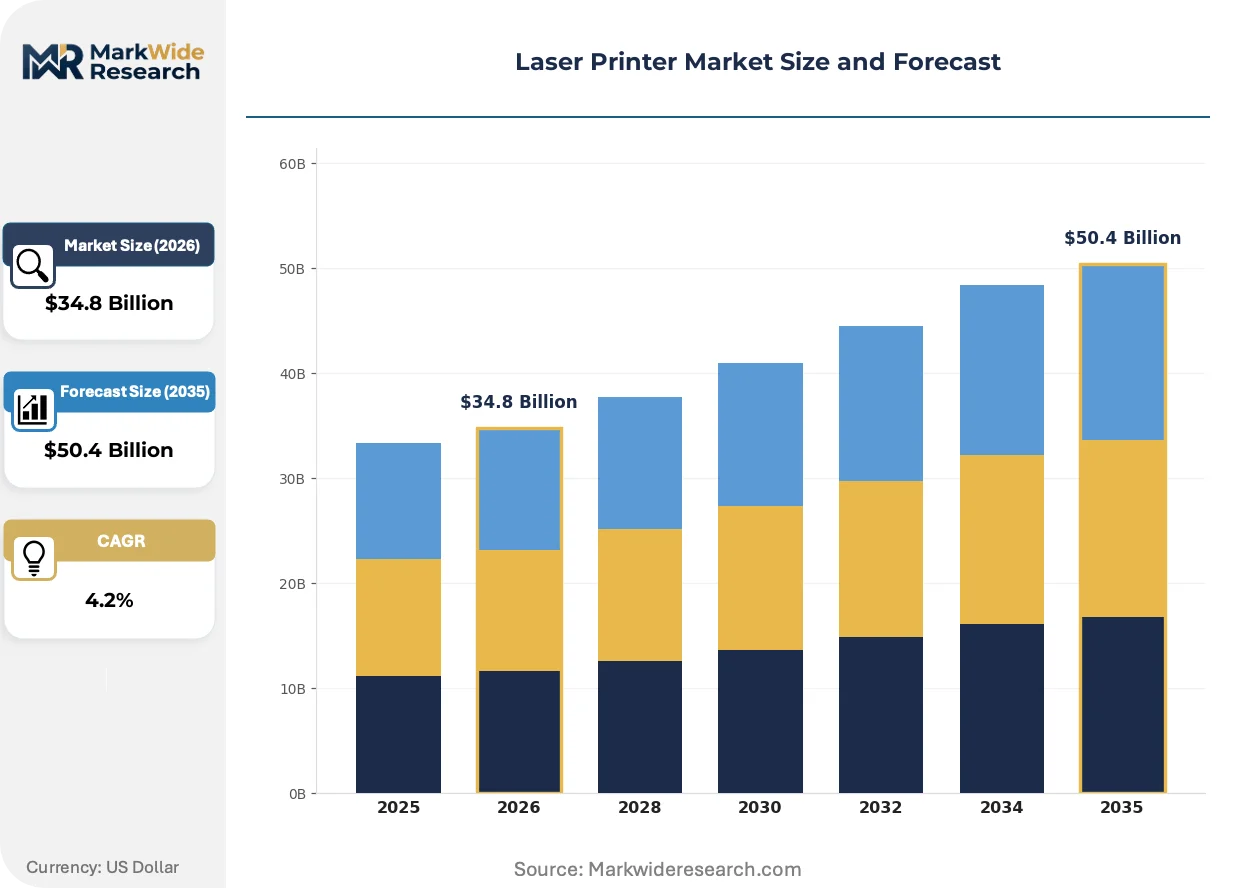
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $50.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochrome, Color, Multifunction, Duplex, High-Speed Technology: Electrophotographic, LED, Solid Ink, Laser Ion, Thermal Transfer Application: Corporate Offices, Educational Institutions, Government Agencies, Design Studios, Call Centers End User: Small Enterprises, Large Enterprises, Print Shops, Non-Profit Organizations |
| Companies Covered | Epson, Kyocera, HP, KIP, Fujifilm, Brother Industries, Xerox, Ricoh, Canon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Printer Market Strategic Shifts & Innovations
Electrophotographic hardware is undergoing platform consolidation as multifunction specifications absorb scanning, copying, and document workflow functions into single-footprint devices with embedded security subsystems.
LED-based exposure systems are rendering obsolete traditional laser scanning assemblies in compact color devices. Design studios and distributed creative teams are adopting these solid-state engines for footprint reduction and color stability. The shift is compressing component supplier bases and rewarding vertically integrated imaging specialists.
China's GB standards for energy-efficient office equipment are forcing redesign of fuser and power management subsystems for products entering that market. Manufacturers must maintain parallel hardware variants or accept feature compromise in global platforms. The compliance burden falls heaviest on mid-volume product tiers where price elasticity limits cost pass-through.
Enterprise purchasing departments are unbundling hardware acquisition from service and supply contracts, reversing the bundled managed print service model that dominated the past decade. Large corporate buyers are negotiating direct hardware procurement with separate competitive bidding for consumables and break-fix support. This bifurcation is most visible in North American Fortune 500 accounts where procurement centralization has matured.
Laser Printer Market Segmentation
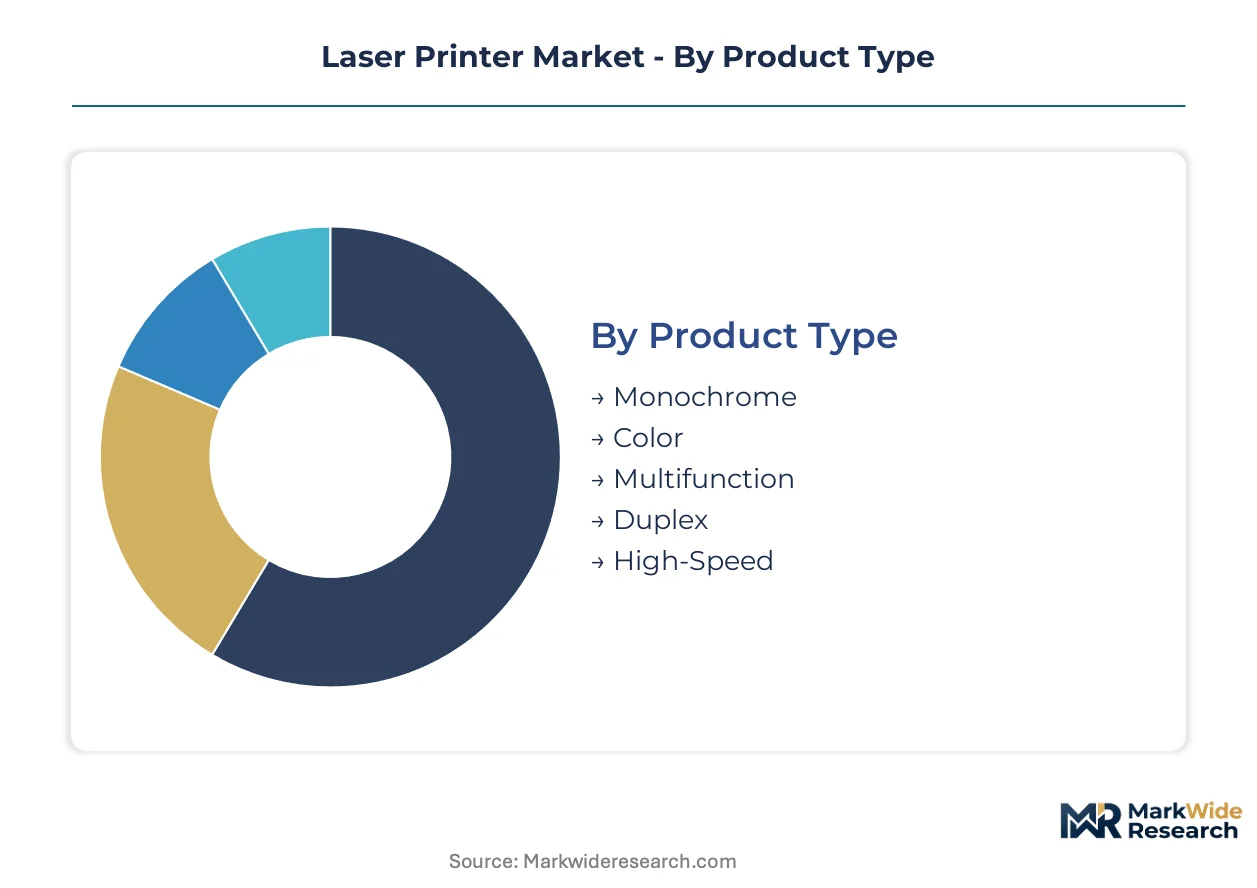
Laser printer segmentation reveals divergent technology maturity curves and procurement patterns across enterprise tiers. Understanding these divisions exposes where hardware margins concentrate versus where service revenue pools form.
Product Type:
Mature monochrome systems coexist with emerging multifunction platforms as fleet consolidation reshapes procurement priorities.
- Monochrome:Single-toner electrophotographic engines deliver 40-60 pages per minute with ceramic drum durability exceeding 100,000 impressions. Demand clusters in financial services transactional printing and legal document discovery where cost-per-page economics dominate equipment selection.
- Color:Four-drum tandem architectures with CMYK toner development units achieve 2400 dpi effective resolution through multi-pass exposure. Corporate marketing departments and in-house creative teams in Germany and France are refreshing fleets to meet EU Ecodesign standby power thresholds.
- Multifunction:Consolidated scanning, copying, and printing subsystems with embedded document workflow software.
- Duplex:Automatic document feeders with reverse-path paper handling for double-sided output.
- High-Speed:Production-grade engines exceeding 100 ppm for centralized print centers.
Monochrome retains volume leadership; multifunction holds the steepest expansion curve.
Technology:
Cost tier stratification separates established electrophotographic platforms from emerging solid-state alternatives.
- Electrophotographic:Rotating polygon mirror laser scanning assemblies with precision optics remain the cost-optimized foundation for mid-volume corporate fleets. Japanese component specialists control fuser assembly supply, creating margin pressure during commodity cycles.
- LED:Solid-state exposure arrays eliminate moving optical elements, reducing footprint and improving color stability in compact devices. Design studios in Tokyo and distributed creative teams across California are adopting these engines where space constraints intersect with color accuracy requirements.
- Solid Ink:Wax-based colorant blocks melted and jetted onto drums for specialized graphic arts applications.
- Laser Ion:Ion deposition imaging for high-speed transactional printing in banking and insurance verticals.
- Thermal Transfer:Ribbon-based monochrome output for barcode and label production environments.
Electrophotographic dominates installed base; LED is climbing the fastest among emerging alternatives.
Application:
Customer type differentiation separates centralized procurement from distributed departmental purchasing.
- Corporate Offices:Fleet refresh programs consolidating hybrid work infrastructure into centrally managed multifunction devices with embedded security and cloud connectivity. North American Fortune 500 accounts are unbundling hardware acquisition from service contracts.
- Educational Institutions:State-level smart classroom deployments and government digitization initiatives in India are accelerating hardware procurement cycles for secondary and tertiary segments.
- Government Agencies:Mandatory BIS registration schemes and extended firmware security certification timelines.
- Design Studios:Color-critical workflows requiring LED exposure stability and ICC profile management.
- Call Centers:High-volume transactional output with space-constrained footprints favoring compact LED systems.
Corporate offices anchor procurement volume; educational institutions in India are gaining share fastest.
End User:
Volume scale separates enterprise fleet managers from price-sensitive small business purchasers.
- Small Enterprises:Compact monochrome systems with total cost of ownership optimization drive selection criteria. Brother Industries specializes in this tier with ceramic drum durability reducing maintenance intervals.
- Large Enterprises:Managed print service contracts with embedded security subsystems and cloud-native document analytics. HP leverages global service infrastructure to anchor long-term agreements.
- Print Shops:Production environments requiring high-volume throughput and substrate flexibility.
- Non-Profit Organizations:Grant-funded procurement with extended equipment lifecycles and remanufactured cartridge acceptance.
Large enterprises concentrate service revenue; small enterprises expand addressable market breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in laser printer hardware and consumables reveal asymmetric dependencies between manufacturing clusters and consumption centers. Component exports from Japanese precision specialists feed assembly operations across multiple continents, while finished equipment moves toward corporate procurement hubs in North America and Europe.
United States
Fortune 500 fleet refresh programs and federal procurement standardization drive equipment demand. The EPA ENERGY STAR program mandates standby power thresholds that disqualify legacy hardware from government contracts. Dallas-Fort Worth hosts centralized distribution infrastructure for North American enterprise accounts.
Germany
Industrial Mittelstand and automotive corporate campuses sustain high-volume monochrome procurement. The EU Ecodesign Directive enforces page-per-watt efficiency minimums that accelerate replacement cycles. Stuttgart engineering clusters source production-grade systems for technical documentation workflows.
China
Domestic enterprise digitization and educational infrastructure expansion create hardware pull-through. SAMR enforces GB standards for electromagnetic compatibility that fragment global product platforms. Shenzhen manufacturing corridors concentrate fuser assembly and precision optical component production.
India
State-level smart classroom deployments and government digitization initiatives accelerate institutional procurement. BIS mandatory registration for electronic goods extends vendor qualification timelines. Karnataka's Bangalore-Chennai corridor anchors southern regional distribution for educational sector tenders.
Japan
Corporate office consolidation and call center infrastructure sustain replacement demand. METI industrial efficiency guidelines influence enterprise equipment selection criteria. Nagoya precision manufacturing clusters supply ceramic drum components and fuser heater elements to global assembly networks.
Laser Printer Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated imaging specialists and diversified electronics conglomerates with captive component capabilities. Strategic differentiation separates full-service enterprise vendors from compact system specialists and production-environment niche players. Dominant competitive moves include geographic footprint expansion through local manufacturing partnerships and technology licensing arrangements for LED exposure arrays.
Among diversified imaging conglomerates, Canon and Fujifilm occupy positions spanning consumer photography through production print environments. HP anchors the enterprise managed print service segment through global service infrastructure. Brother Industries exemplifies the compact monochrome specialist archetype, while Kyocera represents ceramic drum durability differentiation for high-impression applications.
| Leading Market Players |
|---|
| Epson |
| Kyocera |
| HP |
| KIP |
| Fujifilm |
| Brother Industries |
| Xerox |
| Ricoh |
| Canon |
| Others |
Cost & Logistics Intelligence
Overcapacity in Shenzhen precision component corridors is pressuring fuser assembly suppliers to absorb margin compression while OEMs consolidate procurement leverage across monochrome and color electrophotographic platforms.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the laser printer market. Price differentiation hinges on ENERGY STAR certification tier and managed print service bundling intensity. Cost compression in mid-volume segments is intensifying because Chinese SAMR compliance extends development timelines and fragments platform economics. Small enterprises exhibit highest price sensitivity, while Fortune 500 accounts prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk calculus for ceramic heater element procurement. Component concentration rests on Nagoya precision manufacturing clusters, Shenzhen assembly corridors, and Kuala Lumpur distribution hubs. Raw material dependencies include rare-earth magnets for laser scanning motors, ceramic substrates for drum substrates, and specialized thermoplastics for toner particle engineering. Single-source vulnerability persists in fuser thermistor arrays. Distribution runs through Dallas-Fort Worth and Rotterdam for North American and European enterprise accounts respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser printer market is cycling through post-hybrid-work stabilization as corporate fleet refresh programs replace aging electrophotographic infrastructure with EU Ecodesign-compliant multifunction platforms.
For Market Incumbents: Build switching-cost moats through embedded document workflow software and cloud-native fleet management portals. Deepen backward integration into ceramic drum manufacturing to offset Japanese component specialist pricing power. Pre-position BIS testing infrastructure in India ahead of enforcement tightening to capture educational sector tenders before competitors qualify.
For New Entrants and Emerging Players: India's state-level smart classroom deployments represent the most penetrable white-space target for compact LED-based systems. Design studio segments in California and Tokyo offer color-critical workflow entry points with lower incumbent service contract saturation. Pursue direct hardware procurement relationships with procurement-centralized Fortune 500 accounts that have unbundled from managed print service bundles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LED exposure array manufacturing as solid-state imaging engines achieve production scale. Long-term viability favors vendors with closed-loop cartridge logistics capabilities aligned with EU circular economy mandates. Monitor BIS registration acceleration timelines as the signal for India market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Exposure Array Adoption | Solid-state imaging eliminates moving optics for design studio footprint reduction. |
| Managed Print Service Unbundling | Fortune 500 procurement centralization separates hardware from consumables contracts. |
| BIS Pre-Registration Investment | First-mover testing infrastructure captures India educational sector tender cycles. |
| Circular Economy Logistics Buildout | Closed-loop cartridge recovery creates service revenue pools under EU mandates. |
| Firmware Security Certification | Common Criteria validation extends product lifecycles for government contract eligibility. |
Research Approach
A standing panel of fleet procurement managers, managed print service operations directors, OEM product planners, and aftermarket consumables distributors provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against EPA ENERGY STAR certification databases, EU Ecodesign Directive compliance filings, and India BIS registration records. Bottom-up equipment shipment tracking and top-down corporate IT spending analysis were triangulated to establish market sizing.
Scenario-bracketing framed demand projections across the analysis window, modeling segmentation dimensions including product type tier, technology platform, end-user scale, and regional regulatory cluster. CAGRs were derived from equipment refresh cycle compression rates and institutional procurement acceleration patterns. Forecast inputs incorporated hybrid work stabilization trajectories and educational infrastructure spending timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic electrophotographic specialists would shift outcomes. Material shifts in EU circular economy enforcement stringency or India BIS registration timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Aerosol Printing and Graphics Market
Printers
Thermal Printer Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
Inkjet Printers Market
Printers
Refurbished Printers Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Single Function Printer Market
Printers
Dot Matrix Printer Market
Printers
Inkjet Printing Market
Printers
Electrophotographic Printing Market
Printers
Indonesia Thermal Printer Market
Printers
Global UV LED Printers Market
Printers
Multi-Functional Printer Market
Printers
Global Ticket Printers Production Market
Printers
Nanographic Printing Market
Printers
Copier, MFP and Printer Market