
 Thermal Printer Market | 2026-2036
Thermal Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Printer Market Analysis
China is reconfiguring regional supply dynamics through expanded domestic production of printhead assemblies and precision thermal mechanisms. Zebra Technologies Corporation leverages its North American service infrastructure to sustain enterprise fleet contracts across logistics and healthcare. Toshiba Tec Corporation anchors its position in high-volume retail installations through proprietary direct thermal engines. SATO Holdings Corporation specializes in RFID-integrated thermal systems for pharmaceutical track-and-trace applications.
A thermal printer generates images by selectively heating coated thermochromic paper or transferring ink from a ribbon onto a substrate through precise thermal element control, with print resolutions typically ranging from 203 to 600 dots per inch and operating temperatures between 50°C and 150°C depending on media type. These devices serve commercial and industrial functions including barcode label generation, receipt printing, patient wristband creation, and shipping documentation across high-throughput environments. Label printers dominate installed base volumes in warehouse and distribution settings where continuous-form output and peel-and-present mechanisms reduce labor touchpoints. Mobile printers represent the fastest-expanding technology category as field service technicians and delivery operators adopt Bluetooth-connected units for on-demand documentation. Direct thermal technology retains cost advantages in short-lifecycle applications such as receipts and shipping labels, though thermal transfer systems command premium positioning where archival durability and chemical resistance justify higher consumable spend.
FDA 21 CFR Part 11 and UDI (Unique Device Identification) requirements shape product specifications for healthcare thermal printers by mandating machine-readable labels with specific data matrix formats and human-readable content. EPA guidelines on chemical constituents in thermal paper coatings, particularly bisphenol-A restrictions, compel manufacturers to reformulate heat-sensitive media and validate alternative developer chemistry. ECHA REACH compliance in Europe adds substance-level documentation burdens for ribbon coatings and adhesive layers used in industrial labeling. Stakeholders must monitor evolving chemical safety thresholds across FDA, EPA, and ECHA jurisdictions while assessing whether printhead durability improvements or media formulation shifts offer more defensible paths to margin protection.
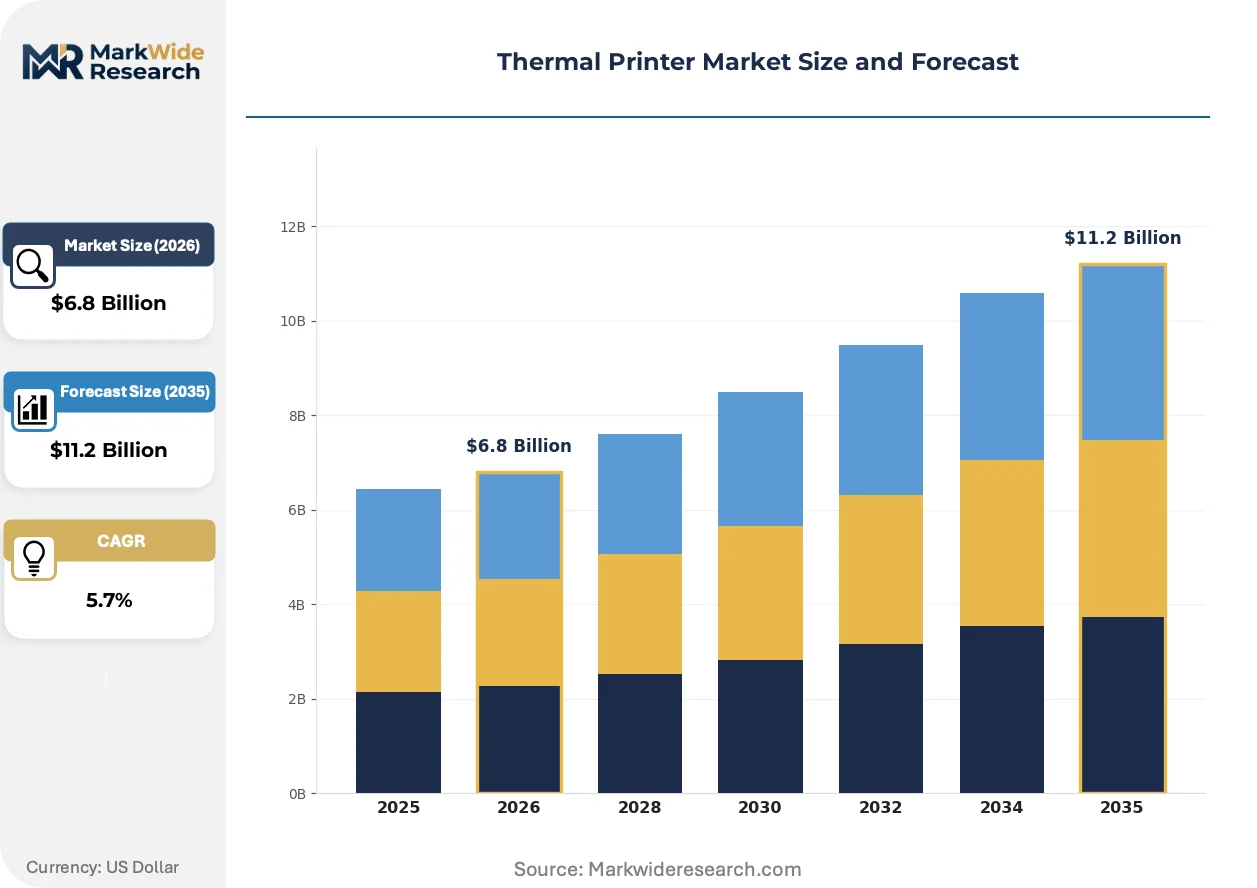
Market Dynamics
Warehouse automation and last-mile logistics networks in the United States are compressing replacement cycles for industrial-grade thermal units, while FDA labeling mandates tighten compliance requirements for variable-data print systems across healthcare supply chains.
Growth Catalysts
- FDA UDI mandates:Medical device manufacturers must deploy machine-readable labels with specific data matrix formats, forcing fleet upgrades across hospital systems and device suppliers.
- Self-checkout expansion:Retail chains across North America and Europe are accelerating deployment of receipt and label printers at automated point-of-sale terminals.
- Bluetooth-connected mobile units:Field service technicians and delivery operators are adopting wireless thermal printers for on-demand documentation in distributed logistics networks.
Market Restraints
- Printhead supply concentration:Precision thermal mechanisms and printhead assemblies concentrate manufacturing in China, creating single-source vulnerability for Western OEMs.
- Bisphenol-A regulatory pressure:EPA restrictions on thermal paper coatings compel expensive media reformulation and alternative developer chemistry validation.
- Direct thermal durability limits:Short-lifecycle applications cannot match thermal transfer archival performance, restricting premium positioning in chemical-resistant labeling segments.
Strategic Opportunities
- RFID-integrated systems:Pharmaceutical track-and-trace applications are opening white space for hybrid thermal-RFID units in serialization compliance.
- India warehouse automation:E-commerce fulfillment centers in Mumbai and Bangalore are underpenetrated for industrial-grade label printer deployment.
- EU CSRD reporting:Corporate sustainability disclosure requirements are creating demand for carbon-footprint labeling solutions on secondary packaging.
Industry Challenges
- Firmware validation timelines:FDA 21 CFR Part 11 compliance requires extensive documentation of software-controlled print systems, extending product launch cycles.
- Legacy ERP integration:Warehouse management systems from the 2010s lack native drivers for modern thermal printer communication protocols, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Printer Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Label Printer, Mobile Printer, Kiosk Printer, Industrial Printer Technology: Direct Thermal, Thermal Transfer, Hybrid Technology, RFID End User: Retail, Transportation, Healthcare, Hospitality Installation: On-Premises, Cloud-Based, Integrated Systems, Standalone Units |
| Companies Covered | Honeywell International Inc., Toshiba Tec Corporation, Zebra Technologies Corporation, Citizen Systems Japan Co., Ltd., TSC Auto ID Technology Co., Ltd., Brother Industries, Ltd., SATO Holdings Corporation, Star Micronics Co., Ltd., Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Printer Market Emerging Trajectories
Cloud-native print management architectures are virtualizing fleet control, while regulatory chemical bans and sustainability mandates are reformulating consumable supply chains. Buyer behavior is shifting toward service-contract bundling that decouples hardware acquisition from per-label economics.
Printhead firmware is virtualizing through over-the-air update capabilities, enabling remote resolution of thermal element calibration drift without technician dispatch. Third-party logistics providers in the United States are deploying these connected units fastest, compressing mean-time-to-repair from days to hours and reducing spare parts inventory carrying costs across multi-site distribution networks.
REACH substance restrictions in Europe are forcing ribbon coating suppliers to document adhesive layer chemistry at the substance level, adding documentation burdens that smaller consumable manufacturers cannot absorb. Industrial labeling segments serving medical device exporters are responding fastest, consolidating supplier relationships toward ECHA-registered formulation houses with existing substance-level dossiers.
Service unbundling is accelerating as enterprise buyers separate hardware procurement from consumable supply and technical support. Large retail chains in Germany and France are piloting per-label pricing contracts that transfer printhead replacement risk to OEMs, shifting capital expenditure to operational expenditure and demanding real-time usage telemetry from deployed fleets.
Thermal Printer Market Segmentation
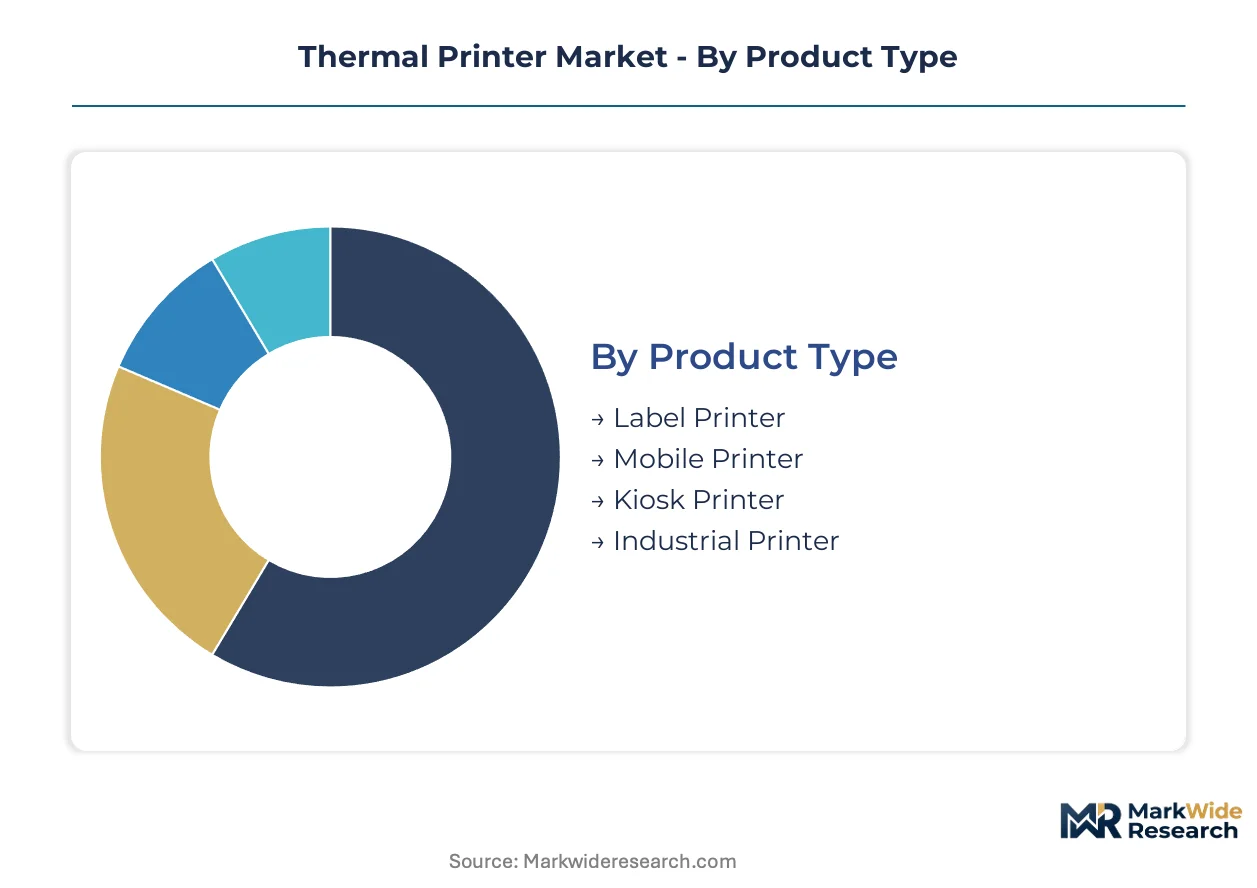
Thermal printer segmentation reveals divergent technology lifecycles and procurement patterns across product architectures. Understanding these divides helps vendors align R&D investment with replacement cycle timing and compliance-driven upgrade windows.
Product Type:
Mature stationary formats coexist with emerging portable architectures as field mobility reshapes documentation workflows.
- Label Printer:Fixed-mount units with continuous-form media handling and peel-and-present mechanisms dominate warehouse and distribution center deployments. Demand concentrates in United States logistics networks where warehouse automation compresses replacement cycles for industrial-grade units handling high-throughput barcode generation.
- Mobile Printer:Battery-powered Bluetooth-connected devices enable on-demand receipt and label generation for field service technicians and delivery operators. Adoption is climbing fastest in last-mile logistics networks across Germany and France as carriers deploy real-time proof-of-delivery documentation systems.
- Kiosk Printer:Compact enclosed mechanisms designed for unattended self-service terminals in retail and transit environments.
- Industrial Printer:Heavy-duty units with metal chassis and 24/7 duty cycles serving manufacturing and bulk distribution operations.
Label printers handle the majority of throughput; mobile printers are gaining share fastest as distributed logistics networks expand.
Technology:
Cost-to-durability tradeoffs segment buyer selection between disposable output and archival-grade labeling requirements.
- Direct Thermal:Heat-activated imaging on thermochromic paper eliminates ribbon costs but produces limited-lifecycle output susceptible to heat and UV degradation. Retail receipt and short-term shipping label applications in North American grocery chains favor this technology for its minimal consumable overhead.
- Thermal Transfer:Wax or resin ribbon melting onto substrate delivers chemical resistance and multi-year legibility required for FDA UDI medical device labels and pharmaceutical serialization. Healthcare supply chains in the United States mandate this format for compliance with 21 CFR Part 11 durability standards.
- Hybrid Technology:Dual-mode engines switch between direct thermal and thermal transfer based on media loaded.
- RFID:Integrated inlay encoding alongside visual print for pharmaceutical track-and-trace and asset management applications.
Thermal transfer commands premium positioning in regulated verticals; RFID integration shows steepest expansion trajectory as serialization mandates proliferate.
End User:
Regulatory intensity and automation maturity create distinct procurement cadences across vertical markets.
- Retail:Self-checkout terminal deployments and inventory management systems drive label and receipt printer demand. European supermarket chains in France and Germany are accelerating automated point-of-sale printer deployment to reduce labor touchpoints.
- Transportation:Fleet documentation, shipping label generation, and proof-of-delivery systems require ruggedized mobile and fixed-mount units. Third-party logistics providers in the United States are adopting cloud-connected thermal fleets to compress mean-time-to-repair across multi-site networks.
- Healthcare:Patient wristband printing, specimen labeling, and medical device UDI compliance impose strict validation requirements.
- Hospitality:Guest receipt, kitchen ticket, and loyalty program label applications prioritize low-cost direct thermal output.
Transportation absorbs the highest unit volumes; healthcare exhibits the most rapid compliance-driven upgrade activity.
Installation:
Architecture choices reflect IT infrastructure maturity and fleet management complexity across enterprise scales.
- On-Premises:Locally hosted print servers and device drivers remain standard for security-sensitive healthcare and financial services deployments. Hospital systems in the United States maintain this architecture to satisfy FDA 21 CFR Part 11 audit trail requirements for software-controlled print systems.
- Cloud-Based:Browser-administered fleet management enables remote firmware updates and usage telemetry without VPN infrastructure. Large retail chains in Germany are piloting per-label pricing contracts contingent on real-time cloud telemetry from deployed units.
- Integrated Systems:Native connections to warehouse management and ERP platforms eliminate middleware dependencies.
- Standalone Units:USB or serial-connected devices operating independently of network infrastructure serve small-format retail and hospitality sites.
On-premises retains dominance in regulated environments; cloud-based deployment is expanding most quickly among multi-location retail enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision thermal mechanisms concentrate manufacturing in China, yet demand clusters in mature logistics networks across the United States, Germany, and Japan where warehouse automation and regulatory compliance drive replacement cycles.
United States
Warehouse automation and last-mile logistics networks compress replacement cycles for industrial-grade thermal units. FDA 21 CFR Part 11 and UDI mandates force fleet upgrades across hospital systems and medical device suppliers. Third-party logistics providers in Chicago and Dallas-Fort Worth deploy cloud-connected thermal fleets to compress mean-time-to-repair.
China
Domestic production of printhead assemblies and precision thermal mechanisms reconfigures regional supply dynamics. MIIT standards and GB certification requirements shape local manufacturing compliance. Yangtze River Delta clusters around Shanghai and Suzhou anchor export-oriented thermal printer fabrication.
Germany
Retail chains accelerate self-checkout terminal deployments with automated point-of-sale printers. ECHA REACH compliance adds substance-level documentation burdens for ribbon coatings and adhesive layers. Industrial labeling demand concentrates in Bavaria's manufacturing belt around Munich and Nuremberg.
Japan
High-volume retail installations and precision manufacturing sustain demand for proprietary direct thermal engines. METI industrial standards and JIS certification frameworks govern equipment specifications. Kanto region clusters around Tokyo and Yokohama host headquarters operations for major thermal printer OEMs.
India
E-commerce fulfillment centers in Mumbai and Bangalore remain underpenetrated for industrial-grade label printer deployment. BIS certification and DGFT import regulations shape equipment procurement patterns. Maharashtra and Karnataka states lead warehouse automation investment.
Thermal Printer Market Vendor Landscape
Industrial-system specialists and precision-component fabricators split the market into technology-tiered competitive bands. Consolidation pressures concentrate around printhead supply security and firmware validation capabilities. Three archetypes dominate: vertically integrated OEMs controlling thermal mechanism production, regional assemblers sourcing precision components from China, and software-centric vendors bundling fleet management platforms. Dominant competitive moves include backward integration into printhead manufacturing and cloud-native service contract bundling.
Within the vertically integrated tier, Honeywell International Inc. and Zebra Technologies Corporation exemplify North American infrastructure plays, while Toshiba Tec Corporation anchors Japanese precision-engineering positioning. SATO Holdings Corporation occupies a specialist niche in RFID-integrated systems.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Toshiba Tec Corporation |
| Zebra Technologies Corporation |
| Citizen Systems Japan Co., Ltd. |
| TSC Auto ID Technology Co., Ltd. |
| Brother Industries, Ltd. |
| SATO Holdings Corporation |
| Star Micronics Co., Ltd. |
| Seiko Epson Corporation |
| Others |
Supply Flow & Price Mechanics
Printhead assembly concentration in China creates single-source vulnerability that compresses margin buffers for Western OEMs while simultaneously widening the spread between thermal transfer premium tiers and direct thermal economy positioning. This dependency structure forces buyers to absorb cost volatility through tiered procurement strategies or accept extended lead times for precision thermal mechanisms.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across healthcare deployments, where validation documentation and audit trail capabilities separate premium thermal transfer systems from standard direct thermal units. Price differentiation hinges on certification grade for pharmaceutical serialization compliance and after-sales service bundling that transfers printhead replacement risk to manufacturers. Cost compression in economy-tier direct thermal receipt printers is intensifying because retail chains in Germany and France are consolidating fleet contracts around per-label operational expenditure models. Hospital systems in the United States exhibit the lowest price sensitivity due to regulatory non-negotiability, while hospitality operators prioritize minimal acquisition cost over durability specifications.
Supply Chain Analysis
Export control regimes on precision semiconductor manufacturing equipment constrain Western OEMs from replicating Chinese thermal mechanism production capabilities domestically. Manufacturing gravity centers on China for printhead assemblies and precision thermal elements, with secondary concentrations in Japan for proprietary direct thermal engines and the United States for cloud-connected fleet management firmware. Raw material dependencies span ceramic substrates for thermal elements, specialized ribbon coatings requiring ECHA REACH documentation, and thermochromic paper formulations reformulated to exclude bisphenol-A. Single-source vulnerability concentrates in Yangtze River Delta fabrication clusters. Distribution runs through authorized service networks for enterprise healthcare contracts and direct e-commerce channels for mobile printer accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehouse automation penetration in Indian e-commerce fulfillment centers signals early-cycle expansion opportunity as Mumbai and Bangalore infrastructure investments lag comparable automation density in United States logistics networks. Bluetooth-connected mobile printer adoption among European last-mile carriers confirms field mobility as the fastest-proliferating documentation paradigm.
For Market Incumbents: Entrench position through backward integration into printhead manufacturing or captive supply agreements with Yangtze River Delta fabricators to mitigate single-source exposure. Invest in firmware validation capabilities to compress FDA 21 CFR Part 11 compliance timelines and defend against software-centric fleet management entrants. Prioritize cloud-native service contract bundling that decouples hardware acquisition from per-label economics for large retail chain procurement committees. For New Entrants and Emerging Players: Pursue white space in RFID-integrated hybrid thermal systems for pharmaceutical track-and-trace serialization mandates where SATO Holdings Corporation currently dominates. Target underpenetrated industrial-grade label printer deployment in Indian e-commerce fulfillment centers around Mumbai and Bangalore. Anchor go-to-market strategy through per-label pricing contracts contingent on real-time usage telemetry, transferring capital expenditure burden to operational expenditure frameworks favored by European retail procurement teams. For Investors and Strategic Acquirers: Firmware-validation specialists with existing FDA 21 CFR Part 11 documentation dossiers represent the most defensible acquisition archetype as regulatory compliance timelines extend product launch cycles. Long-term viability over the next decade hinges on printhead supply security and cloud-connected fleet management platform integration. Watch for inflection signals in India warehouse automation investment intensity across Maharashtra and Karnataka states, where e-commerce fulfillment center buildouts will compress replacement cycle timing for industrial-grade thermal units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printhead Manufacturing | Captive supply of precision thermal mechanisms from Yangtze River Delta clusters mitigates single-source vulnerability for Western OEMs. |
| Cloud-Native Fleet Management Platform | Browser-administered print servers enable per-label pricing contracts with real-time telemetry from German retail chain deployments. |
| RFID-Integrated Hybrid System Development | Dual-mode thermal-RFID engines capture pharmaceutical serialization compliance demand from FDA UDI mandate expansion. |
| Firmware Validation Capability Investment | Software-controlled print system documentation accelerates FDA 21 CFR Part 11 product launch timelines for healthcare verticals. |
| India Distribution Channel Establishment | Localized service infrastructure addresses underpenetrated warehouse automation demand in Mumbai and Bangalore fulfillment centers. |
Methodological Framework
Cross-validation between primary interviews with warehouse automation directors, healthcare biomedical engineers, retail procurement managers, and thermal printer OEM product strategists anchors the qualitative findings against secondary validation from FDA 510(k) filings, ECHA REACH substance dossiers, SEC 10-K equipment segment disclosures, and customs trade data on printhead assembly imports. Bottom-up triangulation across installed base estimates and top-down reconciliation against logistics automation capital expenditure surveys ensure dimensional consistency. Conversations with third-party logistics providers in Chicago and Dallas-Fort Worth yielded cloud-connected fleet deployment timelines, while hospital purchasing committees in the United States clarified FDA compliance documentation burdens.
Calibration against historical replacement cycle data and regulatory mandate implementation schedules shapes the analytical framework across the analysis window. Segmentation dimensions span product architecture, imaging technology, end-use vertical, and installation topology, with geographic regulatory cluster as an additional cross-cutting variable. CAGRs derive from logistic curve penetration modeling for mobile printer adoption and compliance-driven upgrade cycle timing for healthcare thermal transfer systems. Industry-specific forecast inputs include warehouse automation density indices and pharmaceutical serialization mandate phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in e-commerce fulfillment center investment intensity or cross-border trade friction on precision components would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement continuity and printhead supply chain stability. Material shifts in FDA UDI mandate scope or EPA bisphenol-A enforcement thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Retail Printers and Consumables Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Refurbished Printers Market
Printers
Indonesia Thermal Printer Market
Printers
Thermal Inkjet Printer Market
Printers
Global Inkjet Coders Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Single Function Printer Market
Printers
Multi-Functional Printer Market
Printers
Mobile Photo Printer Market
Printers
Global Printer Market
Printers
Electrophotographic Printing Market
Printers
Aerosol Printing and Graphics Market
Printers
Mobile Printer Market
Printers
NCR Printers Market
Printers
Portable Printer Market