
 Global Janitorial Cart Market | 2026-2036
Global Janitorial Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Global Janitorial Cart Market Outlook
REACH is restructuring material-selection protocols for janitorial cart manufacturers selling into European commercial and healthcare channels. Rubbermaid Commercial Products leverages its North American manufacturing footprint to sustain cost advantages across plastic-molded utility cart lines. Continental Commercial Products anchors its position through specialized stainless-steel fabrication for healthcare-grade applications. Carlisle Food Service Products differentiates via vertical integration into polymer compounding for durable, chemical-resistant cart bodies.
A janitorial cart is a wheeled mobile workstation engineered from structural polymers, stainless steel, or aluminum, typically incorporating molded shelves, sealed compartments, and casters rated for specific load capacities, designed to transport cleaning chemicals, tools, and waste within commercial and institutional environments. Heavy-duty carts dominate value pools where durability requirements and replacement cycles extend operational life in high-traffic facilities such as airports and hospitals. Compact carts represent the fastest-expanding configuration as space-constrained urban commercial buildings and residential settings prioritize maneuverability in narrow corridors and elevator-accessible floors. Plastic material formulations lead volume production due to lower unit costs and corrosion immunity, though stainless steel commands premium positioning in healthcare end-use segments where sterilization compatibility governs procurement decisions.
The EPA regulates chemical-storage and labeling standards that directly influence cart compartment design and secondary containment features for commercial cleaning operations in the United States. ECHA enforces REACH substance restrictions that constrain polymer additives and surface coatings deployed in European-manufactured or imported carts. BIS certification requirements in India add compliance layers for imported metal and plastic components entering institutional procurement channels. Stakeholders must monitor evolving material-safety regulations across multiple jurisdictions to align product-development roadmaps with shifting compliance thresholds and procurement qualification criteria.
Market Dynamics
REACH substance restrictions and EPA chemical-storage standards are forcing manufacturers to redesign cart compartments, material formulations, and secondary containment systems across all major commercial channels.
Growth Catalysts
- Healthcare infection-control mandates:Hospitals in the United States, Germany, and Japan are expanding procurement of sealed-compartment carts to meet Joint Commission and WHO sterilization protocols. Specialized stainless-steel fabrication commands premium positioning in operating theater environments.
- REACH compliance deadlines:ECHA substance restrictions on polymer additives and surface coatings are accelerating replacement cycles for non-compliant cart fleets across European commercial and institutional buyers.
- Urban building densification:Space-constrained commercial properties in Singapore, South Korea, and the Netherlands are driving demand for compact, elevator-compatible configurations with enhanced maneuverability.
Market Restraints
- Polymer resin cost volatility:Structural polymer feedstock prices fluctuate with crude oil and natural gas benchmarks, compressing margins on plastic-molded utility cart lines.
- Stainless steel supply concentration:Healthcare-grade 304 and 316 stainless fabrication capacity concentrates in Chinese and Indian metalworking clusters, creating geographic dependency for premium cart segments.
- Secondary containment technical limits:Current sealed-compartment designs face load-capacity trade-offs that restrict chemical-volume storage in compact cart configurations.
Strategic Opportunities
- Indian institutional modernization:BIS certification requirements and government healthcare infrastructure spending are opening procurement channels for compliant imported and locally manufactured carts.
- IoT-enabled inventory tracking:Convergence of RFID tagging and cloud-based asset management systems allows facility managers to monitor supply levels and maintenance schedules remotely.
- EU Green Deal procurement incentives:Public-sector buyers in France, Italy, and Spain now weight recycled-content thresholds and end-of-life recyclability in tender evaluations.
Industry Challenges
- Multi-jurisdiction compliance engineering:Product-development teams must simultaneously satisfy EPA chemical-storage standards, REACH substance restrictions, and BIS certification timelines, extending qualification cycles.
- Legacy fleet integration complexity:Healthcare facilities with mixed-vendor cart populations face interoperability gaps when upgrading to smart-enabled or specialized infection-control configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Janitorial Cart Market |
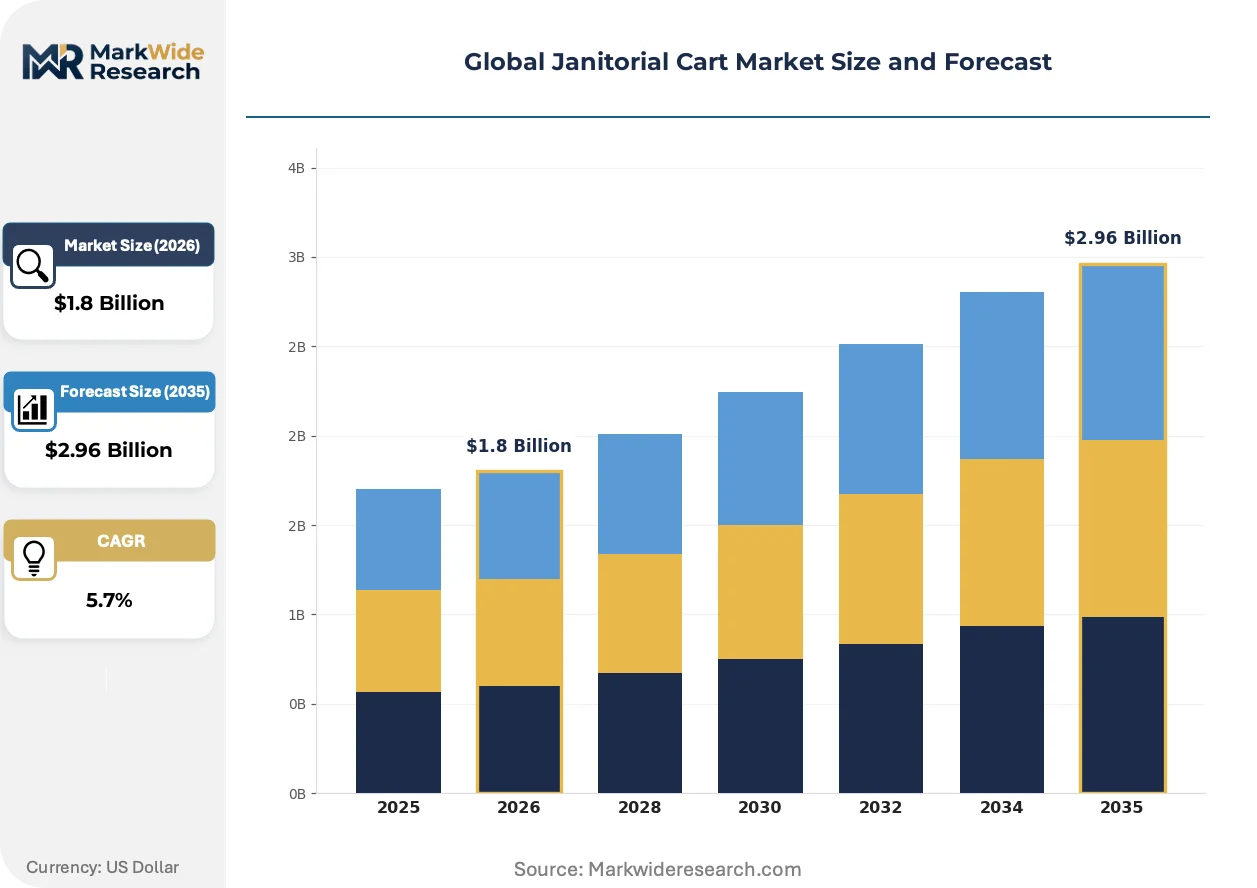
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cart, Utility Cart, Heavy-Duty Cart, Compact Cart Material: Plastic, Stainless Steel, Aluminum, Wood End User: Commercial Facilities, Residential Settings, Healthcare, Educational Institutions Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Rubbermaid Commercial Products, Forbes Industries Inc., Fitch Co., Arcat, Inc., Dura Wax Company, Carlisle Food Service Products, Continental Commercial Products, Architectural Brass, Geerpres Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Janitorial Cart Market Strategic Shifts
Modular polymer compounding and connected asset-tracking systems are restructuring how manufacturers design, produce, and service janitorial carts across commercial and institutional segments.
Advanced polymer formulations with embedded antimicrobial additives are decentralizing the traditional separation between cart body materials and surface disinfection protocols. Healthcare facilities in Germany and the United States are adopting these integrated-material carts at accelerated replacement cycles. The technology is decentralizing procurement decisions from facilities management to infection-control committees with distinct sterilization-compliance authority.
EPA chemical-storage and labeling standards are tightening compartment-design specifications for commercial cleaning operations across the United States. Manufacturers must now engineer secondary containment features and sealed drainage systems that satisfy secondary spill-containment thresholds. Hospital and airport procurement teams in California, Texas, and New York are prioritizing pre-certified designs to accelerate vendor qualification.
Facility managers are consolidating vendor relationships and demanding bundled service contracts covering equipment, consumables, and preventive maintenance. Distributors serving hospitality and corporate office segments face margin compression as direct manufacturer engagement displaces traditional wholesale channels. This concentration is most visible in the United Kingdom and Australia where facilities management outsourcing has concentrated buying power with national service providers.
Global Janitorial Cart Market Segmentation
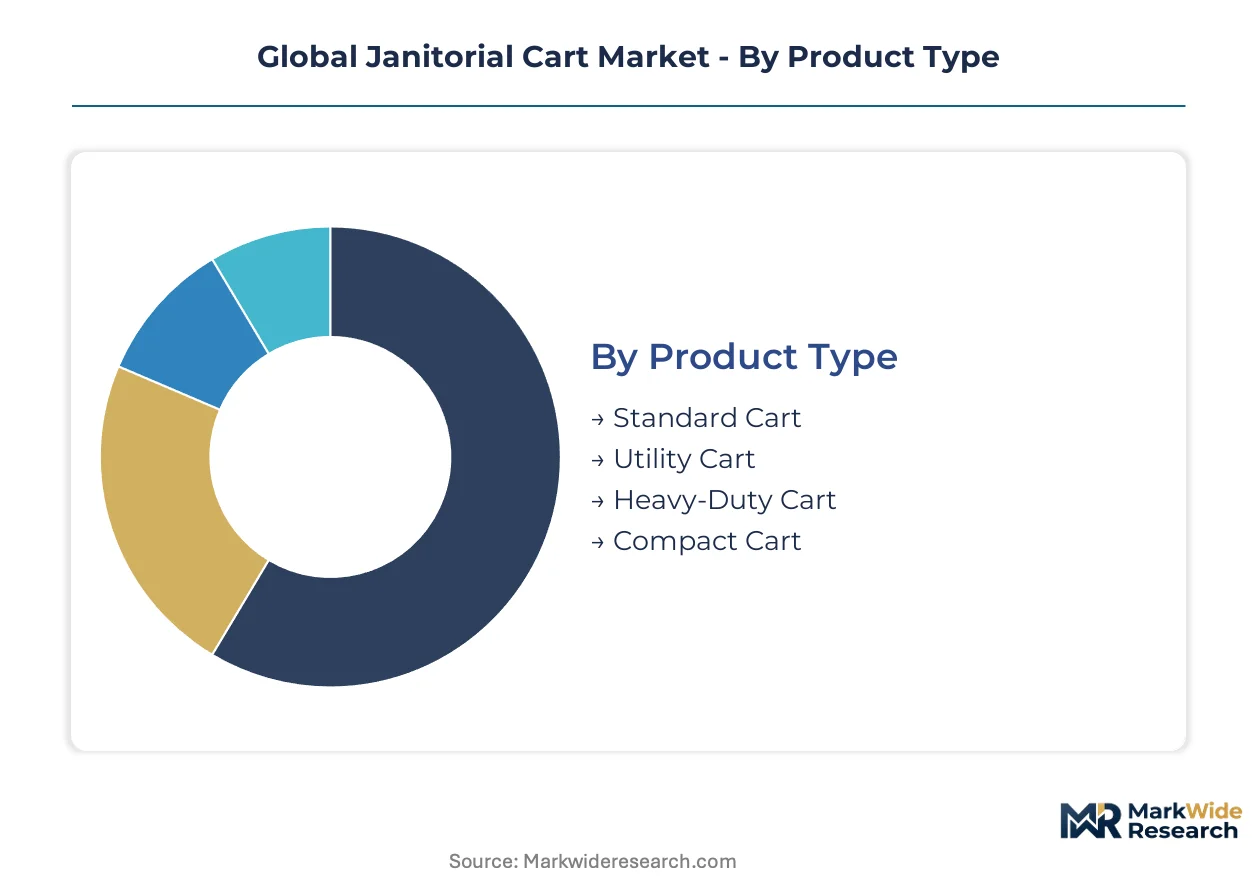
Cart configuration and material selection determine procurement priorities across facility types with distinct durability, mobility, and compliance requirements. Segmentation reveals how infection-control mandates and space constraints reshape demand patterns across product categories.
Product Type:
Integration depth varies sharply: heavy-duty and compact carts embed specialized functions for dedicated environments, while standard and utility carts serve standalone general-purpose deployment.
- Heavy-Duty Cart:Engineered with reinforced polymer or steel framing, load-rated casters, and sealed chemical containment systems. Demand concentrates in United States airports and German hospitals where Joint Commission and WHO sterilization protocols mandate extended service life under intensive use.
- Compact Cart:Configured with collapsible frames, reduced footprint dimensions, and elevator-compatible profiles. Singapore and South Korean commercial buildings prioritize these units where corridor width and storage volume impose strict spatial constraints on cleaning operations.
- Standard Cart:Baseline molded-shelf designs for routine commercial maintenance without specialized containment features.
- Utility Cart:Modular accessory-mount systems adaptable across multiple facility maintenance tasks beyond janitorial functions.
Heavy-duty configurations lead volumes today; compact variants are gaining share fastest.
Material:
Cost tier stratification separates premium corrosion-resistant grades from commodity formulations, with procurement committees weighing sterilization compatibility against capital expenditure limits.
- Plastic:Structural polymer formulations with embedded antimicrobial additives dominate unit economics. United States healthcare facilities accelerate replacement cycles for integrated-material carts that decentralize surface disinfection protocols from separate chemical application.
- Stainless Steel:304 and 316 grade fabrication for operating theater and sterile processing environments. German hospital procurement teams specify these units where steam sterilization compatibility governs material selection above cost considerations.
- Aluminum:Lightweight corrosion-resistant framing for mobility-critical applications without stainless-grade premium positioning.
- Wood:Limited niche deployment in aesthetic-sensitive hospitality settings where visual integration overrides functional specifications.
Plastic leads volumes today; stainless steel is climbing the fastest on infection-control premiumization.
End User:
Application environment dictates compartment sealing standards, with healthcare and education segments embedding regulatory compliance into procurement specifications.
- Healthcare:Sealed-compartment designs with secondary spill containment and drainage systems. California and Texas hospital systems prioritize EPA pre-certified configurations to accelerate vendor qualification timelines.
- Educational Institutions:Durable polymer construction with vandal-resistant hardware for high-traffic K-12 and university maintenance programs.
- Commercial Facilities:Standard utility configurations for corporate offices, retail, and hospitality where bundled service contracts consolidate vendor relationships.
- Residential Settings:Compact maneuverable units for multi-unit building maintenance with elevator and narrow-access compatibility.
Commercial facilities lead volumes today; healthcare is expanding most quickly on regulatory mandate intensity.
Capacity:
Volume scale aligns with facility square footage and staffing models, with extra-large units concentrated in centralized supply operations.
- Large:Multi-shelf configurations with integrated waste segregation and chemical storage for full-shift autonomous operation. United States airport authorities specify these units for terminal maintenance crews covering extensive linear footage.
- Extra Large:Maximum load-rated systems with reinforced chassis for centralized distribution hubs serving multiple floor zones.
- Medium:Balanced storage-to-mobility ratio for standard commercial building maintenance without specialized containment requirements.
- Small:Minimal-footprint units for spot cleaning and rapid response tasks in space-constrained environments.
Medium capacity leads volumes today; large configurations show steepest expansion trajectory on facility size growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facilities management workforces in the United States, Germany, and China anchor geographic demand concentration for janitorial cart procurement. Hospital maintenance crews in Texas and California drive specialized stainless-steel cart orders. German commercial cleaning cooperatives enforce REACH-compliant material specifications. Chinese airport authorities expand heavy-duty fleet deployments across new terminal construction.
United States
Healthcare maintenance crews and airport operations teams drive specialized cart procurement across Texas, California, and New York hospital systems. EPA chemical-storage standards tighten compartment-design specifications for commercial cleaning contractors serving federal buildings. Rubbermaid Commercial Products anchors North American manufacturing capacity through plastic-molded utility lines produced domestically.
Germany
Hospital sterilization technicians and commercial cleaning cooperatives mandate infection-control-grade cart specifications throughout Bavaria and North Rhine-Westphalia. ECHA REACH substance restrictions accelerate replacement cycles for polymer-additive formulations in European-manufactured fleets. Continental Commercial Products exemplifies specialized stainless-steel fabrication positioning for healthcare-grade operating theater environments.
China
Airport expansion projects and healthcare infrastructure modernization drive heavy-duty cart demand across Beijing, Shanghai, and Guangzhou maintenance operations. GB standards and MEE environmental regulations constrain polymer formulations for institutional procurement channels. Metalworking clusters in Zhejiang and Jiangsu provinces concentrate 304 and 316 stainless fabrication capacity for premium healthcare exports.
India
Government healthcare infrastructure spending and institutional modernization programs expand procurement channels in Maharashtra, Karnataka, and Tamil Nadu. BIS certification requirements add compliance layers for imported metal and plastic components entering hospital and airport maintenance divisions. Local manufacturing capacity in Pune and Chennai industrial corridors scales to meet domestic tender specifications.
Japan
Hospital infection-control committees and aged-care facility managers prioritize sealed-compartment designs meeting JIS standards and METI procurement guidelines. Compact cart configurations dominate Tokyo and Osaka commercial buildings where elevator dimensions and corridor width impose strict spatial constraints. Carlisle Food Service Products represents vertical integration positioning through polymer compounding for chemical-resistant cart bodies.
Global Janitorial Cart Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with cross-sector manufacturing capabilities. Mid-scale specialists occupy niche positions in stainless-steel healthcare fabrication and antimicrobial polymer compounding. Three archetypes dominate: North American mass-market molders, European precision metalworkers, and Asia-Pacific integrated material compounders. Geographic expansion through distribution partnerships and backward integration into polymer resin supply represent the dominant competitive moves.
Among North American manufacturers, Rubbermaid Commercial Products and Carlisle Food Service Products exemplify divergent strategic positioning. Rubbermaid Commercial Products anchors mass-market plastic-molded utility production with domestic manufacturing footprint advantages. Carlisle Food Service Products occupies specialty polymer compounding positioning for chemical-resistant and antimicrobial-embedded cart bodies. Continental Commercial Products represents European precision metalworking specialization in healthcare-grade stainless fabrication.
| Leading Market Players |
|---|
| Rubbermaid Commercial Products |
| Forbes Industries Inc. |
| Fitch Co. |
| Arcat, Inc. |
| Dura Wax Company |
| Carlisle Food Service Products |
| Continental Commercial Products |
| Architectural Brass |
| Geerpres Inc. |
| Others |
Value Chain & Pricing Dynamics
Polymer resin feedstock costs cascade through three distinct pricing tiers as structural polymer formulations travel from Chinese and Indian compounding facilities to healthcare procurement committees in Germany and the United States. Raw material volatility at the upstream tier compresses margins on plastic-molded utility lines while stainless-steel fabrication commands premium positioning downstream.
Pricing Analysis
Bundled service contracts covering equipment, consumables, and preventive maintenance now dominate pricing structures across United Kingdom and Australian facilities management markets. Three-tier pricing structure across premium, standard, and economy levels separates EPA pre-certified stainless-steel healthcare configurations from commodity plastic-molded commercial units. Pricing pressure stems from polymer resin cost volatility tied to crude oil benchmarks, with hospitality and corporate office segments showing highest price sensitivity while German hospital infection-control committees prioritize sterilization compatibility above capital expenditure limits.
Supply Chain Analysis
Dual-sourcing requirements from United States airport authorities and German hospital systems mandate multi-supplier qualification for 304 and 316 grade stainless fabrication, dispersing procurement across Chinese and Indian metalworking clusters. Raw material dependencies center on structural polymer resins, antimicrobial additive compounds, and corrosion-resistant steel grades. Single-source vulnerability concentrates in Zhejiang and Jiangsu province stainless capacity. Distribution runs through national facilities management service providers consolidating vendor relationships in outsourced maintenance markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through antimicrobial polymer premiumization and IoT-enabled service bundling that shifts revenue from transactional equipment sales to recurring software-adjacent contracts.
For Market Incumbents: Cement defensible positioning through backward integration into polymer compounding and captive stainless-steel fabrication capacity in India and China. Acquire BIS certification capabilities ahead of Indian healthcare infrastructure tenders. Lock in multi-year service contracts with United States airport authorities to forestall direct manufacturer engagement by national facilities management consolidators. For New Entrants and Emerging Players: REACH compliance deadlines in Europe open a window for specialized stainless-steel fabrication targeting replacement cycles in German and French hospital systems. Penetrate the compact cart segment in Singapore and South Korean urban commercial buildings where elevator-compatible configurations face supply gaps. Lead with RFID-enabled inventory tracking as a differentiated service layer rather than equipment-only positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale antimicrobial polymer compounders because healthcare procurement committees are decentralizing buying authority to infection-control specialists with distinct material specifications. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor ECHA substance restriction announcements as the critical signal for replacement cycle timing and portfolio revaluation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Carlisle Food Service Products exemplifies margin capture through captive antimicrobial additive formulation. |
| Healthcare-Grade Certification Investment | EPA pre-certification accelerates vendor qualification for California and Texas hospital procurement teams. |
| IoT-Enabled Service Contract Bundling | RFID tagging convergence allows facilities managers to monitor supply levels remotely across distributed building portfolios. |
| Geographic Manufacturing Footprint Expansion | Rubbermaid Commercial Products sustains cost advantages through North American plastic-molding capacity. |
| Regulatory Compliance Infrastructure Buildout | REACH, EPA, and BIS multi-jurisdiction engineering capabilities extend qualification cycle barriers against emerging competitors. |
Study Parameters
Bottom-up healthcare and commercial facilities modeling reconciled against top-down polymer resin and stainless-steel supply tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, facilities management directors, janitorial equipment distributors, and infection-control committee members combined with secondary validation from EPA chemical-storage guidance documents, ECHA REACH substance restriction databases, BIS certification registries, and customs trade data on polymer and steel imports. Triangulation across these sources calibrated volume estimates against actual procurement patterns.
Input-output matrices mapped cart configuration demand against material supply availability across the projection horizon. Segmentation dimensions modeled include product type, material formulation, end-user industry, and geographic regulatory cluster. CAGRs derived from facility modernization spending trajectories, replacement cycle acceleration from compliance deadlines, and penetration curves for connected asset-tracking technologies. Forecast inputs incorporated hospital infection-control mandate intensity and urban building densification rates in space-constrained metropolitan markets.
Revisions become necessary when REACH substance restriction timelines shift, EPA chemical-storage standards tighten beyond current compartment-design specifications, or polymer resin cost volatility disrupts tiered pricing structures. Deviation in Indian BIS certification enforcement or Chinese stainless-steel export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Global All Purpose Cleanser Market