
 Canister Vacuum Cleaners Market | 2026-2036
Canister Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Canister Vacuum Cleaners Market Insights
A capital-intensity divergence between premium engineering houses and volume-oriented assemblers is rotating competitive dynamics in the canister vacuum sector. Miele sustains its position through captive motor manufacturing and German-based component fabrication. SharkNinja competes on agile supply chains and rapid product-cycle turnover across North American retail channels. Electrolux anchors its portfolio through European service networks and institutional maintenance contracts.
Canister vacuum cleaners are wheeled, hose-connected cleaning appliances housing the motor and dust-collection unit in a separate rolling body, typically operating at 1,200–2,200 watts with suction control via variable airflow regulation; they serve residential deep-cleaning, commercial facility maintenance, and industrial debris recovery where maneuverability exceeds upright formats. Corded configurations still dominate margin pools in commercial and industrial usage types, though cordless battery variants are gaining fastest in residential settings where storage constraints and stair-accessibility matter. HEPA filtration features command premium positioning in allergy-sensitive segments, while bagless designs compete on total cost of ownership across price-sensitive channels.
The EU Ecodesign Regulation and Energy Labeling Directive constrain motor-wattage claims and mandate transparency on suction performance, forcing redesigns toward airflow-optimized impellers rather than raw power ratings. The US EPA and FDA frameworks indirectly shape demand through indoor air-quality advisories that elevate HEPA specification requirements in healthcare and institutional procurement. Stakeholders must monitor how battery-chemistry regulations from China's MIIT and the EU's Battery Directive reshape cordless product viability against corded baseline economics.
Market Dynamics
Motor-efficiency mandates from the EU Ecodesign Regulation are compressing wattage ceilings while forcing redesigns toward airflow-optimized impellers, fundamentally altering how manufacturers compete on performance claims.
Growth Catalysts
- HEPA-grade filtration mandates:Indoor air-quality advisories from the US EPA elevate specification requirements in healthcare procurement, expanding addressable market for certified units.
- Battery-chemistry advances:Lithium-ion cell density improvements enable cordless variants to challenge corded suction performance in residential stair-accessibility applications.
- Multi-surface versatility:German engineering clusters near Miele's Gütersloh facility concentrate R&D talent for brush-roll and suction-control integration.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings from Chinese export quotas squeeze motor-manufacturing margins for premium and mid-tier producers alike.
- Energy-labeling compliance friction:The EU Energy Labeling Directive's suction-performance transparency rules invalidate legacy marketing based on raw wattage claims.
- Robotic vacuum substitution:Autonomous cleaning platforms capture maintenance-cleaning occasions that previously sustained canister replacement cycles.
Strategic Opportunities
- Institutional maintenance contracts:Electrolux's European service-network density creates defensive positioning in commercial facility-management procurement.
- India residential penetration:Rising hard-surface flooring installation rates in urban centers expand addressable base beyond traditional carpet-dominant markets.
- IoT-enabled predictive maintenance:Sensor-integrated motors and filter-life monitoring enable subscription revenue streams alongside hardware sales.
Industry Challenges
- Aerodynamics simulation talent scarcity:Computational fluid dynamics expertise for impeller redesign commands premium compensation in German and Austrian engineering labor markets.
- Dual certification timelines:Concurrent CE marking and US EPA verification processes extend product-launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canister Vacuum Cleaners Market |
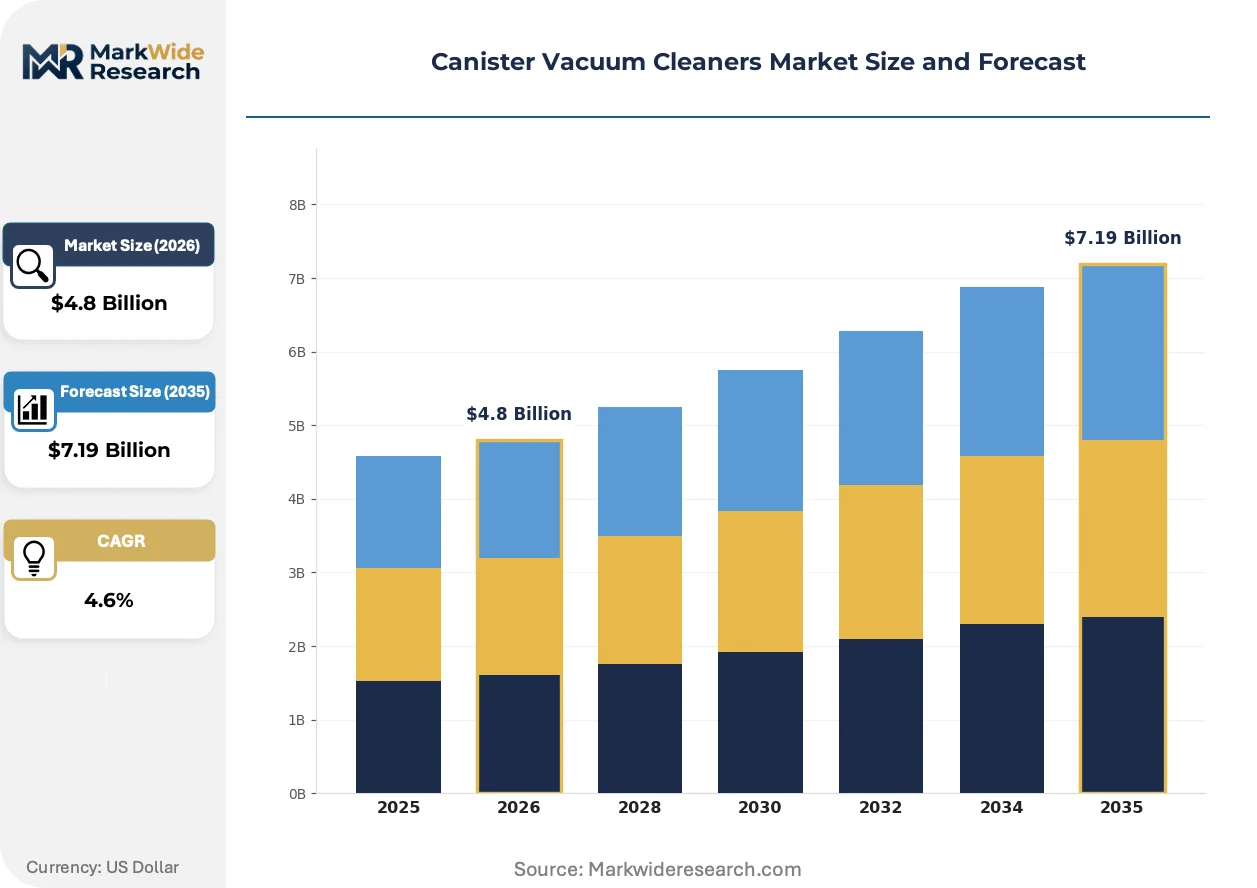
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Stick Power Source: Corded, Cordless, Battery, Hybrid Usage Type: Residential, Commercial, Industrial, Institutional Feature: HEPA Filters, Bagless, Noise Reduction, Multi-surface |
| Companies Covered | Miele, Dyson, SharkNinja, Samsung Electronics, Electrolux, Philips, Panasonic, Alfred Karcher SE & Co., Nilfisk Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canister Vacuum Cleaners Market Trends and Innovations
Cordless powertrains, intelligent suction modulation, and filtration-certification layering are actively reconfiguring how manufacturers differentiate and how buyers evaluate total cost of ownership.
Brushless DC motor architectures are fragmenting the traditional universal-motor supply base by enabling variable-speed control without mechanical airflow regulators. Residential buyers in Germany and France adopt these configurations fastest where energy-label scrutiny is highest. The technology is fragmenting margin pools away from high-wattage motor specialists toward electronics-integrated system designers.
REACH substance restrictions on persistent organic pollutants in plastics and rubber components force housing-material substitutions across EU-bound production lines. Compounders in Bavaria and Baden-Württemberg reformulate ABS and TPE grades to maintain impact resistance while eliminating restricted flame retardants. Corded canister lines serving institutional buyers face compressed redesign timelines to maintain market access.
After-sales service unbundling from product purchase is compressing traditional dealer-margin structures in North American retail channels. Big-box retailers in the US now push extended-warranty attachments and direct-to-consumer filter-subscription programs that bypass regional service networks. This pattern concentrates in suburban markets where buyer density supports logistics-scale economics for consumable replenishment.
Canister Vacuum Cleaners Market Segmentation
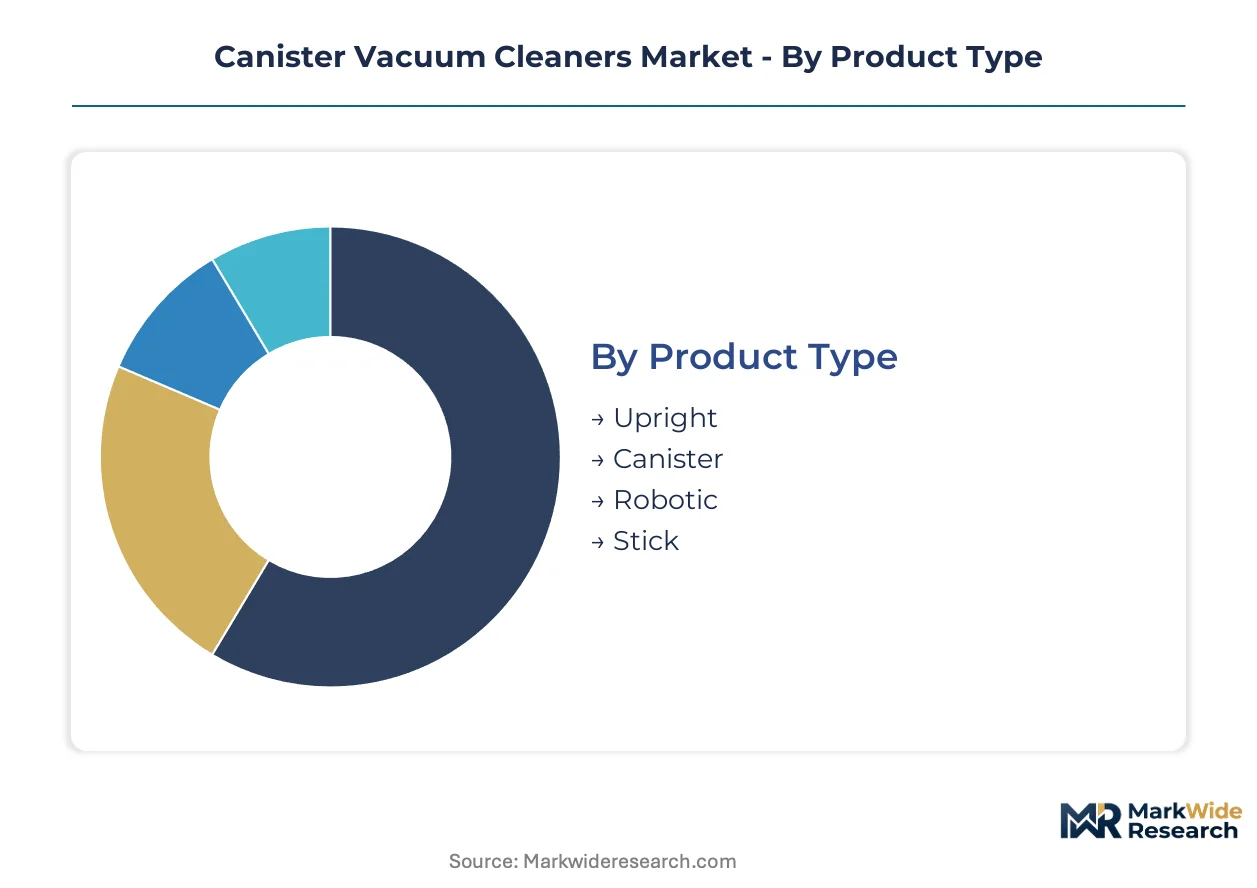
Segmentation in canister vacuum cleaners determines channel placement, margin structure, and compliance burden. Product type and power source dictate retail versus commercial distribution, while usage type and feature sets shape certification requirements and service-network density.
Product Type:
Channel mix varies sharply by form factor, with canister units commanding premium placement in specialty appliance retail while robotic variants displace through e-commerce direct-to-consumer routes.
- Upright:Motor and suction head integrate in a single vertical unit, typically favored in North American carpet-dominant households. Demand concentrates in suburban US markets where storage space accommodates larger footprints, constrained by stair-accessibility limitations in multi-level dwellings.
- Canister:Wheeled body houses motor and dust collection separately from the cleaning hose, enabling maneuverability across surfaces. German engineering clusters near Gütersloh concentrate production for EU energy-label compliance, with suction-control integration driving premium positioning.
- Robotic:Autonomous navigation platforms for maintenance cleaning without human operation. Chinese manufacturing bases in Shenzhen and Dongguan dominate component assembly.
- Stick:Lightweight cordless configurations with integrated handheld conversion. Battery-chemistry advances from South Korean cell suppliers enable runtime extension.
Canister designs dominate installed base in European markets. Robotic configurations are where expansion concentrates.
Power Source:
Cost tier stratification runs from corded baseline economics through lithium-ion premium positioning, with hybrid configurations targeting institutional procurement flexibility.
- Corded:Continuous AC power delivery sustains maximum suction without runtime degradation. Commercial facility managers in Germany and France specify these for duty-cycle reliability, though EU Ecodesign wattage ceilings compress motor-efficiency claims.
- Cordless:Battery-powered mobility eliminates cord-management constraints in stair-accessible residential applications. Urban apartments in Paris and Milan drive fastest adoption where storage space is minimal.
- Battery:Removable cell packs enable field replacement and extended operational continuity. Healthcare procurement in US hospital systems favors swappable configurations.
- Hybrid:Dual-mode operation switching between corded and battery power. Institutional maintenance contracts in Nordic countries specify these for backup-power redundancy.
Corded units anchor commercial installed base. Cordless configurations gain share fastest in residential channels.
Usage Type:
Customer type determines service-network requirements, with institutional buyers demanding preventive maintenance contracts that residential channels rarely support.
- Residential:Individual household procurement for domestic cleaning tasks. HEPA filtration specifications from US EPA indoor air-quality advisories elevate certification requirements in allergy-sensitive segments.
- Commercial:Office, retail, and hospitality facility maintenance. Electrolux service-network density in European capitals creates defensive positioning.
- Industrial:Debris recovery in manufacturing and warehouse environments. Debris-type specialization drives suction-system customization.
- Institutional:Healthcare, education, and government procurement with formal tender processes. Dual CE marking and EPA verification timelines extend product-launch windows.
Residential usage dominates unit volume. Institutional contracts represent the steepest expansion trajectory for service-integrated suppliers.
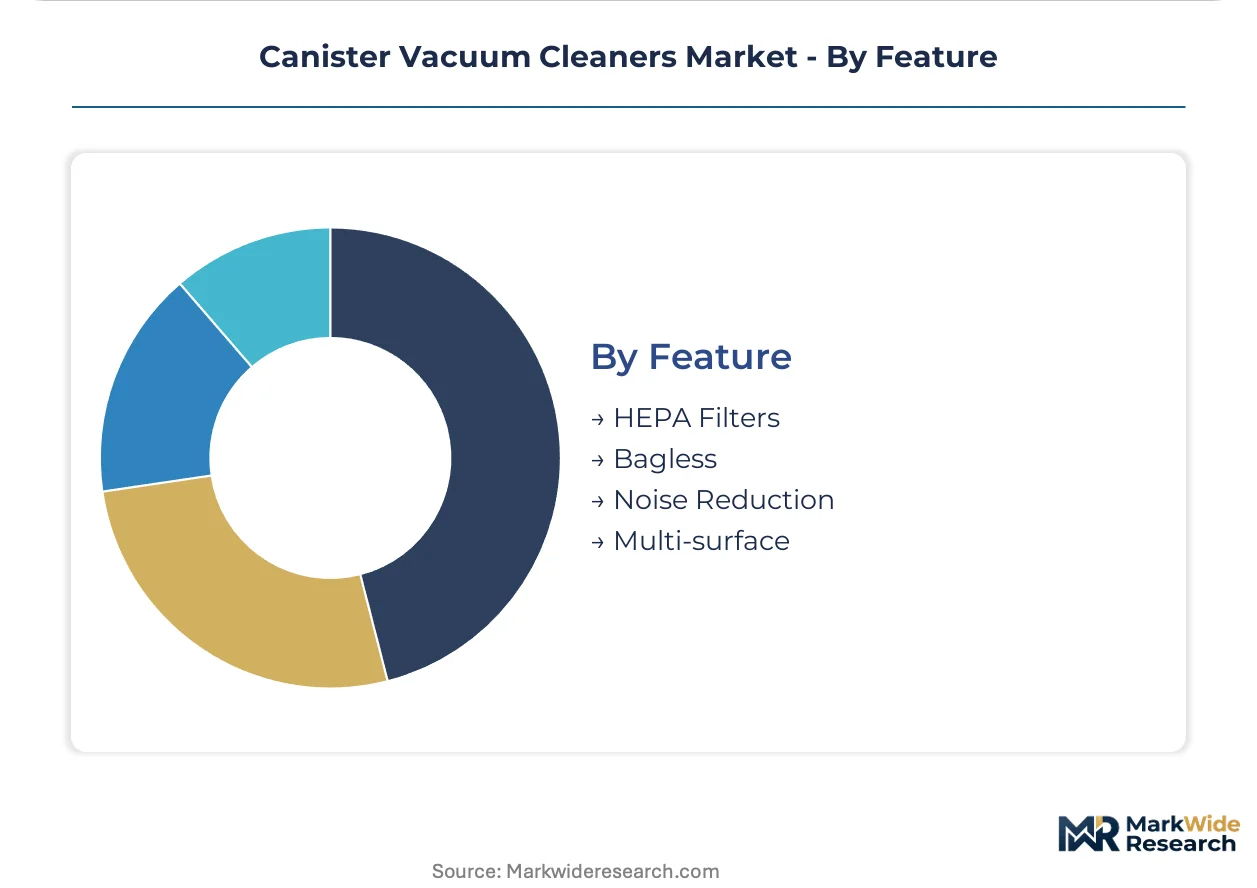
Feature:
Margin differentiation concentrates in certification layering, with HEPA-grade filtration commanding procurement specification while bagless designs compete on total cost of ownership.
- HEPA Filters:High-efficiency particulate air certification captures 99.97% of particles at 0.3 microns. US healthcare procurement mandates elevate specification requirements.
- Bagless:Cyclonic separation eliminates consumable bag replacement. Price-sensitive channels in US big-box retail favor these for ownership-cost transparency.
- Noise Reduction:Acoustic dampening for operation below 70 decibels. German residential buyers prioritize these for apartment-dwelling courtesy norms.
- Multi-surface:Automated or manual brush-roll adjustment across carpet, hard flooring, and upholstery. Indian urban centers with rising hard-surface installation drive specification.
HEPA filtration dominates premium positioning. Multi-surface versatility is where feature-based expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with Indian and Southeast Asian buyers driving hard bargains on total cost of ownership while German and Japanese consumers absorb premiums for engineering credentials and filtration certification.
Germany
Engineering-intensive procurement patterns sustain demand for high-efficiency motors and HEPA-grade filtration systems in residential and institutional channels. The EU Ecodesign Regulation and Energy Labeling Directive enforce strict motor-wattage ceilings and suction-performance transparency requirements. Manufacturing clusters in Gütersloh and surrounding North Rhine-Westphalia concentrate captive motor production and component fabrication for premium-tier supply.
United States
Big-box retail dominance and extended-warranty attachments compress traditional dealer margins while elevating bagless cyclonic designs in price-sensitive suburban markets. EPA indoor air-quality advisories indirectly shape healthcare and institutional procurement specifications for certified filtration. Distribution and service-network density concentrates in Midwest logistics hubs and Southeast population corridors.
China
Rising urban middle-class penetration and hard-surface flooring installation rates expand the addressable base beyond traditional carpet-cleaning applications. MIIT battery-chemistry regulations and the dual carbon goals reshape cordless product development timelines and cell-supplier qualification. Manufacturing concentration in Shenzhen and Dongguan dominates component assembly for robotic and stick-format variants.
India
Urban residential construction and hard-surface flooring adoption in Mumbai, Delhi-NCR, and Bangalore create new demand pockets outside carpet-dominant historical patterns. BIS energy-efficiency labeling and import tariff structures influence landed cost economics for foreign manufacturers. Local assembly partnerships and regional distribution networks concentrate in Maharashtra and Gujarat industrial corridors.
Japan
Compact dwelling norms and acoustic-sensitivity standards elevate noise-reduction specifications and storage-optimized form factors in metropolitan Tokyo and Osaka markets. METI energy-efficiency guidelines and JIS standards constrain motor-performance claims and mandate transparent labeling. Precision engineering supply chains in Aichi Prefecture and Kansai region support brushless DC motor and sensor-integration development.
Canister Vacuum Cleaners Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with engineering-intensive German houses competing against agile Asian supply chains and North American retail-optimized assemblers. The market structure tiered across premium captive-manufacturing specialists, volume-scale OEMs, and diversified appliance conglomerates. Three archetypes dominate: vertically integrated motor manufacturers with in-house component fabrication; retail-channel assemblers leveraging outsourced production and rapid product-cycle turnover; and diversified industrial-cleaning specialists with institutional service-network density. Competitive moves concentrate on portfolio diversification into cordless powertrains and geographic expansion through regional distribution partnerships.
Within the premium engineering tier, Miele GmbH and Alfred Karcher SE & Co. exemplify captive-manufacturing archetypes with German-based production footprints. SharkNinja Operating LLC occupies a position on the agile retail-optimization vector. Among diversified industrial specialists, Nilfisk Group represents service-network-anchored institutional positioning.
| Leading Market Players |
|---|
| Miele |
| Dyson |
| SharkNinja |
| Samsung Electronics |
| Electrolux |
| Philips |
| Panasonic |
| Alfred Karcher SE & Co. |
| Nilfisk Group |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor substitution for universal-motor architectures is redrawing component sourcing maps from Bavarian engineering clusters toward East Asian electronics manufacturing centers, simultaneously compressing legacy motor-supplier pricing power while elevating power-electronics specialists.
Pricing Analysis
Consumable replenishment and extended-warranty tiers now drive lifetime value extraction beyond initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by HEPA certification grade and German-engineering provenance. Price differentiation stems from captive motor manufacturing versus outsourced assembly economics. Pricing pressure intensifies in mid-tier segments as battery-chemistry cost curves flatten runtime advantages. Residential buyers in US big-box channels exhibit highest price sensitivity; German institutional procurement shows lowest sensitivity due to total-cost-of-ownership frameworks.
Supply Chain Analysis
Rare-earth magnet processing chokepoints in Chinese export-licensing regimes tether motor-manufacturing economics to geopolitical clearance timelines. Component concentration spans Germany for precision-motor fabrication, China for lithium-ion cell supply, and South Korea for power-electronics semiconductors. Raw material dependencies include neodymium-iron-boron magnets, ABS housing compounds, and HEPA filter media. Single-source vulnerability concentrates in rare-earth magnet refining. Distribution runs through European specialist retailers, North American big-box chains, and Asian e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment: EU Ecodesign and Energy Labeling Directive compliance creates multi-year certification barriers that favor incumbents with established testing relationships.
For Market Incumbents: Fortify captive motor-production positions through in-house impeller-design capability accumulation, defending against brushless DC substitution threats from Asian electronics integrators. Deepen service-network density in German and French commercial corridors to lock in institutional maintenance contracts. Prioritize REACH-compliant material reformulation ahead of substance-restriction deadlines.
For New Entrants and Emerging Players: Anchor in Indian urban residential segments where hard-surface flooring adoption outpaces established carpet-cleaning incumbents. Target cordless stick-format white space in Japanese compact-dwelling markets where noise-reduction specifications remain underserved. Pursue direct-to-consumer filter-subscription models bypassing traditional retail margin structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European engineering houses holding dormant brand equity and regional distribution networks. Long-term viability hinges on cordless technology transition completion and IoT-enabled predictive maintenance revenue maturation. Monitor MIIT battery-chemistry regulation amendments as inflection signal for cordless product economics viability against corded baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Cordless Powertrain Migration | Brushless DC architectures from South Korean suppliers enable stair-accessibility positioning in European urban markets. |
| HEPA Certification Layering | US EPA indoor air-quality advisories elevate healthcare procurement specifications for premium-tier filtration. |
| IoT Predictive Maintenance Launch | Sensor-integrated motors from Aichi Prefecture engineering clusters unlock subscription revenue streams. |
| Regional Distribution Partnership | Maharashtra and Gujarat industrial corridors in India concentrate local assembly for hard-surface flooring demand. |
| REACH Compliance Repositioning | Bavarian compounders reformulate ABS grades to maintain EU market access under substance restrictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product development directors at German engineering houses, procurement leads at US big-box retailers, aftermarket service heads in European facility management, and battery-supply specialists in South Korean cell manufacturing. Secondary validation drew from EU Ecodesign regulatory filings, EPA indoor air-quality advisories, MIIT battery-chemistry directives, customs trade data for vacuum cleaner component flows, and SEC disclosures from listed appliance manufacturers. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by product type, power source architecture, usage category, and filtration certification tier. CAGRs were derived from installed-base replacement cycles, cordless adoption curves, and regional regulatory phase-in schedules. Industry-specific inputs included rare-earth magnet price volatility indices and EU energy-label compliance cost estimates for motor redesigns.
Material uncertainties — rare-earth export quota disruptions, battery-chemistry regulation amendments, robotic vacuum substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and consumer cordless-preference elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Household Wipes Market