
 Laundry Scent Booster Market | 2026-2036
Laundry Scent Booster Market Size, Share, and Industry Trends Forecast 2026-2036
Laundry Scent Booster Market Analytics
North American fragrance encapsulation capacity is hardening as regional producers expand microencapsulation lines for sustained-release applications. Procter & Gamble Company leverages captive polymer research to anchor premium pod formulations across mass retail channels. Henkel Corporation competes through concentrated liquid technologies that reduce packaging intensity. Church & Dwight Co., Inc. specializes in crystal-based formats that occupy the value-tier shelf position.
Laundry scent boosters comprise fragranced additives—typically composed of perfume microcapsules, carrier salts, and dispersal agents—designed to deposit lasting aroma onto fabrics during wash and dry cycles. The primary commercial purpose centers on extending fragrance longevity beyond conventional detergent performance, particularly in cold-water washing environments. Pods and crystals command disproportionate attention in margin pools, with single-dose pod formats sustaining premium pricing while crystal variants penetrate bulk commercial procurement. Liquid formats remain mature in household channels where pour-control preferences persist.
The U.S. EPA regulates fragrance ingredient disclosure under the Toxic Substances Control Act, while the California Air Resources Board enforces volatile organic compound limits that directly constrain formulation chemistry. The EU REACH framework and ECHA classification requirements govern export-bound production, forcing dual-compliance architectures for multinational suppliers. Stakeholders must monitor evolving state-level right-to-know legislation and fragrance allergen labeling thresholds that threaten to fragment permissible ingredient palettes across jurisdictions.
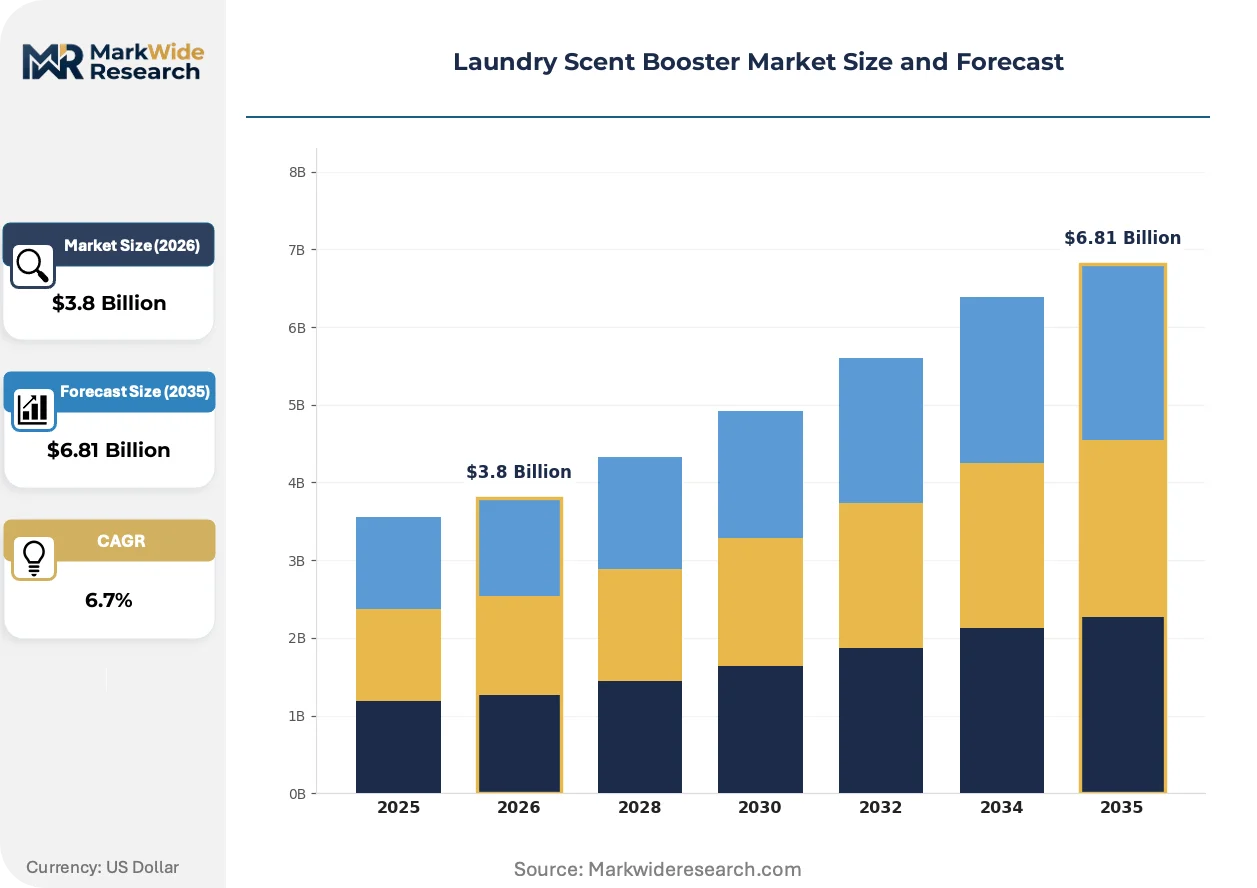
Market Dynamics
Concentrated pod formats are compressing margins across legacy liquid and crystal segments as hospitality procurement shifts toward single-dose systems. The EPA Safer Choice program and California's chemical disclosure mandates are forcing simultaneous reformulation across multiple active chemistry platforms.
Growth Catalysts
- Cold-water washing penetration:Energy-conscious households and commercial laundries in Sun Belt metropolitan areas are accelerating adoption of scent boosters optimized for sub-60°F cycles. This expands addressable use cases beyond traditional hot-wash detergents.
- California Air Resources Board VOC limits:Stricter volatile organic compound ceilings are compelling manufacturers to develop low-emission encapsulation technologies. These regulations inadvertently create competitive moats for compliant producers.
- Microencapsulation R&D:Advances in sustained-release polymer shells are extending fragrance longevity from wash through wear. This technical leap justifies premium positioning in both household and commercial channels.
Market Restraints
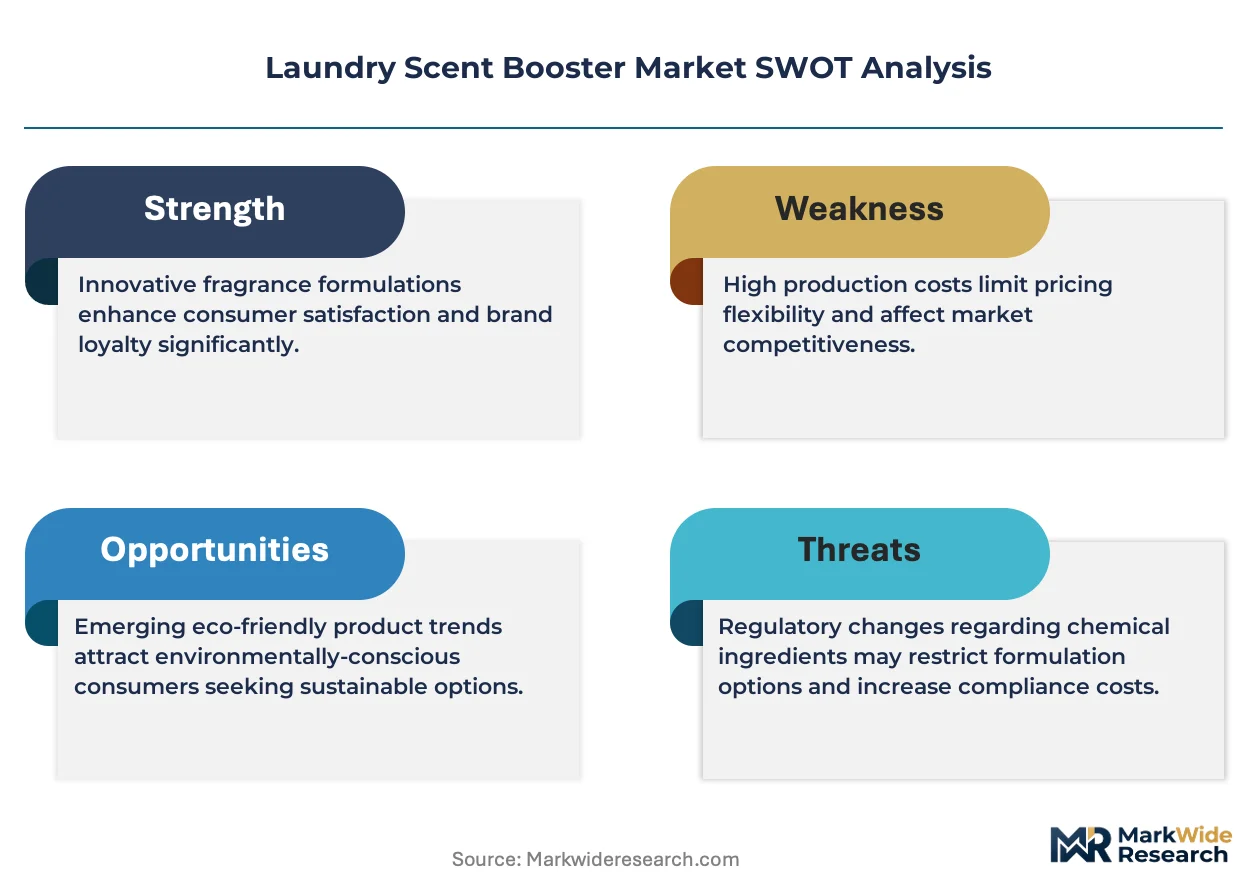
- Fragrance ingredient cost volatility:Natural and synthetic aroma chemical supplies face petrochemical feedstock price swings. This compresses formulation margins unpredictably across quarterly procurement cycles.
- North American encapsulation capacity concentration:Regional microencapsulation line expansion lags demand growth, creating bottlenecks for new market entrants without captive polymer research capabilities.
- EU REACH dual-compliance burden:Export-bound production must satisfy both U.S. EPA and ECHA classification requirements. This fragments permissible ingredient palettes and raises regulatory compliance costs.
Strategic Opportunities
- Underpenetrated multi-family housing segments:Shared laundry facilities in dense urban clusters represent untapped volume for bulk-format scent boosters. Property management procurement channels remain underserved by current retail-centric distribution.
- Subscription commerce integration:Direct-to-consumer replenishment models are bypassing traditional mass retail shelf competition. This channel innovation captures recurring revenue with lower customer acquisition costs.
- Biodegradable carrier salt development:Convergence of enzymatic dispersal agents with plant-derived salts addresses sustainability preferences. Early movers capture green-certification premiums in environmentally conscious segments.
Industry Challenges
- Fragrance chemist talent scarcity:Specialized expertise in microencapsulation formulation and regulatory toxicology commands premium compensation. This constrains R&D velocity for mid-tier manufacturers.
- State-level right-to-know fragmentation:Evolving chemical disclosure thresholds across multiple jurisdictions create compliance timeline uncertainty. Product registration and reformulation cycles compress profitability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laundry Scent Booster Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Pods, Crystals Packaging Type: Box, Bottle, Pouch, Canister Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores End User: Households, Commercial Laundries, Hospitality, Institutions |
| Companies Covered | Reckitt Benckiser, Venus Laboratories, Procter & Gamble Company, Clorox, Recochem, Henkel Corporation, S. C. Johnson & Son, Inc., Unilever, Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laundry Scent Booster Market Evolving Landscape
Active chemistry platforms are diverging as cold-water efficacy requirements clash with volatile organic compound constraints. This tension is accelerating investment in next-generation encapsulation and carrier systems.
Biodegradable polymeric microcapsules are electrifying fragrance delivery architectures. Hospitality laundries in Phoenix, Miami, and Las Vegas are adopting these systems at pace to meet sustainability procurement mandates. The technology is electrifying competitive positioning by enabling premium pricing for certified biodegradable formats while compressing conventional petrochemical-based alternatives.
California's Proposition 65 fragrance allergen labeling thresholds are tightening disclosure requirements for scented consumer products. Manufacturers must now reformulate or relabel to avoid warning label obligations. Pod and crystal formats face the most acute compliance pressure given their concentrated chemistry profiles.
Commercial procurement consolidation is reshaping channel economics. Large hospitality chains are centralizing detergent and additive purchasing through approved vendor programs. This compresses distributor margins and favors suppliers with direct national account capabilities, particularly visible in Sun Belt markets with high hotel density.
Laundry Scent Booster Market Segmentation
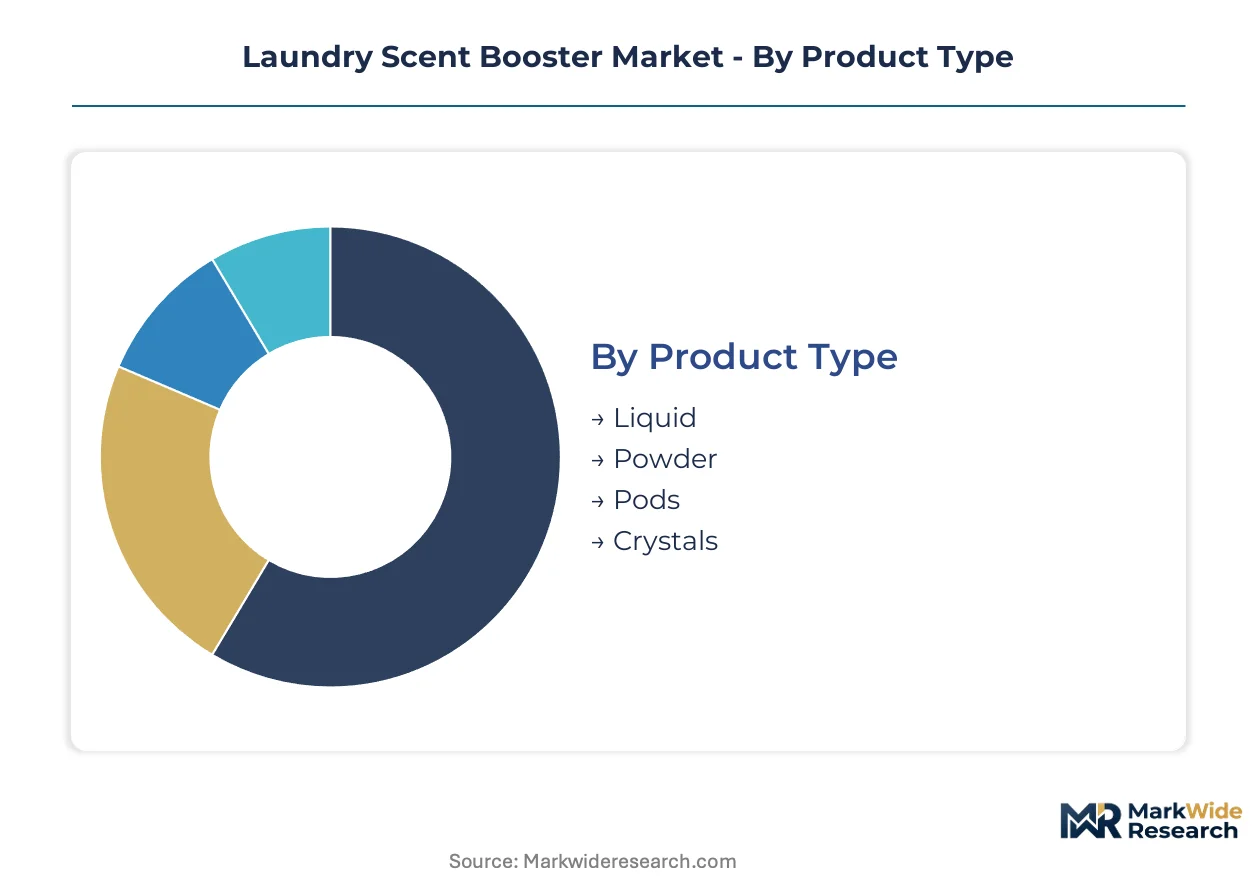
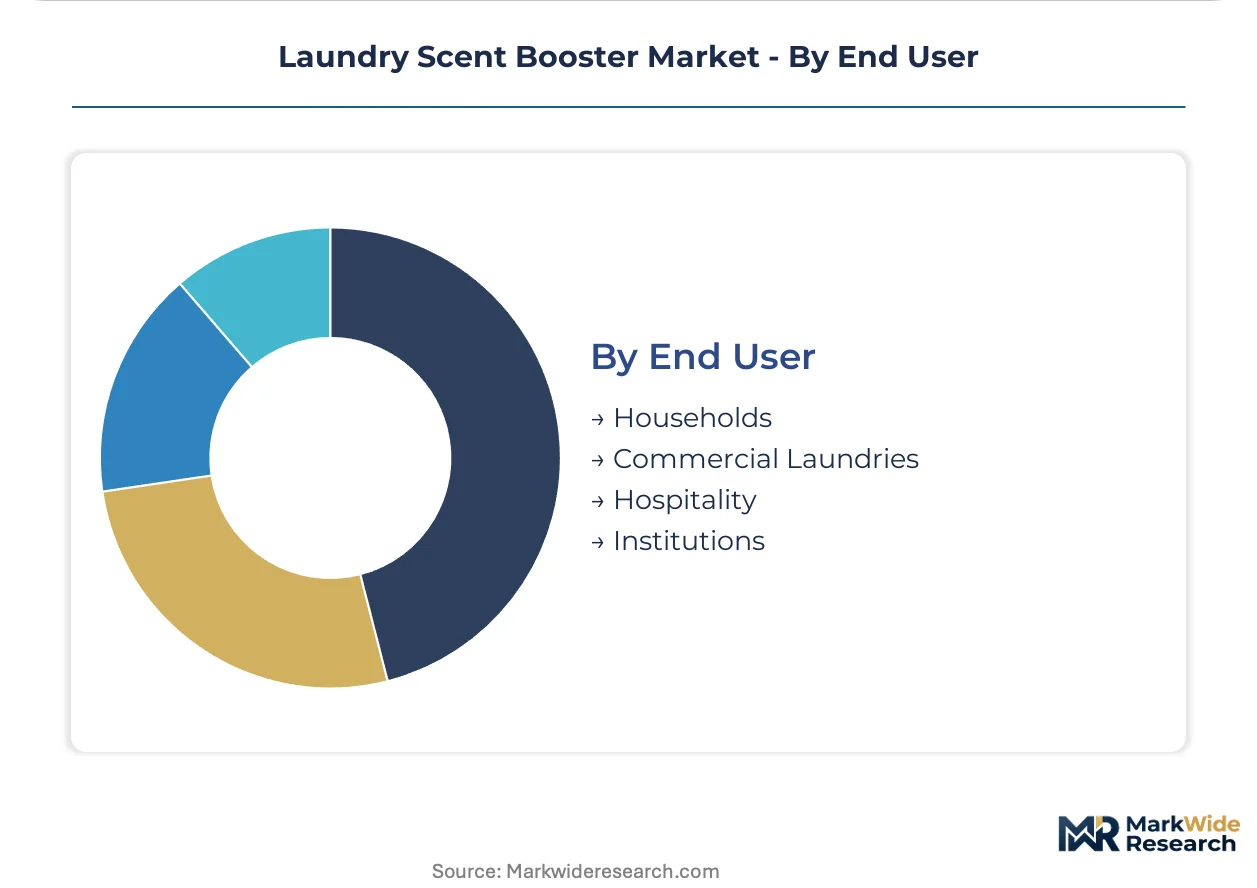
Scent booster manufacturers calibrate formulation chemistry and packaging formats against distinct usage occasions across consumer and commercial laundries. Segmentation discipline separates premium single-dose systems from bulk procurement channels, each demanding incompatible supply chain architectures and margin structures.
Product Type:
Upgrade cycles accelerate as cold-water washing penetration and hospitality automation reshape format preferences away from legacy liquids.
- Pods:Water-soluble film encases concentrated fragrance microcapsules and dispersal polymers in pre-measured single doses. Hospitality procurement in Phoenix, Miami, and Las Vegas favors pod automation compatibility, though California's Proposition 65 allergen thresholds force reformulation of concentrated chemistry profiles.
- Crystals:Solid carrier salts infused with perfume oils deliver extended-release aroma through gradual dissolution in wash cycles. Commercial laundries in Sun Belt metropolitan areas specify crystal formats for bulk dispensers, with biodegradable salt variants capturing sustainability premiums.
- Liquid:Pour-controlled viscosity formulations remain entrenched in household channels where dosing flexibility outweighs convenience premiums.
- Powder:Dry-blended fragrance carriers occupy value-tier positioning, particularly in institutional procurement with cost-constrained specifications.
Pods sit at the top of the volume ranking, with crystals climbing the fastest.
Packaging Type:
Packaging intensity directly determines freight economics and retail shelf space productivity across divergent channel strategies.
- Pouch:Flexible film structures minimize material weight and cube utilization for e-commerce fulfillment. Direct-to-consumer subscription models in dense urban clusters favor pouch formats for mailbox compatibility and reduced shipping cost.
- Canister:Rigid containers with moisture-resistant seals protect crystal integrity in high-humidity commercial laundry environments. Hospitality procurement mandates often specify canister formats with tamper-evident closures for housekeeping inventory control.
- Box:Corrugated retail packaging supports palletization efficiency for mass merchant replenishment cycles.
- Bottle:HDPE containers with precision pour spouts address liquid format household preferences for dosing control.
Canisters dominate commercial volume, with pouches expanding most quickly in subscription channels.
Distribution Channel:
Channel selection locks in margin structure and customer acquisition cost profiles that resist migration once established.
- Online Retail:Direct-to-consumer platforms bypass mass retail slotting fees and enable replenishment automation. Subscription integration captures recurring revenue with lower churn than transactional grocery purchases.
- Supermarkets:Mass merchant shelf space commands trade promotion spending and category management compliance. Pod and crystal formats compete for limited linear footage through velocity guarantees and promotional calendar commitments.
- Specialty Stores:Premium positioning in home goods channels supports fragrance-forward branding and experiential merchandising.
- Convenience Stores:Emergency replenishment occasions capture impulse purchases with single-use and travel-size formats.
Supermarkets anchor current volume leadership, with online retail gaining share fastest through subscription conversion.
End User:
End-use concentration determines formulation specifications, with hospitality and multi-family housing creating distinct demand profiles from single-family households.
- Hospitality:Hotel chains centralize procurement through approved vendor programs with sustainability certification requirements. Biodegradable microencapsulation formats command premium positioning as chains in Phoenix, Miami, and Las Vegas adopt green procurement mandates.
- Commercial Laundries:Industrial-scale operations specify concentrated formats compatible with automated dosing systems and high-throughput tunnel washers.
- Households:Single-family residences drive pod adoption through convenience positioning, while multi-family shared laundry facilities remain underpenetrated for bulk crystal formats.
- Institutions:Healthcare and educational facilities operate under strict chemical disclosure protocols that constrain permissible fragrance palettes.
Hospitality leads commercial volume, with commercial laundries expanding most quickly through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward jurisdictions with narrower chemical disclosure mandates and lower compliance cost burdens. The United States retains formulation leadership despite California's Proposition 65 allergen thresholds, while European REACH obligations compress export margins. Asia-Pacific capacity expansion concentrates in contract manufacturing zones with streamlined environmental permitting.
United States
Hospitality procurement in Phoenix, Miami, and Las Vegas drives concentrated demand for biodegradable microencapsulation formats. The EPA Safer Choice program and California Air Resources Board VOC limits impose dual-layer compliance costs on domestic producers. Sun Belt metropolitan areas with high hotel density anchor commercial volume growth through centralized vendor programs.
Germany
Industrial laundries serving automotive and manufacturing sectors specify concentrated scent boosters compatible with automated dosing systems. ECHA classification requirements under REACH govern permissible fragrance palettes for export-bound production. The North Rhine-Westphalia chemical cluster hosts formulation R&D facilities serving pan-European distribution.
China
Contract manufacturers in the Yangtze River Delta supply private-label scent boosters to North American and European brands seeking cost-competitive encapsulation. GB standards on chemical safety and the Ministry of Ecology and Environment's discharge regulations shape domestic production protocols. Shanghai-based logistics hubs facilitate bulk chemical ingredient procurement for regional fragrance houses.
India
Rising household penetration of washing machines in Maharashtra and Gujarat expands addressable demand for pod and crystal formats. The Bureau of Indian Standards maintains voluntary safety guidelines for fragranced consumer products without mandatory allergen disclosure. Mumbai-Pune industrial corridors attract multinational formulation facilities targeting Middle East export markets.
Brazil
São Paulo's commercial laundry sector adopts concentrated scent boosters for hospitality and healthcare institutional procurement. ANVISA regulates cosmetic-grade fragrance ingredients without equivalent EPA-style chemical disclosure mandates. Southeast Brazilian manufacturing zones leverage Mercosur trade access to supply Argentine and Chilean distribution channels.
Laundry Scent Booster Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and subscription commerce integration to bypass retail shelf competition. The market exhibits moderate consolidation with three to five multinational groups commanding mass retail presence alongside regional specialists in private-label manufacturing. Strategic archetypes include captive polymer researchers, contract encapsulation providers, and direct-to-consumer subscription operators. Dominant competitive moves encompass capacity expansion in microencapsulation lines and strategic partnerships with hospitality procurement consortiums.
Among North American consumer goods conglomerates, Procter & Gamble Company and Church & Dwight Co., Inc. exemplify divergent tier positioning through format specialization. Henkel Corporation represents European-based concentrated liquid expertise, while Reckitt Benckiser and Unilever occupy multinational footprint archetypes spanning mass retail and institutional channels. These named entities anchor competitive dynamics without constraining the full spectrum of active participants.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Venus Laboratories |
| Procter & Gamble Company |
| Clorox |
| Recochem |
| Henkel Corporation |
| S. C. Johnson & Son, Inc. |
| Unilever |
| Church & Dwight Co., Inc. |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility in synthetic aroma chemicals cascades through formulation costs into three-tier pricing structure across premium, standard, and economy levels, with biodegradable salt variants capturing green-certification premiums while conventional petrochemical-based alternatives face margin compression.
Pricing Analysis
Retailer markup layers compress pod format margins as hospitality procurement shifts toward direct national account purchasing. Three-tier pricing structure across premium, standard, and economy levels separates biodegradable microencapsulation formats from conventional petrochemical-based alternatives, with certification grade and volume scale as primary price differentiation drivers. Price erosion runs through crystal segments as bulk commercial procurement centralizes. Multi-family housing property managers exhibit highest price sensitivity; hospitality chains with sustainability mandates show lowest.
Supply Chain Analysis
Freight economics from Yangtze River Delta contract manufacturers to North American distribution centers hinge on flexible pouch formats minimizing cube utilization. Microencapsulation polymer supply draws from Germany, China, and United States production clusters. Fragrance oil sourcing rests on petrochemical feedstock and natural extract dependencies. Single-source vulnerability concentrates in regional microencapsulation line capacity. Distribution runs through mass merchant retail and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with California Air Resources Board VOC limits and EPA Safer Choice certification creating tiered compliance moats that separate premium-positioned suppliers from commodity competitors.
For Market Incumbents: Anticipate concentrated pod format margin compression by accelerating captive polymer research investments in biodegradable microencapsulation. Defend against emerging subscription commerce operators through direct national account capabilities with hospitality procurement consortiums. Prioritize California Proposition 65 reformulation completion ahead of disclosure threshold tightening. For New Entrants and Emerging Players: Multi-family housing property management procurement channels represent the most penetrable white-space target, with shared laundry facilities in dense urban clusters remaining underserved by retail-centric distribution. Subscription commerce integration with mailbox-compatible pouch formats offers the lowest customer acquisition cost pathway. Target bulk crystal sustainability certification for green procurement mandate capture. For Investors and Strategic Acquirers: Consolidation pressure builds where fragrance chemist talent scarcity constrains R&D velocity for mid-tier manufacturers. Long-term viability favors acquirers of contract encapsulation providers with dual-compliance architectures for U.S. EPA and ECHA REACH obligations. Watch state-level right-to-know legislation proliferation as inflection indicator for compliance cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Microencapsulation Scale-Up | Captures hospitality sustainability procurement mandates in Phoenix, Miami, and Las Vegas. |
| Direct-to-Consumer Subscription Launch | Bypasses mass retail slotting fees through replenishment automation in dense urban clusters. |
| Backward Integration into Polymer Research | Secures competitive moats for sustained-release fragrance delivery architectures. |
| California Proposition 65 Reformulation | Avoids warning label obligations as allergen disclosure thresholds tighten. |
| Hospitality National Account Partnership | Locks in volume through approved vendor programs with centralized procurement. |
Research Methodology
Bottom-up hospitality and household modeling reconciled against top-down microencapsulation capacity tracking forms the analytical core. Primary interviews with fragrance formulation chemists, hospitality procurement directors, multi-family housing property managers, and mass merchant category buyers combined with secondary validation from EPA Safer Choice certifications, California Air Resources Board filings, customs trade data, and Nielsen retail audit records. Triangulation across these inputs anchors volume and value estimates.
Input-output matrices map product type, packaging format, distribution channel, and end-user segmentation dimensions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate cold-water washing penetration curves, hospitality procurement automation adoption, and state-level chemical disclosure legislative timelines.
Inputs from hospitality procurement databases and fragrance industry trade associations were available through the study window; gaps in commercial laundry automation deployment rates introduce uncertainty bands around pod format volume estimates. Forecasts reflect assumptions on regulatory enforcement consistency and petrochemical feedstock price stability. A model refresh is warranted upon material change in California Proposition 65 allergen threshold implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market