
 Drain Sponges Market | 2026-2036
Drain Sponges Market Size, Share, and Industry Trends Forecast 2026-2036
Drain Sponges Market Foresight
Aftermarket service revenue is rewriting value capture in the drain sponges ecosystem as manufacturers seek recurring income beyond unit sales. Medline Industries leverages its direct-to-facility distribution network to sustain institutional relationships across acute care settings. Cardinal Health anchors its position through integrated sourcing agreements with hospital purchasing coalitions. B. Braun differentiates via specialized surgical sponge portfolios that meet stringent operating room protocols.
Drain sponges are absorbent, woven or non-woven pads designed to collect and channel fluids from surgical sites, wound beds, or industrial surfaces, typically constructed from cotton, rayon, or synthetic polymer blends with specified porosity and tensile strength ratings. Their primary purpose centers on fluid management, contamination control, and surface preparation across medical, food service, and automotive maintenance environments. Synthetic fiber products dominate hospital procurement due to consistent absorbency and lower linting profiles, while biodegradable variants are gaining traction in food service applications where sustainability mandates intensify. Microfiber segments command premium positioning in automotive and industrial end uses where particle capture precision drives replacement cycles.
The FDA's medical device regulations govern surgical drain sponges through quality system requirements and adverse event reporting, while EPA frameworks influence antimicrobial claims and disposal pathways for saturated materials. OSHA bloodborne pathogen standards shape handling protocols in medical settings, directly impacting product design for barrier protection and single-use disposability. Stakeholders must monitor evolving state-level sustainability mandates and purchasing cooperative consolidation to anticipate volume shifts and qualification requirements.
Market Dynamics
Ambulatory surgical centers are consolidating purchasing power while demanding higher absorbency standards, compressing margins for manufacturers who must simultaneously absorb raw cotton volatility and comply with tightening FDA adverse event reporting mandates.
Growth Catalysts
- OSHA Bloodborne Pathogen Standards:Hospital systems in the United States are accelerating single-use disposability protocols, mandating barrier-protected drain sponges for all invasive procedures to eliminate cross-contamination liability.
- Rayon-polymer hybrid construction:Operating room protocols now specify synthetic blends that deliver consistent fluid wicking rates, displacing traditional cotton in cardiac and orthopedic surgical suites.
- India:CDSCO registration pathways for Class B medical devices are streamlining, enabling faster market entry for absorbent surgical products as hospital infrastructure expands in tier-2 cities.
Market Restraints
- Cotton price volatility:Raw fiber costs swing with climate-driven harvest disruptions in Egypt and India, squeezing margin structures for manufacturers without backward integration into textile sourcing.
- China supply concentration:Synthetic polymer precursor production clusters in Zhejiang and Jiangsu provinces, creating single-point vulnerability for global non-woven supply chains.
- Biodegradability-performance tradeoff:Cellulose-based alternatives degrade faster than synthetic equivalents, limiting their deployment in procedures requiring extended fluid management duration.
Strategic Opportunities
- Brazil:ANVISA's simplified medical device registration for low-risk absorbents opens underpenetrated surgical markets as private hospital chains expand in São Paulo and Minas Gerais.
- EU Green Deal procurement mandates:Public hospital systems must source 50% sustainable materials by 2030, creating preferential contracting pathways for compostable sponge variants.
- Direct-to-facility distribution:Bypassing traditional medical-surgical distributors through proprietary logistics networks captures margin and locks in multi-year supply agreements.
Industry Challenges
- FDA 510(k) clearance timelines:Novel antimicrobial coating submissions face 12-18 month review cycles, delaying revenue recognition for innovation pipelines.
- ISO 13485 audit complexity:Small manufacturers struggle with quality management system documentation requirements for traceability and batch record retention across multi-site production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drain Sponges Market |
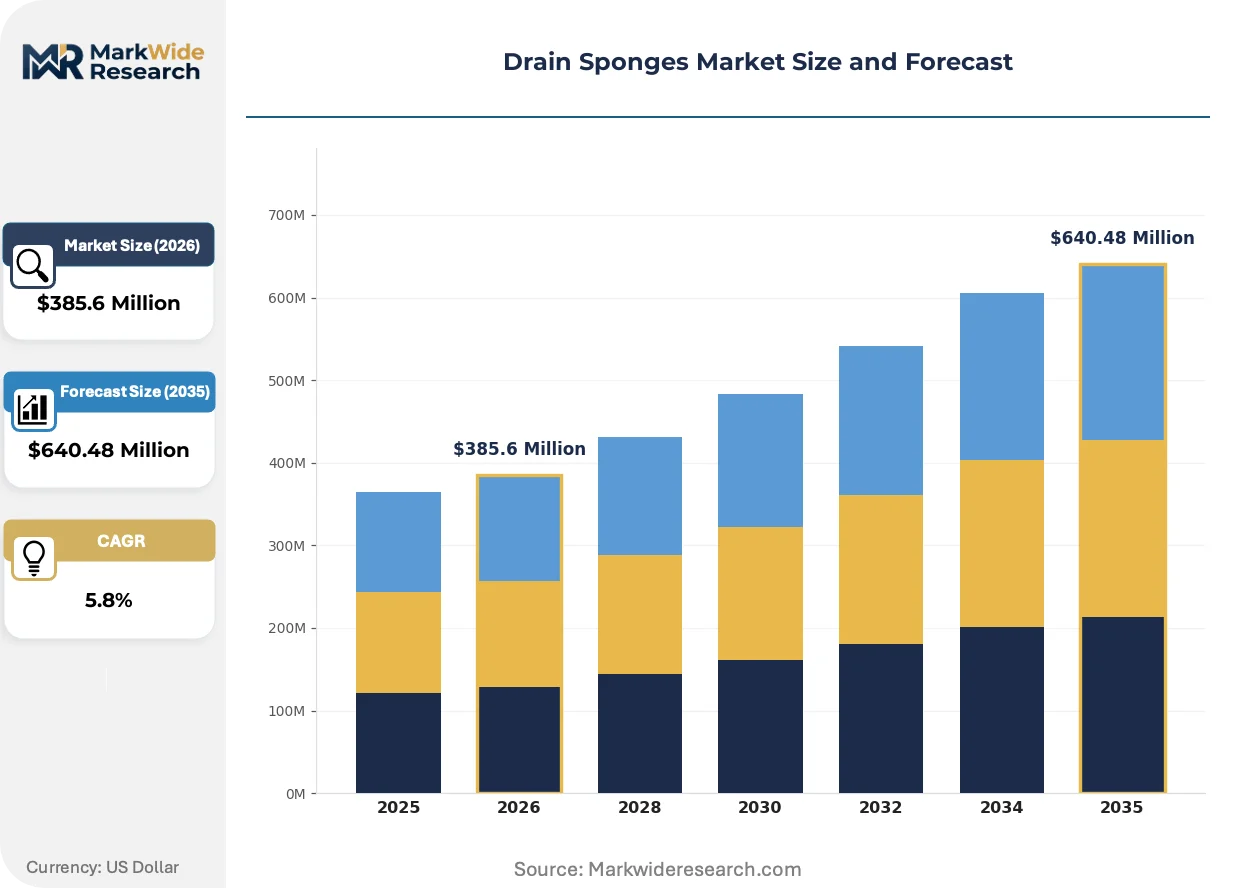
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber, Synthetic Fiber, Biodegradable, Microfiber End User: Households, Commercial Kitchens, Automotive, Industrial Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Food Service, Automotive Maintenance, Household Cleaning, Medical Use |
| Companies Covered | Medline Industries, McKesson Corporation, Cardinal Health, Dukal Corporation, Dynarex Corporation, Covidien, B. Braun, AMD-Ritmed, ReliaMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drain Sponges Market Shifts & Advancements
Material science convergence with infection control protocols is redefining performance benchmarks. Manufacturers now engineer sponge architectures for specific fluid viscosities rather than generic absorbency.
Chitosan-impregnated cellulose is hybridizing antimicrobial functionality with structural integrity. Cardiac surgery units at academic medical centers are piloting these variants for sternal drainage applications. The technology is hybridizing product categories previously separated into standard and antimicrobial SKUs, collapsing hospital inventory complexity.
EPA antimicrobial claim substantiation rules are tightening efficacy data requirements for silver-ion and PHMB-treated sponges. Manufacturers must now submit quantitative kill-rate studies against specific pathogen panels. Surgical sponge portfolios targeting outpatient settings face the steepest compliance cost increases as label claims narrow.
Consolidated purchasing coalitions are unbundling after-sales service from product pricing. Hospital systems now negotiate sponge supply separate from inventory management or clinical training support. This bifurcation is most visible in United States GPO contracting, where unit price transparency dominates RFP scoring over bundled value propositions.
Drain Sponges Market Segmentation
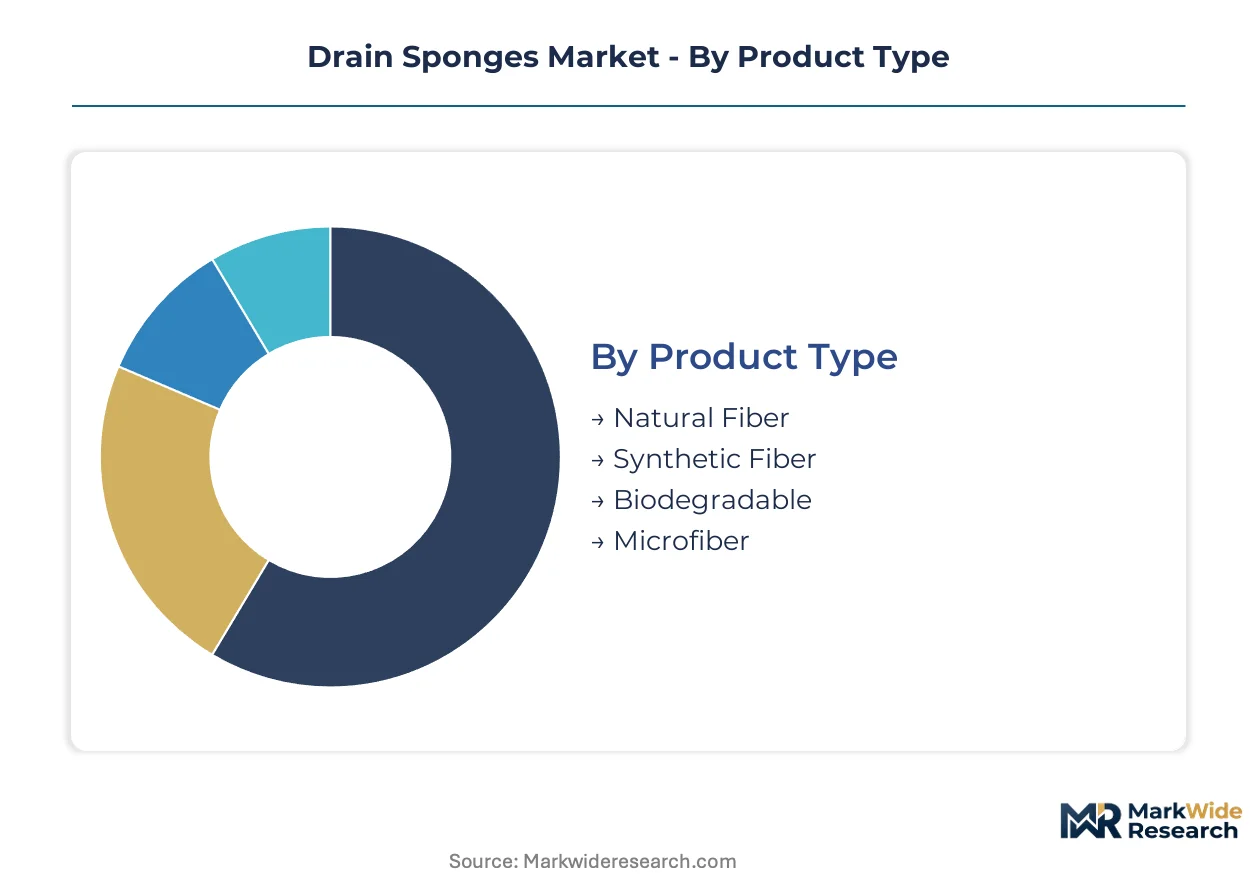
Drain sponge procurement patterns diverge sharply across end-use environments, with medical facilities prioritizing lint-free synthetic construction while food service operators weigh biodegradability against performance. Manufacturers must architect distinct product portfolios for each channel, as absorbency specifications and regulatory compliance requirements vary by application.
Product Type:
Material composition determines performance ceilings, cost structures, and regulatory pathways across hospital, industrial, and consumer applications.
- Synthetic Fiber:Rayon-polymer blends deliver calibrated porosity and minimal linting for cardiac and orthopedic surgical suites. Operating rooms in the United States specify these variants for invasive procedures requiring consistent fluid wicking rates and FDA-compliant barrier protection.
- Natural Fiber:Cotton-based construction retains cost advantages in household and light commercial settings where extended fluid management duration is unnecessary. Egyptian and Indian harvest volatility squeezes margin structures for manufacturers without backward integration into textile sourcing.
- Biodegradable:Cellulose alternatives address EU Green Deal procurement mandates and food service sustainability requirements, though faster degradation limits deployment in procedures requiring sustained absorbency.
- Microfiber:Engineered synthetic filaments capture sub-micron particles for automotive detailing and precision industrial surface preparation.
Synthetic fiber commands the established base in medical procurement. The steepest expansion runs through biodegradable variants as public hospital systems face mandated sustainable material thresholds.
End User:
Customer type shapes volume scale, pricing tolerance, and technical specification intensity across the demand spectrum.
- Commercial Kitchens:High-turnover food service operations prioritize disposability and grease-handling capacity over unit economics. EPA disposal pathway regulations for saturated materials influence procurement decisions in United States institutional food service chains.
- Automotive:Detailing shops and maintenance facilities demand particle capture precision and chemical resistance for solvent-based cleaning protocols.
- Industrial:Manufacturing maintenance departments specify tensile strength ratings for heavy-duty surface preparation and spill containment.
- Households:Price-sensitive consumers drive private-label penetration through supermarket and online retail channels.
Commercial kitchens anchor volume concentration. The steepest expansion trajectory belongs to automotive end users as electric vehicle production expands precision maintenance requirements.
Distribution Channel:
Channel selection determines margin capture, customer relationship depth, and inventory velocity for manufacturers and intermediaries.
- Wholesale:Medical-surgical distributors and industrial supply houses move bulk volume to hospital systems and manufacturing facilities under multi-year sourcing agreements.
- Online Retail:E-commerce platforms aggregate fragmented household and small commercial demand, compressing delivery timelines and expanding private-label penetration.
- Specialty Stores:Surgical supply dealers and automotive detailing retailers provide technical consultation and product education for specification-intensive buyers.
- Supermarkets:Mass retail captures household replenishment purchases through high-visibility placement and promotional pricing.
Wholesale channels retain institutional volume leadership. Online retail is climbing the fastest as direct-to-facility distribution models bypass traditional distributor markups.
Application:
Use case specificity dictates absorbency architecture, antimicrobial requirements, and disposal protocols across divergent operating environments.
- Medical Use:Surgical drain sponges must meet FDA quality system requirements and OSHA bloodborne pathogen standards for single-use disposability. Chitosan-impregnated cellulose variants are piloting in academic medical center cardiac units for sternal drainage.
- Food Service:Commercial kitchens balance grease absorption performance against compostability mandates intensifying under state-level sustainability regulations.
- Automotive Maintenance:Precision surface preparation for painting and coating operations requires microfiber segments with specified particle retention ratings.
- Household Cleaning:General-purpose absorbency for spills and surface maintenance prioritizes cost efficiency over specialized performance metrics.
Medical use anchors premium pricing and regulatory compliance investment. Food service is gaining share fastest as sustainability procurement mandates reshape institutional purchasing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among household consumers in India and Brazil contrasts sharply with premium tolerance in German surgical suites and US academic medical centers, creating divergent margin architectures across geographies.
United States
Ambulatory surgical center volume expansion in Texas and Florida drives absorbent product procurement, while OSHA bloodborne pathogen standards mandate single-use disposability protocols. FDA 510(k) clearance timelines for novel antimicrobial coatings extend 12-18 months, delaying revenue recognition for innovation pipelines. The Dallas-Fort Worth metroplex anchors distribution hub consolidation as Medline Industries and Cardinal Health optimize direct-to-facility logistics.
Germany
EU Green Deal procurement mandates require public hospital systems to source 50% sustainable materials by 2030, accelerating compostable sponge variant qualification. EMA medical device regulations and MDR quality system requirements tighten traceability documentation for surgical absorbents. The Baden-Württemberg industrial corridor hosts specialized non-woven manufacturing clusters serving cardiac and orthopedic surgical instrument supply chains.
China
Synthetic polymer precursor production concentrates in Zhejiang and Jiangsu provinces, creating single-point vulnerability for global non-woven supply chains. NMPA medical device registration pathways for Class II absorbents are streamlining, though quality system audits intensify for foreign manufacturers. Shanghai's Yangtze River Delta logistics hub channels export volume to Southeast Asian hospital construction projects.
India
CDSCO registration pathways for Class B medical devices are accelerating market entry as hospital infrastructure expands in tier-2 cities like Pune and Lucknow. Raw cotton price volatility from climate-driven harvest disruptions in Maharashtra and Gujarat squeezes margin structures for manufacturers lacking backward integration into textile sourcing. The Delhi-NCR corridor concentrates medical-surgical distributor networks serving northern private hospital chains.
Brazil
ANVISA's simplified medical device registration for low-risk absorbents opens underpenetrated surgical markets as private hospital chains expand in São Paulo and Minas Gerais. Price-sensitive procurement in public health systems contrasts with premium positioning opportunities in Rio de Janeiro's cosmetic surgery clinics. The São Paulo metropolitan area anchors regional distribution infrastructure for imported synthetic fiber products.
Drain Sponges Market Competitive Landscape
Capability concentration sits with specialized surgical sponge manufacturers; scale advantage sits with diversified health care distributors. The market structures around three tiers: integrated health care supply conglomerates with direct-to-facility networks, mid-cap medical device specialists with ISO 13485-certified production, and regional private-label fabricators serving price-sensitive channels. Dominant competitive moves include proprietary logistics network expansion to bypass distributor markups, and chitosan-impregnated cellulose R&D to collapse antimicrobial and standard SKU inventories.
Among diversified health care distributors, Medline Industries, McKesson Corporation, and Cardinal Health exemplify the scale-driven tier. These entities leverage institutional purchasing relationships and integrated sourcing agreements with hospital coalitions. Medline Industries occupies a position anchored in direct distribution infrastructure. McKesson Corporation represents the pharmaceutical-wholesale heritage applied to medical-surgical categories. Cardinal Health sits within the group purchasing organization contracting ecosystem, capturing volume through multi-year supply agreements rather than product differentiation.
| Leading Market Players |
|---|
| Medline Industries |
| McKesson Corporation |
| Cardinal Health |
| Dukal Corporation |
| Dynarex Corporation |
| Covidien |
| B. Braun |
| AMD-Ritmed |
| ReliaMed |
| Others |
Supply & Pricing Matrix
Zhejiang and Jiangsu province polymer precursor clusters concentrate upstream bargaining power with rayon-polymer blend manufacturers, pushing margin capture toward direct-to-facility distributors who bypass traditional medical-surgical markups. Raw cotton harvest volatility in Egypt and India further compresses pricing flexibility for natural fiber product tiers.
Pricing Analysis
After-sales service revenue tiers—including inventory management contracts and clinical training support—drive lifetime value capture as hospital purchasing coalitions unbundle these services from unit pricing. Three-tier pricing structure across premium chitosan-impregnated cellulose, standard synthetic fiber, and economy cotton grades reflects ISO 13485 certification investment and FDA 510(k) clearance status. Cost compression in economy cotton tiers is intensifying because climate-driven harvest disruptions in Maharashtra and Gujarat squeeze margin structures. Ambulatory surgical centers exhibit highest price sensitivity due to consolidated GPO contracting, while academic medical center cardiac units tolerate premium positioning for antimicrobial variants.
Supply Chain Analysis
Upstream feedstock angles center on Egyptian and Indian cotton cultivation, Chinese synthetic polymer precursor production, and Brazilian eucalyptus pulp for cellulose alternatives. Raw material dependencies span rayon staple fiber, petroleum-derived polymer resins, and pharmaceutical-grade chitosan coatings. Single-source vulnerability concentrates in Zhejiang province non-woven substrate manufacturing, where NMPA quality system audits create foreign manufacturer qualification delays. Distribution runs through direct-to-facility logistics networks for hospital systems, wholesale medical-surgical distributors for mid-tier facilities, and online retail platforms for household and small commercial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as chitosan-impregnated cellulose hybridizes antimicrobial and standard SKU categories, collapsing hospital inventory complexity and threatening legacy product line differentiation.
For Market Incumbents: Pre-empt antimicrobial coating commoditization by accelerating proprietary chitosan-cellulose R&D pipelines and securing exclusive sternal drainage pilot contracts with academic medical center cardiac units. Backward integration into Egyptian cotton sourcing or Zhejiang polymer precursor partnerships defends margin structures against raw fiber volatility and supply concentration risks. For New Entrants and Emerging Players: Establish a beachhead in Brazil's underpenetrated surgical markets by leveraging ANVISA's simplified low-risk absorbent registration pathway and targeting private hospital chain expansion in São Paulo. Direct-to-facility distribution partnerships with tier-2 city hospital infrastructure projects in India bypass entrenched medical-surgical distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap medical device specialists possessing ISO 13485-certified production but lacking direct distribution infrastructure. Long-term viability hinges on five-to-ten year EU Green Deal procurement mandate compliance, where compostable sponge variant qualification determines contract eligibility. Monitor FDA 510(k) clearance timeline compression for novel antimicrobial submissions as inflection indicator for innovation pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chitosan-Impregnated Cellulose R&D Investment | Collapses antimicrobial and standard SKU inventories for academic medical center cardiac units. |
| Direct-to-Facility Distribution Expansion | Bypasses Cardinal Health and McKesson distributor markups through proprietary logistics networks. |
| Egyptian Cotton Backward Integration | Captures margin from climate-driven harvest volatility in Maharashtra and Gujarat cultivation zones. |
| Brazil ANVISA Registration Acceleration | Opens São Paulo private hospital chain procurement for low-risk absorbent surgical products. |
| EU Green Deal Compliance Certification | Qualifies compostable sponge variants for 2030 mandatory sustainable material thresholds in German public hospitals. |
Research Methodology
Initial hypotheses were tested against primary input from operating room supply managers, hospital purchasing committee directors, biomedical engineers, and GPO contracts specialists, and refined through secondary validation against FDA 510(k) clearance databases, EPA antimicrobial claim substantiation filings, hospital procurement contract registries, and customs trade data for rayon-polymer precursor flows. Bottom-up facility-level demand modeling and top-down macro healthcare expenditure triangulation anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning material composition tiers, end-use environment specifications, distribution channel architectures, and regional regulatory cluster compliance requirements. CAGRs derived from facility construction pipelines, ambulatory surgical center volume trajectories, and sustainable procurement mandate phase-in schedules. Industry-specific inputs incorporated OSHA bloodborne pathogen standard enforcement intensity and EU MDR traceability documentation requirements.
Sensitivities concentrate around FDA 510(k) review cycle elongation for novel antimicrobial coatings, Egyptian cotton harvest disruption frequency, and Zhejiang province logistics chokepoint vulnerability. Cross-checking against CMS hospital outpatient procedure volume benchmarks and EMA medical device registration trend data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Household Cleaning Products Market