
 Janitorial Service Market | 2026-2036
Janitorial Service Market Size, Share, and Industry Trends Forecast 2026-2036
Janitorial Service Market Intelligence
The Occupational Safety and Health Administration's (OSHA) Hazard Communication Standard, aligned with Europe's REACH framework, is broadening the scope of required chemical safety training. This shift elevates compliance costs and favors larger, sophisticated providers. ISS A/S leverages its global scale to standardize training protocols and procurement across multiple countries. In contrast, ABM Industries differentiates through specialized service bundles tailored for high-security and technical facilities in the United States.
Janitorial service encompasses contracted cleaning, sanitation, and maintenance activities for buildings and facilities. These services utilize specific protocols, such as using HEPA-filtered vacuums to meet indoor air quality standards and employing certified disinfection technologies. Commercial cleaning for corporate clients forms the market's foundational volume, while services for healthcare facilities offer higher margins due to specialized compliance requirements. The contract-based service model remains the dominant structure, though on-demand services are gaining traction in the residential cleaning segment.
Regulatory oversight from bodies like the U.S. Environmental Protection Agency (EPA) through its Safer Choice program directly influences product selection. In parallel, standards organizations such as India's BIS and China's SAMR set compliance benchmarks for cleaning chemicals and equipment, impacting market access. Service providers must now strategically decide on capital investment in automated cleaning equipment versus managing a fluctuating labor force.
Market Dynamics
The janitorial service market is being fundamentally reshaped by the convergence of stringent public health requirements and corporate sustainability mandates. This dual pressure forces providers to simultaneously upgrade hygiene protocols and adopt environmentally responsible operating models, favoring scale and technical sophistication.
Growth Catalysts
- Healthcare Hygiene Mandates:Heightened infection control standards in hospitals and clinics drive demand for specialized services, including the use of HEPA-filtered vacuums and certified disinfection technologies to meet stringent indoor environmental quality benchmarks.
- Green Building Certifications:Policies like the European Union's Green Deal and voluntary standards for commercial real estate create a strong pull for services that use eco-friendly products and sustainable waste management practices.
- Corporate Outsourcing Trends:The persistent trend of outsourcing non-core functions within large corporations continues to fuel demand, particularly in major commercial office markets across the United States and Western Europe.
Market Restraints
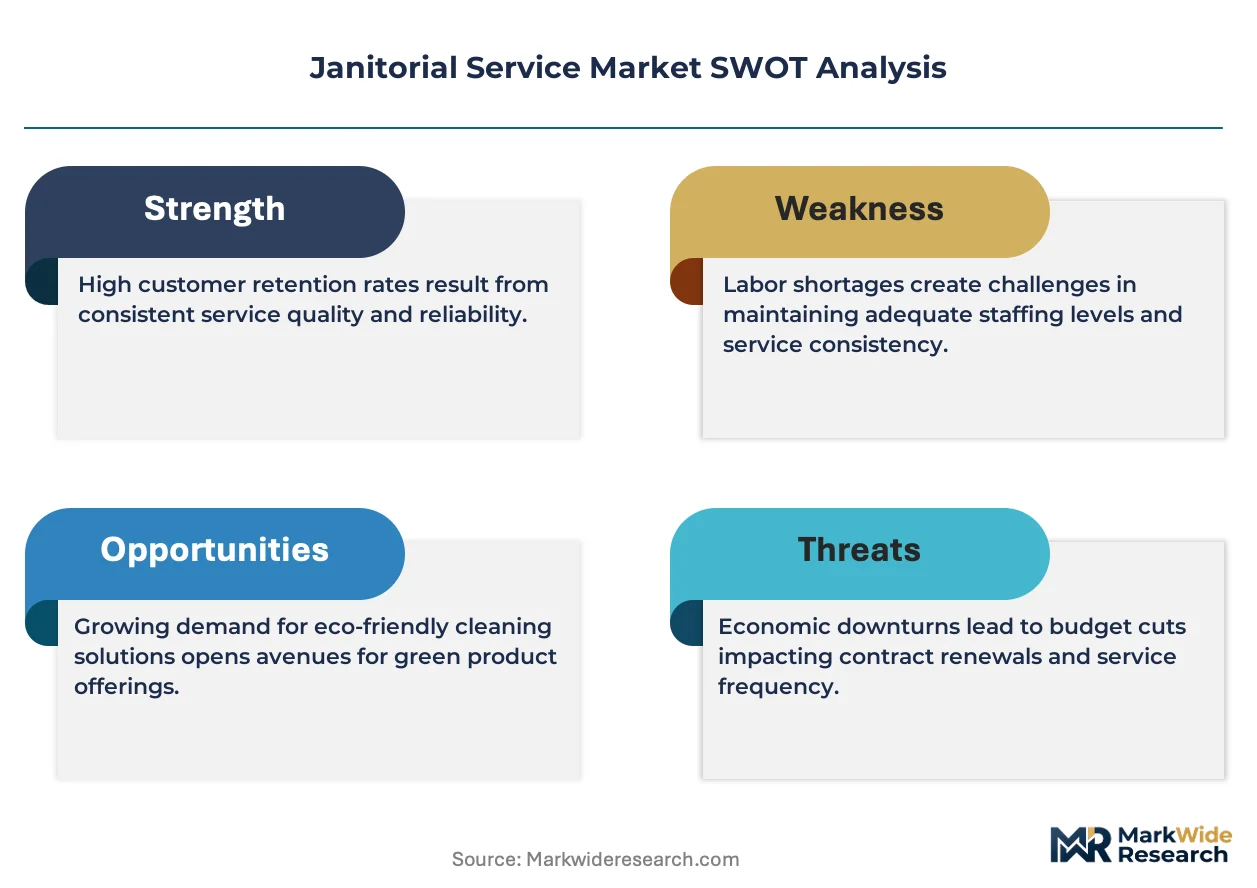
- Labor Force Volatility:The industry's high dependence on a fluctuating labor force creates persistent challenges in recruitment, training, and retention, leading to unpredictable operating costs and service consistency issues for providers.
- Chemical Compliance Costs:Alignment between regulations like OSHA's Hazard Communication Standard and Europe's REACH framework increases the complexity and cost of chemical safety training and documentation for all service providers.
- Automation Capital Expenditure:The high upfront investment required for robotic scrubbers, autonomous vacuums, and other automated cleaning equipment acts as a significant barrier for small and medium-sized service companies.
Strategic Opportunities
- Specialized Service Bundling:Providers can develop and market integrated service packages tailored to high-value niches, such as cleaning and maintenance for high-security government facilities, data centers, or biopharmaceutical cleanrooms.
- On-Demand Digital Platforms:The development of mobile-first, on-demand booking platforms presents an opportunity to capture a larger share of the fragmented residential and small commercial cleaning segments, bypassing traditional contract models.
- Certified Green Cleaning:Achieving certifications under programs like the EPA's Safer Choice allows providers to differentiate their services and command premium pricing from clients focused on sustainability and employee wellness.
Industry Challenges
- Advanced Training Requirements:A growing skills gap exists for janitorial staff who must be trained not only in cleaning protocols but also in operating smart equipment and handling a wider range of specialized, eco-friendly chemicals.
- Technology Integration Complexity:Integrating new automated cleaning systems with clients' existing facility management software and building security protocols presents a significant operational hurdle for service providers.
- Sustainable Supply Chain Gaps:Ensuring a consistent and cost-effective supply of certified green cleaning chemicals and recycled paper products remains a logistical challenge, particularly outside of major metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Janitorial Service Market |
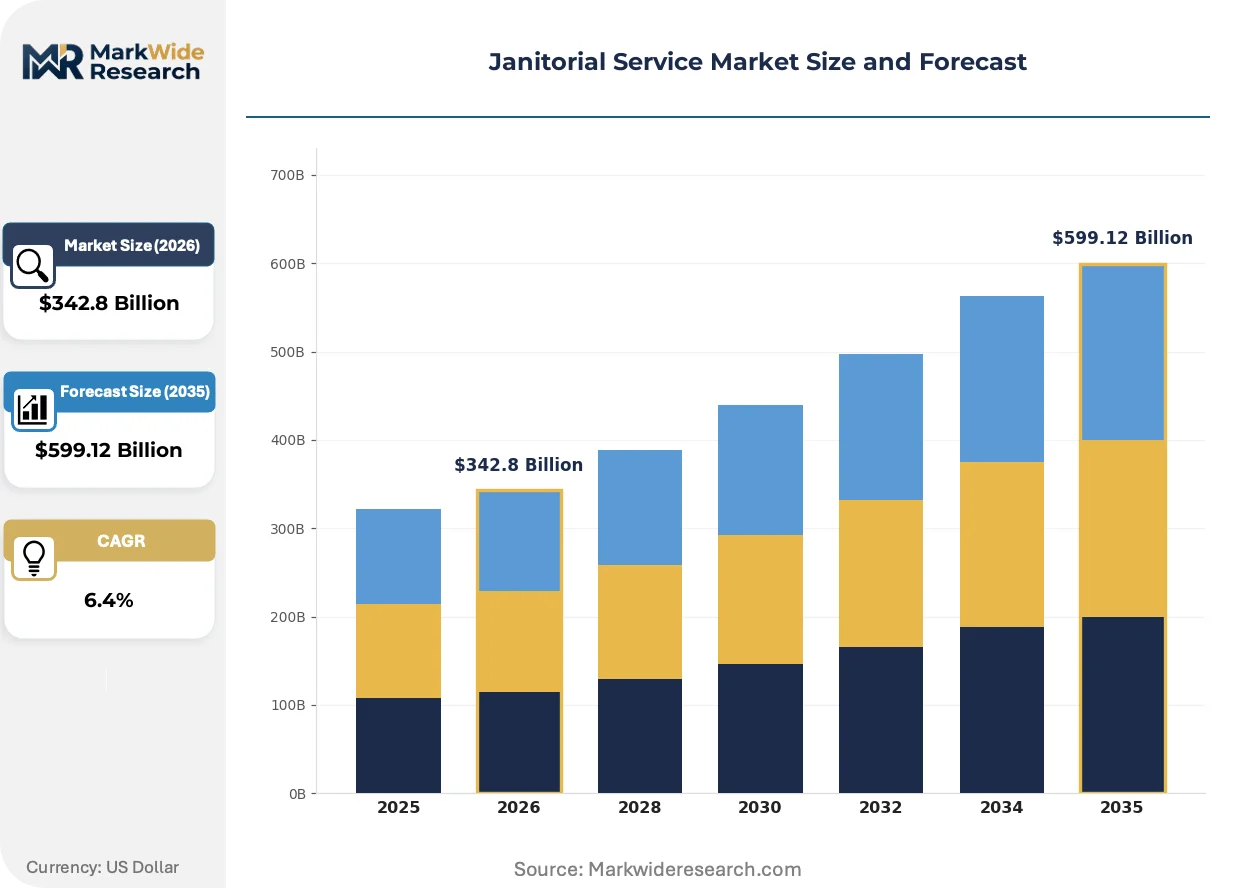
| Market Size in 2026 | $342.8 Billion |
| Market Size in 2035 | $599.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Commercial Cleaning, Residential Cleaning, Specialty Cleaning, Carpet Care Client Type: Corporations, Educational Institutions, Healthcare Facilities, Hospitality Technology: Eco-Friendly Products, Automated Cleaning Equipment, Disinfection Technology, Hard Surface Restoration Service Model: Contract-Based Services, On-Demand Services, Outsourced Services, In-House Services |
| Companies Covered | ABM Industries, Jani-King International, ServiceMaster Clean, ISS A/S, Mitie Group, Jan-Pro Franchising, Aeon Delight, Coverall North America, Pritchard Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Janitorial Service Market Strategic Shifts & Innovations
Service delivery models are shifting from a focus on manual labor and fixed schedules to an emphasis on verified cleanliness, sustainability, and operational efficiency. This evolution is driven by technological advancements and changing client expectations for healthier indoor environments.
Automated cleaning systems, particularly robotic floor scrubbers and vacuums equipped with IoT sensors, provide real-time data on usage and coverage. Large commercial real estate operators and healthcare networks are adopting this technology to improve efficiency across vast facilities. This autonomous cleaning technology is converging with building management systems to enable predictive maintenance schedules and digitally verify compliance with cleaning protocols.
China's State Administration for Market Regulation (SAMR) is enforcing more stringent GB standards for the composition and efficacy of cleaning chemicals. This regulatory action compels both domestic and international manufacturers to reformulate products to maintain market access, elevating research and certification costs. The commercial cleaning segment is most affected, as providers must now rigorously document the compliance of their chemical inventory.
Clients are increasingly moving from fixed-frequency contracts to performance-based agreements that link payment to measurable outcomes, such as specific indoor air quality metrics or surface microbial counts. This model disrupts the traditional approach of billing for labor hours, replacing it with a focus on verified results. This shift is most visible within high-stakes verticals like data centers and healthcare, where cleanliness directly impacts operational integrity and safety.
Janitorial Service Market Segmentation
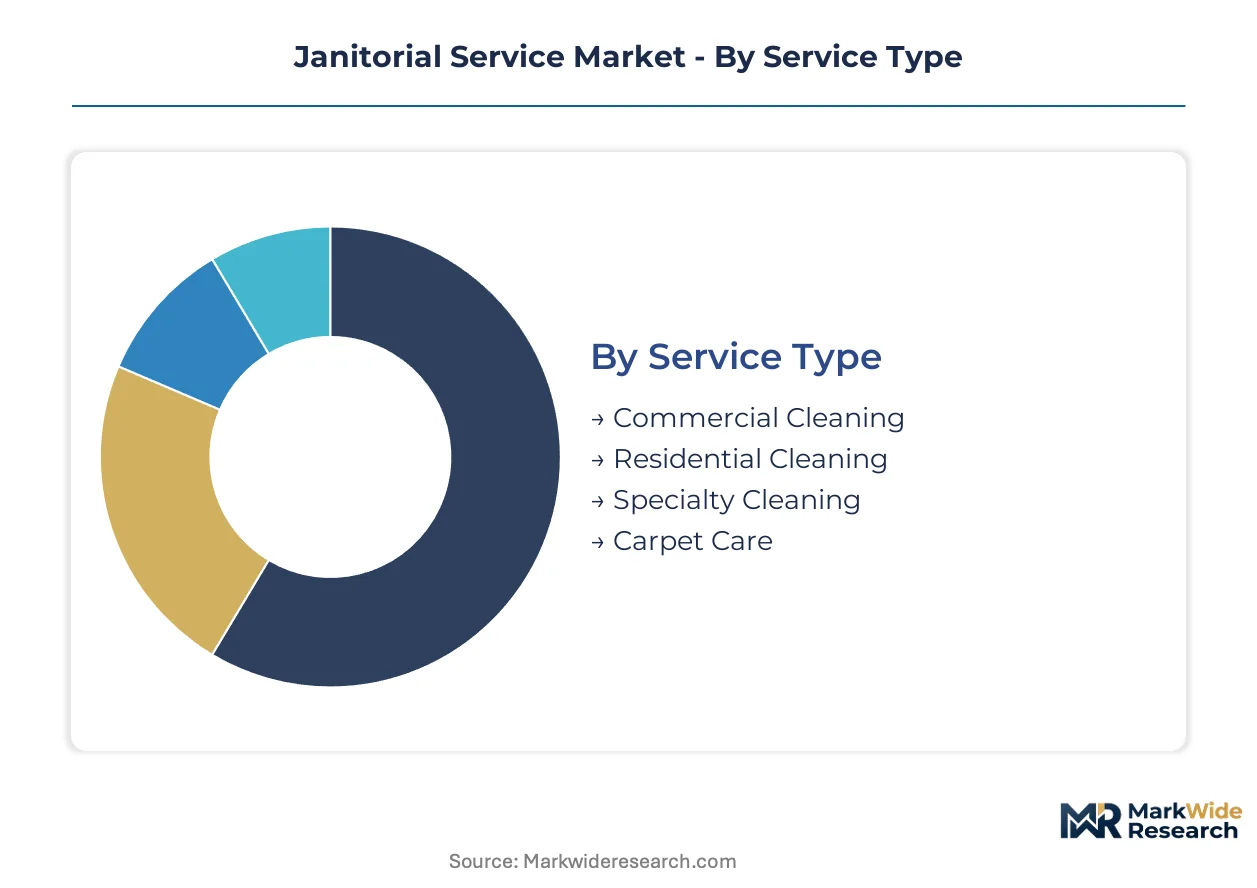
Market segmentation provides a critical framework for understanding the diverse operational strategies and specialized service delivery within the janitorial industry. Analyzing distinct segments reveals how providers tailor their offerings to meet specific client demands, technological advancements, and evolving regulatory landscapes.
Service Type:
Service type segmentation reveals how core cleaning operations integrate into broader facility management or function as standalone offerings.
- Commercial Cleaning:This segment encompasses routine and deep cleaning services provided to offices, retail spaces, and industrial facilities. Demand concentrates in major commercial office markets across the United States and Western Europe, driven by corporate outsourcing trends.
- Specialty Cleaning:These services involve highly specialized protocols for environments like data centers, biopharmaceutical cleanrooms, or post-construction sites. Healthcare facilities and high-security government buildings require these services due to stringent compliance and operational integrity needs.
- Residential Cleaning:Services target individual homes and apartment complexes, often leveraging digital platforms for booking and scheduling. This segment is experiencing growth through on-demand service models.
- Carpet Care:This specialized service focuses on deep cleaning, stain removal, and maintenance of various carpet types within commercial and residential settings. Specific equipment and chemical treatments are often required.
Commercial Cleaning leads volumes today; Specialty Cleaning is gaining share fastest.
Client Type:
Client type segmentation highlights distinct service requirements driven by varying operational environments and regulatory frameworks.
- Healthcare Facilities:These clients demand stringent infection control protocols, including HEPA-filtered vacuums and certified disinfection technologies. Regulatory bodies like OSHA and the EPA mandate specific hygiene standards for patient safety.
- Corporations:This segment represents a foundational volume base, encompassing large office buildings, corporate campuses, and business parks. Outsourcing non-core functions remains a primary driver for these clients in major economic centers.
- Educational Institutions:Schools and universities require services tailored to high-traffic areas and varying schedules, often including summer deep cleaning. Student health and safety protocols are paramount for these clients.
- Hospitality:Hotels, resorts, and restaurants prioritize rapid turnaround times and meticulous presentation to enhance guest experience. Maintaining high aesthetic standards is crucial for brand reputation.
Corporations represent the largest volume segment; Healthcare Facilities command the highest service margins.
Technology:
Technology segmentation illustrates the market's adoption of advanced tools and sustainable practices to enhance efficiency and meet evolving client expectations.
- Automated Cleaning Equipment:This segment includes robotic floor scrubbers, autonomous vacuums, and IoT-enabled devices that provide real-time data on cleaning coverage. Large commercial real estate operators adopt this technology to improve efficiency across vast facilities.
- Eco-Friendly Products:These products adhere to sustainability mandates and certifications from programs like the EPA's Safer Choice and the European Union's Green Deal. Corporate sustainability initiatives and employee wellness programs drive demand for these solutions.
- Disinfection Technology:This category encompasses advanced methods such as electrostatic sprayers and UV-C light systems for pathogen elimination. Heightened public health requirements are driving the adoption of these solutions.
- Hard Surface Restoration:Services involve specialized techniques and chemicals for maintaining and restoring various hard surfaces, including stone, tile, and concrete. Extending the lifespan of facility assets is a key benefit.
Automated Cleaning Equipment attracts significant capital investment; Eco-Friendly Products offer a key differentiation point.
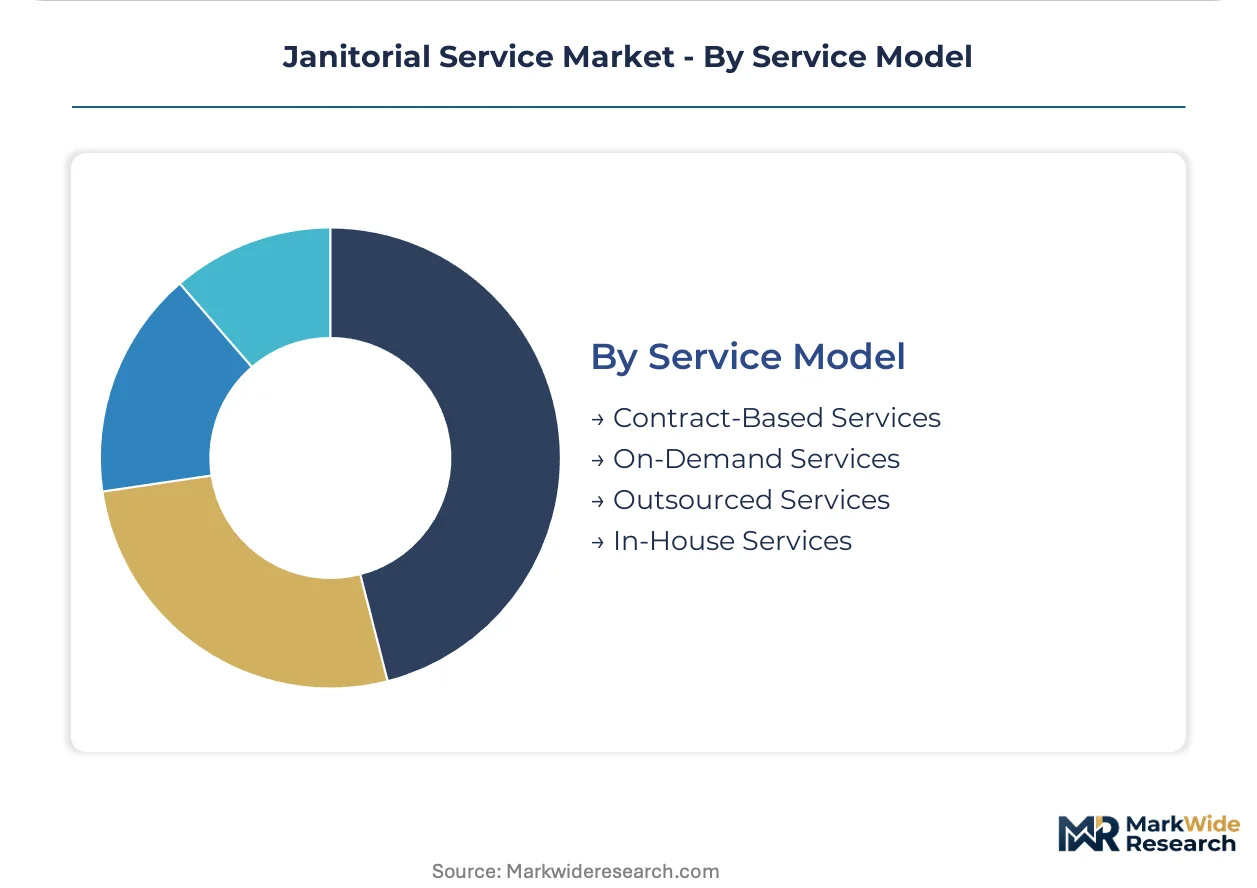
Service Model:
Service model segmentation outlines the fundamental operational structures through which janitorial providers deliver their offerings to diverse clientele.
- Contract-Based Services:This dominant model involves long-term agreements for recurring cleaning and maintenance, providing predictable revenue streams for providers. Major commercial clients primarily utilize these structured arrangements.
- On-Demand Services:These flexible services are typically booked through digital platforms for immediate or short-notice cleaning needs. The residential and small commercial segments are increasingly adopting this convenient model.
- Outsourced Services:Corporations and institutions delegate their janitorial functions to third-party providers to focus on core competencies. This model aims to achieve operational efficiencies and cost savings.
- In-House Services:Facilities directly employ their own janitorial staff, maintaining full control over operations and personnel. This model is often preferred for highly sensitive environments or smaller, specialized sites.
Contract-Based Services hold the largest market share; On-Demand Services are disrupting traditional models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The janitorial service industry scaled significantly in the United States, driven by post-industrialization commercial expansion. Early 20th-century urban growth created a sustained need for professional building maintenance. This foundation established contract-based cleaning as a critical support service for businesses.
United States
Corporate outsourcing trends and the extensive commercial office markets drive consistent demand for janitorial services. OSHA's Hazard Communication Standard elevates the complexity and cost of chemical safety training. Major metropolitan areas like New York City and Chicago concentrate demand for specialized commercial cleaning and facility maintenance.
Germany
Stringent sustainability mandates and the presence of advanced manufacturing facilities underpin demand for eco-friendly janitorial solutions. The European Union's Green Deal directly influences service delivery through mandates on product selection and operational sustainability. Industrial centers such as the Ruhr Valley focus on integrating green cleaning practices for factories and corporate campuses.
China
Rapid urbanization and expanding commercial infrastructure, including new office towers and retail complexes, fuel janitorial service growth. SAMR's GB standards enforce strict requirements for the composition and efficacy of cleaning chemicals. Megacities like Shanghai and Beijing exhibit high demand for commercial cleaning services with documented chemical compliance and advanced disinfection technologies.
India
A growing corporate sector and increasing healthcare infrastructure are creating significant demand for professional janitorial services. India's BIS standards set compliance benchmarks for cleaning chemicals and equipment, impacting market access for providers. Urban hubs such as Bengaluru and Mumbai are adopting sophisticated janitorial services for IT parks and modern hospitals.
United Kingdom
High concentrations of commercial offices and a strong emphasis on green building certifications sustain demand for specialized janitorial services. UK environmental regulations align closely with EU sustainability principles, influencing product selection and waste management practices. London's financial district consistently requires premium janitorial services that utilize sustainable practices and certified disinfection.
Janitorial Service Market Key Industry Players
The competitive structure tilts toward a tiered system, balancing large, integrated service providers with numerous specialized local firms. Market consolidation trends are visible among top-tier players, while fragmentation persists in regional and niche segments. Strategic archetypes include global facility management integrators, regional specialized service groups, and local on-demand providers leveraging digital platforms. Portfolio diversification into complementary services and technology integration, particularly automation, are dominant competitive moves across the industry.
Global facility management integrators like ISS A/S, a Denmark-based public limited company, exemplify the scale-driven approach to standardizing protocols across multiple countries. ABM Industries, an American corporation, occupies a position focused on specialized service bundles for high-security and technical facilities in the United States. ServiceMaster Clean, a US-based franchise system, represents the widespread network model for delivering commercial and residential cleaning services through local operators.
| Leading Market Players |
|---|
| ABM Industries |
| Jani-King International |
| ServiceMaster Clean |
| ISS A/S |
| Mitie Group |
| Jan-Pro Franchising |
| Aeon Delight |
| Coverall North America |
| Pritchard Industries |
| Others |
Cost & Logistics Intelligence
Urban labor pools in major metropolitan areas drive significant labor-cost differentials, directly influencing the pricing tiers for janitorial services. These variations create distinct pricing strategies across regions and service types.
Pricing Analysis
Contract-based service agreements form the dominant pricing model across commercial janitorial services. Price differentiation stems from specialized certifications for healthcare facilities and the scale of service bundles for corporate clients. Pricing softness stems from intense competition in the commercial cleaning segment, particularly for routine services. Large corporations often exhibit high price sensitivity, while healthcare facilities prioritize compliance and specialized protocols over cost.
Supply Chain Analysis
Direct procurement from manufacturers and major distributors characterizes the janitorial supply chain for cleaning chemicals and equipment. China and India are significant sources for basic cleaning chemicals, while automated equipment often originates from European and North American suppliers. Dependence on petrochemical derivatives for many cleaning agents creates commodity price volatility, impacting input costs. Distribution runs through specialized janitorial supply houses and direct sales channels to large service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The janitorial service market functions as a stable compounder, driven by the persistent corporate outsourcing trend for non-core functions. This fundamental demand ensures consistent, albeit moderate, growth.
For Market Incumbents: Hedge against labor force volatility by investing in advanced automated cleaning equipment and upskilling existing staff for specialized tasks. Consolidate regional operations to achieve procurement efficiencies and standardize service protocols against the threat of localized price competition. Leverage investment in specialized certifications like EPA Safer Choice to differentiate services and command premium pricing from sustainability-focused clients.
For New Entrants and Emerging Players: Capture fragmented residential and small commercial segments through mobile-first, on-demand booking platforms offering transparent pricing. Target underserved suburban markets with certified green cleaning services, leveraging digital marketing for rapid customer acquisition. The residential cleaning segment is most penetrable, offering a clear go-to-market angle through convenience and eco-friendly solutions.
For Investors and Strategic Acquirers: Facility management integrators are the most active acquirers in this space, seeking to broaden service portfolios and geographic reach. The market remains viable over the next decade, supported by hygiene mandates and corporate sustainability goals. Acquisition targets include regional specialized service groups with strong client relationships or unique technological capabilities; watch for increased M&A activity around automation providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Automated Cleaning Equipment | Enhances operational efficiency and addresses labor scarcity within commercial facilities. |
| Expand Specialized Service Bundles | Captures higher-margin opportunities in healthcare and high-security environments. |
| Develop On-Demand Digital Platforms | Disrupts traditional contract models and penetrates fragmented residential segments. |
| Secure Green Certifications | Differentiates offerings and meets corporate sustainability mandates from major clients. |
| Standardize Training Protocols Globally | Ensures consistent service quality and compliance across diverse international markets. |
Research Approach
Direct dialogue with facility managers, procurement officers, janitorial service providers, and chemical manufacturers provided primary insights. This qualitative data was validated against secondary sources including OSHA reports, EPA Safer Choice program data, and corporate financial disclosures. Bottom-up analysis of segment performance was triangulated with top-down market sizing from industry associations and government statistics.
Market volume and value projections were developed using a robust analytical framework across the analysis window. Segmentation dimensions modeled included service type, client type, technology adoption, and regional economic indicators. Compound annual growth rates were derived from historical trends and anticipated shifts in regulatory mandates. Forecast inputs included commercial real estate occupancy rates and green building certification uptake.
Labor force volatility, new regulatory mandates, and rapid technology adoption are the dominant revision risks for these forecasts. All projections reflect a specific set of assumptions documented within this report. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Contract Cleaning Services Market