
 Floor Cleaning Device Market | 2026-2036
Floor Cleaning Device Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Cleaning Device Market Insights
Autonomous navigation fused with machine vision is rewriting how floor cleaning equipment gets specified and deployed. Alfred Kärcher leverages its captive sensor development to anchor premium robotic deployments in European facility management. Nilfisk competes through specialized industrial wet-dry architectures that sustain margins in food processing plants. Tennant dominates North American commercial contracts by controlling service-channel density for ride-on scrubber fleets.
Floor cleaning devices are electromechanical systems combining brush motors, suction assemblies, solution tanks, and recovery mechanisms, typically operating at 24–48V DC in cordless configurations or three-phase AC in industrial stationary units, designed to remove particulate, liquid, and adhered contaminants from hard surface flooring. Robotic cleaners lead value creation as smart navigation with LiDAR and SLAM algorithms displaces manual operation in large-format retail and logistics warehouses, while floor scrubbers retain the deepest margin pools due to aftermarket consumables and service contracts. Vacuum cleaners represent the most mature segment with compressed pricing and brand-driven replacement cycles, whereas steam mops occupy a narrower niche constrained by surface compatibility and water quality sensitivity.
The EU Ecodesign for Sustainable Products Regulation and REACH chemical restrictions shape motor efficiency mandates and material disclosure requirements for manufacturers selling into Europe, while the US EPA Safer Choice program influences formulation chemistry for cleaning solutions bundled with equipment. The EU AI Act introduces conformity obligations for autonomous navigation systems that process environmental data in public and semi-public spaces. Stakeholders must monitor how regulatory fragmentation between energy efficiency standards and emerging AI governance frameworks affects product architecture decisions and market access timelines.
Market Dynamics
Facility management outsourcing contracts are compressing equipment replacement cycles while mandating connected-asset telemetry, forcing manufacturers to embed IoT modules and predictive maintenance software into hardware architectures previously sold as standalone mechanical systems.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Motor efficiency mandates and material recovery requirements accelerate replacement demand for legacy equipment across German, French, and Italian facility fleets.
- Logistics warehouse automation:E-commerce fulfillment centers deploy autonomous scrubbers with LiDAR navigation to maintain OSHA-compliant floor conditions across three-shift operations.
- Lithium-ion battery chemistry:Energy density improvements extend cordless runtime to 4-6 hours, eliminating tethering constraints in airport terminals and hospital corridors.
Market Restraints
- Rare earth magnet supply concentration:Brushless motor production depends on neodymium processing concentrated in Chinese refining facilities, exposing cost volatility.
- Technical limitation in carpet-edge detection:Machine vision algorithms struggle to distinguish low-contrast transitions between flooring types, requiring manual zone pre-mapping.
- REACH chemical restrictions:Formulation limits on surfactants and solvents constrain cleaning solution efficacy for industrial grease removal applications.
Strategic Opportunities
- India facility management expansion:IT park and pharmaceutical manufacturing growth in Hyderabad and Bangalore creates first-time automated cleaning procurement.
- Subscription-based fleet management:Channel partners bundle equipment, consumables, and predictive service into per-square-meter pricing for retail chains.
- EU AI Act conformity:Early certification for autonomous navigation systems in semi-public spaces creates regulatory moats against non-compliant imports.
Industry Challenges
- Mechatronics technician shortage:Maintenance of sensor-fused robotic systems requires skills spanning embedded software, optics calibration, and mechanical repair.
- ISO/TS 15066 integration complexity:Collaborative robot safety standards for human-robot workspace sharing extend deployment timelines in mixed-traffic environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Cleaning Device Market |
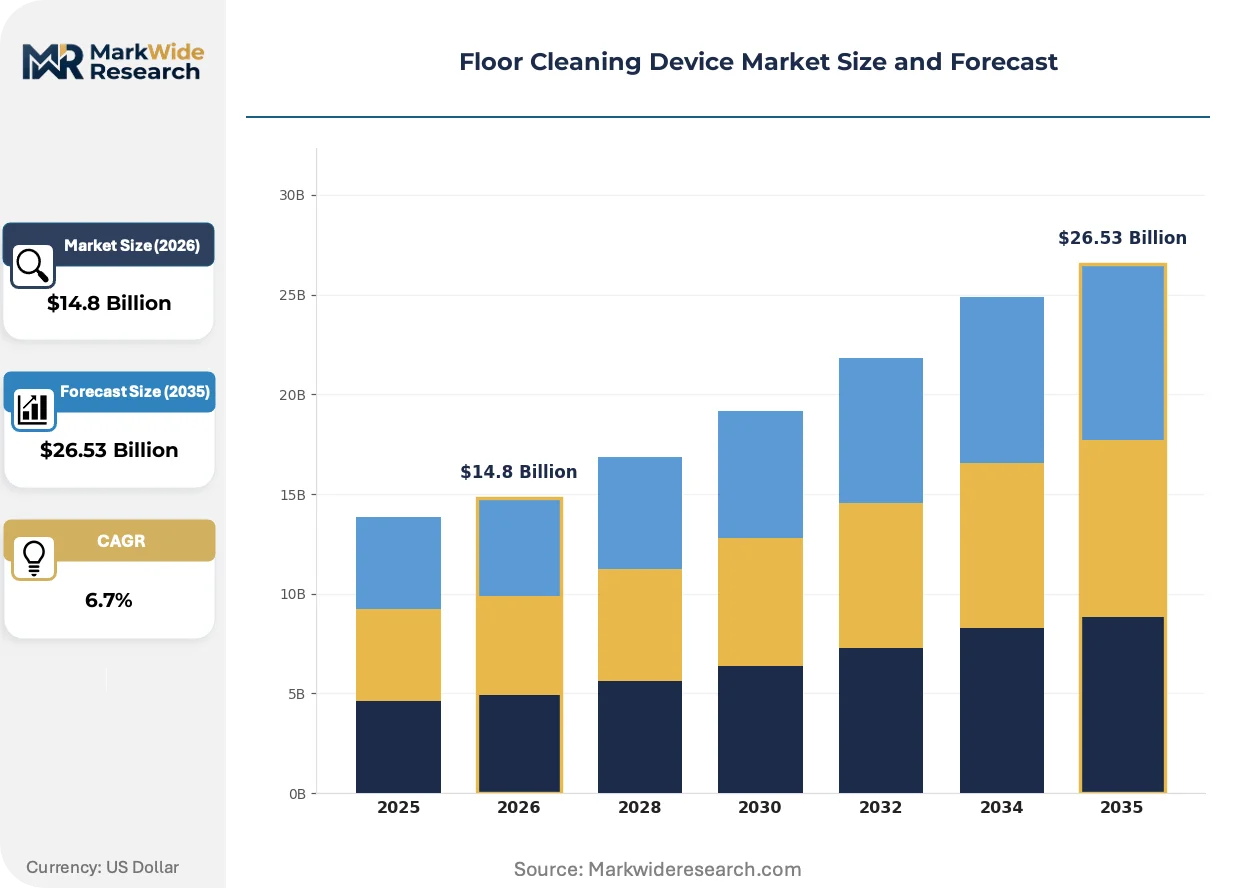
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Cleaners, Vacuum Cleaners, Steam Mops, Floor Scrubbers Technology: Smart Navigation, Ultrasonic Cleaning, Cordless, Manual End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Dyson, Bosch, Alfred Kärcher, Taski, Comac, Nilfisk, Hako, IPC Group, Tennant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Cleaning Device Market Trends and Innovations
Sensor fusion and edge computing are redistributing intelligence from centralized building management systems onto mobile cleaning platforms, creating autonomous decision-making capabilities that reduce supervisory labor requirements.
SLAM-based navigation is digitizing facility mapping workflows. Large-format retail operators deploy robotic scrubbers that generate centimeter-accurate floor plans during cleaning cycles. Real estate managers leverage this spatial data for space utilization analytics, compressing the payback period for equipment procurement.
REACH chemical disclosure requirements are reformulating bundled cleaning solutions. Manufacturers reformulate surfactant packages to eliminate SVHC candidates while maintaining degreasing performance. Food processing plants in Denmark and the Netherlands adopt these compliant formulations to preempt supply chain audit failures.
Consolidated procurement through national facility management groups is concentrating buying power. ISS and Sodexo negotiate multi-year fleet agreements specifying interoperability standards and telemetry data ownership. Equipment vendors respond with white-label hardware architectures that accommodate client-branded software overlays.
Floor Cleaning Device Market Segmentation
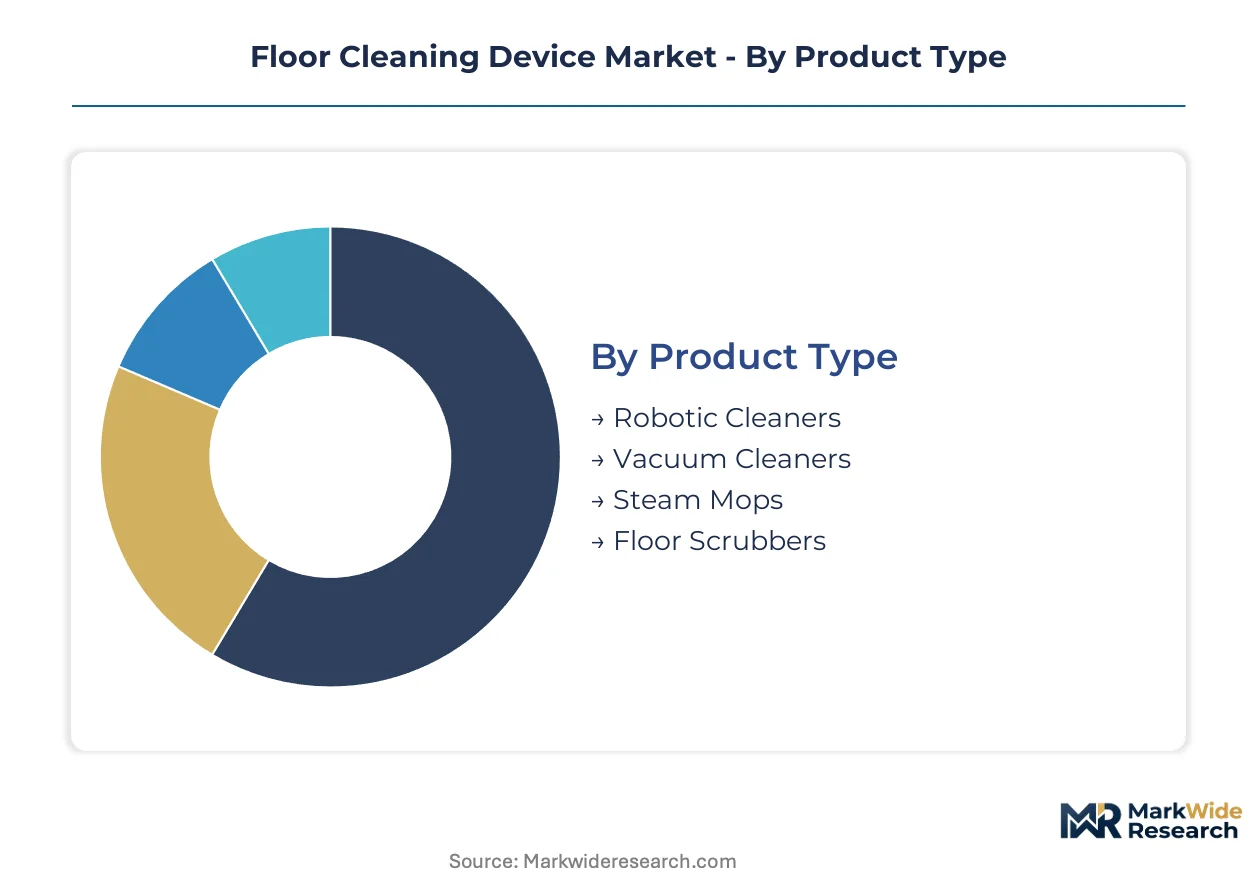
Segmentation in floor cleaning devices determines service contract structures and consumables revenue. Aftermarket intensity varies dramatically across product architectures, reshaping how manufacturers prioritize R&D and channel investment.
Product Type:
After-sales-service intensity diverges sharply across mechanical complexity tiers, with sensor-fused platforms commanding multi-year maintenance agreements while basic motor-driven units rely on replacement cycles.
- Robotic Cleaners:Autonomous platforms integrate LiDAR, SLAM algorithms, and edge-computing modules for navigation without human supervision. Logistics warehouses in Germany and the Netherlands deploy these systems across three-shift operations to maintain OSHA-compliant floor conditions, with predictive maintenance software bundled into fleet management contracts.
- Floor Scrubbers:Ride-on and walk-behind electromechanical systems combine brush motors, solution tanks, and recovery mechanisms operating at 24-48V DC. Facility management outsourcing in France and Italy drives premium procurement for connected-asset telemetry, locking in consumables and service revenue streams.
- Vacuum Cleaners:Mature motor-driven suction systems face compressed pricing and brand-driven replacement cycles in residential channels.
- Steam Mops:Heat-based sanitization units remain constrained by surface compatibility limitations and water quality sensitivity in hard-water regions.
By volume, Vacuum Cleaners leads. By growth pace, Robotic Cleaners is ahead.
Technology:
Cost tier stratification separates premium sensor-integrated platforms from price-competitive mechanical alternatives, with cordless architectures capturing mid-market displacement.
- Smart Navigation:Sensor fusion and machine vision systems redistribute intelligence from building management onto mobile platforms. EU AI Act conformity requirements for autonomous operation in semi-public spaces create regulatory moats for early-certified deployments.
- Cordless:Lithium-ion battery chemistry improvements extend runtime to 4-6 hours, eliminating tethering constraints in airport terminals and hospital corridors across Spain and Poland.
- Ultrasonic Cleaning:High-frequency vibration systems target precision contamination removal in pharmaceutical manufacturing environments.
- Manual:Unpowered or basic motorized units retain share in budget-constrained residential segments and emerging market first-time procurement.
Smart Navigation commands premium pricing. Cordless architectures are expanding most quickly across commercial retrofit installations.
End User:
Application-specific durability and certification requirements segment procurement specifications, with industrial hygiene mandates driving specification divergence from residential convenience priorities.
- Industrial:Heavy-duty architectures face REACH chemical restrictions on bundled cleaning formulations while sustaining degreasing performance for food processing and pharmaceutical manufacturing in Denmark and the Netherlands.
- Hospitality:24/7 operational requirements and brand-standard compliance drive automated cleaning program scaling with telemetry integration for ISS and Sodexo fleet agreements.
- Commercial:Office and retail deployments balance upfront capital constraints against connected-asset requirements from consolidated facility management procurement.
- Residential:Brand-driven replacement cycles and online retail price transparency dominate purchasing behavior.
Industrial users generate highest service attach rates. Hospitality is gaining share fastest through outsourcing contract expansion.
Distribution Channel:
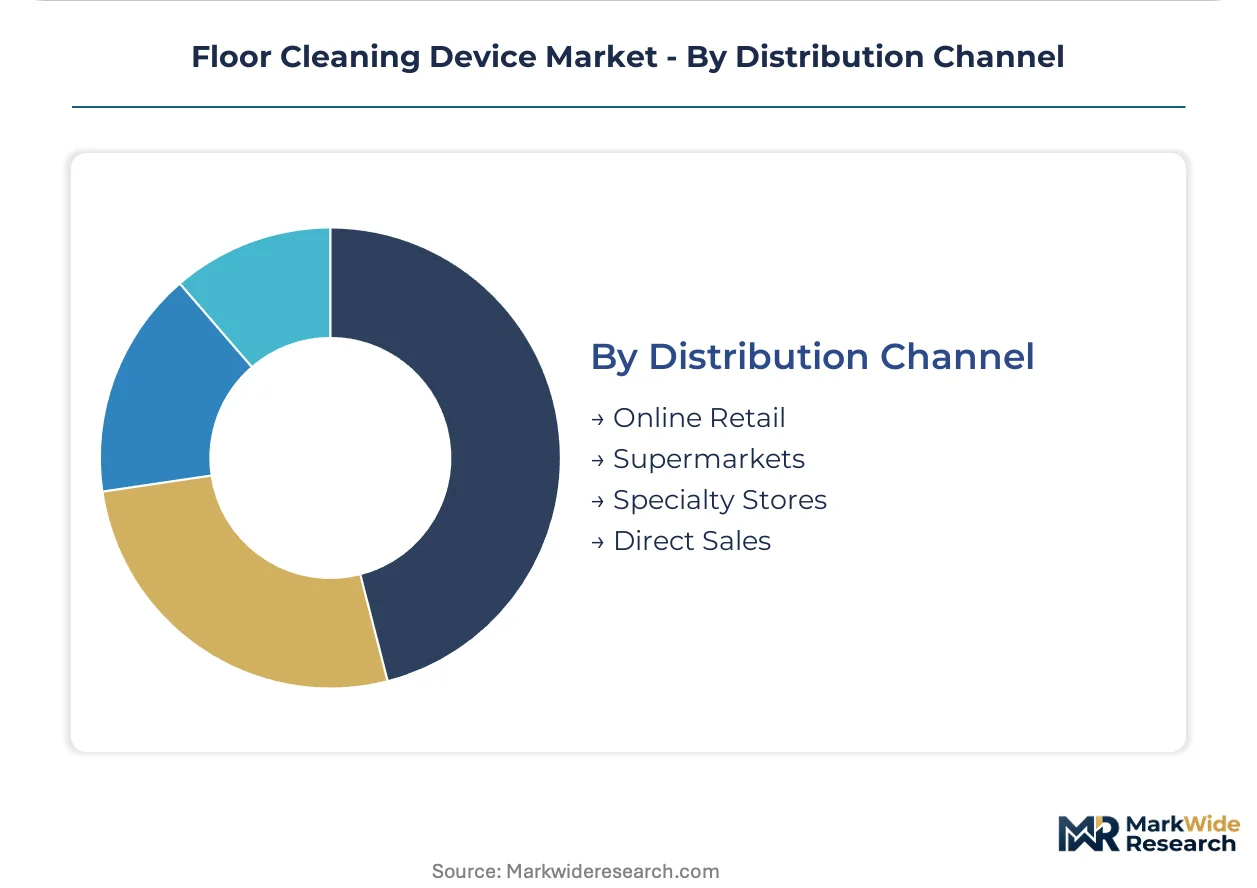
Customer-type concentration shapes channel economics, with enterprise fleet procurement consolidating through direct relationships while fragmented residential demand flows through retail intermediaries.
- Direct Sales:National facility management groups negotiate multi-year agreements specifying interoperability standards and telemetry data ownership, with vendors responding through white-label hardware architectures.
- Online Retail:E-commerce platforms capture residential vacuum and robotic cleaner volume through price transparency and replacement part availability.
- Specialty Stores:Technical consultation and demonstration requirements sustain this channel for commercial scrubber specification.
- Supermarkets:Mass-market placement dominates steam mop and entry-level vacuum distribution.
Direct Sales captures largest contract value. Online Retail is climbing the fastest on unit volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered floor cleaning equipment to facility management operators across France, Italy, and the Netherlands. This trade corridor channels premium robotic scrubbers and connected-asset systems into Western European outsourcing contracts.
Germany
Facility management outsourcing drives replacement demand for legacy motor-driven fleets. The EU Ecodesign for Sustainable Products Regulation mandates motor efficiency upgrades and material recovery compliance. Frankfurt and Munich facility clusters deploy connected scrubbers with predictive maintenance telemetry under ISS and Sodexo multi-year agreements.
United States
Logistics warehouse automation sustains three-shift scrubber deployment for OSHA-compliant floor conditions. The EPA Safer Choice program influences bundled cleaning solution formulations. Chicago and Dallas fulfillment centers integrate LiDAR-navigated autonomous units into building management workflows.
China
Domestic manufacturing scale supports cost-competitive cordless platform exports. GB standards and MIIT efficiency directives shape motor specifications for domestic procurement. Shenzhen and Shanghai industrial parks test machine-vision navigation for mixed-traffic warehouse environments.
India
IT park and pharmaceutical manufacturing expansion in Hyderabad and Bangalore creates first-time automated cleaning procurement. BIS certification requirements and PLI scheme incentives accelerate local assembly partnerships. Mumbai facility operators pilot subscription-based fleet management models.
Netherlands
Food processing hygiene mandates drive REACH-compliant formulation adoption. ECHA disclosure requirements reshape surfactant packages for industrial grease removal. Rotterdam and Eindhoven pharmaceutical plants specify compliant scrubber-solution bundles to preempt supply chain audit failures.
Floor Cleaning Device Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans German engineering houses, Danish industrial specialists, and US commercial fleet operators. Three archetypes dominate: sensor-integrated robotics developers, industrial wet-dry architecture specialists, and service-channel density controllers. Competitive moves concentrate on white-label hardware architectures for facility management interoperability and predictive maintenance software bundling.
Within the European engineering tier, Alfred Kärcher GmbH and Nilfisk anchor premium positioning through captive development ecosystems. Tennant represents North American commercial contract density. These three exemplify divergent specialization vectors: sensor fusion, industrial architecture, and service infrastructure respectively.
| Leading Market Players |
|---|
| Dyson |
| Bosch |
| Alfred Kärcher |
| Taski |
| Comac |
| Nilfisk |
| Hako |
| IPC Group |
| Tennant |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese motor manufacturing facilities is compressing brushless DC motor pricing while simultaneously constraining supplier willingness to absorb rare earth cost volatility, forcing European OEMs to renegotiate long-term supply agreements with indexed material clauses.
Pricing Analysis
Cost-plus contracts with neodymium price indexation dominate procurement agreements for brushless motor assemblies. Three-tier pricing structure across premium sensor-integrated, standard cordless, and economy manual tiers separates predictive maintenance bundles from bare equipment sales. Pricing pressure stems from lithium-ion cell cost compression in Chinese gigafactories. Residential vacuum buyers exhibit highest price sensitivity, while German facility management groups prioritize telemetry integration over unit cost.
Supply Chain Analysis
Export controls on machine vision processors under US Commerce Department restrictions limit LiDAR sensor flows to Chinese robotic cleaner manufacturers. Neodymium refining concentrates in Chinese facilities, while battery cell production clusters in South Korea and Japan. Brushless motors, lithium-ion cells, and optical sensor modules constitute critical input dependencies. Single-source vulnerability in rare earth magnet supply creates margin volatility. Distribution runs through direct sales teams for facility management contracts and e-commerce platforms for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of mechatronics technicians capable of calibrating sensor-fused robotic systems is widening the competitive moat for incumbents with captive training infrastructure, while constraining deployment velocity for asset-light challengers.
For Market Incumbents: Build regulatory moats through early EU AI Act conformity certification for autonomous navigation in semi-public spaces. Deepen backward integration into captive sensor development to secure component supply against export control disruption. Capacity addition in Indian assembly partnerships defends margin position against logistics cost inflation from Chinese sourcing. For New Entrants and Emerging Players: Establish a beachhead in Indian IT park facility management where first-time automated cleaning procurement lacks incumbent relationships. Target subscription-based fleet management models in Mumbai and Bangalore where per-square-meter pricing reduces upfront capital barriers. Partner with local BIS-certified assemblers to accelerate market entry under PLI scheme incentives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated robotic cleaner developers with multi-year predictive maintenance contracts. Long-term viability favors platforms with telemetry data ownership rights in ISS and Sodexo fleet agreements. Acquisition target archetype: mid-cap specialists with EU AI Act certification progress and white-label hardware architectures. Watch for inflection when facility management outsourcing contracts mandate connected-asset telemetry as standard specification.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Early certification creates regulatory barriers against non-compliant imports from Chinese manufacturers. |
| Predictive Maintenance Software Bundling | Telemetry integration locks in recurring revenue from ISS and Sodexo multi-year fleet agreements. |
| Indian Assembly Partnership | PLI scheme incentives and BIS certification requirements favor local production for domestic procurement. |
| White-Label Hardware Architecture | Interoperability standards from consolidated facility management groups demand client-branded software overlays. |
| REACH-Compliant Formulation Development | Surfactant reformulation eliminates SVHC candidates while maintaining degreasing performance for food processing audits. |
Research Methodology
Initial hypotheses were tested against primary input from facility management procurement directors, robotic cleaner R&D heads, aftermarket service technicians, and lithium-ion battery supply planners and refined through secondary validation against customs trade data, SEC equipment manufacturer filings, EU Ecodesign regulatory impact assessments, and BIS certification registries. Bottom-up equipment shipment data triangulated against top-down facility management outsourcing contract values.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling product type, technology tier, end-use application, and distribution channel dimensions. CAGRs derived from segment-level replacement cycle analysis and penetration rate assumptions. Forecast inputs incorporated EU Ecodesign motor efficiency mandate compliance timelines and lithium-ion energy density improvement curves.
Sensitivities concentrate around rare earth magnet price volatility, EU AI Act implementation timing, and facility management outsourcing contract renewal cycles. Forecasts reflect documented assumptions on technology adoption rates and regulatory enforcement intensity. Material shifts in Chinese export control scope or REACH SVHC candidate list expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Furniture Polish Market