
 Hand Wash Market | 2026-2036
Hand Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Wash Market Intelligence
Healthcare end-user procurement is repositioning toward higher-efficacy formulations as hospitals upgrade hand hygiene protocols. GOJO Industries leverages specialized dispensing systems to dominate clinical settings. Procter & Gamble sustains household brand strength through broad retail distribution networks. Unilever competes across multiple price tiers with regional formulation adaptations.
Hand wash comprises surfactant-based cleansing preparations, typically containing anionic or nonionic detergents at concentrations between 10% and 20% active matter, designed to remove soil, microorganisms, and lipid residues from skin surfaces. Liquid formulations lead volume due to dispenser compatibility and dosing control, while foam variants capture fastest growth through reduced water consumption per use and premium perception in hospitality settings. Antibacterial formulations command margin concentration in healthcare channels, whereas herbal positioning anchors natural-product shelf space in European pharmacy retail.
FDA monograph compliance governs active ingredient claims for antibacterial hand washes sold in the United States, while REACH registration shapes chemical disclosure and safety assessment obligations across Europe. The EPA regulates antimicrobial efficacy claims for institutional products, creating dual-track compliance burdens for manufacturers serving both consumer and professional segments. Stakeholders must monitor evolving preservative restrictions under ECHA review and adapt formulation pipelines accordingly.
Market Dynamics
Healthcare procurement mandates are compressing formulation approval cycles as hospitals demand faster pathogen kill claims under tightened Joint Commission accreditation standards. Institutional buyers now require documented efficacy against emerging resistant strains, forcing reformulation investments across supply chains.
Growth Catalysts
- REACH registration deadlines:ECHA's 2026 substance evaluation timeline is accelerating disclosure investments among European manufacturers, creating first-mover advantages for compliant suppliers in pharmacy retail channels.
- Hospital-acquired infection protocols:US acute care facilities are expanding automated dispenser deployments to achieve 90% hand hygiene compliance targets under CDC guidelines.
- Surfactant concentration optimization:Advanced alkyl polyglucoside blends at 12-15% active matter are delivering superior lipid removal with reduced dermal irritation, expanding professional segment acceptance.
Market Restraints
- Palm kernel oil volatility:Primary fatty acid feedstock prices swing with Malaysian and Indonesian export policy shifts, compressing margin stability for surfactant-dependent producers.
- EPA dual-registration burden:Antimicrobial efficacy claims require separate institutional and consumer pathway approvals, extending time-to-market by 18-24 months for cross-segment launches.
- Preservative restriction cascade:ECHA's ongoing methylisothiazolinone review is forcing reformulation of established rinse-off products without equivalent cost-effective alternatives.
Strategic Opportunities
- India tier-2 hospital expansion:Government health infrastructure programs are creating procurement entry points for antibacterial formulations in 400+ district hospitals under Ayushman Bharat.
- Foam-dispenser retrofit kits:Hospitality chains are converting liquid systems to reduce per-use water consumption by 40%, opening aftermarket hardware revenue streams.
- ISO 16128 natural origin certification:European pharmacy buyers are prioritizing verifiable botanical content claims, differentiating premium shelf positioning.
Industry Challenges
- Microbiologist talent scarcity:Formulation teams lack sufficient expertise in preservative efficacy testing under evolving compendial standards, delaying stability validation.
- Automated line conversion costs:Foam variant production requires dedicated aeration equipment incompatible with legacy liquid filling infrastructure.
- FDA monograph alignment:Pending benzalkonium chloride concentration limits are forcing parallel formulation tracks pending final rule publication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Wash Market |
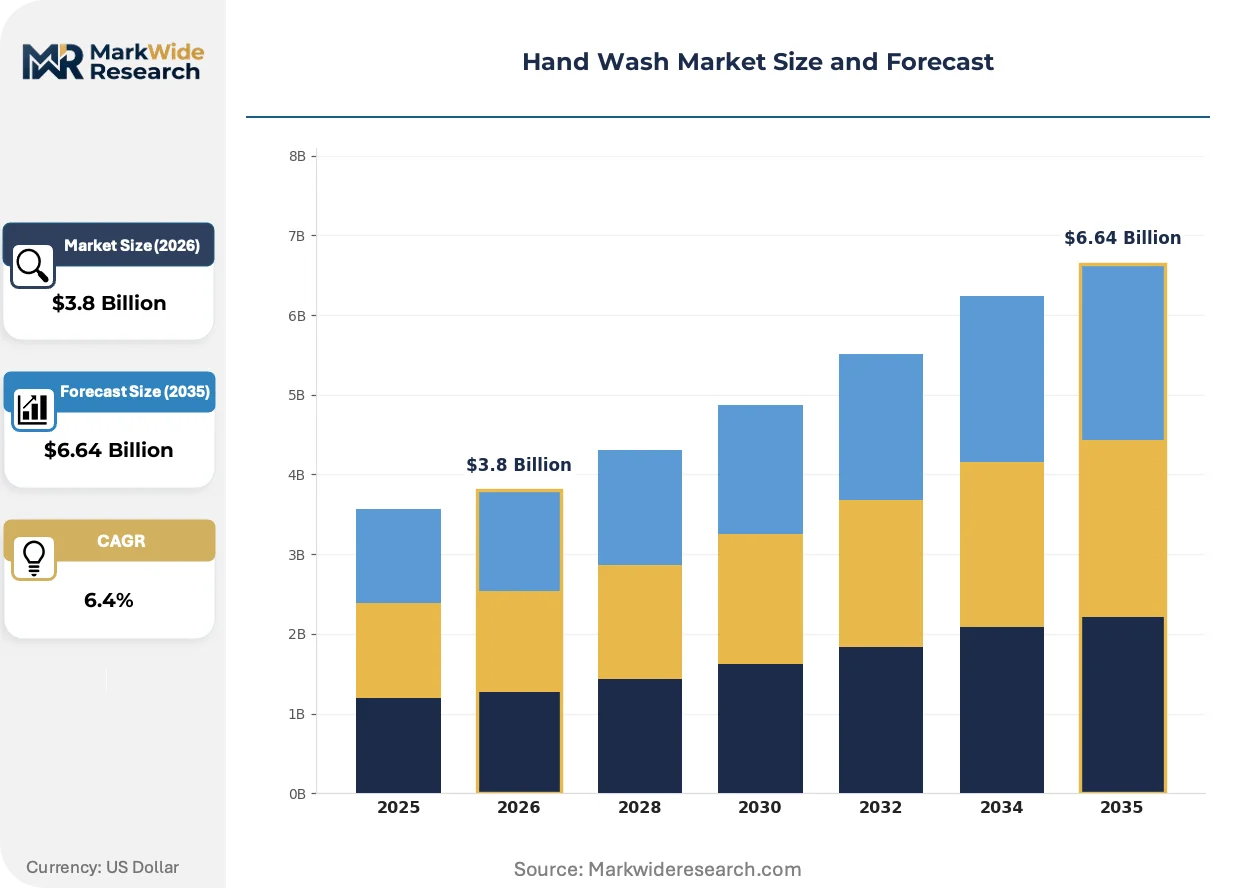
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Foam, Spray Formulation: Alcohol-Based, Non-Alcoholic, Antibacterial, Herbal Distribution Channel: Online, Supermarket, Pharmacy, Convenience Store End User: Household, Healthcare, Hospitality, Educational |
| Companies Covered | Colgate-Palmolive Company, GOJO Industries, Inc., Procter & Gamble Company, 3M Company, Henkel AG & Co. KGaA, Unilever PLC, Johnson & Johnson, Kimberly-Clark Corporation, Reckitt Benckiser Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Wash Market Strategic Shifts & Innovations
Formulation science is pivoting toward waterless and rinse-free modalities as healthcare settings confront infrastructure constraints. Dispensing hardware is converging with IoT telemetry to generate compliance analytics. Regulatory fragmentation is accelerating regional specialization in product development pipelines.
Alcohol-free quaternary ammonium formulations are consolidating institutional preference as healthcare facilities seek alternatives to flammable ethanol bases in surgical environments. Long-term care operators are adopting these chemistries at twice the pace of acute care hospitals. The technology is consolidating procurement specifications around non-flammable storage and broader surface compatibility.
REACH Article 33 disclosure obligations are reshaping supply chain transparency requirements for surfactant suppliers across European manufacturing. Downstream formulators must now document full substance composition above 0.1% w/w concentration thresholds. Professional segment products face the steepest compliance cost escalation as institutional buyers demand batch-level traceability.
Direct-to-facility e-procurement platforms are displacing traditional distributor relationships among US hospital systems exceeding 200 beds. Group purchasing organizations are ceding volume allocation authority to individual facility supply chain managers. This channel shift is most pronounced in the Southeast and Southwest regions where health system consolidation has concentrated buying power.
Hand Wash Market Segmentation
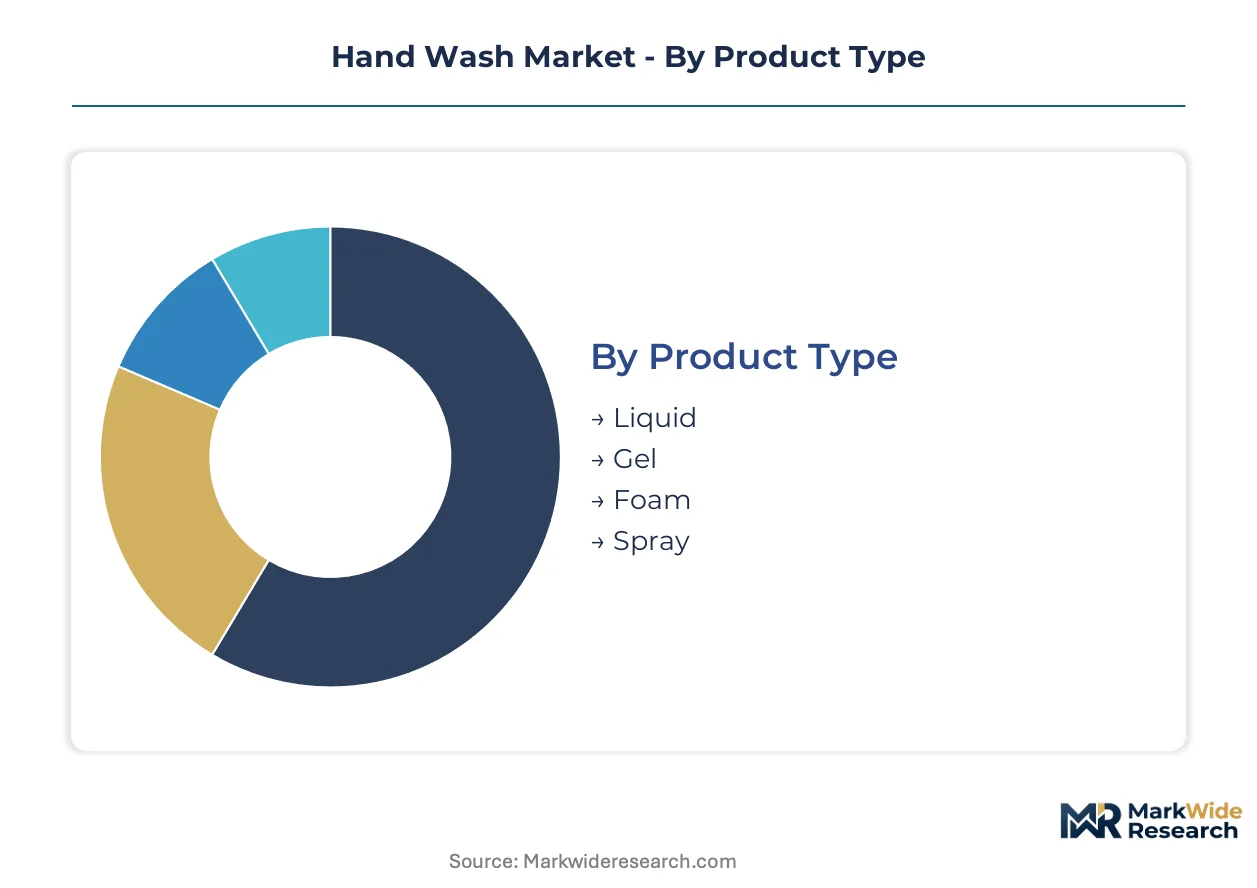
Hand wash segmentation reflects divergent compliance burdens across institutional and consumer pathways. FDA monograph alignment governs antibacterial claims in healthcare procurement, while REACH registration shapes surfactant disclosure obligations in European pharmacy retail. Manufacturers must maintain parallel formulation tracks to serve regulated professional segments alongside mass-market channels.
Product Type:
FDA monograph compliance for antibacterial claims applies uniformly across all physical forms, though dispenser compatibility requirements create divergent certification timelines for institutional buyers.
- Liquid:Surfactant-based preparations at 10-20% active matter dominate institutional procurement through compatibility with sensor-activated wall-mounted dispensers. Healthcare facilities in the United States specify liquid formats for 90% hand hygiene compliance tracking under CDC guidelines, with GOJO Industries and Ecolab capturing volume through specialized dispensing hardware contracts.
- Foam:Aerated formulations reduce per-use water consumption by approximately 40% compared to liquid equivalents, driving hospitality chain adoption for sustainability credentialing. Southeast Asian hotel operators in Thailand and Vietnam are retrofitting liquid systems to capture operational cost reductions alongside premium guest perception.
- Gel:Thickened rheology targets portable and travel formats where spill resistance outweighs dosing precision requirements.
- Spray:Aerosolized delivery suits rapid-application environments without dedicated washing infrastructure, though EPA registration extends approval cycles for antimicrobial variants.
Liquid sits at the top of the volume ranking, with foam climbing the fastest.
Formulation:
Cost tier stratification separates premium-positioned chemistries from commodity surfactant bases, with certification burden intensity determining margin architecture.
- Antibacterial:Quaternary ammonium and benzalkonium chloride formulations command institutional premium pricing through documented efficacy against resistant pathogens. US acute care facilities now mandate kill-claim documentation under tightened Joint Commission accreditation standards, compressing supplier qualification timelines.
- Herbal:Botanical-derived surfactants with ISO 16128 natural origin certification anchor European pharmacy retail positioning. German and French buyers prioritize verifiable ingredient provenance, with alkyl polyglucoside blends from coconut and corn glucose feedstocks gaining shelf space.
- Alcohol-Based:Ethanol and isopropanol formulations face flammability storage restrictions in surgical environments, limiting penetration outside consumer channels.
- Non-Alcoholic:Synthetic surfactant bases without antimicrobial actives serve cost-sensitive household volume through supermarket and convenience store distribution.
Antibacterial formulations capture the steepest margin tier, with herbal variants expanding most quickly in European premium channels.
Distribution Channel:
Customer type concentration determines channel infrastructure requirements, with institutional buyers demanding batch-level traceability unavailable through traditional retail.
- Pharmacy:European pharmacy retail enforces REACH Article 33 disclosure above 0.1% w/w concentration thresholds, creating compliance barriers for non-specialized suppliers. French and Italian pharmacy chains now require full substance composition documentation for surfactant-based rinse-off products.
- Online:Direct-to-facility e-procurement platforms displace distributor relationships among US hospital systems exceeding 200 beds, with group purchasing organizations ceding volume allocation authority to individual supply chain managers.
- Supermarket:Mass-market retail moves volume through broad SKU distribution, with private-label capture concentrated in standard surfactant formulations without antimicrobial claims.
- Convenience Store:Impulse-purchase formats favor travel-sized gel and spray variants with minimal packaging complexity.
Pharmacy leads value concentration, with online channels gaining share fastest in institutional procurement.
End User:
Application environment dictates performance specification intensity, from basic soil removal in household settings to pathogen kill-claim documentation in surgical suites.
- Healthcare:Acute care hospitals and long-term care operators require dual-track EPA registration for institutional antimicrobial claims alongside FDA monograph alignment for cross-segment launches. US facilities face 18-24 month approval extensions when pursuing both consumer and professional pathway certifications.
- Household:Mass-market volume concentrates in standard surfactant formulations through retail distribution networks, with Procter & Gamble and Unilever competing across price tiers through regional formulation adaptations.
- Hospitality:Hotel and foodservice operators prioritize foam-dispenser compatibility for water consumption reduction alongside guest-facing sustainability messaging.
- Educational:School districts and university systems specify bulk liquid formats through centralized procurement, with cost per use dominating vendor selection criteria.
Healthcare commands the premium tier, with hospitality expanding most quickly through sustainability-driven retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers seek jurisdictions with streamlined compliance pathways for surfactant-based formulations. REACH registration costs in Europe are pushing some volume toward Asian production bases, though proximity to end-markets remains the dominant location factor.
United States
Hospital-acquired infection prevention programs drive institutional procurement concentration. FDA monograph compliance governs antibacterial claims, with EPA dual-registration extending approval cycles for cross-segment products. Cincinnati and Chicago anchor manufacturing clusters where GOJO Industries and Ecolab maintain specialized dispensing system production.
Germany
European pharmacy retail prioritizes ISO 16128 natural origin certification for botanical formulations. ECHA substance evaluation deadlines accelerate disclosure investments among domestic manufacturers. The Rhine-Ruhr industrial corridor concentrates surfactant production capacity serving downstream formulators.
China
Domestic hospital infrastructure expansion under Healthy China 2030 generates procurement volume for antibacterial hand wash. NMPA registration requirements align with international GMP standards for institutional-grade products. Guangdong province hosts contract manufacturing clusters supplying Southeast Asian hospitality chains.
India
Ayushman Bharat district hospital expansion creates entry points for antibacterial formulations across 400+ facilities. BIS standards govern surfactant quality specifications for institutional procurement. Maharashtra and Gujarat concentrate manufacturing capacity serving domestic pharmacy and modern trade channels.
Brazil
ANVISA registration requirements shape formulation adaptation for Latin American market entry. Hospital infection control protocol upgrades drive professional segment demand in São Paulo and Rio de Janeiro. Southeast industrial zones concentrate import substitution manufacturing for surfactant-dependent products.
Hand Wash Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers retrofit liquid lines for foam-variant production. The market structures around three tiers: multinational consumer goods conglomerates, specialized institutional hygiene suppliers, and regional pharmacy-channel specialists. Consolidation pressures intensify as compliance costs escalate and automated dispensing contracts lock in multi-year procurement relationships. Geographic expansion and portfolio diversification represent the two most frequent competitive moves.
Among diversified consumer goods conglomerates, Procter & Gamble Company and Unilever PLC occupy positions spanning household retail across multiple price tiers. GOJO Industries, Inc. exemplifies the specialized institutional supplier archetype, anchoring clinical settings through integrated dispensing hardware and formulation systems. These three entities represent distinct strategic postures: broad retail distribution, institutional contract depth, and hybrid multi-channel presence.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| GOJO Industries, Inc. |
| Procter & Gamble Company |
| 3M Company |
| Henkel AG & Co. KGaA |
| Unilever PLC |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Reckitt Benckiser Group plc |
| Others |
Cost & Logistics Intelligence
Malaysian palm kernel oil futures volatility cascades through surfactant production costs into tiered pricing architectures for hand wash formulations. Feedstock price swings compress margin stability for producers dependent on fatty acid derivatives, forcing differentiation through certification grade and channel positioning to sustain profitability across healthcare and consumer segments.
Pricing Analysis
Distributor margins in institutional procurement compress pricing flexibility for antibacterial formulations serving US hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered clinical grades from mass-market surfactant bases, with ISO 16128-certified botanical variants commanding shelf-space premiums in European pharmacy retail. Price differentiation stems from certification burden intensity and volume scale, with procurement managers at consolidated health systems exhibiting lowest sensitivity due to compliance mandate rigidity. Cost compression in standard surfactant tiers is intensifying because private-label supermarket capture concentrates volume in undifferentiated formulations.
Supply Chain Analysis
Direct-to-facility e-procurement channels handle hyperscale demand from US hospital systems exceeding 200 beds, displacing traditional distributor relationships. Manufacturing concentration spans Malaysia and Indonesia for palm-derived fatty acid feedstocks, Germany for alkyl polyglucoside surfactant synthesis, and China for contract packaging serving Southeast Asian hospitality chains. Formulation production rests on palm kernel oil derivatives, coconut-derived glucosides, and quaternary ammonium biocide imports. Single-source vulnerability in Malaysian feedstock supply creates exposure to export policy shifts. Distribution runs through specialized institutional hygiene suppliers for healthcare, pharmacy wholesale for European retail, and mass-market retail networks for household volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration cost differentials between European and Asian manufacturing bases create geographic-arbitrage opportunities for surfactant-dependent producers seeking compliance efficiency.
For Market Incumbents: Anticipate preservative restriction cascades under ECHA review by accelerating reformulation pipelines for methylisothiazolinone alternatives before compliance deadlines tighten. Defensive consolidation through backward integration into captive surfactant production in Malaysia or Indonesia mitigates palm kernel oil price volatility exposure. Channel control through automated dispenser hardware contracts locks in multi-year procurement relationships against emerging institutional competitors. For New Entrants and Emerging Players: Tier-2 district hospitals under India's Ayushman Bharat program represent an underserved buyer archetype with concentrated procurement entry points across 400+ facilities. White-space targets include foam-dispenser retrofit kits for Southeast Asian hospitality chains seeking water consumption reductions, and ISO 16128-certified botanical formulations for German and French pharmacy retail prioritizing verifiable ingredient provenance. A direct-to-facility e-procurement go-to-market angle bypasses established distributor relationships in consolidated US health systems. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized institutional hygiene suppliers possessing integrated dispensing hardware and formulation capabilities. Long-term viability across the projection horizon favors suppliers with dual-track FDA monograph and EPA registration expertise serving cross-segment healthcare demand. Acquisition target archetypes include regional pharmacy-channel specialists with REACH compliance infrastructure and established botanical certification pipelines. The signal to watch as inflection indicator is ECHA substance evaluation timeline acceleration driving disclosure investment requirements and compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive palm kernel oil sourcing in Malaysia insulates margin stability from export policy volatility. |
| Foam-Dispenser Retrofit Kit Development | Hospitality chain adoption in Thailand and Vietnam captures 40% water consumption reduction messaging. |
| ISO 16128 Certification Investment | European pharmacy retail prioritization in Germany and France secures premium shelf positioning. |
| Direct-to-Facility E-Procurement Platform Launch | US hospital systems exceeding 200 beds bypass group purchasing organization volume allocation control. |
| Dual-Track Regulatory Registration | Parallel FDA monograph and EPA pathway alignment enables cross-segment antibacterial claim deployment. |
Research Approach
Bottom-up healthcare procurement modeling reconciled against top-down surfactant production tracking forms the analytical core of this study. Primary interviews with hospital supply chain managers, pharmacy retail category buyers, contract manufacturing executives, and ECHA regulatory affairs specialists combined with secondary validation from FDA monograph filings, REACH registration databases, customs trade records, and hospital procurement platform disclosures. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map surfactant concentration optimization, dispenser hardware deployment rates, and formulation certification timelines across product type, end-user segment, and regional regulatory cluster dimensions. CAGRs derive from modeled adoption curves for foam variants, institutional compliance mandate intensification, and channel shift velocities. Forecast inputs include palm kernel oil price trajectory assumptions, ECHA substance evaluation timelines, and hospital infrastructure expansion program procurement schedules.
Underlying measurement precision varies by segment; healthcare institutional procurement carries tighter precision than hospitality retrofit cycles due to documented contract visibility. Forecasts reflect assumptions regarding regulatory deadline adherence, feedstock price stability, and channel migration velocity. Periodic stress-testing of base assumptions is recommended against preservative restriction cascades, Malaysian export policy shifts, and health system consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Fabric Care Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Fabric Freshener Market