
 Carpet Cleaning Products Market | 2026-2036
Carpet Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Cleaning Products Market Analysis
Plant-derived surfactant chemistry is consolidating its position against petroleum-based alternatives in carpet cleaning formulations. BISSELL Inc. leverages its captive supply of enzymatic pretreatment solutions to protect margin pools in the residential segment. Alfred Kärcher SE & Co. KG anchors its European installed base with professional extraction equipment bundled with proprietary detergent chemistry. The Clorox Company competes through retail shelf dominance and private-label manufacturing scale for institutional buyers.
Carpet cleaning products encompass liquid, powder, foam, and shampoo formulations designed to suspend soil, neutralize odors, and restore pile appearance through mechanical agitation and extraction, with pH typically ranging from 6.5 to 10 depending on fiber compatibility and soil alkalinity. Their primary commercial purpose spans routine maintenance in hospitality, healthcare, and residential settings where foot traffic deposits particulate and organic matter into textile substrates. Liquid concentrates now lead volume in the product type dimension because dilution-at-use reduces freight cost and packaging waste for commercial fleets. Enzymatic formulations represent the fastest-expanding formulation category as facilities managers specify biodegradable actives to meet procurement scorecards tied to LEED and BREEAM certifications. The residential end-user segment remains mature with stable replacement demand, while institutional buyers concentrate margin in multi-year supply contracts for K-12 districts and hospital networks.
The EPA Safer Choice program and state-level VOC regulations in California shape permissible solvent content and disclosure requirements for products sold into the United States market. REACH registration obligations in Europe restrict certain quaternary ammonium compounds and mandate full supply chain communication on Substances of Very High Concern. Stakeholders must monitor pending amendments to the EU Detergents Regulation and emerging per- and polyfluoroalkyl substance restrictions that could force reformulation of stain-resistant carpet treatments bundled with cleaning protocols.
Market Dynamics
Commercial hospitality chains now drive bulk procurement of concentrated formulations, compressing supplier margins while rewarding scale chemistry providers with captive fleet contracts.
Growth Catalysts
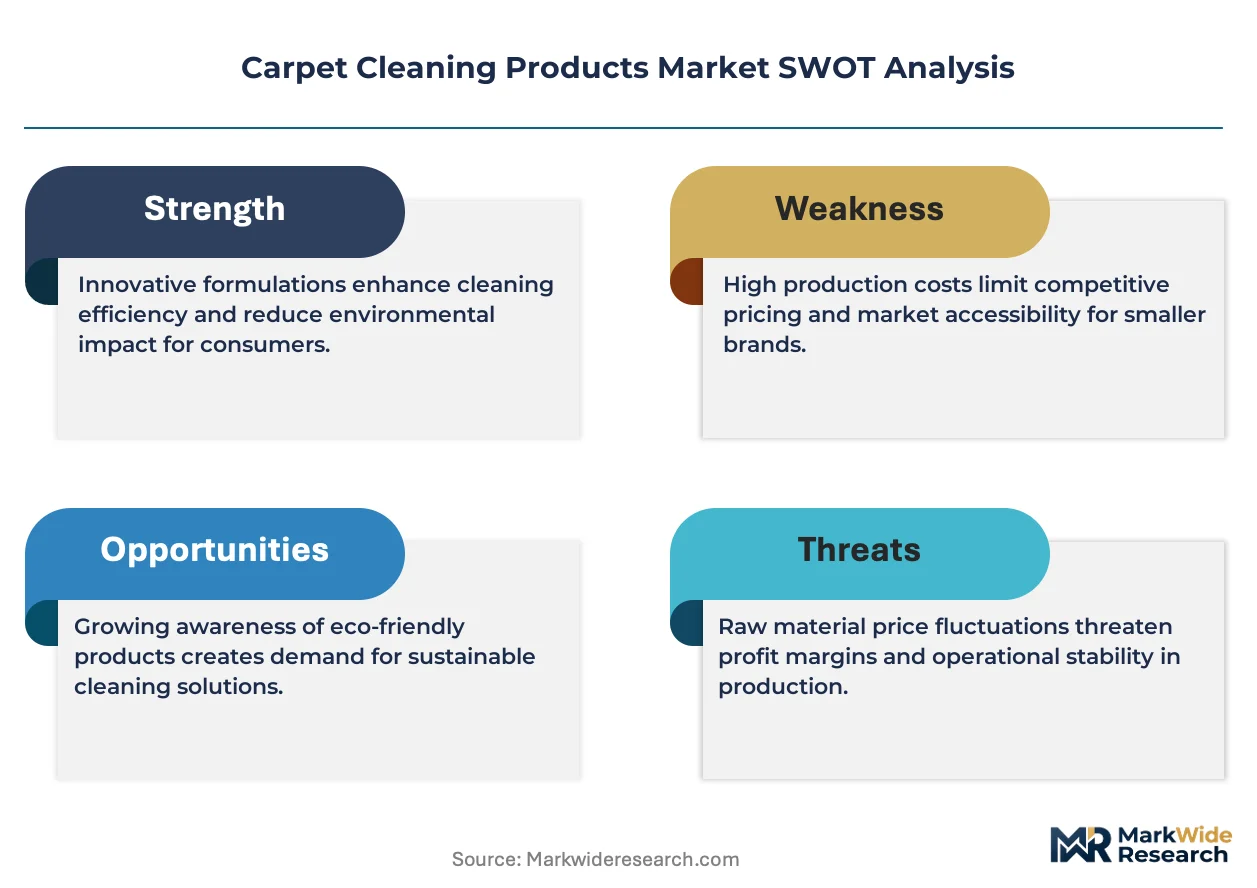
- EPA Safer Choice program:Tightened ingredient disclosure rules in the United States force legacy reformulation toward biodegradable actives, expanding addressable market for certified low-residue protocols.
- Enzymatic chemistry:Facilities managers specify biodegradable actives to meet procurement scorecards tied to LEED and BREEAM certifications, accelerating specification in hospital and K-12 networks.
- China facility management sector:Certified cleaning protocols now penetrate tier-one city commercial real estate, creating concentrated demand for extraction equipment bundled with compliant detergents.
Market Restraints
- Petroleum-derived surfactant cost volatility:Crude-linked feedstock pricing squeezes margin pools for manufacturers maintaining dual petroleum and plant-derived formulation lines.
- REACH registration obligations:European restrictions on quaternary ammonium compounds force supply chain requalification, extending product launch timelines by 12-18 months.
- Per- and polyfluoroalkyl substance restrictions:Pending amendments to EU frameworks threaten stain-resistant carpet treatment bundles, risking revenue displacement in professional cleaning adjacencies.
Strategic Opportunities
- German healthcare networks:Underpenetrated sterilization-grade carpet maintenance protocols create white space for enzymatic formulations meeting hospital infection control standards.
- California state-level VOC regulations:Stricter solvent content limits than federal baselines reward early reformulators with preferential retail placement and institutional procurement preference.
- Direct-to-fleet digital platforms:Dilution-at-use concentrate ordering via integrated facility management software disintermediates traditional distribution, capturing recurring revenue streams.
Industry Challenges
- Formulation chemist talent scarcity:Cross-functional expertise spanning surfactant science, fiber compatibility testing, and regulatory dossier preparation concentrates in legacy European and North American labor markets.
- Dual-certification timeline compression:Simultaneous EPA Safer Choice and EU Detergents Regulation compliance requires parallel toxicology studies, straining R&D bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Cleaning Products Market |
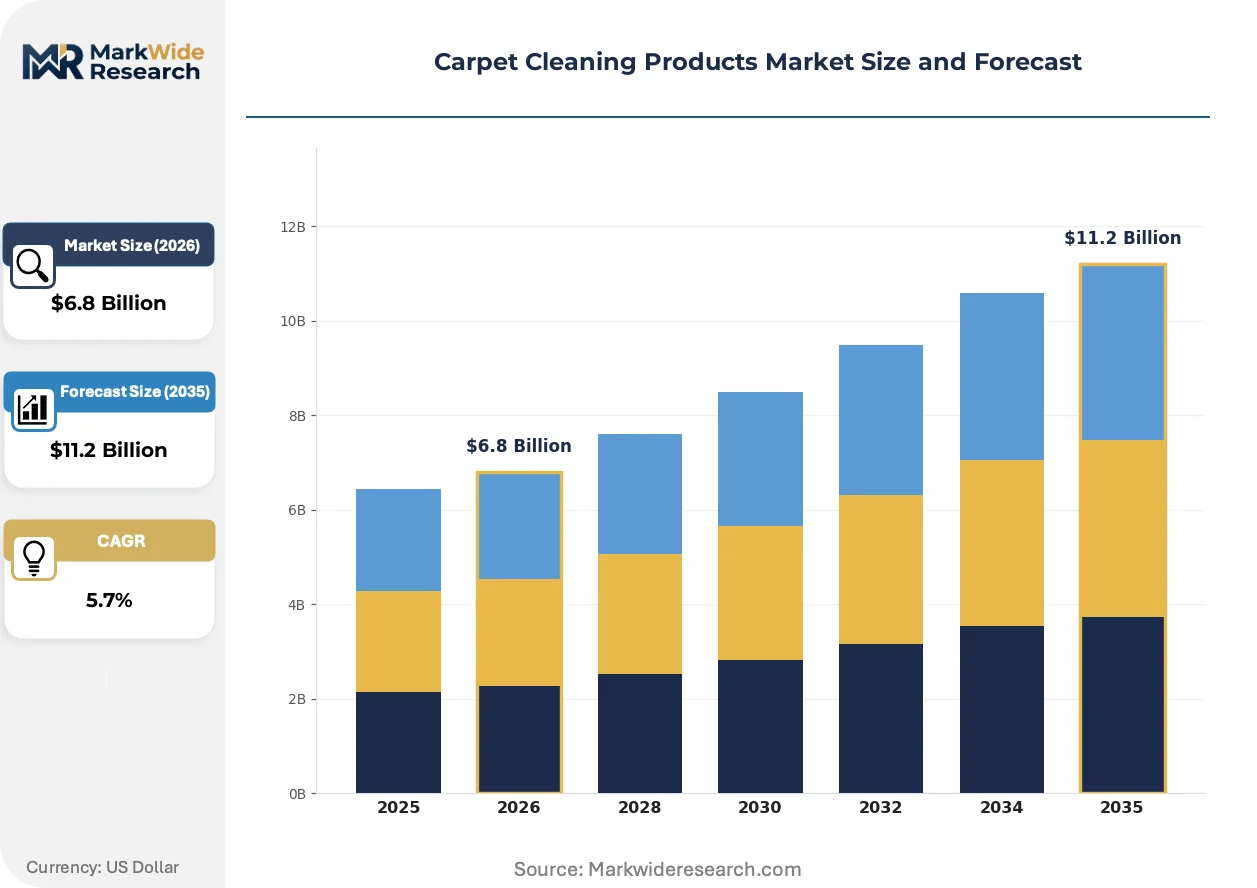
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Powder, Liquid, Foam Formulation: Enzymatic, Biodegradable, Synthetic, Organic End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | BISSELL Inc., Techtronic Industries Co. Ltd., The Clorox Company, Zep Inc., Tennant Company, Reckitt Benckiser Group plc, Alfred Kärcher SE & Co. KG, Sprayway Inc., Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Cleaning Products Market Emerging Trajectories
Formulation chemistry and procurement infrastructure are converging to reward transparency and concentrated delivery systems over legacy dilute-ready retail packaging.
Electrochemical activation systems for on-site generation of cleaning agents are electrifying capital deployment patterns in commercial cleaning fleets. Hospitality chains with 500-plus property portfolios pilot these units to eliminate concentrate shipping and storage liability. The technology is electrifying competitive positioning around total cost of ownership rather than per-gallon chemistry pricing.
REACH registration obligations for Substances of Very High Concern now mandate full supply chain communication on quaternary ammonium compounds used in antimicrobial carpet treatments. European formulators face reformulation deadlines or withdrawal of legacy actives from professional product lines. German institutional buyers accelerate substitution toward enzymatic alternatives ahead of enforcement windows.
Facility management scorecards now weight environmental certification directly in vendor selection criteria, displacing historical price-per-gallon benchmarking. Hospital networks and K-12 districts unbundle cleaning chemistry procurement from equipment leases to capture LEED and BREEAM compliance credits. This behavioral pivot concentrates contract value with suppliers offering certified low-residue protocols in United States coastal metropolitan markets.
Carpet Cleaning Products Market Segmentation
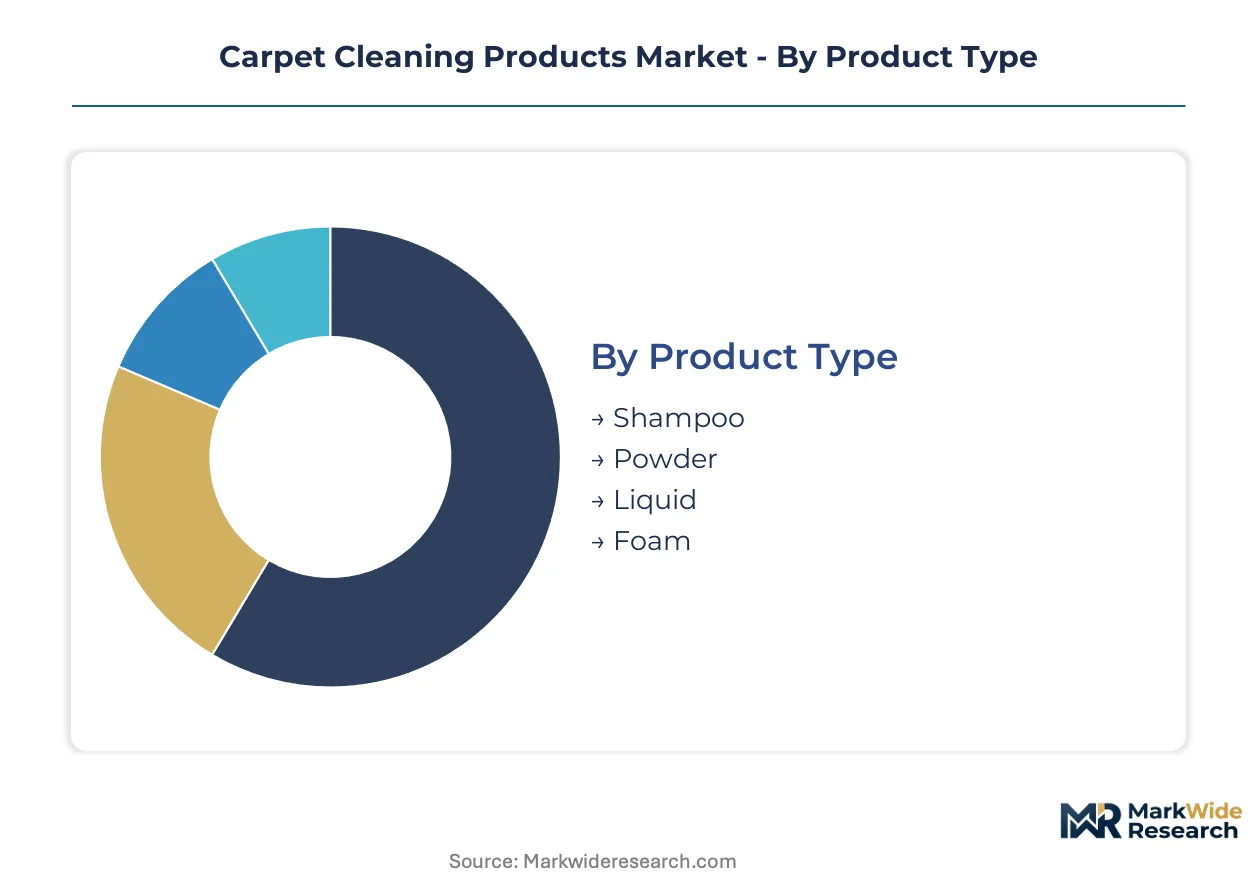
Procurement patterns in carpet cleaning products diverge sharply across formulation chemistry, packaging format, and buyer sophistication. Facility managers, hospitality chains, and residential consumers each prioritize distinct performance attributes and compliance certifications when selecting products.
Product Type:
Commercial fleets prioritize total cost of ownership over per-unit pricing, driving divergence between concentrate and ready-to-use formats.
- Liquid:Concentrated formulations dominate commercial procurement through dilution-at-use economics that reduce freight expenditure and packaging waste. Hospitality chains with multi-property portfolios specify liquid concentrates to standardize fleet-wide chemistry protocols.
- Shampoo:High-foam formulations engineered for rotary brush agitation retain installed base in residential rental equipment channels. Consumer preference for visible cleaning action sustains demand in North American retail despite slower extraction times.
- Powder:Dry-crystal absorbents target moisture-sensitive natural fiber applications in heritage hospitality and museum conservation settings.
- Foam:Low-moisture encapsulation chemistry penetrates quick-dry maintenance contracts in commercial office towers with restricted downtime windows.
Volume sits with Liquid concentrates; growth tilts toward Foam encapsulation systems.
Formulation:
Regulatory pressure on volatile organic compounds and disclosure requirements is restructuring competitive advantage toward certified biodegradable actives.
- Enzymatic:Protein- and cellulase-based actives digest organic soil loads without petroleum-derived surfactants. Hospital networks in Germany and K-12 districts in the United States specify enzymatic formulations to meet infection control scorecards and LEED procurement credits.
- Biodegradable:Surfactant chains meeting OECD 301B ready biodegradability standards capture institutional contracts with mandatory environmental compliance clauses.
- Synthetic:Quaternary ammonium compound blends face REACH registration pressure in Europe but retain cost advantage in price-sensitive commercial segments.
- Organic:Plant-derived solvent systems from citrus terpenes and corn-based alcohols command premium positioning in residential channels with ingredient transparency preferences.
Procurement concentrates on Biodegradable certified lines; specification velocity favors Enzymatic chemistry.
End User:
Contract structure and compliance burden separate institutional buyers from discretionary residential purchasing.
- Commercial:Hospitality chains and facility management companies negotiate multi-year supply agreements with chemistry bundled into equipment service contracts. California state-level VOC regulations and EPA Safer Choice certification requirements filter supplier pools.
- Institutional:Hospital networks and educational districts unbundle cleaning procurement from equipment leases to capture standalone compliance credits. German healthcare procurement now weights sterilization-grade carpet maintenance protocols in vendor evaluation.
- Residential:Replacement demand tied to seasonal deep-cleaning cycles and pet ownership patterns sustains stable volume through retail and e-commerce channels.
- Industrial:Manufacturing facilities with heavy particulate loading specify alkaline extraction chemistry for periodic restoration of high-traffic textile flooring.
Margin pools concentrate in Institutional multi-year contracts; volume expansion tracks Commercial fleet consolidation.
Distribution Channel:
Channel selection determines access to compliance documentation, technical support, and replenishment velocity.
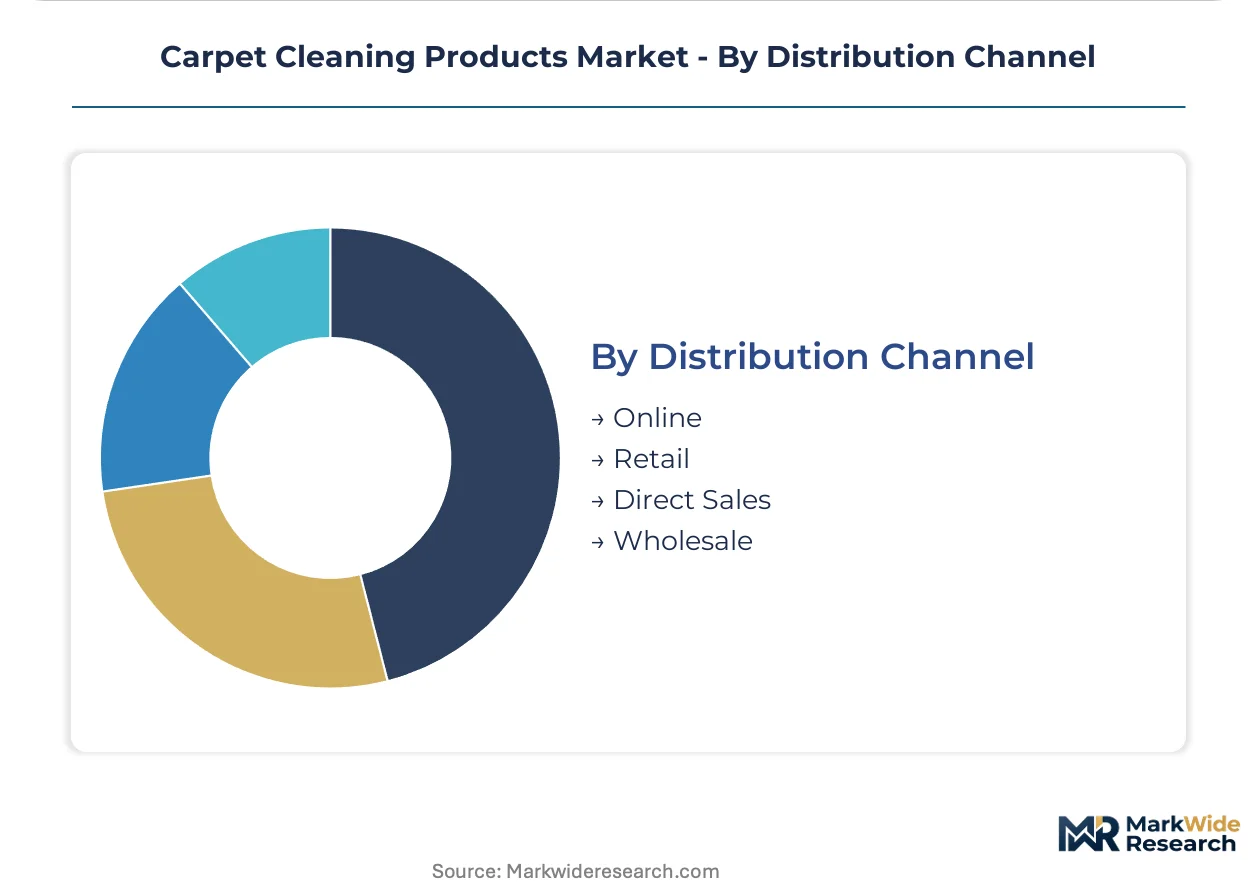
- Direct Sales:Manufacturer field teams serve hospitality chains and healthcare networks with customized dilution systems and regulatory dossier support. Electrochemical activation equipment pilots bypass traditional chemical distribution entirely.
- Wholesale:Janitorial supply distributors aggregate fragmented commercial demand and provide local inventory buffers for emergency restoration calls.
- Online:E-commerce platforms capture residential replenishment and small commercial trial orders with subscription models for concentrate refills.
- Retail:Mass merchandisers and home improvement chains dominate residential volume through seasonal promotional cycles and private-label placement.
Revenue gravity centers on Direct Sales for institutional accounts; Online channels gain share in mid-market commercial procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shanghai and Shenzhen concentrate contract manufacturing for export-oriented carpet cleaning chemistry, while domestic facility management procurement accelerates in tier-one commercial corridors.
United States
Hospitality chains with 500-plus property portfolios drive bulk concentrate procurement through integrated facility management platforms. The EPA Safer Choice program tightens ingredient disclosure thresholds for surface-care chemistry sold into institutional channels. California's South Coast Air Quality Management District enforces VOC limits stricter than federal baselines, rewarding early reformulators with preferential retail placement in Los Angeles and San Diego metropolitan markets.
Germany
Healthcare networks in Bavaria and North Rhine-Westphalia specify sterilization-grade carpet maintenance protocols to meet hospital infection control standards. REACH registration obligations for quaternary ammonium compounds force supply chain requalification timelines extending 12-18 months. The Stuttgart industrial corridor hosts formulation R&D clusters where enzymatic chemistry specialists serve automotive manufacturing facility contracts.
China
Certified cleaning protocols penetrate Shanghai and Beijing commercial real estate as facility managers prioritize LEED-compliant procurement scorecards. The Ministry of Ecology and Environment advances dual carbon goals that favor biodegradable surfactant formulations in state-owned enterprise supply chains. The Yangtze River Delta manufacturing belt concentrates electrochemical activation equipment assembly for hospitality fleet pilots.
United Kingdom
K-12 districts and National Health Service trusts unbundle cleaning chemistry procurement from equipment leases to capture standalone BREEAM compliance credits. The Health and Safety Executive reviews antimicrobial carpet treatment classifications ahead of anticipated EU alignment post-Brexit. London's commercial property management sector leads specification of low-moisture encapsulation systems for quick-dry maintenance contracts.
Carpet Cleaning Products Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring integrated chemistry-equipment bundles while retail channels reward shelf-space dominance. The vendor base concentrates around three tiers: multinational household names with captive detergent lines, European equipment OEMs with proprietary formulation subsidiaries, and regional concentrate blenders serving janitorial supply distributors. Two strategic archetypes predominate: chemistry-forward players leveraging enzymatic patent positions, and equipment-anchored competitors bundling detergent supply into service contracts. M&A activity targets mid-scale enzymatic formulators, while capacity expansion concentrates in lower-cost manufacturing zones serving export markets.
Among North American branded specialists, BISSELL Inc. and The Clorox Company exemplify divergent positioning—one integrating captive enzymatic pretreatment supply for residential margin protection, the other leveraging retail shelf dominance and private-label manufacturing scale for institutional buyers. Alfred Kärcher SE & Co. KG represents the European equipment-anchored archetype, where professional extraction hardware bundling with proprietary detergent chemistry protects installed-base relationships. These three occupy positions across the premium-brand, retail-mass, and professional-industrial vectors respectively.
| Leading Market Players |
|---|
| BISSELL Inc. |
| Techtronic Industries Co. Ltd. |
| The Clorox Company |
| Zep Inc. |
| Tennant Company |
| Reckitt Benckiser Group plc |
| Alfred Kärcher SE & Co. KG |
| Sprayway Inc. |
| Church & Dwight Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Bulk concentrate procurement by hospitality chains with 500-plus property portfolios forces supply chain reconfiguration toward dilution-at-use economics, compressing per-gallon margins while rewarding freight-optimized formulations with multi-year fleet contracts.
Pricing Analysis
Short lead-time premiums attach to enzymatic formulations facing REACH registration bottlenecks in Europe, while spot inventory of petroleum-derived surfactants trades at discounts during crude price softness. Three-tier pricing structure across premium certified, standard commercial, and economy private-label levels reflects EPA Safer Choice certification status and volume commitment scale. Cost compression in synthetic quaternary ammonium lines is intensifying because of dual petroleum and plant-derived formulation maintenance. Residential retail channels exhibit highest price sensitivity; institutional buyers with LEED procurement scorecards show lowest.
Supply Chain Analysis
Formulation chemist talent scarcity in Germany and North American labor markets constrains enzymatic chemistry scale-up, extending product launch timelines for mid-tier manufacturers. Manufacturing concentrates in the United States, Germany, and China's Yangtze River Delta, with the latter hosting electrochemical activation equipment assembly. Surfactant feedstocks draw from palm-derived oleochemicals and petroleum-based ethylene oxide. Single-source vulnerability sits with Malaysian oleochemical supply. Distribution runs through direct sales for institutional accounts and janitorial supply distributors for fragmented commercial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic formulation capacity bottlenecks prop pricing premiums, creating supply-constrained conditions that favor early movers with certified production lines and captive R&D pipelines.
For Market Incumbents: Acquire mid-scale enzymatic formulators with EPA Safer Choice dossiers to consolidate certification assets ahead of REACH enforcement windows. Expand backward integration into plant-derived surfactant supply to hedge petroleum feedstock volatility. Electrochemical activation equipment pilots by hospitality chains threaten traditional concentrate volume, demanding equipment-chemistry bundling responses. For New Entrants and Emerging Players: Capture German healthcare network sterilization-grade carpet maintenance protocols, an underpenetrated specification segment where enzymatic alternatives displace legacy quaternary ammonium treatments. California state-level VOC regulations create preferential procurement entry points for early reformulators. Direct-to-fleet digital platforms offer disintermediation angles bypassing entrenched janitorial supply distributors. For Investors and Strategic Acquirers: The window for entry favors chemistry-forward specialists with enzymatic patent positions and dual EPA-EU certification capabilities. Long-term viability hinges on regulatory compliance moats widening over the projection horizon. Watch pending EU per- and polyfluoroalkyl substance restrictions as signal for stain-resistant treatment bundle displacement and adjacent revenue risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | Captive oleochemical sourcing insulates margin pools from crude-linked feedstock volatility in dual-formulation lines. |
| Enzymatic Patent Portfolio Acquisition | Protein- and cellulase-based active ownership secures specification preference in hospital and K-12 procurement scorecards. |
| Direct-to-Fleet Digital Platform Launch | Integrated facility management software ordering disintermediates traditional distribution and captures recurring concentrate revenue. |
| Dual Certification Investment | Parallel EPA Safer Choice and EU Detergents Regulation compliance creates vendor pool scarcity and pricing power. |
| Electrochemical Activation Partnership | On-site cleaning agent generation pilots with hospitality chains reposition competitive advantage around total cost of ownership. |
Methodological Framework
Trade publications, customs shipment records, and EPA Safer Choice certified product registries formed the secondary backbone, cross-referenced with primary interviews across formulation chemists, hospitality procurement directors, facility management executives, and janitorial supply distributors. Bottom-up and top-down triangulation validated volume estimates against equipment installation bases and concentrate consumption rates.
Bottom-up modeling built from product-type, formulation chemistry, and end-user segmentation dimensions across the analysis window, with top-down cross-checks against regional facility management spend patterns. CAGRs derived from installed base growth rates, replacement cycle analysis, and procurement contract renewal velocity. Industry-specific inputs included LEED and BREEAM certification penetration curves and REACH registration timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU per- and polyfluoroalkyl substance regulatory amendments and petroleum surfactant cost volatility. Forecasts reflect documented assumptions on certification adoption rates and enforcement timing. Material deviation in EPA Safer Choice disclosure thresholds or REACH quaternary ammonium compound restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Fabric Care Market