
 US Cleaning Products Market | 2026-2036
US Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Cleaning Products Market Insights
Texas is reconfiguring manufacturing capacity for cleaning products as energy costs and petrochemical feedstock proximity attract new production investments. Procter & Gamble leverages its R&D intensity to dominate branded household formulations. The Clorox Company anchors its position through backward integration into bleach chemistry. SC Johnson competes on fragrance technology and sustainable packaging credentials.
US cleaning products encompass formulated chemical solutions containing surfactants, solvents, chelating agents, and antimicrobial actives designed to remove soil, eliminate pathogens, or maintain material surfaces across residential and commercial environments. The residential application segment sustains the largest revenue pool due to recurring purchase frequency and brand loyalty, while the institutional end user category including hospitals and schools registers the fastest structural expansion as infection control protocols intensify. Liquid formulations maintain volume leadership though spray and wipe formats are capturing share in commercial channels where convenience and labor efficiency command premium positioning.
The EPA regulates antimicrobial claims through FIFRA registration requirements while OSHA sets workplace chemical exposure limits affecting industrial formulation standards. California's Proposition 65 and the EPA Safer Choice program are forcing reformulation away from volatile organic compounds and respiratory sensitizers. Stakeholders must monitor pending state-level chemical disclosure laws that will determine which formulations retain shelf access in high-population coastal markets.
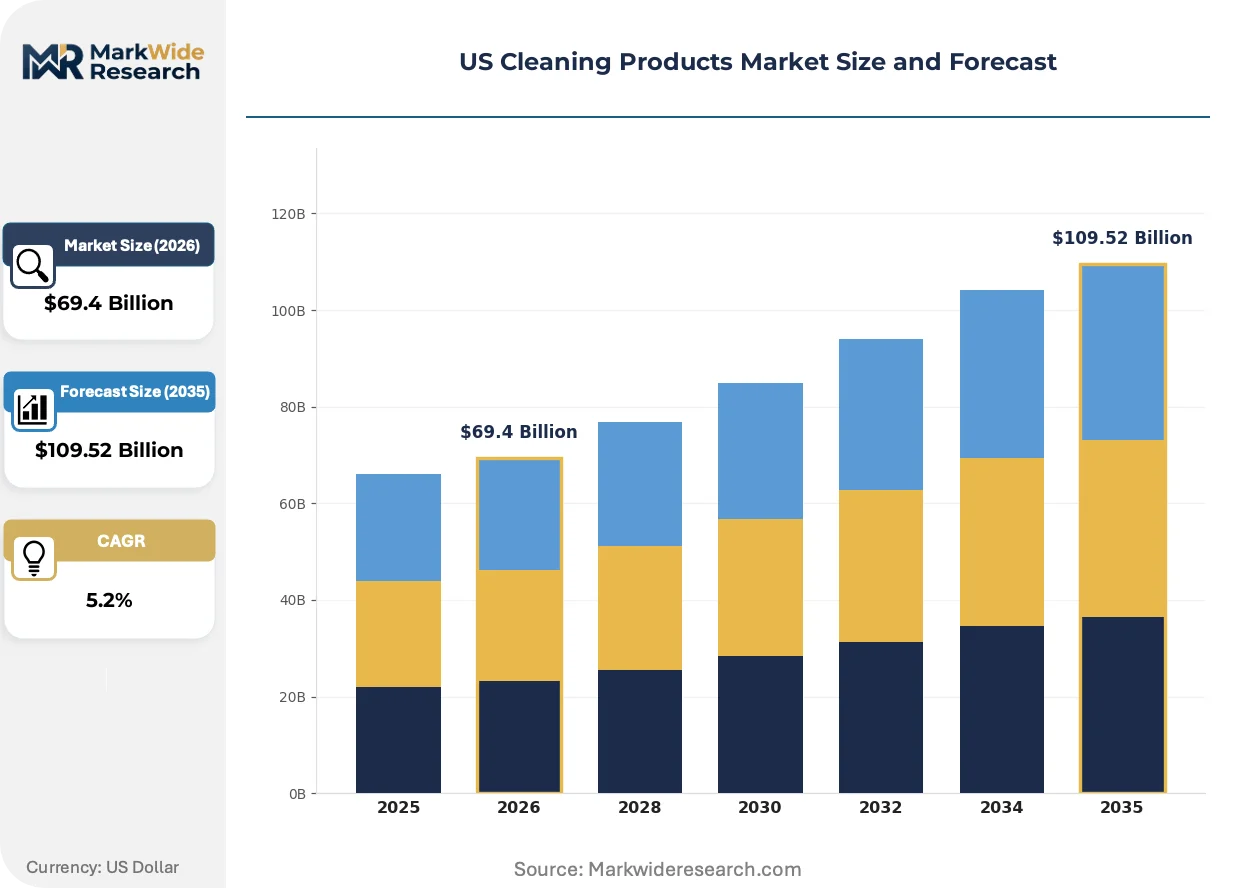
Market Dynamics
EPA Safer Choice disclosure mandates and California Proposition 65 enforcement are forcing wholesale reformulation of legacy chemistries, compressing product development cycles and raising compliance costs across the value chain.
Growth Catalysts
- Hospital Infection Control Mandates:Joint Commission accreditation standards now require documented surface disinfection protocols in acute care facilities, expanding institutional procurement of hospital-grade actives.
- Texas Petrochemical Feedstock Proximity:Low-cost natural gas liquids from the Permian Basin are attracting new surfactant and solvent manufacturing capacity to the Gulf Coast.
- OSHA Workplace Exposure Limits:Revised permissible exposure limits for quaternary ammonium compounds are accelerating substitution toward peracetic acid and hydrogen peroxide-based systems.
Market Restraints
- Chlor-Alkali Supply Concentration:Three producers control 80% of US caustic soda and chlorine feedstock, creating input cost volatility for bleach-dependent formulations.
- EPA FIFRA Registration Timelines:New antimicrobial active ingredient approvals average 36-48 months, blocking rapid innovation in emerging pathogen claims.
- Propylene Oxide Price Volatility:Surfactant feedstock costs swing with crude oil and propylene derivative markets, compressing margin stability for mid-tier manufacturers.
Strategic Opportunities
- Arizona and Nevada Commercial Real Estate Expansion:Phoenix and Las Vegas office and hospitality construction is outpacing national averages, creating concentrated demand for janitorial supply contracts.
- Refill and Concentrate Systems:Water-soluble pod and bulk concentrate formats reduce shipping weights and plastic packaging, aligning with California extended producer responsibility mandates.
- Electrolyzed Water On-Site Generation:Hypochlorous acid systems installed at food processing and healthcare facilities are displacing shipped chemical inventories.
Industry Challenges
- Toxicologist and Formulation Chemist Shortage:EPA registration dossier preparation requires specialized expertise that universities are not producing at replacement rates.
- Legacy ERP Integration with Batch Manufacturing:Small and mid-sized compounders struggle to connect formula management systems with modern lot traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cleaning Products Market |
| Market Size in 2026 | $69.4 Billion |
| Market Size in 2035 | $109.52 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Cleaners, Surface Cleaners, Disinfectants, Stain Removers Application: Residential, Commercial, Industrial, Institutional Formulation: Liquid, Powder, Spray, Wipe End User: Households, Offices, Hospitals, Schools |
| Companies Covered | Procter & Gamble, The Clorox Company, SC Johnson, Church & Dwight, Reckitt Benckiser, Unilever, Ecolab, Henkel, Zep, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cleaning Products Market Trends and Innovations
Formulation science is converging with digital compliance tools and on-site generation hardware, reshaping how cleaning chemistry is produced, validated, and delivered to end users.
Electrolyzed water systems is virtualizing the traditional chemical supply model by generating hypochlorous acid and sodium hydroxide on demand from salt, water, and electricity. Food processing plants and hospital environmental services departments in the Midwest are piloting these units to eliminate drum handling and inventory management. The technology is virtualizing distribution margins and regulatory documentation burdens by shifting compliance responsibility to facility operators.
EPA's Safer Choice Standard is tightening surfactant and solvent disclosure requirements through mandatory third-party toxicological screening. Manufacturers must now submit complete chemical inventories rather than generic functional descriptions, raising formulation transparency to unprecedented levels. Household and institutional product lines targeting California and Northeast retail channels are reformulating away from alkylphenol ethoxylates and glycol ethers to retain shelf access.
Facility managers are consolidating supplier relationships around full-line janitorial distributors capable of delivering chemicals, dispensing equipment, training, and compliance documentation through single-source contracts. This behavior is compressing the independent chemical rep network that historically sold individual product categories. The shift is most visible in Class A office buildings and multi-site healthcare systems in Texas and Florida where procurement departments prioritize invoice consolidation over product-level optimization.
US Cleaning Products Market Segmentation
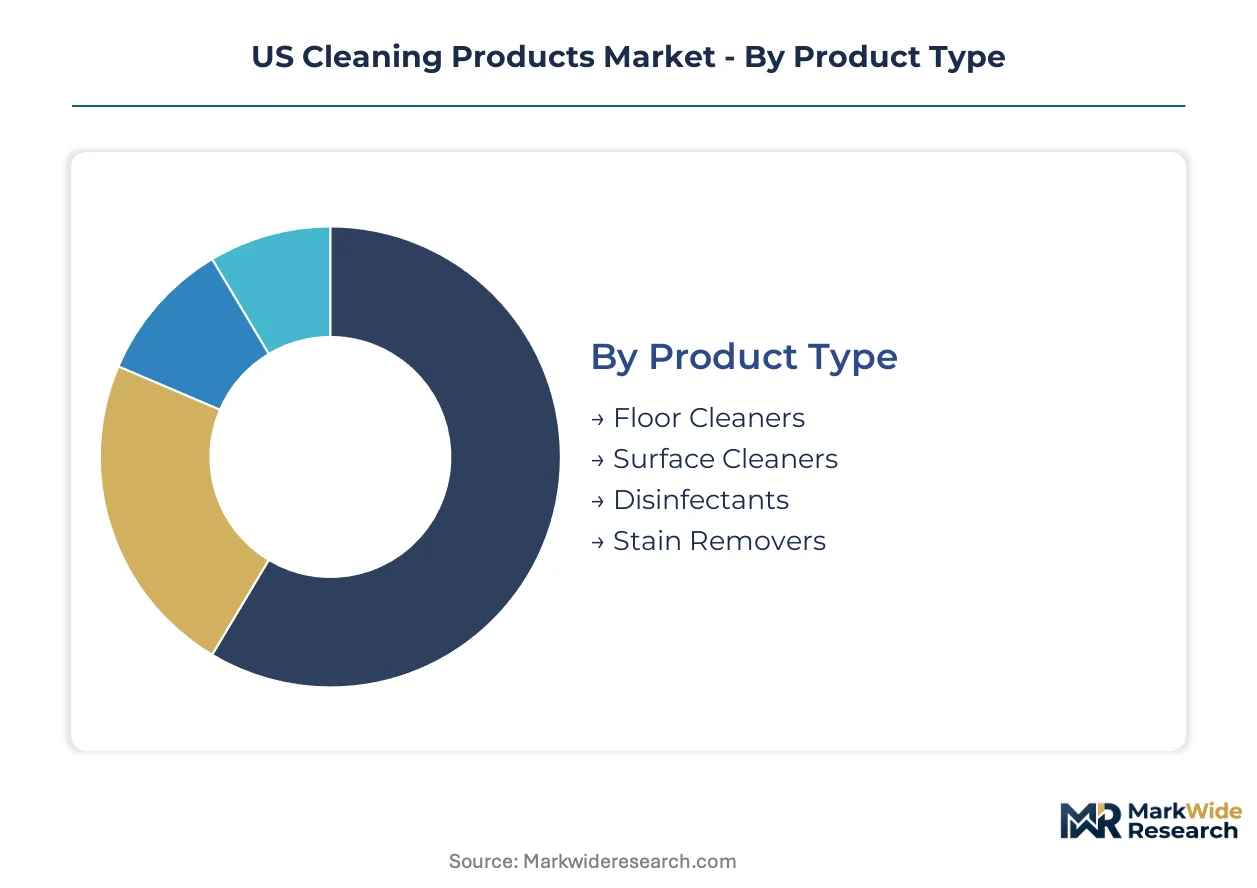
Cleaning products segmentation reveals divergent profit mechanics across purchase cycles. Residential households replenish monthly while institutional buyers negotiate annual contracts with compliance documentation requirements.
Product Type:
Floor cleaners turn inventory fastest at mass retail while disinfectants sit in procurement review cycles lasting quarters.
- Floor Cleaners:Polymer-fortified emulsions and pH-neutral formulations designed for sealed wood, tile, and resilient flooring substrates. Demand clusters in Texas and California commercial real estate corridors where property management firms specify bulk concentrate systems for janitorial contracts.
- Disinfectants:EPA-registered formulations carrying FIFRA-approved kill claims against specified pathogens including SARS-CoV-2, norovirus, and C. difficile spores. Hospital procurement departments in the Midwest and Southeast are expanding hospital-grade quaternary ammonium and peracetic acid inventories under Joint Commission pressure.
- Surface Cleaners:All-purpose degreasers and specialty formulations for glass, stainless steel, and stone surfaces.
- Stain Removers:Enzymatic and oxygen-bleach actives targeting protein, oil, and dye soils in textile and hard surface applications.
Surface cleaners dominate household purchase frequency. Disinfectants are where expansion concentrates.
Application:
Cost tier separation runs deepest here: residential buyers self-select at shelf while institutional procurement teams run total-cost-of-ownership models.
- Residential:Brand-loyal repeat purchases of familiar formulations through grocery, mass merchant, and e-commerce channels. California and Northeast households are driving reformulation toward Safer Choice-certified surfactants and fragrance-free variants for respiratory sensitivity.
- Commercial:Office building, retail, and hospitality maintenance contracts specifying dilution-control systems and documented training protocols. Phoenix and Las Vegas property managers are consolidating supplier relationships around full-line distributors.
- Industrial:Heavy-duty degreasers, parts washers, and process equipment cleaners for manufacturing and food processing facilities.
- Institutional:Infection control protocols in acute care, long-term care, and educational facilities with EPA-registered hospital-grade requirements.
Residential commands volume leadership. Institutional is climbing the fastest.
Formulation:
Volume economics favor liquids for shipping efficiency while spray and wipe formats capture labor-cost premiums in commercial channels.
- Liquid:Concentrated and ready-to-use solutions dominating bulk institutional procurement and value-positioned household segments. Gulf Coast manufacturing proximity to Texas petrochemical feedstock sustains cost competitiveness.
- Spray:Trigger-dispensed formulations capturing convenience premiums in kitchen, bathroom, and quick-clean applications. Commercial buyers in Class A office buildings specify spray formats for reduced dwell time and labor efficiency.
- Powder:Abrasive scouring compounds and oxygen-bleach laundry additives with extended shelf stability.
- Wipe:Pre-saturated substrates in canister and flat-pack formats for healthcare surface disinfection and foodservice sanitization.
Liquid formulations anchor manufacturing scale. Spray formats are gaining share fastest.
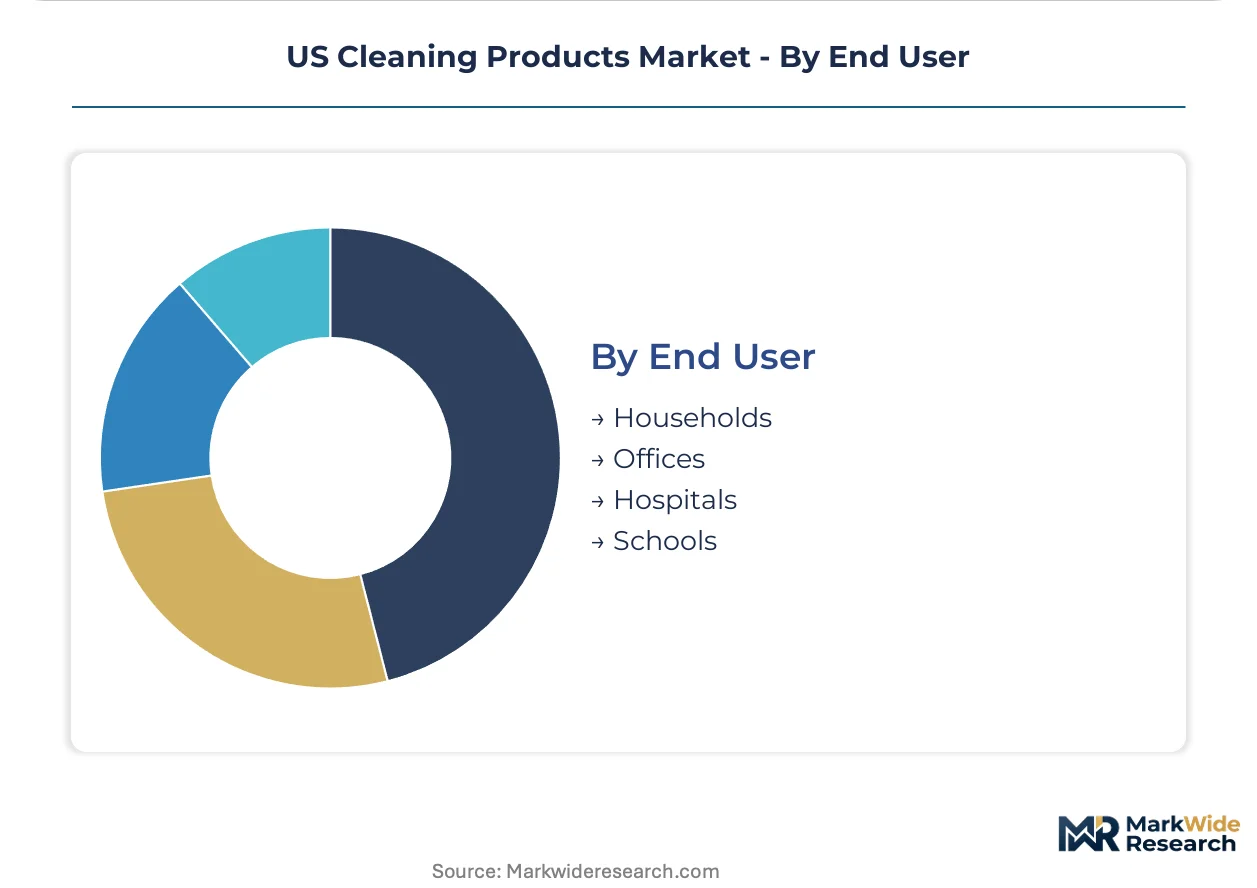
End User:
Customer type determines regulatory exposure: households face minimal oversight while hospitals navigate EPA, OSHA, and Joint Commission layering.
- Households:Individual consumers making brand-driven purchase decisions through retail and direct-to-consumer channels. California Proposition 65 disclosure requirements are reshaping ingredient transparency expectations.
- Offices:Facility management departments specifying products compatible with LEED certification and indoor air quality standards. Texas and Florida multi-site operators prioritize invoice consolidation over product-level optimization.
- Hospitals:Environmental services departments managing infection control protocols with documented surface disinfection and terminal cleaning requirements.
- Schools:K-12 and university procurement balancing efficacy against student safety with restricted-chemical lists and green cleaning mandates.
Households sustain the largest revenue pool. Hospitals are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California consume cleaning products through divergent lenses: Texas prioritizes bulk institutional procurement for expanding commercial real estate, while California households drive reformulation toward fragrance-free and Safer Choice-certified formulations.
California
California households command the largest residential revenue pool through repeat purchases of premium-positioned formulations. Proposition 65 enforcement and the state's Safer Choice certification program are forcing disclosure of complete chemical inventories rather than generic functional descriptions. Los Angeles and San Francisco Bay Area property management firms specify bulk concentrate systems for janitorial contracts in Class A office buildings.
Texas
Texas institutional buyers anchor the fastest-growing demand segment as hospital infection control mandates intensify procurement of EPA-registered disinfectants. OSHA workplace exposure limits for quaternary ammonium compounds are accelerating substitution toward peracetic acid systems in Gulf Coast healthcare facilities. Houston and Dallas-Fort Worth commercial corridors attract new surfactant manufacturing capacity drawn by Permian Basin petrochemical feedstock proximity.
New York Metro
New York Metro multi-site healthcare systems consolidate supplier relationships around full-line distributors capable of delivering chemicals, dispensing equipment, and compliance documentation through single-source contracts. Joint Commission accreditation standards require documented surface disinfection protocols in acute care facilities across Manhattan and Long Island. Brooklyn and Queens industrial zones host mid-sized compounders struggling with legacy ERP integration against modern lot traceability requirements.
Florida
Florida hospitality and long-term care facilities drive institutional demand for spray-format disinfectants optimized for labor efficiency in high-turnover environments. State procurement departments prioritize invoice consolidation over product-level optimization across multi-site operations. Miami and Orlando property managers specify products compatible with LEED certification and indoor air quality standards in new construction.
Illinois
Illinois food processing plants pilot electrolyzed water on-site generation systems to eliminate drum handling and inventory management burdens. Midwest hospital environmental services departments test hypochlorous acid units for terminal cleaning requirements under Joint Commission pressure. Chicago metropolitan industrial zones concentrate formulation chemist talent pools supporting EPA registration dossier preparation.
US Cleaning Products Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three producer categories: multinational consumer goods conglomerates with captive R&D infrastructure, mid-sized institutional specialists with backward integration into bleach chemistry, and regional compounders serving private-label retail channels. Strategic moves concentrate on portfolio diversification toward sustainable packaging formats and geographic expansion into Arizona and Nevada commercial real estate corridors.
Within the multinational tier, Procter & Gamble, The Clorox Company, and SC Johnson occupy positions defined by R&D intensity, captive chemical production, and fragrance technology specialization respectively. Procter & Gamble exemplifies the scale-driven archetype through branded household formulation dominance. The Clorox Company anchors the backward-integrated segment with captive bleach chemistry capabilities. SC Johnson sits within the sustainability-positioned tier competing on packaging credentials and third-party certification alignment.
| Leading Market Players |
|---|
| Procter & Gamble |
| The Clorox Company |
| SC Johnson |
| Church & Dwight |
| Reckitt Benckiser |
| Unilever |
| Ecolab |
| Henkel |
| Zep |
| Others |
Pricing and Supply Chain Analysis
Gulf Coast petrochemical corridors near Houston anchor US surfactant and solvent manufacturing capacity, leveraging Permian Basin natural gas liquids feedstock to compress input costs and extend pricing power to backward-integrated producers. This geographic concentration creates tiered margin structures where captive chlorine and caustic soda production insulates against chlor-alkali oligopoly volatility.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement as hospital systems and multi-site property managers negotiate annual agreements with documented compliance documentation. Three-tier pricing structure across premium, standard, and economy levels separates Safer Choice-certified formulations from conventional chemistry and private-label alternatives. Pricing pressure stems from California Proposition 65 enforcement and EPA disclosure mandates forcing costly reformulation cycles. Residential households exhibit highest price sensitivity through brand switching at shelf, while institutional buyers prioritize total-cost-of-ownership over unit pricing.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain working capital for mid-sized compounders serving retail private-label channels. Manufacturing draws from Texas, Louisiana, and New Jersey production hubs with concentrated chlor-alkali, surfactant, and fragrance supply. Propylene oxide and quaternary ammonium compound feedstocks expose margins to crude oil derivative volatility. Single-source vulnerability concentrates in three producers controlling caustic soda and chlorine supply. Distribution runs through full-line janitorial distributors consolidating independent chemical rep networks in Texas and Florida commercial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Safer Choice disclosure mandates and on-site electrolyzed water generation constitute a dual technological-regulatory inflection, compressing traditional formulation margins while virtualizing chemical distribution. Stakeholders must reposition around transparency credentials and capital-light service models.
For Market Incumbents: Entrench backward integration into bleach chemistry and captive surfactant production to defend against peracetic acid substitution and hypochlorous acid displacement. Expand Gulf Coast manufacturing capacity to exploit Permian Basin feedstock proximity. Invest in EPA registration dossier capabilities as toxicologist shortage intensifies compliance bottlenecks.
For New Entrants and Emerging Players: Arizona and Nevada commercial real estate corridors offer concentrated janitorial contract opportunities with less entrenched distributor relationships than Texas and California markets. Target electrolyzed water on-site generation hardware and service contracts for Midwest food processing plants seeking drum elimination. Pursue direct facility relationships bypassing traditional chemical distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with EPA registration expertise and Safer Choice certification pipelines over commodity bleach producers. Five-to-ten year viability hinges on reformulation agility and compliance documentation capabilities. Monitor state-level chemical disclosure law passage as shelf-access inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Bleach Chemistry | The Clorox Company's captive chlorine production insulates margin against chlor-alkali oligopoly pricing volatility. |
| EPA Safer Choice Certification Investment | Complete chemical inventory disclosure retains California and Northeast retail shelf access under tightening mandates. |
| Electrolyzed Water On-Site Generation Deployment | Hypochlorous acid systems displace shipped chemical inventories in Midwest food processing and healthcare facilities. |
| Full-Line Distributor Consolidation | Single-source contracts for chemicals, equipment, and training compress independent rep networks in Texas and Florida. |
| Refill and Concentrate Format Expansion | Water-soluble pods reduce shipping weights and align with California extended producer responsibility mandates. |
Research Methodology
A standing panel of plant managers at Gulf Coast surfactant facilities, procurement leads at multi-site healthcare systems, janitorial distribution channel partners, and EPA registration consultants provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against customs and trade data, American Chemistry Council sector reports, SEC 10-K filings, and EPA FIFRA registration databases. Bottom-up volume modeling and top-down value triangulation cross-verified segment-level outputs.
Scenario bracketing around regulatory enforcement intensity and feedstock price volatility anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, formulation, and end user with geographic production hub differentiation. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion schedules. Forecast inputs incorporated chlor-alkali capacity utilization rates and hospital infection control procurement cycle timing.
Practitioners should monitor pending state chemical disclosure legislation and electrolyzed water adoption curves for early signals of demand displacement. Forecasts reflect assumptions around EPA registration timeline stability and Permian Basin feedstock cost persistence. Macroeconomic contraction, accelerated regulatory restriction, or breakthrough on-site generation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Cleaning and Hygiene Products Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Household Cleaning Products Market