
 Commercial Vacuum Cleaners Market | 2026-2036
Commercial Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vacuum Cleaners Market Insights
Hospitality is repositioning procurement toward cordless and robotic units to reduce labor costs and improve turnaround times. Alfred Kärcher leverages its European service network to dominate hotel and conference center contracts. Nilfisk competes through specialized wet-and-dry systems for food service environments. Tennant Company anchors North American demand with autonomous floor care integration.
Commercial vacuum cleaners are motorized suction devices engineered for continuous-duty cycles, typically rated above 1,000 watts with sealed HEPA filtration to capture particles as small as 0.3 microns for health-sensitive environments. Canister units sustain the largest installed base in European office complexes due to maneuverability on mixed flooring. Robot technology leads growth acceleration as facilities managers prioritize overnight autonomous operation with minimal supervision. Backpack configurations occupy niche demand in aviation and theater cleaning where aisle access restricts wheeled equipment.
OSHA indoor air quality guidelines and the EU F-Gas Regulation shape motor efficiency and refrigerant-based cooling requirements for battery-powered units. ECHA REACH compliance restricts certain plastics and coatings in housing materials, forcing redesigns across supply chains. Stakeholders must monitor battery chemistry certification timelines and building automation integration standards to preserve market access.
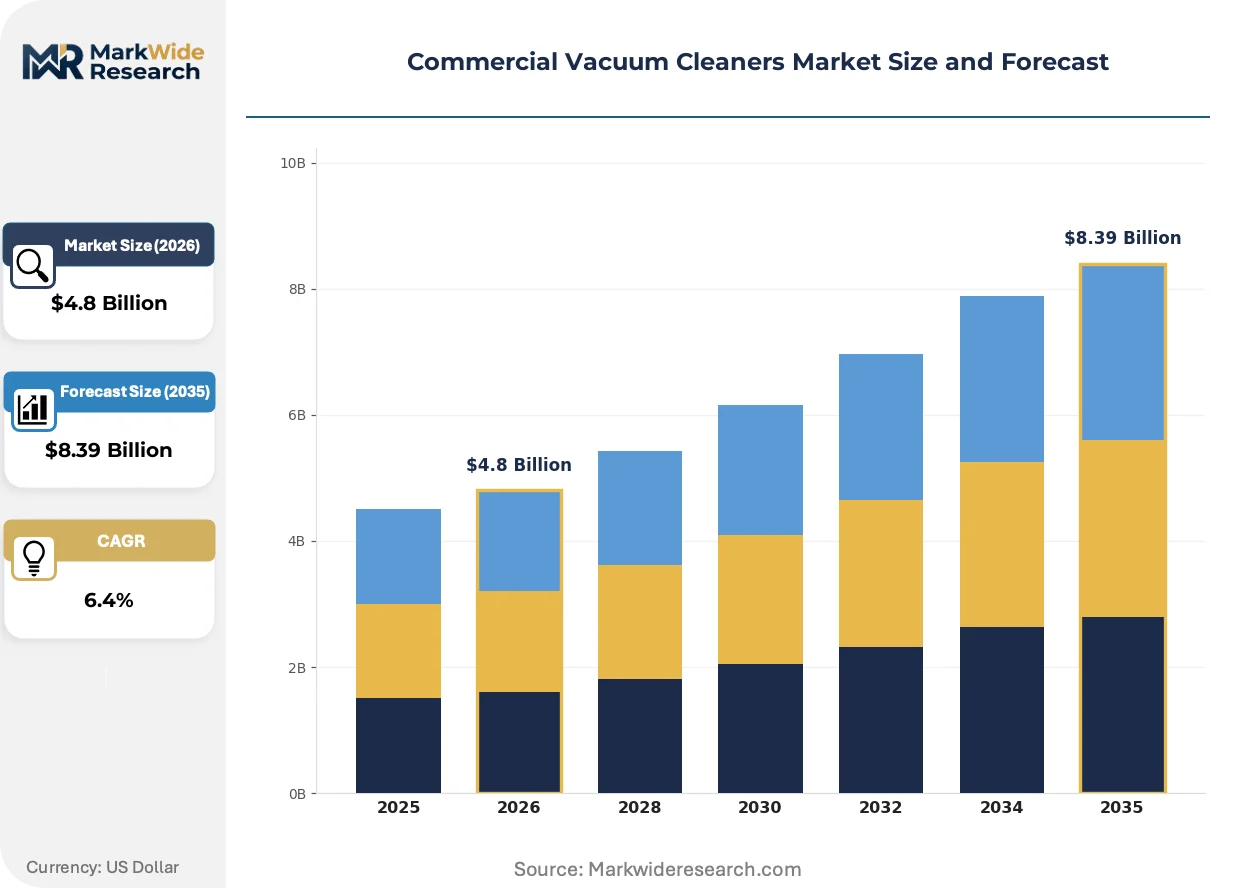
Market Dynamics
Autonomous cleaning fleets are compressing labor dependency across commercial facilities, forcing equipment makers to embed navigation software and fleet management APIs directly into hardware specifications.
Growth Catalysts
- OSHA indoor air quality guidelines:Mandates for HEPA-grade filtration in healthcare and education facilities are accelerating replacement cycles for legacy units lacking sealed systems.
- Battery chemistry advances:Lithium iron phosphate cells are extending cordless runtime past four hours, enabling overnight cleaning without facility power access.
- Germany's industrial cleaning corridor:Concentrated demand from automotive manufacturing plants and pharmaceutical cleanrooms sustains premium equipment procurement volumes.
Market Restraints
- Critical motor component concentration:Brushless DC motor production clusters in China create supply vulnerability for European and North American assembly plants.
- ECHA REACH compliance costs:Restrictions on halogenated flame retardants and certain ABS plastics force housing material redesigns with 18-24 month recertification timelines.
- Manual cleaning labor arbitrage:Low-wage janitorial staffing in emerging markets delays automation adoption in price-sensitive commercial segments.
Strategic Opportunities
- EU AI Act building automation standards:Compliance mandates for connected equipment create first-mover advantage for vendors with pre-certified autonomous navigation systems.
- Aviation sector aisle-access configurations:Backpack vacuum demand from airport terminal operators remains underpenetrated relative to wheeled equipment saturation.
- Leasing and servitization models:Equipment-as-a-service contracts bundling maintenance and filter replacement are displacing capital purchase structures in hospitality chains.
Industry Challenges
- Robotics integration talent scarcity:Facilities managers lack training in fleet calibration and obstacle-mapping software, creating deployment friction.
- Multi-standard certification complexity:Simultaneous CE marking, UL listing, and GB standard compliance for battery systems extends product launch timelines.
- Legacy building infrastructure incompatibility:Narrow elevator dimensions and pre-war electrical systems in urban commercial properties restrict autonomous unit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vacuum Cleaners Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Backpack, Robot Application: Hospitality, Education, Office, Retail Technology: HEPA Filter, Corded, Cordless, Wet & Dry End User: Commercial Facilities, Cleaning Services, Industrial Sites, Government Agencies |
| Companies Covered | IPC, Bosch Professional, Nilfisk, Shop-Vac Corporation, Makita Corporation, Alfred Kärcher, Festool, Pullman Ermator, Tennant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vacuum Cleaners Market Trends and Innovations
Connected equipment architectures and predictive maintenance algorithms are redefining how commercial cleaning assets are monetized and operated across facility management contracts.
Robot navigation systems utilizing LiDAR and simultaneous localization and mapping are overtaking manual push units in large-format retail and logistics warehouses. Amazon fulfillment centers and IKEA distribution hubs are deploying hundred-unit fleets with minimal overnight supervision. This compression of labor oversight is overtaking traditional equipment procurement criteria centered on unit purchase price.
The EU F-Gas Regulation is restricting refrigerant-based cooling in battery thermal management systems for cordless equipment. Manufacturers are pivoting to phase-change materials and passive cooling architectures to maintain runtime performance. German industrial cleaning contractors face the most acute compliance pressure due to stringent federal enforcement of the framework.
Third-party fleet management platforms are unbundling after-sales service from original equipment vendors. ISS and Sodexo are consolidating supplier relationships around interoperability standards rather than single-brand loyalty. This aggregation is most visible in London and Frankfurt commercial property clusters where multi-site contracts dominate procurement authority.
Commercial Vacuum Cleaners Market Segmentation
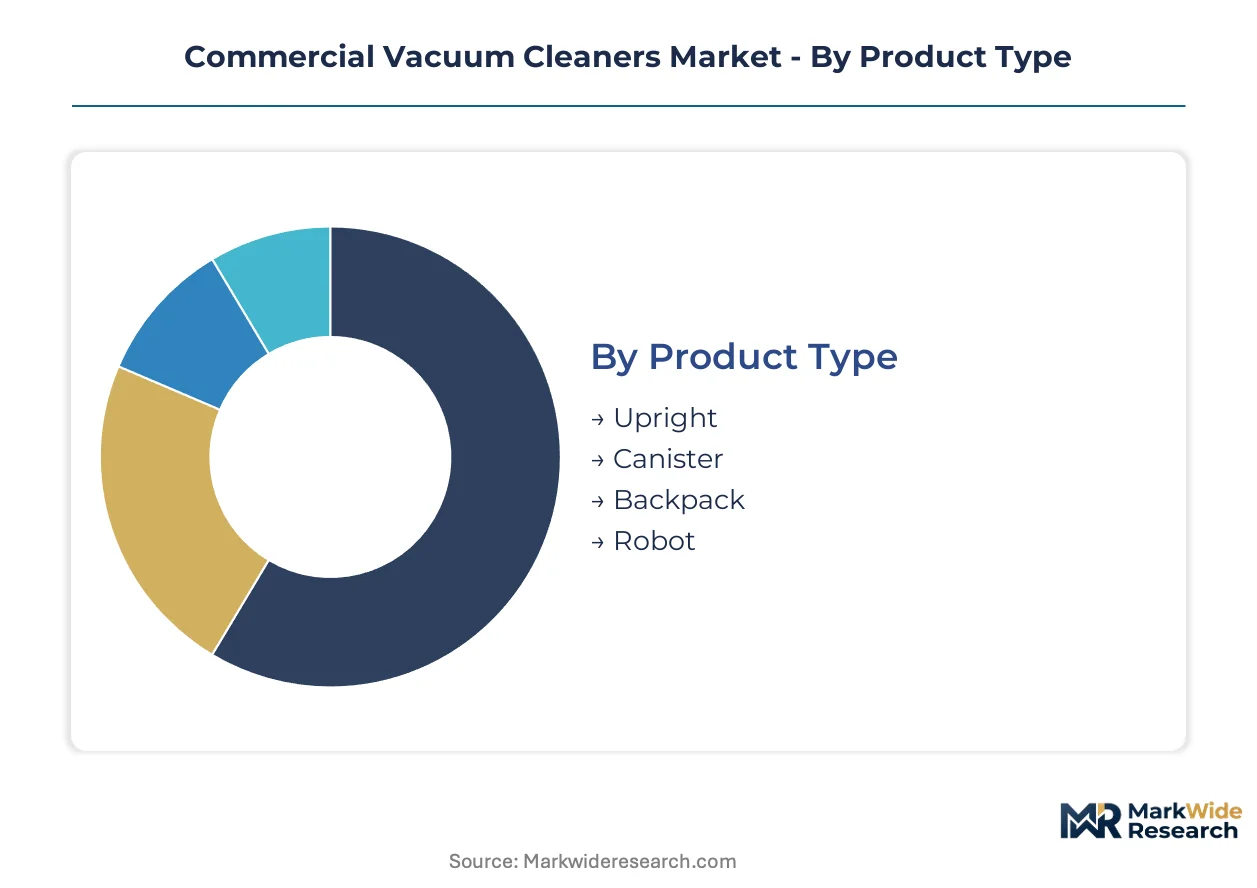
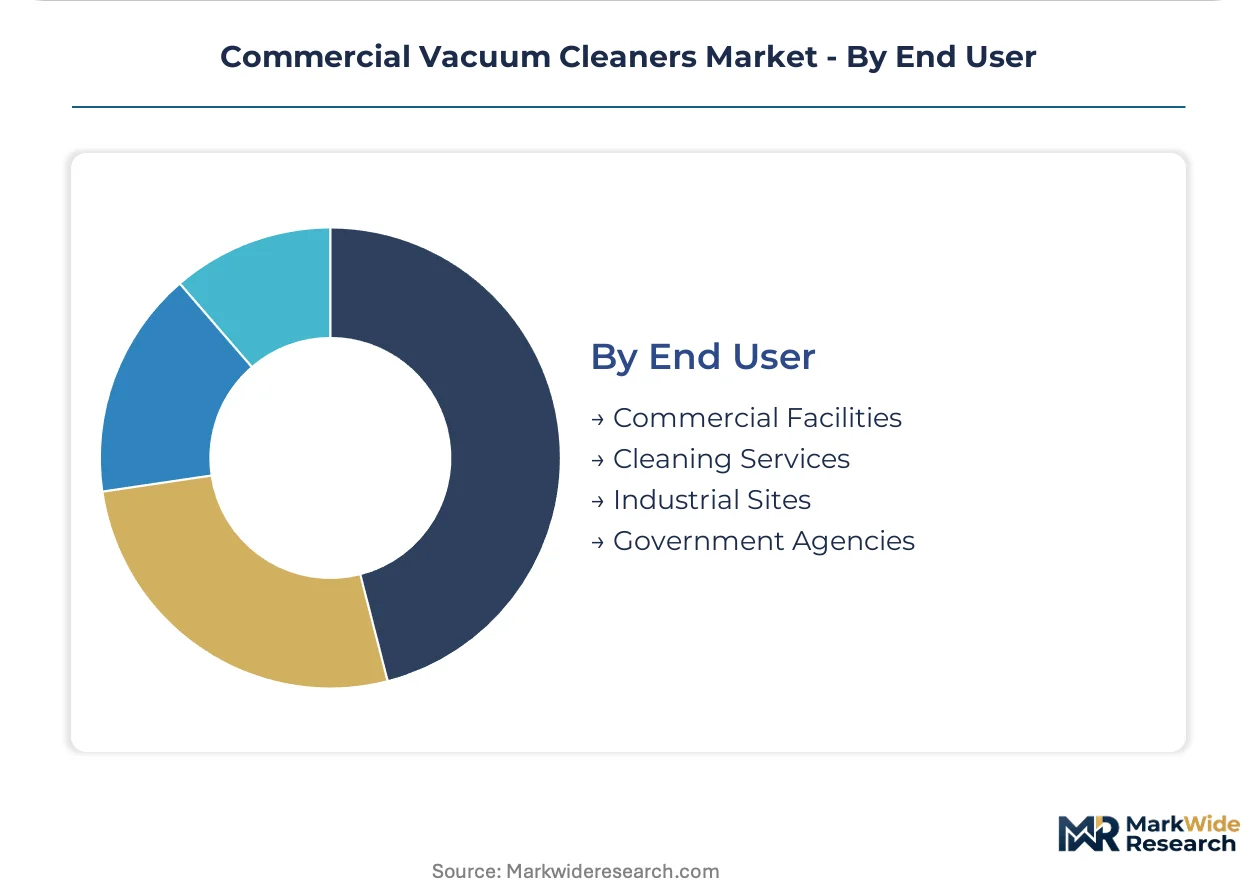
Equipment specifications diverge sharply between labor-cost-sensitive hospitality chains and compliance-heavy healthcare education facilities. Procurement authority sits with facilities managers who weight runtime autonomy against filtration certification tiers.
Product Type:
Volume concentration favors established form factors with proven service networks, while premium growth concentrates in autonomous navigation platforms requiring software integration capabilities.
- Robot:LiDAR-enabled navigation systems with fleet management APIs support overnight autonomous operation in logistics warehouses and retail supercenters. Amazon fulfillment centers and IKEA distribution hubs in Germany and the United States deploy hundred-unit fleets with minimal supervision, compressing labor dependency and shifting procurement criteria from unit price to total cost of ownership.
- Canister:Sealed HEPA configurations rated above 1,000 watts sustain the largest installed base across European office complexes with mixed flooring surfaces. Maneuverability on carpet-hardwood transitions and established service infrastructure in Germany's industrial cleaning corridor preserve procurement volumes despite cordless encroachment.
- Upright:Direct-drive brushroll systems dominate North American hotel corridor maintenance where rapid turnaround times prioritize single-pass debris removal.
- Backpack:Aviation terminals and theater aisles with width restrictions drive niche demand for torso-mounted units with HEPA exhaust filtration.
Mature deployment sits with canister configurations in European office infrastructure. Newer deployment is concentrated in robot fleets across North American logistics and retail properties.
Application:
End-use differentiation tracks cleaning frequency requirements and regulatory exposure rather than facility square footage alone.
- Hospitality:Casino resorts and conference centers in Las Vegas and Macau prioritize cordless runtime extension and robotic overnight coverage to reduce union labor scheduling constraints. Turnaround time compression between guest checkouts drives replacement cycles shorter than equipment depreciation schedules.
- Education:K-12 districts and university systems face OSHA indoor air quality mandates for sealed HEPA systems in classrooms and administrative buildings. Procurement concentrates in summer replacement windows with bond-funded capital allocations.
- Office:Class A commercial properties in Frankfurt and London financial districts specify connected equipment with building automation integration for LEED certification maintenance.
- Retail:Big-box operators and grocery chains balance open-hours cleaning visibility against after-hours labor cost structures.
Procurement standardization is deepest in education through cooperative purchasing agreements. Specification divergence is widest in hospitality where brand differentiation drives custom fleet configurations.
Technology:
Power delivery architecture and filtration certification together determine equipment eligibility for regulated environments.
- Cordless:Lithium iron phosphate battery chemistry extends runtime past four hours, enabling overnight cleaning without facility power access. German automotive manufacturing plants and pharmaceutical cleanrooms deploy cordless fleets to eliminate trip hazards in cleanroom garment protocols.
- HEPA Filter:Sealed systems capturing 0.3-micron particles are mandatory for healthcare-adjacent education facilities and pharmaceutical manufacturing under OSHA and EU occupational exposure guidelines.
- Corded:Continuous-duty AC motor systems retain cost advantage in fixed-route cleaning with predictable electrical infrastructure.
- Wet & Dry:Food service environments and manufacturing facilities with liquid spill exposure specify corrosion-resistant housings and sealed motor compartments.
Technology integration is most advanced in cordless HEPA combinations. Standalone wet-dry systems remain concentrated in industrial maintenance contracts with limited crossover to commercial facilities.
End User:
Contract structure determines capital deployment timing and service bundling preferences across procurement authorities.
- Cleaning Services:ISS, Sodexo, and regional facility management contractors consolidate multi-site contracts around interoperability standards rather than single-brand loyalty. Equipment-as-a-service leasing with bundled maintenance and filter replacement is displacing capital purchase structures.
- Commercial Facilities:Corporate real estate portfolios with in-house janitorial staff prioritize total cost visibility and depreciation scheduling over operational flexibility.
- Industrial Sites:Automotive and pharmaceutical manufacturing specify cleanroom-compatible configurations with ECHA REACH-compliant housing materials.
- Government Agencies:Federal and municipal procurement operates through competitive bidding with domestic content preferences and small business set-aside requirements.
Service bundling penetration is highest among cleaning services contractors with multi-site scale. Direct capital ownership persists in government and industrial end users with depreciation-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial cleaning corridor operates as a specialized economic zone attracting premium equipment procurement through automotive and pharmaceutical concentration. Tax incentives for facility automation in Baden-Württemberg and Bavaria compress replacement cycles below standard depreciation schedules.
United States
OSHA indoor air quality mandates accelerate HEPA-grade equipment turnover in healthcare-adjacent education facilities. The EPA's energy efficiency guidelines for commercial buildings filter into procurement specifications for connected cleaning assets. Amazon fulfillment centers across Pennsylvania, Texas, and California deploy hundred-unit autonomous fleets with minimal overnight supervision.
Germany
ECHA REACH compliance restrictions on halogenated flame retardants force housing material redesigns with 18-24 month recertification timelines. The EU F-Gas Regulation restricts refrigerant-based cooling in battery thermal management systems. Frankfurt's Class A commercial property cluster specifies building automation integration for LEED certification maintenance.
China
GB standards for battery-powered equipment and MIIT industrial automation directives shape cordless vacuum certification pathways. Commercial property hubs in Shanghai and Shenzhen concentrate demand from logistics warehouse operators and retail supercenters. Domestic brushless DC motor production clusters create supply advantages for regional assembly plants.
United Kingdom
CE marking alignment post-Brexit maintains equipment import standards while creating dual certification requirements for battery systems. London's financial district Class A properties specify connected equipment with predictive maintenance capabilities. ISS and Sodexo multi-site contracts in the Southeast consolidate procurement around interoperability standards.
Commercial Vacuum Cleaners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European heritage brands commanding premium positioning in hospitality and healthcare while Asian fabricators capture volume in price-sensitive commercial channels. The vendor base organizes into three strategic archetypes: integrated cleaning solution providers with autonomous navigation software, specialized filtration and containment specialists for regulated environments, and scale-driven component assemblers serving private-label retail. Consolidation pressure concentrates around fleet management platform capabilities and battery chemistry certification assets. Geographic expansion through distribution partnerships and technology licensing for navigation algorithms represent the dominant competitive moves.
Within the integrated solution tier, Alfred Kärcher leverages its European service network positioning, while Tennant Company anchors North American demand through autonomous floor care integration. Nilfisk occupies a specialist position exemplifying wet-and-dry system differentiation for food service environments. These three represent distinct archetype endpoints rather than overlapping competitive sets.
| Leading Market Players |
|---|
| IPC |
| Bosch Professional |
| Nilfisk |
| Shop-Vac Corporation |
| Makita Corporation |
| Alfred Kärcher |
| Festool |
| Pullman Ermator |
| Tennant Company |
| Others |
Pricing and Supply Chain Analysis
Robotics integration talent scarcity in Germany's industrial cleaning corridor widens pricing-tier spreads between autonomous fleet providers and conventional equipment vendors, compressing margins for assemblers lacking software capabilities while premium navigation systems command service-bundled contracts.
Pricing Analysis
Short lead-time premiums apply to cordless HEPA units with ECHA REACH-compliant housing materials, while spot inventory of legacy ABS-plastic configurations trades at discount. Three-tier pricing structure across premium, standard, and economy levels separates fleet-managed autonomous systems from standalone canister units and entry-level upright models. Price differentiation hinges on battery chemistry certification and sealed filtration tier. Cost compression in standard cordless tiers is intensifying because Chinese brushless DC motor exports face escalating logistics chokepoint exposure. Education facilities exhibit highest price sensitivity due to bond-funded capital windows, whereas pharmaceutical cleanrooms prioritize certification compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in China's Guangdong and Jiangsu provinces limit assembly capacity expansion for battery-powered units despite domestic motor production advantages. Component sourcing draws from South Korean lithium iron phosphate cell suppliers, German precision filtration media manufacturers, and Taiwanese sensor module fabricators. Single-source vulnerability concentrates in brushless DC motor controllers from Shenzhen-based semiconductor packaging facilities. Distribution runs through ISS and Sodexo fleet management platforms consolidating multi-site procurement authority in London and Frankfurt commercial property clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vacuum cleaner manufacturing is consolidating around autonomous navigation software capabilities, with ECHA REACH recertification timelines forcing sub-scale housing suppliers to exit.
For Market Incumbents: Anticipate margin compression from third-party fleet management platforms unbundling after-sales service by acquiring battery chemistry certification assets and embedding predictive maintenance APIs directly into hardware specifications. Prioritize backward integration into lithium iron phosphate cell supply to secure runtime performance claims against cordless competitors. Defend hospitality channel position through equipment-as-a-service leasing contracts bundling filter replacement and overnight fleet supervision. For New Entrants and Emerging Players: EU AI Act building automation standards in Germany open a window for pre-certified autonomous navigation systems targeting Frankfurt's Class A commercial property cluster with LEED certification maintenance requirements. White-space concentration sits with aviation sector backpack vacuum configurations serving airport terminal operators in London and Dubai where aisle width restrictions exclude wheeled equipment. Deploy through cleaning services contractor interoperability standards rather than OEM direct sales to bypass established service network disadvantages. For Investors and Strategic Acquirers: Re-rating potential sits with specialized filtration and containment specialists given OSHA indoor air quality mandate acceleration across healthcare-adjacent education facilities. Long-term viability favors vendors with captive battery chemistry certification and REACH-compliant housing material pipelines. Acquisition target archetype: mid-cap autonomous navigation software developers with existing fleet management API integrations. Signal to watch: Baden-Württemberg tax incentive modifications compressing replacement cycles below standard depreciation schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Management Platform Integration | ISS and Sodexo interoperability requirements displace single-brand loyalty in multi-site contracts. |
| Battery Chemistry Certification Investment | Lithium iron phosphate cell qualification secures ECHA REACH compliance for cordless runtime claims. |
| Autonomous Navigation Software Acquisition | LiDAR-enabled SLAM capabilities differentiate premium positioning in logistics warehouse deployments. |
| REACH-Compliant Housing Material Redesign | ECHA restrictions on halogenated flame retardants force 18-24 month recertification timelines for incumbents. |
| Equipment-as-a-Service Leasing Launch | Hospitality chains in Las Vegas and Macau prioritize operational flexibility over capital ownership structures. |
Research Methodology
Document review covered regulatory filings from OSHA and ECHA, trade customs data for brushless DC motor imports, and hospitality procurement databases, complemented by interviews with facilities managers at Amazon fulfillment centers, biomedical engineers in pharmaceutical cleanrooms, aftermarket service heads at European industrial cleaning contractors, and GPO contracts managers in K-12 districts. Secondary validation drew from SEC equipment manufacturer filings, EU F-Gas Regulation enforcement records, and LEED certification maintenance logs. Bottom-up unit shipment estimates triangulated against top-down facility automation spending projections.
Historical deployment patterns in Germany's industrial cleaning corridor were cross-referenced against panel input from autonomous fleet operators in Pennsylvania and Texas logistics hubs. Segmentation dimensions modeled include product type, application, power delivery architecture, filtration certification tier, and end-user contract structure. CAGRs were derived from replacement cycle compression analysis and labor cost arbitrage sensitivity testing. Forecast inputs incorporated battery thermal management regulatory phase-out timelines and building automation integration adoption curves.
The model assumes a particular technology adoption path for LiDAR-enabled navigation systems; alternative pathways for camera-based visual SLAM would alter the outlook for premium equipment procurement volumes. Forecasts reflect assumptions regarding ECHA REACH enforcement consistency and OSHA indoor air quality guideline expansion. Material deviation in Baden-Württemberg facility automation tax incentives or Shenzhen semiconductor packaging capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Hand Cleaning Accessories Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Brush Cleaner Market