
 Commercial Laundry Detergent Market | 2026-2036
Commercial Laundry Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Laundry Detergent Market Outlook
On-premise laundry operations in healthcare facilities is unwinding toward third-party commercial service providers. Ecolab leverages its institutional hygiene portfolio to anchor contracts with hospital networks and hotel chains. Procter & Gamble competes through concentrated dosing systems that reduce freight and storage burdens for high-volume buyers. Stepan Company specializes in surfactant chemistry, supplying base materials to formulators while sustaining backward integration into bio-based feedstocks.
Commercial laundry detergent comprises surfactant-based cleaning formulations engineered for high-temperature wash cycles, typically containing alkylbenzene sulfonates, ethoxylated alcohols, and alkaline builders at pH ranges of 9–11. These products serve industrial laundries processing linens, uniforms, and textiles at volumes exceeding five hundred kilograms per cycle. Liquid detergent occupies the dominant revenue position due to automated dosing compatibility and reduced residue on commercial equipment. Specialty detergent represents the fastest-expanding category as healthcare and food-service sectors impose sterilization-grade performance standards. Pods remain limited in commercial settings because bulk packaging economics favor drums and refillable bulk containers for continuous operations.
The EPA regulates surfactant biodegradability under Clean Water Act discharge standards, while the EU REACH framework restricts phosphonate and quaternary ammonium compound concentrations in institutional formulations. OSHA workplace exposure limits further constrain volatile organic compound levels in commercial laundry environments. Stakeholders must monitor evolving state-level chemical disclosure mandates and weigh reformulation investments against private-label substitution risks in contract negotiations.
Market Dynamics
Centralized linen-service outsourcing across hospitality and healthcare sectors is consolidating procurement power into fewer buyers, forcing formulators to restructure pricing and service models around volume guarantees and technical support rather than transactional drum sales.
Growth Catalysts
- EPA Safer Choice compliance:Federal biodegradability mandates under the Clean Water Act are accelerating surfactant reformulation toward ethoxylated alcohols and bio-based builders that discharge safely into municipal water systems.
- Hospitality outsourcing:Hotel chains across the United States and Germany are divesting on-premise laundry assets and contracting regional commercial processors, creating sustained bulk demand for automated dosing-compatible liquid formulations.
- High-temperature wash engineering:Alkaline builders at pH 9–11 are enabling sterilization-grade performance in healthcare textile processing without supplemental chlorine bleach cycles.
Market Restraints
- Palm kernel oil volatility:Bio-based surfactant feedstocks face price swings tied to Southeast Asian agricultural output, compressing margin stability for formulators committed to renewable chemistry.
- REACH phosphonate restrictions:EU ECHA limits on quaternary ammonium compounds are forcing costly reformulation of institutional detergents serving European healthcare and food-service accounts.
- Limited pod economics:Single-use packaging formats cannot achieve unit-cost parity with bulk drum systems in continuous-feed commercial operations, constraining format innovation.
Strategic Opportunities
- Japan's aging commercial infrastructure:Replacement cycles for centralized laundry equipment in Tokyo-Osaka industrial corridors create openings for integrated detergent-dosing system suppliers.
- EU Green Deal procurement incentives:Public hospital and municipal linen contracts now weight lifecycle carbon metrics, advantaging formulators with verified bio-based supply chains.
- Enzyme-surfactant convergence:Protease and lipase stabilization in high-pH formulations is enabling lower-temperature wash protocols that reduce energy costs for industrial laundries.
Industry Challenges
- Surfactant chemist scarcity:Formulation expertise in alkylbenzene sulfonate alternatives and bio-based feedstock compatibility is concentrated among retiring specialists with limited pipeline replacement.
- OSHA VOC compliance timelines:Workplace exposure limit documentation for reformulated low-volatility products delays contract renewals with hospital networks requiring rapid vendor recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Laundry Detergent Market |
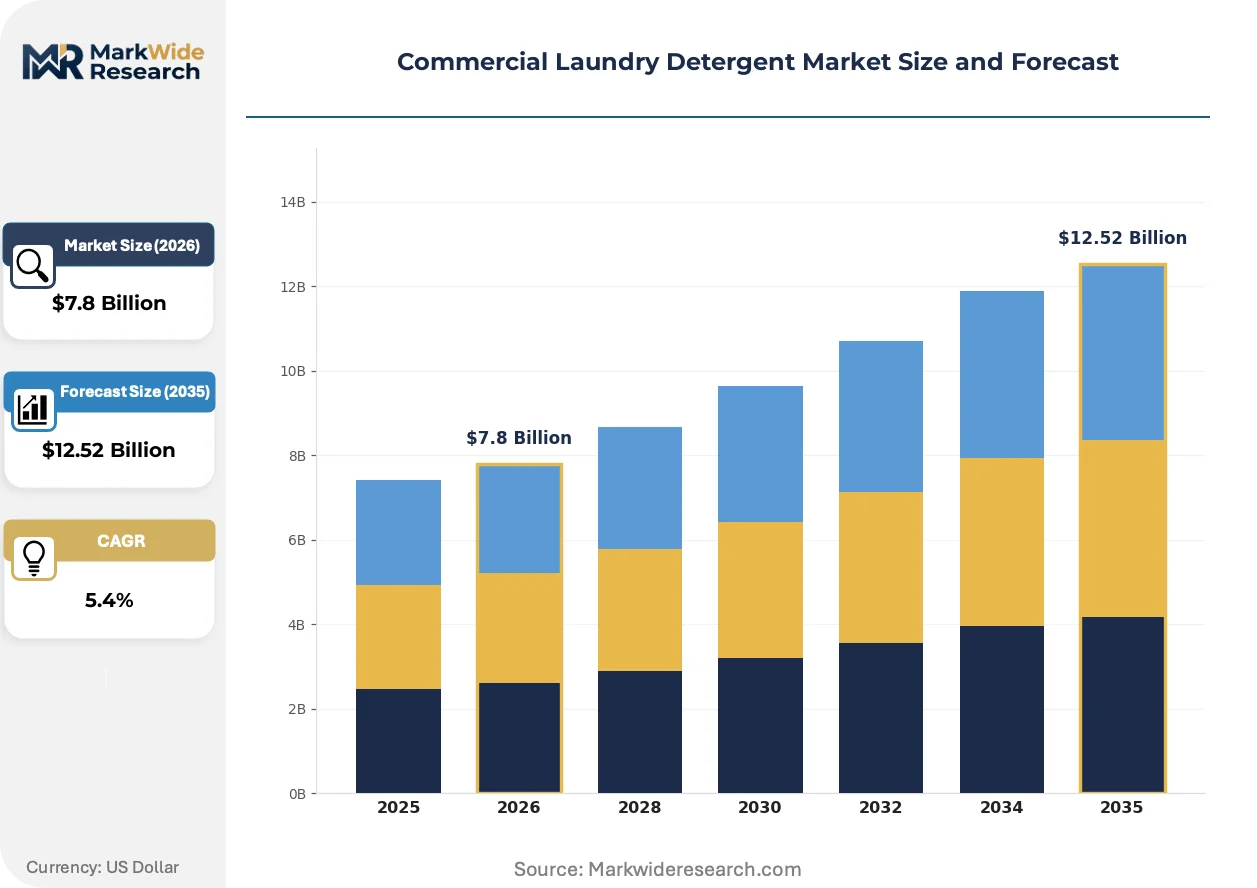
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Detergent, Powder Detergent, Pods, Specialty Detergent Customer Type: Hotels, Restaurants, Dry Cleaners, Laundromats Packaging Type: Bottles, Bulk Containers, Sachets, Drums Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Ecolab, BASF, Procter & Gamble, Stepan Company, Solvay, Unilever, Kao Corporation, Croda International, The Clorox Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Laundry Detergent Market Strategic Shifts
Formulation chemistry and service delivery models are diverging sharply as regulatory pressure and buyer consolidation force simultaneous investment in sustainable inputs and outcome-based contracting structures.
Enzyme-stabilized detergents are decomposing traditional high-alkaline formulations in healthcare textile processing. Hospital networks in Germany and Japan are adopting protease-lipase blends at accelerating rates. This transition is decomposing the historical trade-off between thermal energy costs and sterilization assurance, enabling lower-temperature protocols without performance sacrifice.
REACH authorization requirements for quaternary ammonium biocides are tightening discharge standards for commercial laundries serving EU food-service and healthcare sectors. ECHA's evolving restricted substances list is forcing formulators to document biodegradability pathways for surfactant metabolites. Specialty detergent producers serving Netherlands and French hospital consortia are accelerating phosphonate-free builder development to preempt compliance deadlines.
Buyer consolidation among third-party linen service providers is compressing vendor counts and extending contract durations. Regional processors across the United States are demanding integrated chemical-dosing equipment leases bundled with detergent supply. This restructuring is most visible in Texas and Florida healthcare outsourcing markets, where multi-facility hospital systems are awarding five-year exclusive agreements to single-source hygiene service platforms.
Commercial Laundry Detergent Market Segmentation
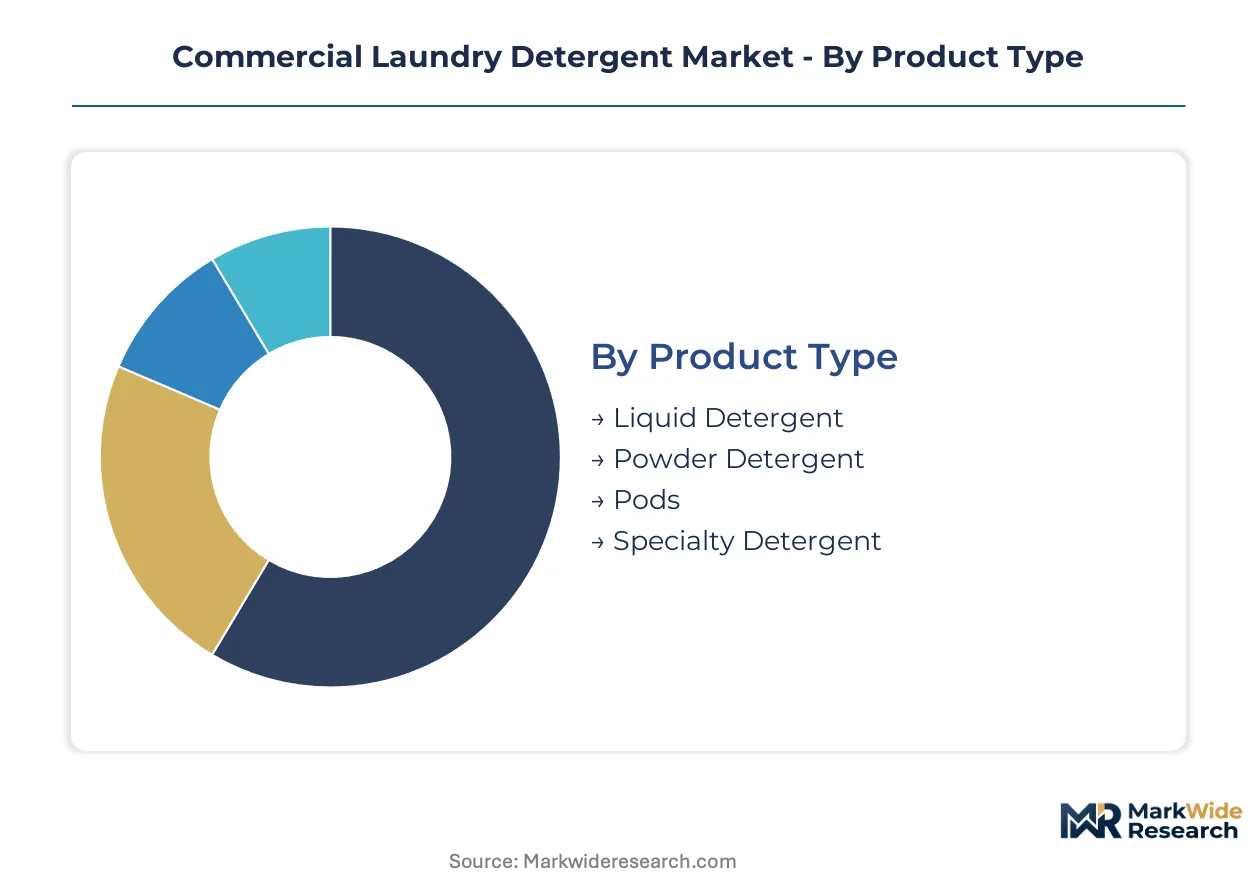
Segmentation in commercial laundry detergent reveals how procurement power, dosing infrastructure, and regulatory exposure fragment demand across incompatible operational models. Channel alignment and format economics determine which formulations capture volume in hospitality, healthcare, and food-service verticals.
Product Type:
Liquid formulations flow through automated dosing systems in industrial laundries, while powder and specialty variants serve segmented niches with distinct technical requirements and margin profiles.
- Liquid Detergent:Alkylbenzene sulfonate and ethoxylated alcohol blends engineered for pH 9–11 alkaline wash cycles integrate seamlessly with continuous-feed dosing equipment. Hospitality outsourcing contracts in the United States and Germany specify liquid formats exclusively to minimize residue buildup on high-throughput tunnel washers.
- Specialty Detergent:Protease-lipase enzyme blends and sterilization-grade formulations target healthcare textile processing where thermal energy reduction intersects with infection control mandates. Hospital networks in Japan and Germany are accelerating adoption to meet EU Green Deal procurement incentives and lower-temperature protocol requirements.
- Powder Detergent:Alkaline builder concentrates retain relevance in legacy on-premise operations with manual dosing infrastructure.
- Pods:Single-unit packaging faces structural exclusion from commercial drum economics and bulk procurement contracts.
By volume, liquid detergent leads. By growth pace, specialty detergent is ahead.
Customer Type:
Procurement concentration varies sharply across customer tiers, with consolidated hospitality chains demanding integrated service platforms while fragmented dry cleaners transact through wholesale distributors.
- Hotels:Divestment of on-premise laundry assets across North American and European chains is consolidating linen-service outsourcing into regional commercial processors. Bulk procurement contracts now bundle detergent supply with equipment leasing and technical support, compressing vendor counts and extending durations.
- Laundromats:Self-service and attended coin-op facilities in Japan's Tokyo-Osaka corridor are entering replacement cycles for centralized equipment, creating openings for integrated chemical-dosing system suppliers. Aging infrastructure and municipal water discharge standards are accelerating upgrade timelines.
- Restaurants:Food-service textile processing faces REACH phosphonate restrictions and quaternary ammonium compound limits in EU markets.
- Dry Cleaners:Perchloroethylene transition pressures and solvent substitution trends are reshaping chemical procurement patterns.
Hotels command the largest contract values. Laundromats show the steepest equipment-driven replacement demand.
Packaging Type:
Format selection tracks operational scale and dosing automation level, with bulk systems dominating continuous-feed environments and smaller formats serving intermittent or mobile operations.
- Drums:Refillable bulk containers achieve unit-cost parity essential for automated dosing systems in industrial laundries processing five hundred-plus kilograms per cycle. EPA Safer Choice compliance documentation and REACH biodegradability certifications are increasingly bundled with drum supply contracts.
- Bulk Containers:Intermediate-format totes serve mid-scale regional processors with flexible volume commitments and reduced freight intensity versus smaller packaging.
- Bottles:Manual-dose formats persist in on-premise hospitality operations with legacy infrastructure.
- Sachets:Single-use packets address mobile or emergency textile processing with minimal capital equipment.
Drums anchor procurement economics. Bulk containers are gaining traction among scaling regional processors.
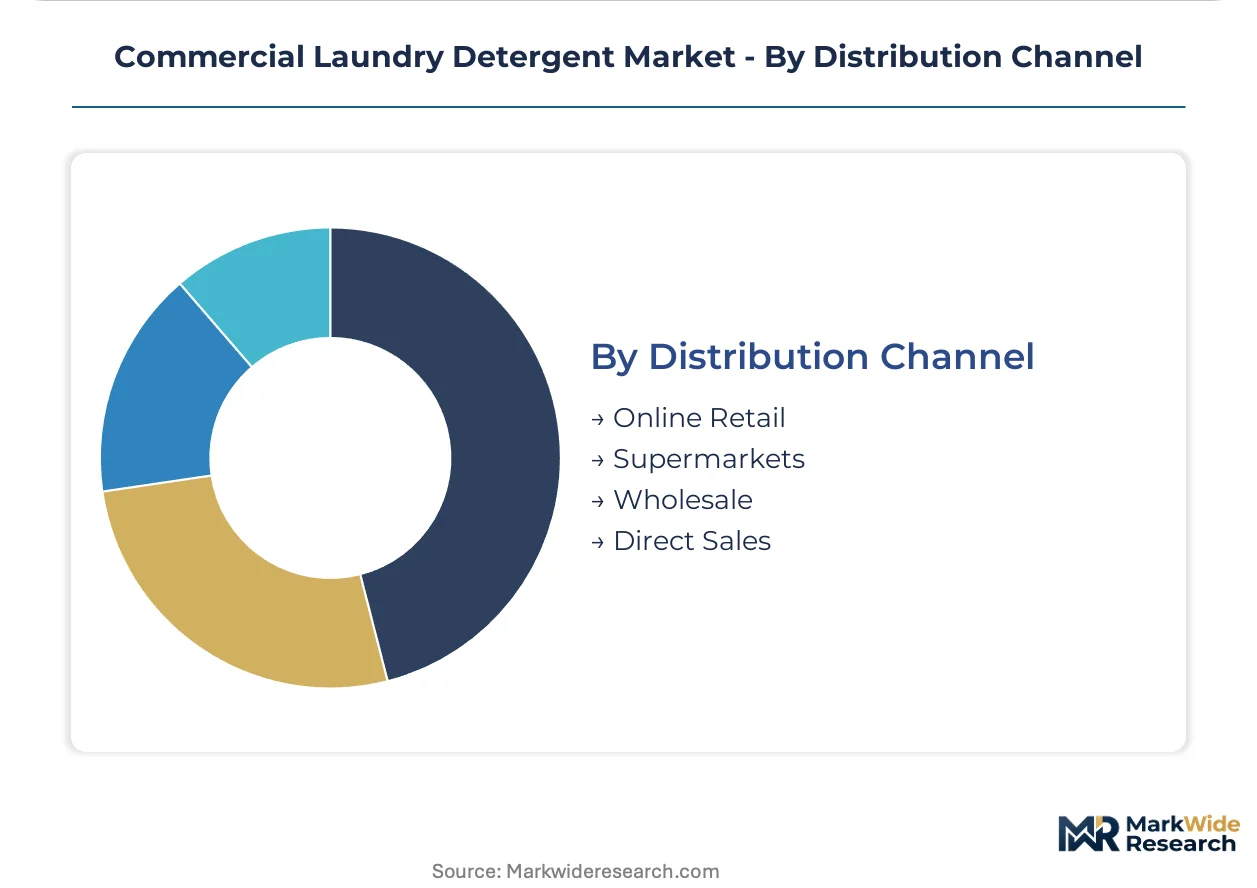
Distribution Channel:
Channel structure reflects buyer consolidation and technical service requirements, with direct relationships displacing arm's-length transactions in high-volume accounts.
- Direct Sales:Integrated chemical-dosing equipment leases bundled with detergent supply are restructuring vendor relationships in Texas and Florida healthcare outsourcing markets. Five-year exclusive agreements with single-source hygiene service platforms are displacing transactional drum sales.
- Wholesale:Regional distributors serve fragmented dry cleaner and independent laundromat accounts with inventory pooling and technical support limitations.
- Online Retail:E-procurement platforms capture spot purchases and smaller-volume accounts without service integration requirements.
- Supermarkets:Consumer-facing retail channels retain minimal relevance for institutional-grade formulations.
Direct sales capture the largest contract values. Online retail is expanding fastest among unserved small-account segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German formulators export alkylbenzene sulfonate blends to hospital networks across Central Europe. United States producers ship concentrated liquid systems to Canadian hospitality chains seeking automated dosing compatibility.
United States
Hospital networks in Texas and Florida are awarding exclusive linen-service contracts to single-source hygiene platforms. EPA Safer Choice compliance documentation now accompanies drum supply agreements for municipal water discharge safety. Regional processors in the Southeast are bundling chemical-dosing equipment leases with detergent procurement.
Germany
Hotel chains are divesting on-premise laundry assets and contracting regional commercial processors at accelerating rates. EU REACH phosphonate restrictions are forcing reformulation of institutional detergents serving healthcare accounts. The Rhine-Ruhr industrial corridor hosts concentrated surfactant production serving Benelux export markets.
Japan
Laundromats in the Tokyo-Osaka corridor are entering replacement cycles for aging centralized equipment. METI efficiency standards are accelerating upgrade timelines for commercial washing infrastructure. Kansai-based processors are adopting integrated chemical-dosing systems to meet municipal water discharge regulations.
France
Food-service textile processors face tightening ECHA limits on quaternary ammonium biocides in discharge water. EU Green Deal procurement incentives are weighting lifecycle carbon metrics in public hospital contracts. The Île-de-France region concentrates demand from hospitality and healthcare outsourcing consortia.
United Kingdom
Independent regional linen services are consolidating procurement power into fewer buyers with extended contract durations. HSE workplace exposure documentation requirements are delaying vendor recertification timelines for reformulated low-volatility products. The Midlands industrial cluster retains legacy on-premise operations with manual dosing infrastructure.
Commercial Laundry Detergent Market Competitive Environment
Listed leaders compete with private specialists across institutional hygiene and surfactant chemistry. The vendor base organizes around three archetypes: diversified chemical conglomerates with backward integration into bio-based feedstocks, institutional hygiene platforms bundling equipment leases with chemical supply, and pure-play surfactant specialists supplying base materials to third-party formulators. Dominant competitive moves include vertical integration into renewable feedstock cultivation and outcome-based contracting structures that replace transactional drum sales.
Within the institutional hygiene tier, Ecolab and Procter & Gamble occupy positions anchored by hospital network and hotel chain relationships. Stepan Company exemplifies the surfactant specialist archetype, supplying base materials while maintaining upstream control over bio-based feedstock development. These three entities represent distinct strategic postures: service integration, concentrated dosing innovation, and chemical supply chain mastery.
| Leading Market Players |
|---|
| Ecolab |
| BASF |
| Procter & Gamble |
| Stepan Company |
| Solvay |
| Unilever |
| Kao Corporation |
| Croda International |
| The Clorox Company |
| Others |
Value Chain & Pricing Dynamics
EPA Safer Choice certification gates both supplier qualification and price tiering simultaneously, separating drum-format biodegradable formulations from uncertified commodity alternatives in contract negotiations with hospital networks and hospitality chains.
Pricing Analysis
Legacy high-alkaline formulations trade at commodity parity against enzyme-stabilized next-generation detergents commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects EPA compliance tier, volume commitment scale, and bundled equipment lease inclusion. Cost compression in standard-tier alkylbenzene sulfonate blends is intensifying because Southeast Asian palm kernel oil feedstock volatility feeds through to surfactant base costs. Independent laundromats and dry cleaners exhibit highest price sensitivity, while consolidated hospital networks prioritize technical service integration over unit cost.
Supply Chain Analysis
Malaysia and Indonesia anchor global palm kernel oil cultivation for bio-based surfactant feedstocks, while Germany and the United States concentrate alkylbenzene sulfonate and ethoxylated alcohol production. Formulation chemistry draws from petrochemical derivatives, tropical oleochemicals, and enzyme cultivation batches. Single-source vulnerability concentrates in Southeast Asian agricultural output exposed to climate disruption and export policy shifts. Distribution runs through direct sales teams for high-volume institutional accounts and regional wholesale distributors serving fragmented downstream operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among third-party linen service providers fragments procurement into discrete regional niches, creating entry openings for specialized formulators targeting compliance-heavy healthcare verticals.
For Market Incumbents: Fortify contract renewal rates by embedding EPA Safer Choice documentation and REACH biodegradability certifications into five-year exclusive agreements with Texas and Florida hospital networks. Backward integration into captive bio-based feedstock supply hedges palm kernel oil volatility exposure. Priority investment targets enzyme stabilization R&D to defend against protease-lipase specialists eroding high-alkaline formulation share. For New Entrants and Emerging Players: Anchor in Japan's Tokyo-Osaka laundromat equipment replacement cycle, where aging centralized infrastructure and METI efficiency standards create unserved demand for integrated chemical-dosing system suppliers. EU Green Deal procurement incentives in French and Dutch hospital consortia offer second penetration vector. Go-to-market positioning emphasizes lifecycle carbon verification and phosphonate-free builder credentials. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional linen service platforms consolidating procurement power across Southeastern United States healthcare markets. Five-to-ten year viability hinges on contract duration extension and exclusive vendor lock-in achievement. Signal to monitor: ECHA authorization timeline acceleration for quaternary ammonium biocide restrictions triggering reformulation capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive palm kernel oil supply from Malaysia and Indonesia insulates margin stability against agricultural volatility. |
| Enzyme Stabilization R&D Investment | Protease-lipase compatibility at pH 9–11 enables lower-temperature healthcare protocols without sterilization sacrifice. |
| Integrated Equipment-Dosing System Leasing | Five-year exclusive contracts with Texas hospital networks displace transactional drum sales and compress vendor counts. |
| REACH Phosphonate-Free Reformulation | Preemptive ECHA compliance in Netherlands and French hospital consortia secures contract renewal eligibility. |
| Regional Linen Service Platform Acquisition | Consolidated procurement power in Florida healthcare outsourcing markets extends detergent supply contract durations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across hospital procurement managers, commercial laundry plant engineers, surfactant R&D directors, and institutional distribution channel partners. Secondary validation incorporated EPA Safer Choice certified product listings, ECHA REACH restricted substances notifications, U.S. customs trade data for surfactant imports, and SEC 10-K filings from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Across the analysis window, projections segmented by product type, customer vertical, packaging format, and distribution channel with regional regulatory cluster overlays. CAGRs derived from historical volume trajectories adjusted for hospitality outsourcing acceleration and healthcare sterilization-grade specification tightening. Industry-specific inputs included enzyme adoption rates in German hospital networks and Japanese laundromat equipment replacement cycles.
Underlying assumptions cover EPA biodegradability mandate enforcement continuity and EU REACH authorization timeline adherence, with deviation risk concentrated in Southeast Asian palm kernel oil supply disruption and OSHA VOC workplace exposure limit acceleration. Recalibration cycles align with material shifts in ECHA restricted substances list updates and hospital network consolidation event frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Commercial Cleaning Service Market