
 Household Cleaning Tools and Supplies Market | 2026-2036
Household Cleaning Tools and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Household Cleaning Tools and Supplies Market Analysis
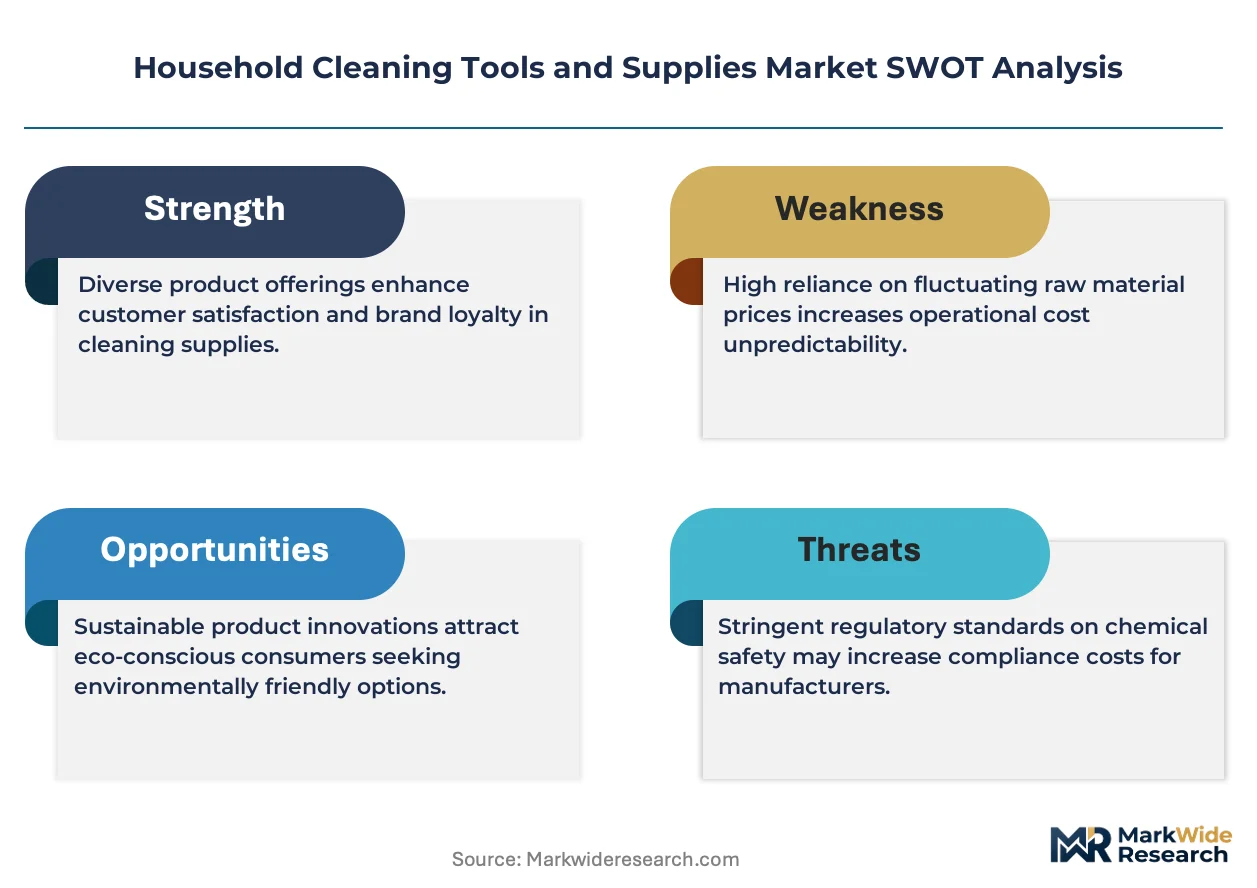
Refill and concentrate revenue is rewriting profitability maps across the industry. Procter & Gamble leverages its global distribution network to push pod-based and dilutable formats into mainstream retail. Henkel anchors its position in European markets through concentrated formulations that reduce packaging intensity and shipping costs. The Clorox Company competes on brand trust in disinfectant categories, sustaining premium shelf placement through institutional certification programs.
Household cleaning tools and supplies encompass chemically formulated agents and physical implements designed to remove soil, pathogens, and allergens from residential and commercial environments, with surfactant concentrations typically ranging from five to twenty percent in ready-to-use liquid products and pH levels engineered for surface compatibility. These products serve the fundamental commercial purpose of maintaining sanitary conditions that comply with health codes and reduce disease transmission in occupied spaces. Surface cleaners and disinfectants command the largest revenue share due to their universal application across home and institutional settings, while spray formats are capturing faster growth as consumers prioritize convenience and controlled dosage over traditional liquid pour bottles. Fabric-based cleaning tools, including microfiber mops and cloths, are gaining traction as reusable alternatives that align with waste-reduction preferences in commercial cleaning contracts.
The EPA regulates antimicrobial claims through FIFRA registration requirements, compelling manufacturers to substantiate efficacy data before marketing disinfectant properties. The EU REACH framework and F-Gas Regulation restrict certain solvent chemistries and propellant systems, redirecting formulation investment toward plant-derived active ingredients. OSHA guidelines for workplace chemical hazard communication further shape product labeling and safety data sheet obligations in commercial channels. Stakeholders must monitor how fragmented state-level ingredient disclosure laws in the United States evolve against the backdrop of harmonized European standards.
Market Dynamics
Concentrated refill and concentrate formats are compressing packaging costs and logistics footprints across the household cleaning tools and supplies market, forcing incumbent liquid-format suppliers to reconfigure production lines and distribution economics.
Growth Catalysts
- Healthcare facility expansion:Hospital and long-term care construction in the United States is absorbing institutional-grade disinfectant volumes at contract scale.
- REACH framework compliance:European Union chemical registration requirements are accelerating biodegradable surfactant substitution in spray formulations.
- Microfiber adoption:Commercial cleaning contractors are standardizing reusable fabric tools to meet waste-reduction clauses in municipal procurement contracts.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent input costs fluctuate with crude oil derivatives, compressing margin stability for mid-tier formulators.
- Propellant chemistry restrictions:The EU F-Gas Regulation limits hydrofluorocarbon aerosol systems, forcing capital-intensive retooling of spray product lines.
- Private-label substitution:Retailer-owned disinfectant brands are capturing shelf space through price undercutting in standard surface cleaner categories.
Strategic Opportunities
- Indian urban sanitation programs:Swachh Bharat Mission infrastructure investment is creating first-time household disinfectant demand in tier-two cities.
- Subscription replenishment channels:Direct-to-consumer concentrate pod services are bypassing traditional retail slotting fees in North American markets.
- Green chemistry tax incentives:United States IRA clean manufacturing credits are offsetting R&D costs for plant-derived active ingredient development.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in pH-stable biodegradable surfactants commands premium compensation and extends product development timelines.
- FIFRA registration delays:EPA antimicrobial claim substantiation requires 12-18 month efficacy study completion before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Cleaning Tools and Supplies Market |
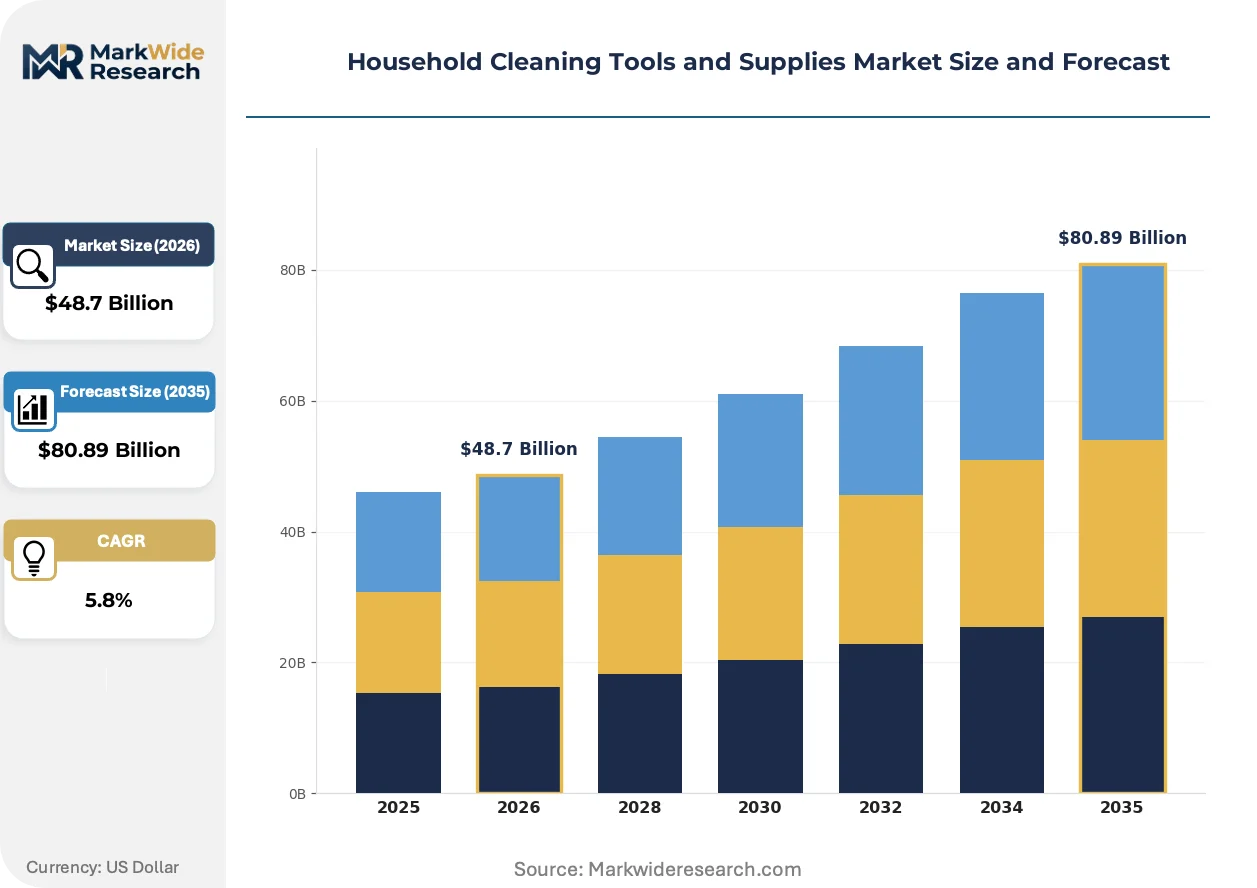
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Floor Cleaners, Disinfectants, Window Cleaners Material: Plastic, Metal, Fabric, Wood Form: Spray, Liquid, Powder, Wipes Application: Home Use, Commercial Use, Industrial Use, Institutional Use |
| Companies Covered | Church & Dwight Co., Inc., Reckitt, Procter & Gamble, 3M Company, Henkel, The Clorox Company, Colgate-Palmolive, Freudenberg Group, S.C. Johnson & Son, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Cleaning Tools and Supplies Market Emerging Trajectories
Connected dispensing hardware and sensor-enabled dosage control are embedding intelligence into cleaning protocols, shifting competitive advantage from chemical formulation precision to data-driven usage optimization.
Smart dispensing systems equipped with RFID-enabled concentrate cartridges are digitizing inventory management for commercial cleaning fleets. Facility management operators in United States healthcare and hospitality verticals are piloting these units to eliminate manual dilution errors and track consumption per square foot. The technology is digitizing procurement workflows by automating reorder triggers and compressing emergency stockholding requirements.
EPA Safer Choice and EU Ecolabel harmonization discussions are converging disclosure standards for volatile organic compound limits and aquatic toxicity thresholds. Manufacturers serving transatlantic distribution channels face dual certification pathways that raise compliance overhead but create premium positioning for products meeting both frameworks. Surface cleaner segments with institutional contract exposure are reformulating fastest to capture specified procurement preferences.
Buyers in United States professional cleaning services are consolidating supplier relationships around full-protocol vendors who bundle chemicals, tools, and training into single-source contracts. This behavior is displacing fragmented purchasing across separate chemical, equipment, and consumable suppliers. The shift concentrates volume with integrated providers and compresses margins for standalone product manufacturers lacking service capabilities.
Household Cleaning Tools and Supplies Market Segmentation
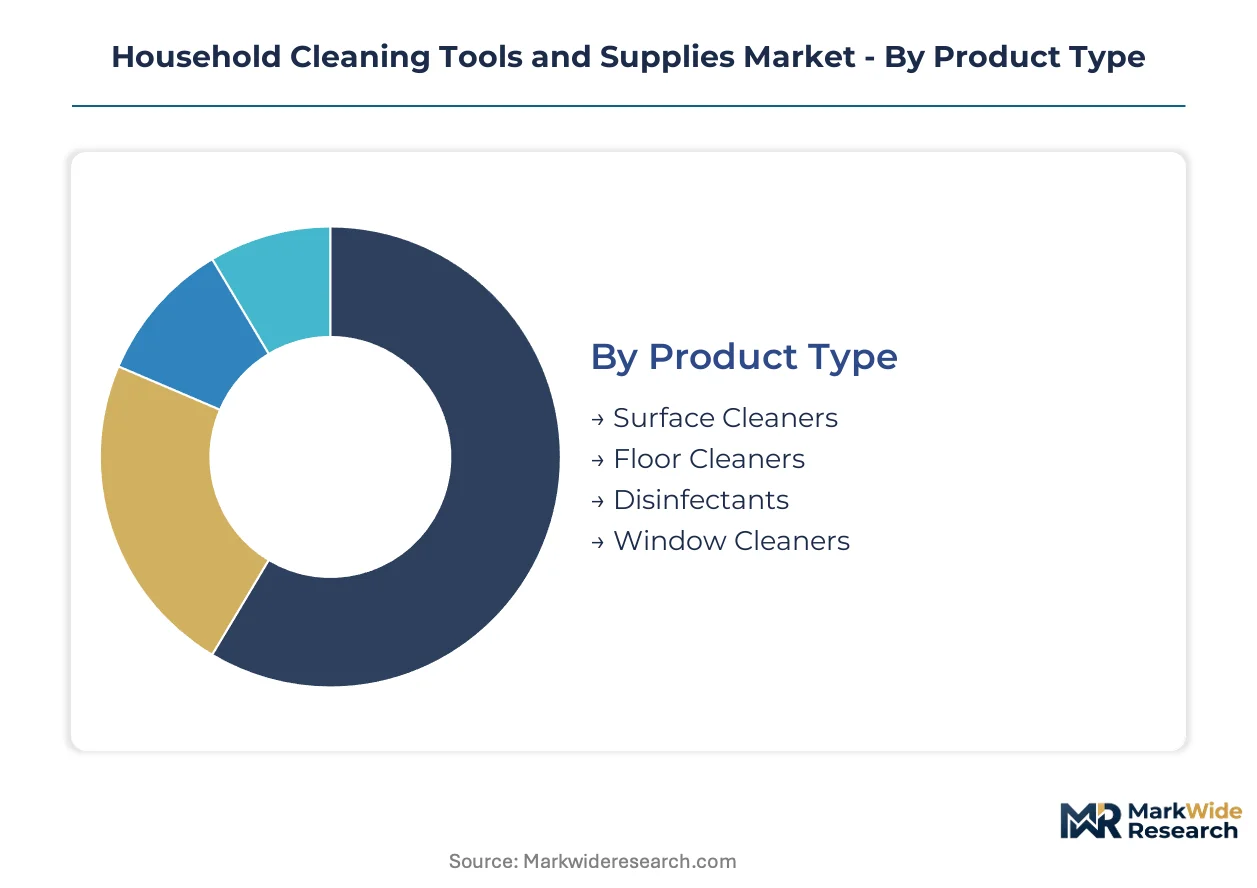
Segmentation in household cleaning tools and supplies reveals how formulation chemistry, material durability, and delivery mechanisms align with distinct usage intensities across residential and professional environments. These divisions expose where margin concentrates and where volume scales.
Product Type:
Use-case spectrum spans routine soil removal to pathogen elimination, with each category commanding different certification requirements and procurement channels.
- Surface Cleaners:Formulations with pH-balanced surfactant systems between 5-20% concentration handle countertops, appliances, and fixtures without substrate damage. Hospital procurement departments in the United States specify these for non-critical touchpoint maintenance, prioritizing EPA Safer Choice credentials to satisfy joint commission audits.
- Disinfectants:Antimicrobial agents requiring FIFRA registration carry substantiated kill-claims against specific pathogen classes. Healthcare facility expansion across the United States absorbs institutional-grade volumes through multi-year supply contracts, though EPA efficacy study timelines extend development cycles.
- Floor Cleaners:Specialized formulations address hardwood, tile, and composite surface compatibility with residue-minimizing chemistry.
- Window Cleaners:Ammonia and ammonia-free variants target streak elimination on glass and mirrored surfaces.
The dominant share belongs to Surface Cleaners, while Disinfectants is closing the gap fastest.
Material:
Cost tier stratification separates disposable consumables from capital-equipment durability expectations in commercial cleaning contracts.
- Plastic:Polypropylene and polyethylene dominate spray bottles, trigger mechanisms, and bucket assemblies due to chemical resistance and injection-molding economies. Municipal procurement contracts in the United States increasingly specify post-consumer recycled content thresholds, forcing resin sourcing adjustments.
- Fabric:Microfiber constructions with denier ratings below 0.3 enable particle capture without chemical dependency. Commercial cleaning contractors standardize reusable cloth and mop systems to satisfy waste-reduction clauses in European municipal tenders.
- Metal:Stainless steel and aluminum reinforce structural components in professional-grade equipment.
- Wood:Traditional handles and specialty brushes serve premium residential segments and aesthetic-conscious hospitality settings.
Plastic commands the volume base, though Fabric is expanding most quickly on sustainability mandates.
Form:
Volume economics and logistics footprint differentiate delivery mechanisms, with concentrate formats disrupting traditional ready-to-use packaging.
- Spray:Aerosol and trigger-dispense systems enable controlled dosage and reduced waste versus pour applications. EU F-Gas Regulation restrictions on hydrofluorocarbon propellants force capital-intensive retooling of aerosol lines toward compressed gas or pump alternatives.
- Liquid:Pour bottles and refill concentrates represent the historical standard, with dilutable formats compressing shipping costs.
- Powder:Low-moisture formulations reduce packaging mass for bulk institutional supply.
- Wipes:Pre-saturated substrates deliver convenience in healthcare quick-turnover and food-service compliance settings.
Liquid retains the largest installed base, while Spray climbs the fastest on convenience premiums.
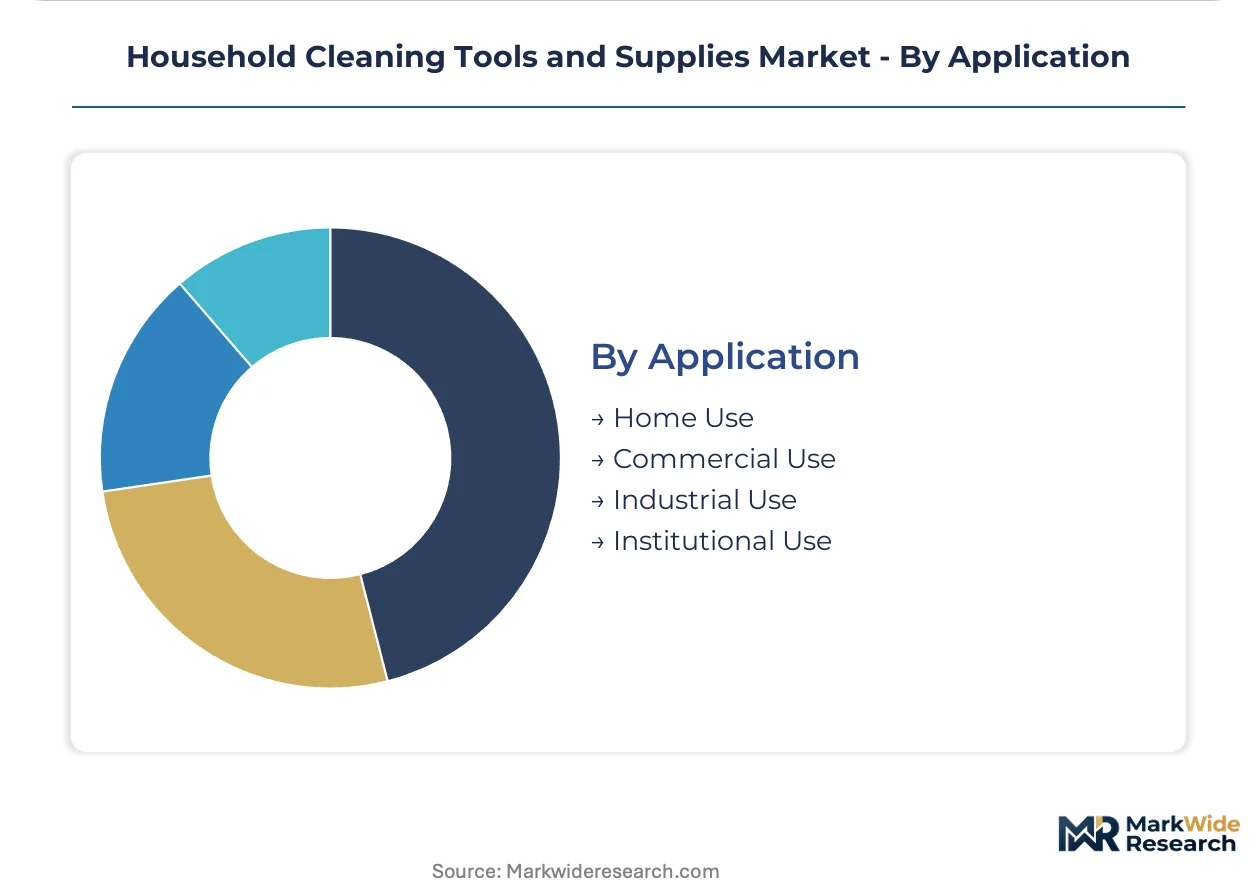
Application:
Customer type determines specification intensity, with institutional buyers imposing certification and training requirements absent in residential channels.
- Commercial Use:Professional cleaning services, hospitality, and retail facilities demand full-protocol suppliers bundling chemicals, tools, and compliance documentation. United States contract cleaners consolidate purchasing around integrated vendors, displacing fragmented supplier relationships.
- Home Use:Individual consumers prioritize convenience formats and brand recognition through retail and direct-to-subscription channels.
- Industrial Use:Manufacturing and warehouse environments require heavy-duty degreasers and specialized equipment for safety compliance.
- Institutional Use:Schools, government facilities, and correctional institutions operate under public procurement rules with mandated disclosure and competitive bidding.
Commercial Use holds the revenue concentration, while Home Use is gaining share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. United States buyers absorb premium disinfectant formulations through institutional contracts, while Indian households remain highly sensitive to per-unit costs in emerging urban markets.
United States
Hospital construction and long-term care facility expansion drive institutional-grade disinfectant absorption through multi-year supply agreements. EPA FIFRA registration requirements extend product development timelines to 12-18 months for antimicrobial claim substantiation. The Chicago-Milwaukee corridor concentrates professional cleaning service headquarters consolidating vendor relationships around full-protocol suppliers.
Germany
REACH framework compliance accelerates biodegradable surfactant substitution in spray formulations across industrial and commercial channels. The EU F-Gas Regulation restricts hydrofluorocarbon propellant systems, forcing capital-intensive retooling of aerosol production lines. The Rhine-Ruhr industrial cluster hosts concentrated formulation R&D facilities serving transatlantic distribution networks.
China
Urban sanitation infrastructure investment and rising middle-class hygiene awareness expand household disinfectant penetration in tier-two cities. The country's national environmental regulator enforces volatile organic compound limits on surface cleaner formulations. The Yangtze River Delta manufacturing belt supplies global private-label brands with cost-optimized spray and liquid packaging systems.
India
Swachh Bharat Mission infrastructure programs create first-time disinfectant demand in rapidly urbanizing secondary cities. Bureau of Indian Standards certification requirements shape product safety labeling for domestic market entry. The Mumbai-Pune industrial corridor concentrates contract manufacturing capacity for regional brand owners targeting price-conscious mass-market segments.
United Kingdom
Post-pandemic hospitality sector recovery sustains commercial cleaning service expansion and premium product specification. HSE workplace chemical hazard communication guidelines mandate detailed safety data sheet obligations for institutional procurement channels. Greater London hosts headquarters operations for European distribution networks managing cross-border compliance with dual EU-UK regulatory frameworks.
Household Cleaning Tools and Supplies Market Vendor Landscape
Capability concentration sits with specialized formulators possessing FIFRA registration expertise and biodegradable surfactant chemistry; scale advantage sits with diversified consumer goods conglomerates leveraging global distribution infrastructure. The market structures around three tiers: multinational brand owners commanding retail shelf space, mid-tier private-label suppliers serving cost-sensitive channels, and niche specialists targeting institutional certification requirements. Dominant competitive moves include portfolio diversification into concentrate and pod formats and backward integration into surfactant manufacturing to secure input cost stability.
Among the diversified multinational tier, Procter & Gamble and Henkel occupy positions defined by global scale and regional formulation adaptation, while The Clorox Company exemplifies brand-trust anchoring in disinfectant categories through institutional certification relationships. These entities represent distinct archetypes: the former pair leverage distribution density and concentrated format innovation, while the latter maintains premium positioning through regulatory compliance depth and healthcare channel penetration.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Reckitt |
| Procter & Gamble |
| 3M Company |
| Henkel |
| The Clorox Company |
| Colgate-Palmolive |
| Freudenberg Group |
| S.C. Johnson & Son |
| Others |
Supply Flow & Price Mechanics
Petrochemical surfactant concentration in the Yangtze River Delta and Rhine-Ruhr corridor directly determines where margin pools accumulate downstream, with formulation specialists capturing premium spreads while private-label assemblers compete on logistics efficiency.
Pricing Analysis
After-sales service contracts and subscription replenishment programs now drive lifetime value more than initial product transactions. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered disinfectants from Safer Choice-certified surface cleaners from unbranded private-label alternatives. Price differentiation hinges on institutional certification depth and geographic delivery density. Pricing pressure stems from retailer-owned brand expansion in standard surface cleaner categories. Home use segments exhibit highest price sensitivity, while healthcare procurement departments absorb premiums for validated kill-claims.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for spray packaging and concentrate cartridge sourcing. Manufacturing concentration spans China, Germany, and India for finished formulations, with China supplying bulk surfactant intermediates and India providing contract manufacturing for regional brands. Raw material dependencies center on palm-derived feedstocks, petroleum-based solvents, and post-consumer recycled resins. Single-source vulnerability persists in specialized biodegradable surfactant chemistry. Distribution runs through consolidated retail networks in North America and fragmented wholesale channels in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in pH-stable biodegradable surfactants remains scarce relative to demand, compressing product development timelines and inflating compensation for qualified formulation chemists across the industry.
For Market Incumbents: Harden institutional certification portfolios against FIFRA registration delays by maintaining parallel efficacy study pipelines. Deepen backward integration into surfactant manufacturing to neutralize petrochemical feedstock volatility. Consolidate vendor relationships around full-protocol service capabilities to displace fragmented chemical-tool-consumable suppliers. For New Entrants and Emerging Players: Establish a beachhead in Indian tier-two urban sanitation programs where first-time disinfectant demand outpaces established supply infrastructure. Target subscription replenishment channels in North America to bypass retail slotting fee barriers. Leverage green chemistry tax incentives under United States IRA provisions to offset plant-derived active ingredient R&D costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier private-label suppliers serving European municipal procurement contracts. Long-term viability favors specialists with captive biodegradable surfactant chemistry and transatlantic dual-certification capabilities. Monitor EPA Safer Choice and EU Ecolabel harmonization progress as inflection indicator for premium positioning consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Manufacturing | Captive supply of palm-derived and petroleum-based feedstocks insulates margin from crude oil derivative volatility. |
| Dual-Certification Investment | Simultaneous EPA Safer Choice and EU Ecolabel compliance unlocks premium procurement channels in transatlantic institutional markets. |
| Subscription Channel Launch | Direct-to-consumer concentrate pod services bypass traditional retail slotting fees and capture recurring revenue streams. |
| Smart Dispensing Hardware Deployment | RFID-enabled systems digitize inventory management for United States healthcare facility management operators. |
| Biodegradable Surfactant R&D Expansion | Plant-derived active ingredient development aligns with REACH framework compliance and green chemistry tax incentive eligibility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists, commercial cleaning contract managers, hospital procurement directors, and retail category buyers. Secondary validation drew from EPA FIFRA registration databases, EU REACH substance dossiers, customs trade records, and institutional procurement contract filings. Bottom-up volume estimates triangulated against top-down market sizing across product type, material, form, and application dimensions.
Calibration against historical absorption patterns in healthcare facility expansion and subscription channel penetration anchored the analytical framework across the projection horizon. Segmentation modeling spanned formulation chemistry tiers, delivery mechanism formats, end-use intensity levels, and regional regulatory clusters. CAGRs were derived from weighted scenario analysis incorporating feedstock cost trajectories and certification adoption curves. Industry-specific inputs included EPA efficacy study completion timelines and EU F-Gas Regulation compliance capital requirements.
Sensitivities concentrate around petrochemical feedstock volatility, FIFRA registration delays, and harmonization progress between EPA Safer Choice and EU Ecolabel standards. Forecasts reflect documented assumptions regarding healthcare construction absorption rates and urban sanitation program execution timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Cleaning Services Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Countertop Spray Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Screen Cleaner Market