
 Spin Mops Market | 2026-2036
Spin Mops Market Size, Share, and Industry Trends Forecast 2026-2036
Spin Mops Market Outlook
A capital-intensity divergence between integrated manufacturers and assembly-only competitors is rotating competitive dynamics in the spin mops sector. O-Cedar leverages captive microfiber production to control input costs and quality consistency across its bucket mop lines. Freudenberg Group anchors its position through synthetic fiber technology leadership that supplies multiple downstream brands. Vileda competes on European retail channel density, sustaining shelf presence in hypermarket chains across Germany, France, and Italy.
Spin mops are centrifugal-force cleaning devices comprising a bucket-mounted wringing mechanism and detachable fiber head, typically constructed from polypropylene housings and microfiber or synthetic filament pads with absorbency ratings exceeding 400 percent by weight. The apparatus eliminates hand-wringing through pedal or handle-activated rotation, serving residential and commercial users requiring hygienic floor maintenance with reduced physical strain. Microfiber mops command margin pools due to superior particle capture and durability, while electric mops represent the fastest-growing product type as battery technology improves cordless runtime. Household end users dominate volume, though commercial cleaners extract higher per-unit value through specialized synthetic fiber configurations and replacement head contracts.
REACH compliance in Europe restricts phthalate content in plastic bucket components, compelling manufacturers to reformulate polypropylene blends or source alternative polymers. The EPA's Safer Choice program in the United States shapes demand for cleaning systems compatible with reduced-chemical formulations, influencing microfiber pad design for water-only cleaning efficacy. China's GB standards for household electrical appliances govern safety certification requirements for emerging electric mop segments. Stakeholders must monitor evolving chemical disclosure mandates and battery safety protocols as product electrification accelerates.
Market Dynamics
The EU Green Deal's material sourcing mandates are forcing polypropylene reformulation across European supply chains, while battery electrification in cordless models is fragmenting competitive capabilities between electrical and mechanical engineering competencies.
Growth Catalysts
- REACH Phthalate Restrictions:European manufacturers accelerating bio-based polymer adoption in bucket housings, creating first-mover certification advantages for compliant suppliers.
- Urban Apartment Density:German metropolitan households demanding collapsible, storage-minimal cleaning systems with sub-15-liter bucket footprints.
- Microfiber Technology Maturation:Synthetic filament absorbency thresholds exceeding 600 percent by weight enabling water-only cleaning protocols that reduce chemical consumption.
Market Restraints
- Petrochemical Input Volatility:Polypropylene resin prices tied to naphtha cracking economics create margin compression for injection-molded bucket producers.
- East Asian Component Concentration:Centrifugal wringer mechanisms and pedal assemblies concentrate among Zhejiang and Guangdong province suppliers, exposing lead time risks.
- Electric Mop Runtime Limitations:Lithium-ion cell energy density constraints restrict cordless operation to sub-45-minute cycles, constraining commercial adoption.
Strategic Opportunities
- India Tier-2 Urbanization:Rising middle-class household formation in Pune, Kochi, and Indore creating demand for mechanized cleaning alternatives to traditional cloth mopping.
- EPA Safer Choice Alignment:Microfiber pad designs optimized for chemical-free efficacy qualifying for federal procurement preferences in institutional cleaning contracts.
- Subscription Replacement Head Models:Direct-to-consumer channels capturing recurring revenue through automated refill programs for detachable fiber pads.
Industry Challenges
- Cross-Disciplinary Engineering Talent:Electric mop development requires rare combinations of mechanical design and battery thermal management expertise.
- GB Standard Certification Timelines:China's household electrical appliance safety protocols impose 8-14 month approval cycles for new cordless product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spin Mops Market |
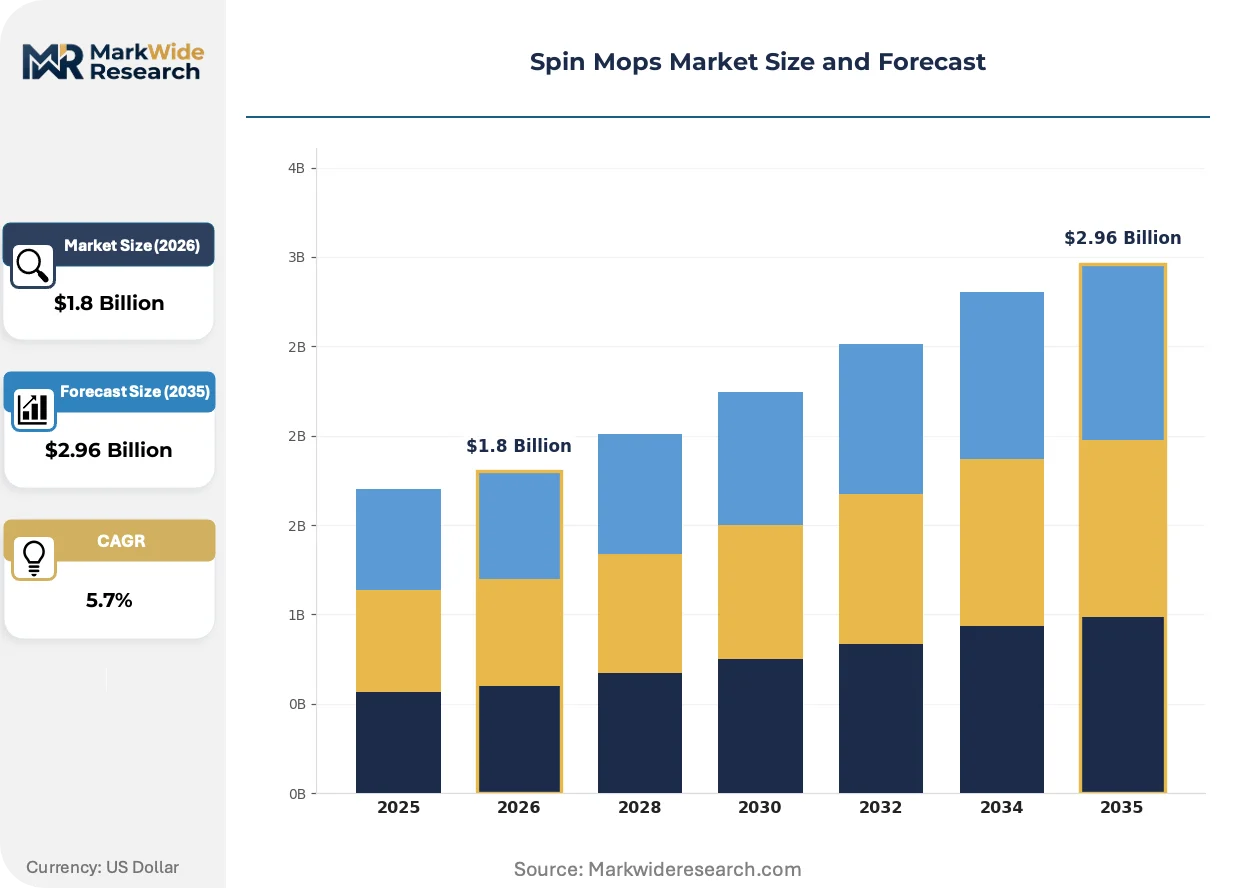
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Mops, Electric Mops, Dual-Head Mops, Microfiber Mops End User: Households, Commercial Cleaners, Hospitality Industry, Industrial Facilities Size: Standard Size, Compact Size, Extra Large, Mini Size Material: Microfiber, Cotton, Synthetic Fibers, Blended Materials |
| Companies Covered | O-Cedar, Hurricane Spin, Libman, BISSELL, Mopnado, Vileda, Scotch-Brite, 3M, Freudenberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spin Mops Market Strategic Shifts
Product architecture is splitting between premium electrified systems and simplified mechanical designs, while regulatory chemistry constraints and direct-channel commerce are rewiring how manufacturers reach end users.
Battery-powered spin mops is bifurcating the product landscape into two distinct performance tiers. Residential buyers in Japan and South Korea are adopting 20V+ lithium platforms for whole-home cordless operation. This voltage escalation is compressing margins for entry-tier mechanical manufacturers unable to fund cell chemistry R&D.
REACH Annex XVII phthalate limitations are compelling polypropylene compounders to certify bio-based alternatives for bucket and wringer housing production. German retailers now require full material disclosure documentation for shelf placement. Small-scale assemblers without polymer science capabilities are exiting the European market rather than reformulating.
Direct-to-consumer platforms are displacing hypermarket dominance for replacement head replenishment. Urban German households now source microfiber pads through manufacturer-owned subscription portals rather than retail stock-up trips. This channel migration is most advanced in Berlin and Hamburg, where same-day logistics networks enable just-in-time pad delivery.
Spin Mops Market Segmentation
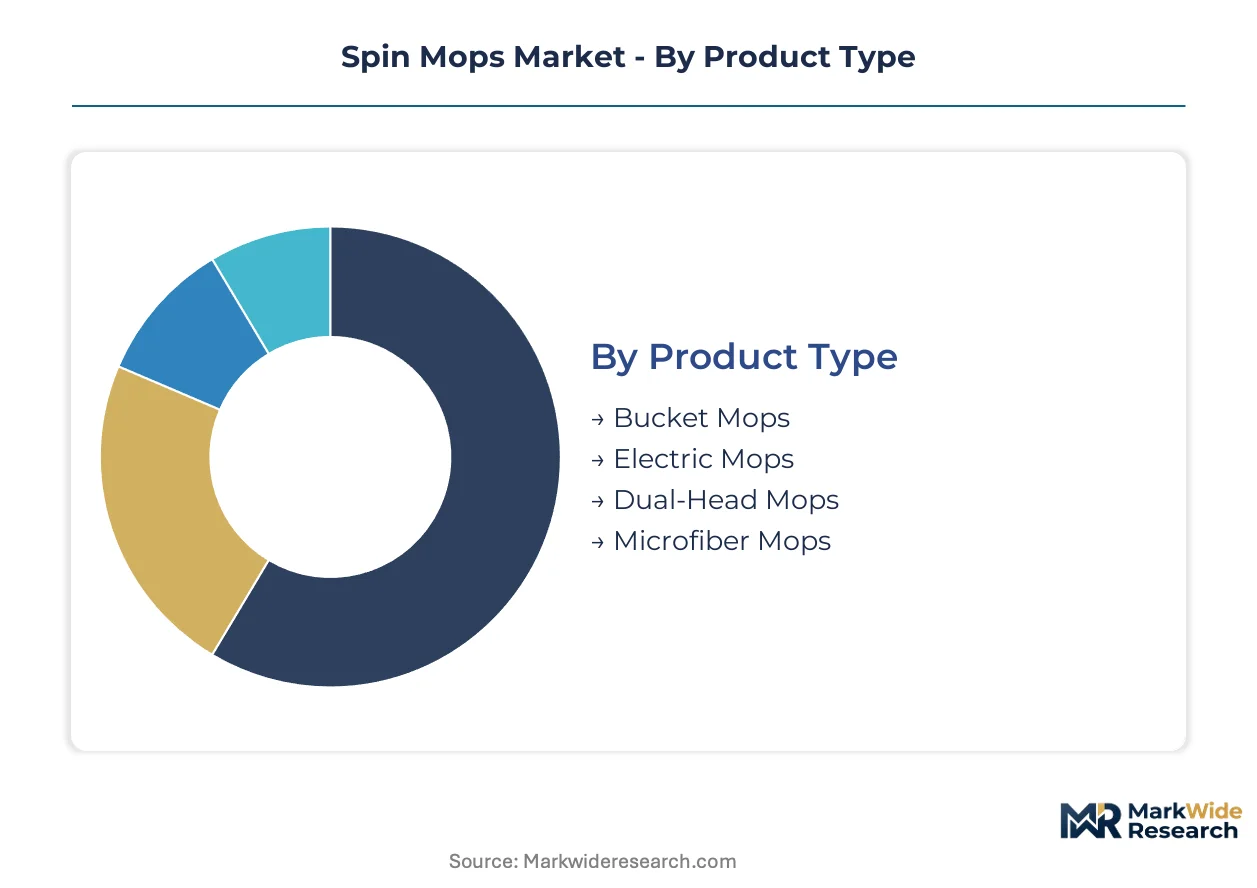
Spin mop segmentation reflects divergent engineering competencies and regulatory compliance burdens across mechanical and electrified product architectures. Material chemistry restrictions and battery safety protocols create distinct margin profiles that reshape competitive positioning within each category.
Product Type:
REACH Annex XVII phthalate restrictions and GB standard electrical safety protocols bifurcate R&D investment between polymer reformulation and battery thermal management capabilities.
- Bucket Mops:Pedal-activated centrifugal wringers housed in injection-molded polypropylene buckets dominate German metropolitan retail channels. Urban apartment dwellers in Berlin and Hamburg favor sub-15-liter footprints with collapsible handles for storage efficiency.
- Electric Mops:Lithium-ion powered cordless systems with 20V+ platforms are expanding most quickly in Japan and South Korea where whole-home runtime demands exceed mechanical alternatives. Battery cell energy density constraints currently limit commercial adoption cycles to sub-45-minute operation.
- Dual-Head Mops:Twin rotating heads with independent motor drives require dual certification pathways under China's GB standards.
- Microfiber Mops:Synthetic filament pads with absorbency thresholds exceeding 600 percent by weight enable water-only cleaning protocols aligned with EPA Safer Choice criteria.
Established volume favors bucket mops; emerging adoption favors electric mops.
End User:
Contract value differentiation separates recurring replacement head revenue from single-purchase residential transactions.
- Households:Residential buyers extract value through subscription replacement head models delivered via direct-to-consumer channels in Berlin and Hamburg. Just-in-time logistics networks displace hypermarket stock-up behavior for microfiber pad replenishment.
- Commercial Cleaners:Institutional procurement contracts specify synthetic fiber configurations with specialized durability ratings and automated refill programs. EPA Safer Choice alignment qualifies suppliers for federal procurement preferences.
- Hospitality Industry:Hotel chains in Pune and Kochi specify compact storage systems for housekeeping cart efficiency.
- Industrial Facilities:Heavy-duty blended material heads address chemical spill containment requirements in manufacturing environments.
Per-unit margins concentrate with commercial cleaners; transaction velocity concentrates with households.
Size:
Urban density patterns in target geographies dictate dimensional constraints across residential and commercial applications.
- Standard Size:15-20 liter bucket capacity serves multi-room residential cleaning in suburban German households.
- Compact Size:Sub-15 liter footprints with collapsible components address space constraints in Frankfurt and Munich apartment stock. EU Green Deal material sourcing mandates apply to reduced-volume polypropylene formulations.
- Extra Large:Industrial-scale systems exceed residential storage feasibility and concentrate in facility maintenance contracts.
- Mini Size:Single-room or vehicle interior applications occupy niche direct-channel segments.
Storage constraints favor compact size; coverage efficiency favors standard size.
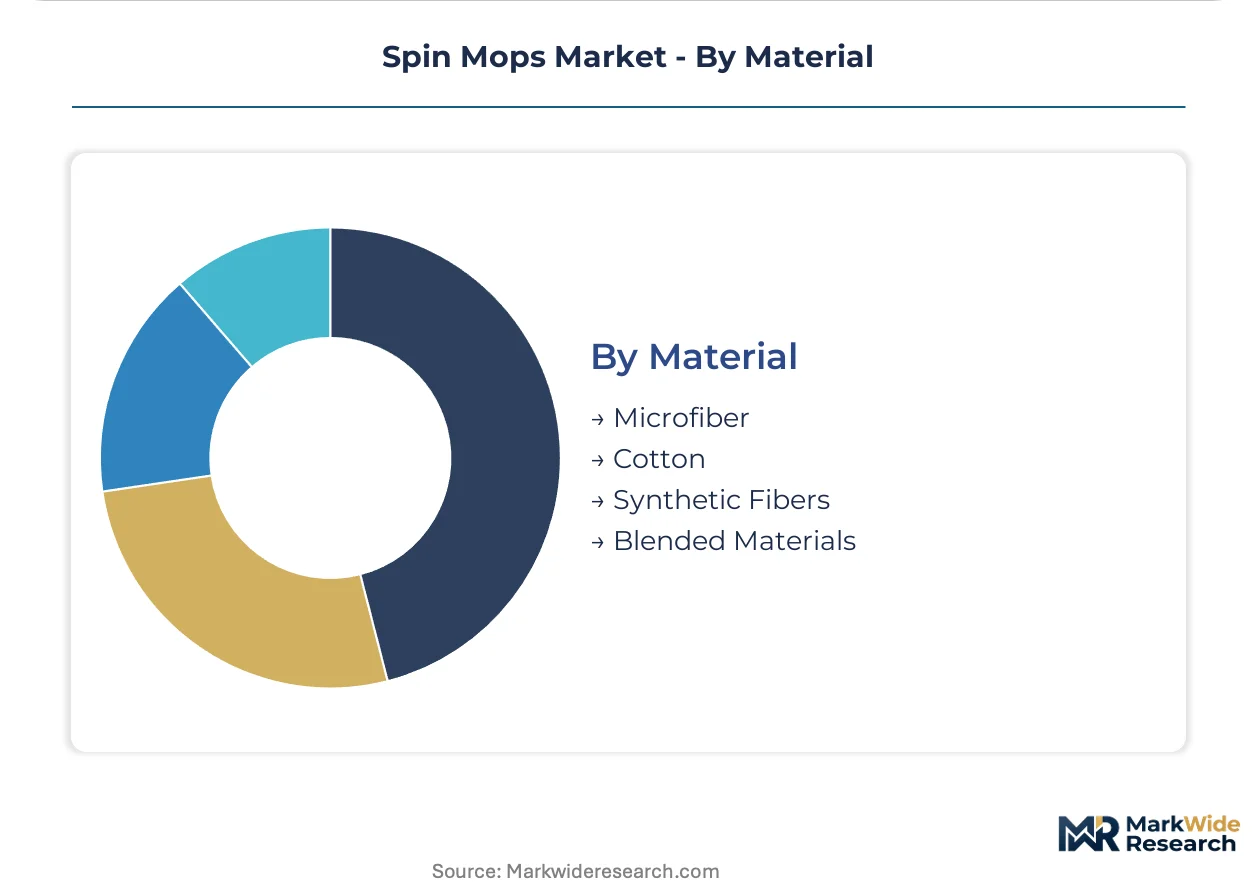
Material:
REACH compliance timelines and bio-based polymer certification requirements reshape sourcing strategies for fiber and housing components.
- Microfiber:Synthetic filament technology with particle capture efficiency exceeding 400 percent absorbency by weight commands premium positioning. Freudenberg Group's fiber leadership supplies multiple downstream brands with REACH-certified compounds.
- Cotton:Natural fiber alternatives face absorbency limitations and slower drying characteristics that reduce replacement cycle frequency.
- Synthetic Fibers:Polypropylene and polyester blends optimize cost-performance ratios for entry-tier mechanical mop assemblies.
- Blended Materials:Hybrid compositions balance durability and absorbency for industrial spill containment applications.
Regulatory compliance favors microfiber; cost minimization favors synthetic fibers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German buyers absorb premium pricing for REACH-certified systems. Indian consumers gravitate toward entry-tier mechanical alternatives. Japanese households prioritize battery performance over unit cost.
United States
EPA Safer Choice program compliance shapes institutional procurement specifications for water-only cleaning efficacy. Federal procurement preferences favor microfiber pad designs aligned with reduced-chemical protocols. The Southeast manufacturing corridor concentrates injection-molded bucket production serving mass-market retail channels.
Germany
Urban apartment density in Berlin and Hamburg drives demand for sub-15-liter collapsible storage systems. EU Green Deal material sourcing mandates compel polypropylene reformulation across domestic supply chains. The North Rhine-Westphalia industrial basin anchors captive microfiber production for integrated manufacturers.
China
GB standard certification timelines for cordless electrical appliances extend 8-14 months for new product launches. Zhejiang and Guangdong province suppliers concentrate centrifugal wringer mechanism and pedal assembly production. The Yangtze River Delta cluster dominates export-oriented manufacturing for global brand supply.
India
Tier-2 urbanization in Pune, Kochi, and Indore generates demand for mechanized cleaning alternatives to traditional cloth mopping. BIS certification requirements apply to electrical appliance segments entering domestic distribution. Maharashtra's industrial corridor hosts assembly operations targeting price-sensitive household segments.
Japan
Whole-home cordless runtime demands accelerate 20V+ lithium platform adoption among residential buyers. METI energy efficiency guidelines influence battery thermal management design specifications. The Kanto region concentrates R&D competencies for high-voltage electric mop development.
Spin Mops Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the spin mops sector. Integrated manufacturers with captive fiber production command margin pools through input cost control and quality consistency. Assembly-only competitors compete on volume scale and retail channel density. Strategic moves concentrate on polymer science certification for EU market access and direct-to-consumer subscription models for replacement head revenue.
Among integrated specialists, O-Cedar and Freudenberg Group exemplify the technology-anchored archetype through upstream control over synthetic fiber supply. Vileda occupies a position representing European retail channel density, sustaining shelf presence across hypermarket chains. These three entities sit within distinct competitive vectors: fiber technology leadership, material compliance certification, and distribution network scale.
| Leading Market Players |
|---|
| O-Cedar |
| Hurricane Spin |
| Libman |
| BISSELL |
| Mopnado |
| Vileda |
| Scotch-Brite |
| 3M |
| Freudenberg Group |
| Others |
Value Chain & Pricing Dynamics
Bio-based polypropylene substitution for phthalate-laden conventional resins is redrawing manufacturing footprints toward EU-certified compounders while compressing margins for assemblers lacking polymer science capabilities. This material transition simultaneously elevates REACH compliance costs and fragments pricing power across European distribution channels.
Pricing Analysis
Replacement head subscription revenue drives lifetime value capture for manufacturers operating direct-to-consumer portals. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified electric systems from mechanical bucket assemblies and entry-tier synthetic fiber variants. Cost compression in entry-tier mechanical segments is intensifying because of petrochemical input volatility and East Asian component concentration. German metropolitan households show lowest price sensitivity, absorbing premiums for collapsible storage systems and certified bio-based materials, while Indian tier-2 buyers gravitate toward economy mechanical alternatives.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and polypropylene resin dominates inventory posture as lead time risks concentrate among Zhejiang and Guangdong province suppliers. Centrifugal wringer mechanisms and pedal assemblies draw from Chinese manufacturing clusters, while synthetic fiber technology rests on German and Japanese specialty chemical producers. Single-source vulnerability in East Asian component concentration exposes brands to logistics chokepoint disruptions. Distribution runs through hypermarket chains in European markets and direct-to-consumer platforms for replacement head replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around direct-to-consumer subscription models and institutional procurement contracts, fragmenting traditional retail channel leverage. Hypermarket buyers in Germany and France face displacement as households migrate to manufacturer-owned replenishment portals.
For Market Incumbents: Secure captive microfiber production capacity to defend input cost control against Freudenberg Group's synthetic fiber technology leadership. Accelerate REACH Annex XVII certification for bio-based polymer formulations before regulatory deadlines force market exit. Channel control through owned subscription platforms represents the critical defensive lever against retail disintermediation.
For New Entrants and Emerging Players: EPA Safer Choice fast-track certification unlocks federal procurement preferences for water-only cleaning efficacy in institutional segments. White-space concentration sits with India's tier-2 urbanization in Pune and Indore, where mechanized cleaning alternatives displace traditional cloth mopping. Direct-to-consumer launch with automated refill programs captures recurring revenue without retail slotting fee barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive fiber production and established REACH compliance infrastructure. Long-term viability favors entities controlling upstream polymer science capabilities and downstream subscription channels. Watch for inflection when GB standard certification timelines compress for electric mop segments entering Chinese distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microfiber Production | O-Cedar's captive fiber capacity controls input costs and quality consistency across bucket mop lines. |
| REACH Bio-Based Polymer Certification | German retailers now require full material disclosure documentation for shelf placement authorization. |
| Direct-to-Consumer Subscription Launch | Berlin and Hamburg households source microfiber pads through manufacturer portals rather than hypermarket trips. |
| EPA Safer Choice Alignment | Federal procurement preferences favor microfiber designs optimized for chemical-free cleaning efficacy. |
| Dual-Head Electric Platform Development | Independent motor drives require dual certification pathways under China's GB standards. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and retail audit databases. Interviews with brand managers, category buyers at European hypermarket chains, supply planners at microfiber producers, and aftermarket service heads at commercial cleaning contractors informed demand-side validation. Secondary sources include ECHA REACH registration databases, EPA Safer Choice certified product listings, and GB standard certification records from Chinese regulatory bodies. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled span product architecture, end-user contract value, urban density-driven size constraints, and material chemistry compliance tiers. CAGRs derive from regression analysis of historical adoption patterns and elasticity-adjusted projection across the modeling period. Forecast inputs incorporate battery energy density improvement curves and EU Green Deal material sourcing mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained electrification investment or accelerated REACH compliance adoption would require recalibration. Forecasts reflect assumptions regarding lithium-ion cost trajectories and polymer certification timelines. Revision becomes warranted when GB standard approval cycles for cordless appliances compress below current 8-14 month baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Consumer Wet Wipes Market