
 Sponge Cloth Market | 2026-2036
Sponge Cloth Market Size, Share, and Industry Trends Forecast 2026-2036
Sponge Cloth Market Analysis
The EU Green Deal is expanding the addressable market for biodegradable cleaning substrates across European retail and institutional channels. Spontex Industrial leverages its manufacturing footprint in France to sustain continental supply for private-label cellulose programs. Ramon Hygiene Products anchors UK demand through specialized industrial wiping contracts. Kalle competes on technical nonwoven integration for premium household segments.
A sponge cloth is a porous, absorbent cleaning substrate typically manufactured from regenerated cellulose derived from wood pulp, often reinforced with cotton or synthetic fibers for tensile strength, capable of absorbing up to twenty times its dry weight in liquid. The product serves commercial and residential surface cleaning, spill management, and controlled solvent application across food service, healthcare, and industrial maintenance settings. Cellulose sponge variants lead volume due to established biodegradability credentials and compatibility with composting infrastructure, while hybrid sponge formats capture margin pools by combining cellulose absorbency with polyester durability for extended-use applications. Flat sheets dominate household channels for universal surface tasks, whereas pre-cut shapes concentrate in medical and food-processing environments where dimensional consistency supports protocol compliance.
REACH compliance governs chemical safety in cellulose processing across EU manufacturing, while the EU F-Gas Regulation indirectly shapes demand by restricting fluorinated solvents historically used in competing synthetic wipe production. EMA guidelines on medical device cleanliness influence substrate selection for clinical applications, particularly in German and Benelux hospital procurement. Stakeholders must monitor evolving packaging waste directives and composting certification standards to secure shelf placement in regulated European retail environments.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing synthetic wipe demand while channeling institutional procurement toward cellulose-based substrates certified for industrial composting.
Growth Catalysts
- REACH compliance:Chemical safety mandates across EU manufacturing favor water-based cellulose processing over solvent-intensive synthetic alternatives, expanding addressable substrate volumes.
- Food service protocols:Commercial kitchens in Germany and France are replacing polyester wipes with flat-sheet cellulose formats to meet HACCP spill-management standards.
- Wood pulp supply clustering:Nordic pulp mills provide cost-competitive raw material feedstock for regenerated cellulose production serving continental European converters.
Market Restraints
- Cotton reinforcement cost volatility:Natural fiber price swings compress margin stability for hybrid sponge formats blending cellulose with cotton scrim.
- Composting infrastructure gaps:Eastern European municipalities lack industrial composting capacity, limiting biodegradability claims to Western European addressable markets.
- Polyester wipe durability:Extended-use synthetic substrates retain share in industrial maintenance settings where replacement frequency drives total cost calculations.
Strategic Opportunities
- Benelux hospital procurement:EMA medical device cleanliness guidelines create specification windows for pre-cut cellulose shapes in sterile processing departments.
- Cellulose-nanofiber integration:Emerging nonwoven reinforcement technologies promise tensile strength improvements without synthetic fiber dependency.
- Private-label retail consolidation:Centralized sustainable sourcing mandates by French and Dutch retail chains favor volume suppliers with certified composting credentials.
Industry Challenges
- Composting certification timeline:EN 13432 compliance testing extends product launch cycles by 8-14 months for new substrate formulations.
- Process engineering talent scarcity:Wet-laid nonwoven expertise concentrates among aging technical workforces in traditional textile regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sponge Cloth Market |
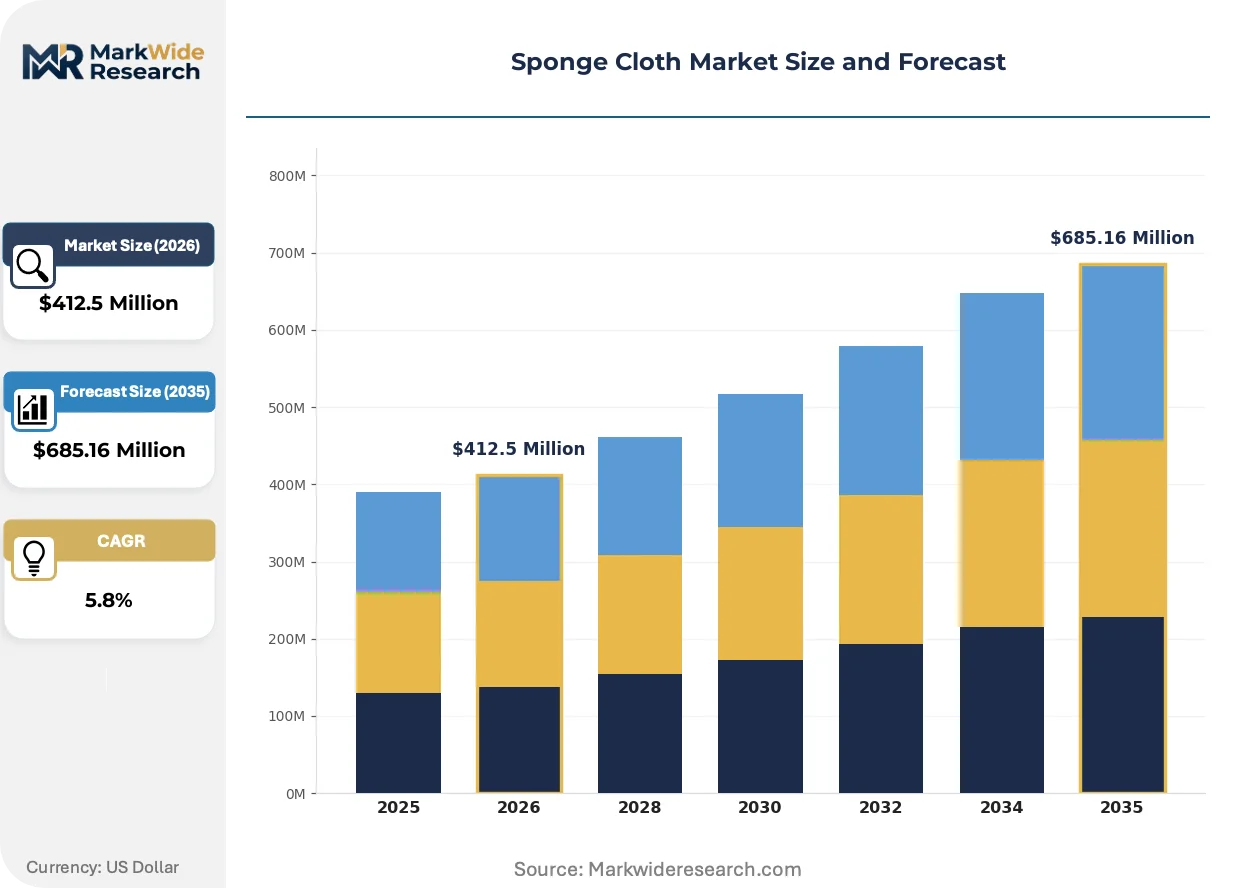
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Sponge, Synthetic Sponge, Natural Sponge, Hybrid Sponge Application: Household Cleaning, Industrial Use, Medical Applications, Personal Care Form: Flat Sheets, Rolls, Pre-Cut Shapes, Bulk Pieces Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Spontex Industrial, Ramon Hygiene Products, Kalle, The Libman Company, Vileda, 3M, Corazzi Fibre, Scrub Daddy, Inc., Freudenberg Home and Cleaning Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sponge Cloth Market Emerging Trajectories
Material science advances are dissolving the performance gap between biodegradable cellulose substrates and durable synthetics, while regulatory pressure accelerates substitution timelines across institutional channels.
Regenerated cellulose sponge production is converging with nanofiber reinforcement techniques to match polyester wipe durability without sacrificing compostability. German industrial laundries are piloting these hybrid formats for fleet vehicle maintenance contracts. The convergence is compressing replacement cycles for premium synthetic wipes in controlled solvent applications.
The EU F-Gas Regulation restricts fluorinated solvents historically used in competing synthetic wipe manufacturing, indirectly elevating cellulose substrate cost competitiveness. Industrial wipe converters face reformulation mandates or supply chain restructuring. Food-processing and electronics-cleaning segments in the Netherlands and Belgium are responding fastest with qualified cellulose alternatives.
Janitorial supply distributors are unbundling after-sales service from product supply, shifting toward specification-based procurement where composting certification determines vendor qualification. Facility management groups in France are consolidating purchasing through centralized sustainability scorecards. This pattern is most visible in Paris and Lyon metropolitan hospital networks.
Sponge Cloth Market Segmentation
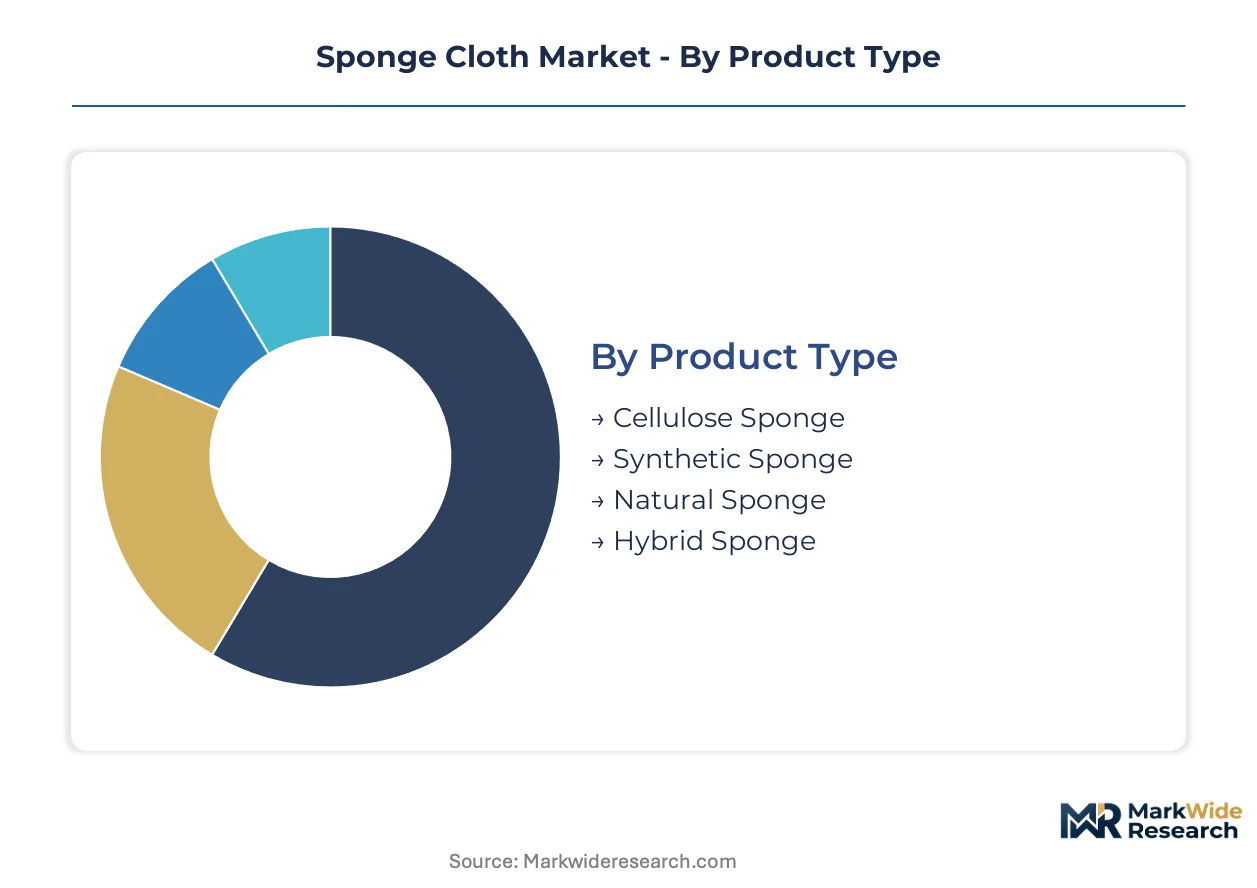
Sponge cloth segmentation reflects divergent material science trajectories and channel economics. Manufacturers configure product lines around biodegradability credentials, durability requirements, and procurement route economics.
Product Type:
Material composition determines regulatory alignment and end-of-life pathway for each substrate variant.
- Cellulose Sponge:Regenerated wood pulp substrates absorb up to twenty times dry weight and biodegrade through industrial composting. REACH-compliant water-based processing expands volumes across EU institutional procurement channels constrained by packaging waste directives.
- Synthetic Sponge:Polyester and polyurethane variants deliver extended-use durability for industrial maintenance settings. Replacement frequency economics retain share where total cost calculations outweigh sustainability mandates.
- Natural Sponge:Harvested marine organisms serve premium personal care and medical applications requiring hypoallergenic credentials.
- Hybrid Sponge:Cellulose-polyester laminates balance absorbency with tensile strength for food service protocols demanding HACCP compliance.
Cellulose sponge leads on scale; hybrid sponge leads on momentum.
Application:
End-use specifications create divergent performance thresholds and certification requirements.
- Household Cleaning:Flat-sheet cellulose formats dominate universal surface tasks across European retail chains absorbing higher volumes as consumers phase out single-use plastics.
- Industrial Use:Controlled solvent applications in fleet vehicle maintenance and electronics cleaning drive qualified substrate selection under EU F-Gas Regulation constraints.
- Medical Applications:Pre-cut shapes concentrate in German and Benelux hospital sterile processing departments where EMA cleanliness guidelines govern procurement.
- Personal Care:Natural and premium cellulose variants capture margin pools through cosmetic and bath accessory channels.
Household cleaning anchors volume concentration; medical applications show steepest specification tightening.
Form:
Physical configuration aligns with task automation and protocol standardization requirements.
- Flat Sheets:Universal format for surface wiping tasks across residential and commercial cleaning operations.
- Rolls:Continuous feed systems support high-throughput industrial laundries and automated dispensing in food processing facilities.
- Pre-Cut Shapes:Dimensional consistency serves clinical environments and food-processing protocols where contamination control demands standardized substrates.
- Bulk Pieces:Unfinished blocks enable downstream converter customization for specialty wiping applications.
Flat sheets dominate unit economics; pre-cut shapes concentrate value capture.
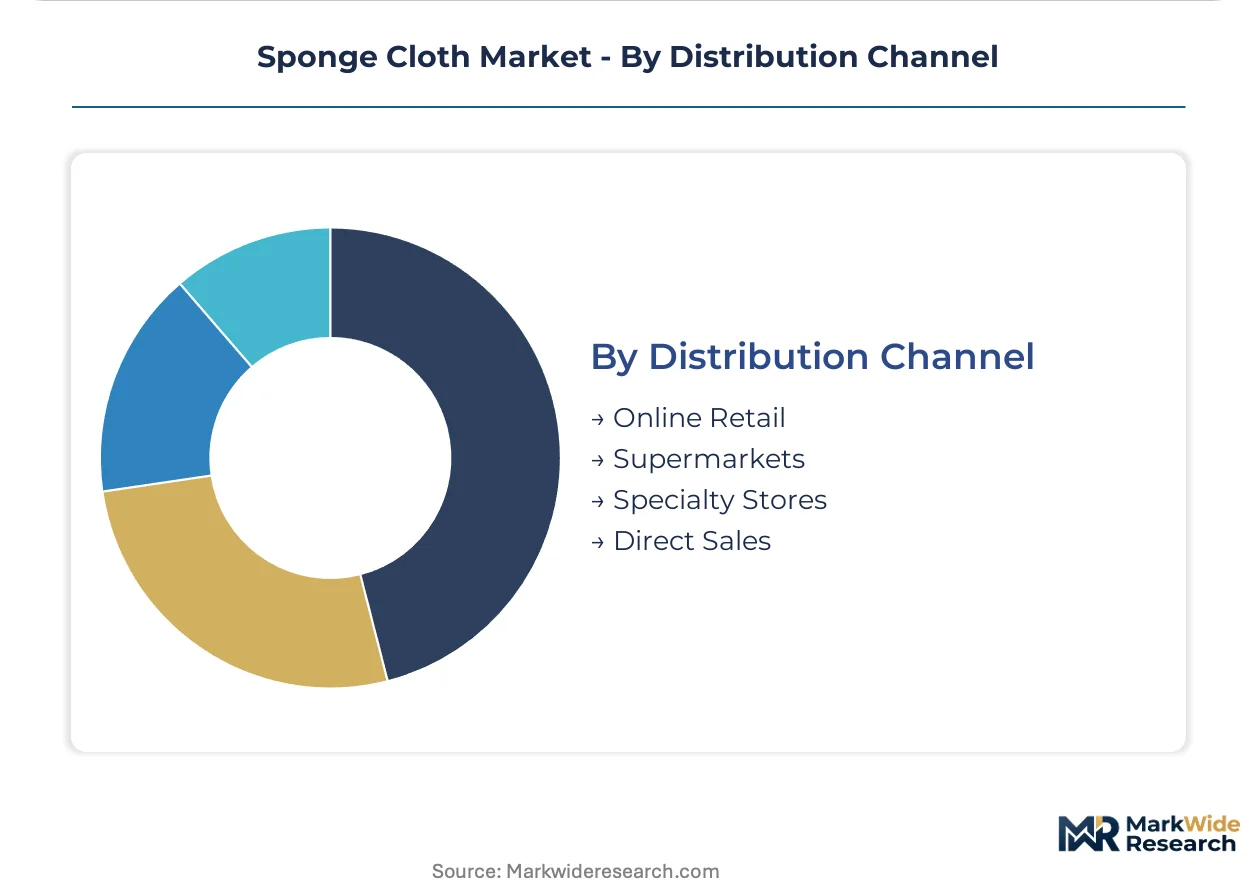
Distribution Channel:
Channel structure determines vendor qualification requirements and sustainability documentation burdens.
- Online Retail:Direct-to-consumer routes accelerate private-label cellulose penetration through composting certification visibility.
- Supermarkets:Centralized sustainable procurement mandates by French and Dutch retail chains favor volume suppliers with EN 13432 credentials.
- Specialty Stores:Janitorial supply distributors unbundle after-sales service from product supply, shifting toward specification-based procurement.
- Direct Sales:Industrial wiping contracts anchor UK demand through specialized technical support and inventory management integration.
Supermarkets concentrate volume throughput; online retail expands access fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellulose sponge cloth manufacturing originated in Swedish forestry regions during the early twentieth century, leveraging abundant Nordic wood pulp supply. The technology diffused through continental Europe before establishing industrial-scale production in Germany and France.
Germany
Industrial laundries in North Rhine-Westphalia pilot cellulose-nanofiber hybrid formats for fleet maintenance contracts under EU F-Gas Regulation constraints. REACH compliance mandates favor water-based cellulose processing over solvent-intensive synthetics. The Stuttgart industrial corridor concentrates converter capacity serving Benelux hospital procurement networks.
France
Paris and Lyon metropolitan hospital networks consolidate purchasing through centralized sustainability scorecards prioritizing EN 13432 certification. The EU Green Deal's packaging waste directives channel retail procurement toward biodegradable substrates. Spontex Industrial maintains manufacturing footprint in northern France for continental private-label supply.
United Kingdom
Specialized industrial wiping contracts anchor demand through technical support and inventory management integration. Ramon Hygiene Products occupies position serving janitorial supply distributors unbundling after-sales service from product supply. The Midlands industrial belt hosts converter operations supplying food-processing protocols.
Netherlands
Food-processing and electronics-cleaning segments in Rotterdam and Eindhoven respond fastest with qualified cellulose alternatives to restricted fluorinated solvents. Centralized sustainable sourcing mandates by Dutch retail chains favor volume suppliers with composting credentials. The Randstad logistics hub enables rapid distribution across continental channels.
Sweden
Nordic pulp mills provide cost-competitive raw material feedstock for regenerated cellulose production serving European converters. The EU Green Deal accelerates material substitutions toward biodegradable substrates in household cleaning departments. Göteborg and Stockholm anchor research clustering for next-generation nanofiber reinforcement technologies.
Sponge Cloth Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models in the sponge cloth market. Integrated cellulose processors control wet-laid nonwoven capacity while specialized converters source substrate from third-party pulp mills. Three archetypes dominate: Nordic pulp-integrated manufacturers, continental European private-label specialists, and North American brand-marketing entities. Competitive moves concentrate on composting certification acquisition and strategic partnerships with retail sustainability procurement offices.
Within the private-label tier, Spontex Industrial and Ramon Hygiene Products exemplify divergent geographic anchoring strategies for institutional channel access. Kalle occupies position representing technical nonwoven integration for premium household segments. Among North American entities, The Libman Company and Scrub Daddy, Inc. sit within brand-marketing archetypes emphasizing direct retail relationship depth over manufacturing asset ownership.
| Leading Market Players |
|---|
| Spontex Industrial |
| Ramon Hygiene Products |
| Kalle |
| The Libman Company |
| Vileda |
| 3M |
| Corazzi Fibre |
| Scrub Daddy, Inc. |
| Freudenberg Home and Cleaning Solutions |
| Others |
Supply Flow & Price Mechanics
Captive pulp supply from Nordic mills anchors both cost position and pricing power for integrated cellulose sponge manufacturers serving EU institutional procurement channels. This backward integration into wood pulp feedstock insulates volume leaders from cotton reinforcement cost volatility while enabling competitive positioning against synthetic alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EN 13432-certified compostable grades from uncertified cellulose and basic synthetic formats. Price differentiation rests on certification grade and volume scale, with French and Dutch retail chains commanding lowest unit costs through centralized sustainable sourcing mandates. Cost compression in standard-tier hybrid sponges is intensifying because cotton scrim price swings compress margin stability. Industrial maintenance buyers show highest price sensitivity due to replacement frequency economics, while Benelux hospital procurement demonstrates lowest sensitivity where EMA cleanliness guidelines govern specification.
Supply Chain Analysis
Rising freight costs from Nordic pulp mills to continental European converters are reshaping regional sourcing strategies for regenerated cellulose substrate. Supply concentrates in Sweden, Germany, and France, with Nordic pulp mills providing cost-competitive feedstock for wet-laid nonwoven production. Raw material dependencies span wood pulp, cotton fiber for hybrid reinforcement, and nanofiber additives for emerging durability applications. Single-source vulnerability around Nordic pulp supply creates concentration risk. Distribution runs through janitorial supply distributors unbundling after-sales service from product supply, with direct sales anchoring UK industrial wiping contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sponge cloth market reads as a late-cycle quality story as EU Green Deal packaging waste directives channel procurement toward premium biodegradable substrates certified for industrial composting.
For Market Incumbents: Lock in pulp supply agreements with Nordic mills to defend margin position against cotton reinforcement cost volatility. Prioritize EN 13432 certification investment to maintain vendor qualification status under French and Dutch retail chain sustainability scorecards. Consolidate converter capacity in the Stuttgart industrial corridor to capture Benelux hospital procurement volume as EMA guidelines tighten substrate specifications. For New Entrants and Emerging Players: The EU F-Gas Regulation in the Netherlands and Belgium opens a window for qualified cellulose alternatives in food-processing and electronics-cleaning segments previously served by fluorinated solvent-based synthetics. Target Rotterdam and Eindhoven industrial laundries piloting cellulose-nanofiber hybrid formats for fleet vehicle maintenance contracts. Pursue private-label partnerships with Dutch retail chains executing centralized sustainable sourcing mandates. For Investors and Strategic Acquirers: Roll-up economics work for wet-laid nonwoven converters because process engineering talent scarcity concentrates among aging technical workforces in traditional textile regions. Acquire mid-cap specialists with captive pulp relationships and established EN 13432 testing protocols. Watch for inflection when cellulose-nanofiber hybrid formats achieve tensile parity with polyester wipes in controlled solvent applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive wood pulp feedstock insulates margin stability from cotton reinforcement cost volatility. |
| EN 13432 Certification Investment | Industrial composting credentials secure vendor qualification under EU Green Deal procurement mandates. |
| Cellulose-Nanofiber Hybrid Development | German industrial laundries pilot formats matching polyester durability without sacrificing compostability. |
| Private-Label Retail Partnership | French and Dutch retail chain consolidation favors volume suppliers with certified sustainability credentials. |
| Benelux Hospital Procurement Concentration | EMA medical device cleanliness guidelines create specification windows for pre-cut cellulose shapes. |
Methodological Framework
Direct dialogue with plant managers at Nordic pulp mills, procurement leads at French retail chains, technical R&D directors at wet-laid nonwoven converters, and janitorial supply distributors informed primary data collection. Secondary validation drew from EU customs and trade data, ECHA REACH registration databases, EN 13432 certification registries, and SEC filings of publicly traded parent entities. Bottom-up volume modeling across product type, application, form, and distribution channel segments triangulated against top-down macroeconomic drivers.
Bottom-up unit economics analysis across cellulose sponge, synthetic sponge, natural sponge, and hybrid sponge categories integrated with top-down EU Green Deal regulatory impact assessment. Segmentation dimensions modeled include material composition, end-use application, physical form configuration, and procurement channel structure. CAGRs were derived from regression analysis against pulp price indices, cotton futures, and institutional procurement volume trends. Forecast inputs incorporated Nordic pulp mill capacity utilization rates and EN 13432 certification timeline assumptions.
Revisions become necessary when EU packaging waste directive implementation timelines accelerate, Nordic pulp supply disruptions materialize, or cellulose-nanofiber hybrid formats achieve cost parity with polyester wipes. Forecasts reflect assumptions about composting infrastructure rollout across Eastern European municipalities and sustained REACH compliance cost structures. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or Nordic pulp mill consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Furniture Polish Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Carpet Spot Remover Market