
 Natural Household Cleaners Market | 2026-2036
Natural Household Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Household Cleaners Market Intelligence
The direct-to-consumer online retail channel is fragmenting the traditional supermarket-dominated landscape. This shift allows niche brands to compete directly with established players on formulation transparency and sustainability credentials. The Honest Company, Inc. leverages its strong brand identity built around safety for families. Meanwhile, Blueland differentiates through its innovative refillable product systems, reducing plastic waste. Established firms like The Clorox Company are responding by expanding their own natural product lines to retain market share.
Natural household cleaners are formulations derived from plant-based or mineral-based sources, such as vinegar, essential oils, and saponified plant oils. They are specifically designed to exclude synthetic chemicals like chlorine, ammonia, and phosphates, aiming to provide effective cleaning with lower environmental toxicity. Within product categories, all-purpose cleaners command the largest share due to their versatility. Formulations based on plant-derived ingredients represent the dominant and fastest-growing segment, eclipsing mineral-based alternatives in consumer preference.
Regulatory frameworks are critical in defining market access and product credibility. In the United States, the EPA's Safer Choice program provides a certification label for products meeting stringent health and environmental criteria. Similarly, the EU Ecolabel sets standards across Europe, guiding manufacturers on ingredient sourcing and biodegradability. Success for market participants hinges on their ability to secure these third-party certifications and effectively communicate the performance benefits of their formulations to skeptical consumers.
Market Dynamics
Regulatory pressure for ingredient transparency is the central force shaping the natural household cleaners market. Mandates from bodies like the United States EPA and Europe's ECHA are compelling manufacturers to reformulate products and disclose sourcing, directly influencing competitive strategy.
Growth Catalysts
- Certification Frameworks:Third-party labels, including the EU Ecolabel and the EPA's Safer Choice program, provide credible validation of health and environmental claims, guiding consumer purchasing decisions and building brand trust.
- Residential Sector Demand:Heightened consumer consciousness regarding chemical exposure in homes, particularly in metropolitan areas of the United States and Germany, drives adoption. This is amplified by higher disposable incomes in these urban centers.
- Ingredient Preference:A strong consumer shift towards formulations based on plant-derived sources like essential oils and saponified vegetable oils is making this the dominant and fastest-growing ingredient segment over mineral-based alternatives.
Market Restraints
- Cost Disparity:The higher procurement cost of high-quality, plant-based ingredients compared to cheaper, mass-produced synthetic chemicals like ammonia and chlorine creates a price premium that can deter price-sensitive consumers.
- Performance Skepticism:A persistent perception among some consumer segments that natural cleaners lack the efficacy and disinfecting power of conventional chemical-based products remains a significant barrier to broader market conversion.
- Supply Chain Volatility:Sourcing consistent, high-quality, and sustainably certified botanical ingredients at scale presents logistical challenges and exposes manufacturers to price fluctuations based on agricultural yields and seasonality.
Strategic Opportunities
- Geographic Expansion:Untapped demand in markets across Latin America and Asia-Pacific, such as Brazil and South Korea, presents a significant growth opportunity as wellness trends and environmental awareness proliferate.
- Commercial Sector Penetration:Developing specialized, high-performance natural cleaning solutions for commercial end-users like hospitality, education, and corporate offices aligns with expanding corporate social responsibility and green procurement initiatives.
- Product System Innovation:The development of concentrated refills, waterless tablets, and reusable packaging systems offers a powerful way to reduce plastic waste and shipping costs, appealing directly to eco-conscious consumers.
Industry Challenges
- Certification Hurdles:Navigating the complex, time-consuming, and costly process of securing and maintaining certifications from bodies like the EPA or obtaining the EU Ecolabel can be a substantial barrier for emerging brands.
- Authentic Marketing:Effectively communicating performance benefits to skeptical consumers without resorting to unsubstantiated claims requires sophisticated marketing strategies and investment in transparent, data-backed evidence of product efficacy.
- Production Scalability:Scaling manufacturing processes for innovative natural formulations while ensuring ingredient purity, stability, and batch-to-batch consistency is a primary operational challenge for rapidly growing companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Household Cleaners Market |
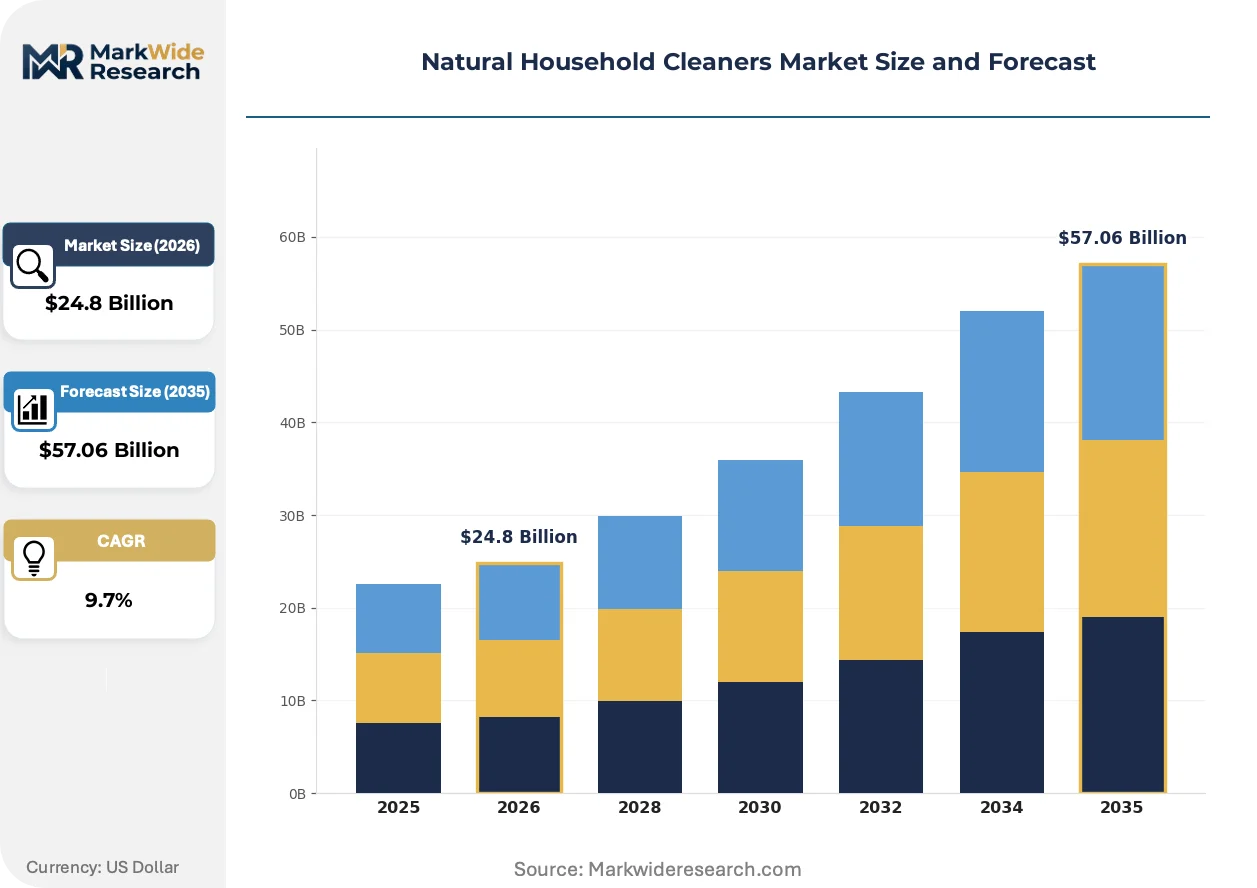
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $57.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Cleaners, Window Cleaners, Floor Cleaners, Dishwashing Liquids Form: Liquid, Spray, Wipe, Concentrate Ingredient Source: Plant-Based, Mineral-Based, Essential Oils, Vinegar Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Pharmacies |
| Companies Covered | Reckitt Benckiser Group PLC, Kao Corporation, Henkel AG & Co. KGaA, The Honest Company, Inc., Godrej Consumer Products Limited, Procter & Gamble, The Clorox Company, Blueland, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Household Cleaners Market Strategic Shifts & Innovations
The market is advancing beyond simple "natural" claims toward a more sophisticated focus on lifecycle sustainability and formulation science. Innovations in packaging, ingredient sourcing, and regulatory compliance are defining the next generation of products and competitive advantages.
Concentrated and waterless product formats, such as dissolvable tablets and solid bars, are gaining significant traction. Eco-conscious residential consumers are the primary adopters, motivated by the reduction in plastic waste and carbon emissions from shipping. This shift toward compact refills is rendering obsolete the traditional single-use plastic bottle model, fundamentally altering logistics and packaging supply chains.
European regulations like the Corporate Sustainability Reporting Directive (CSRD) are forcing greater transparency across the value chain. This mandate requires companies to provide detailed, audited reports on their environmental impact, including ingredient sourcing and end-of-life product management. All manufacturers selling into the EU are affected, compelling investment in robust supply chain traceability and verifiable sustainability metrics.
Subscription-based purchasing models are disrupting established retail channels. Consumers are increasingly using direct-to-consumer (DTC) websites to purchase cleaners, which allows niche brands to bypass traditional supermarket gatekeepers and build direct relationships. This trend is most visible in digitally advanced markets like the United States, where brand narrative and convenience are key purchasing drivers.
Natural Household Cleaners Market Segmentation
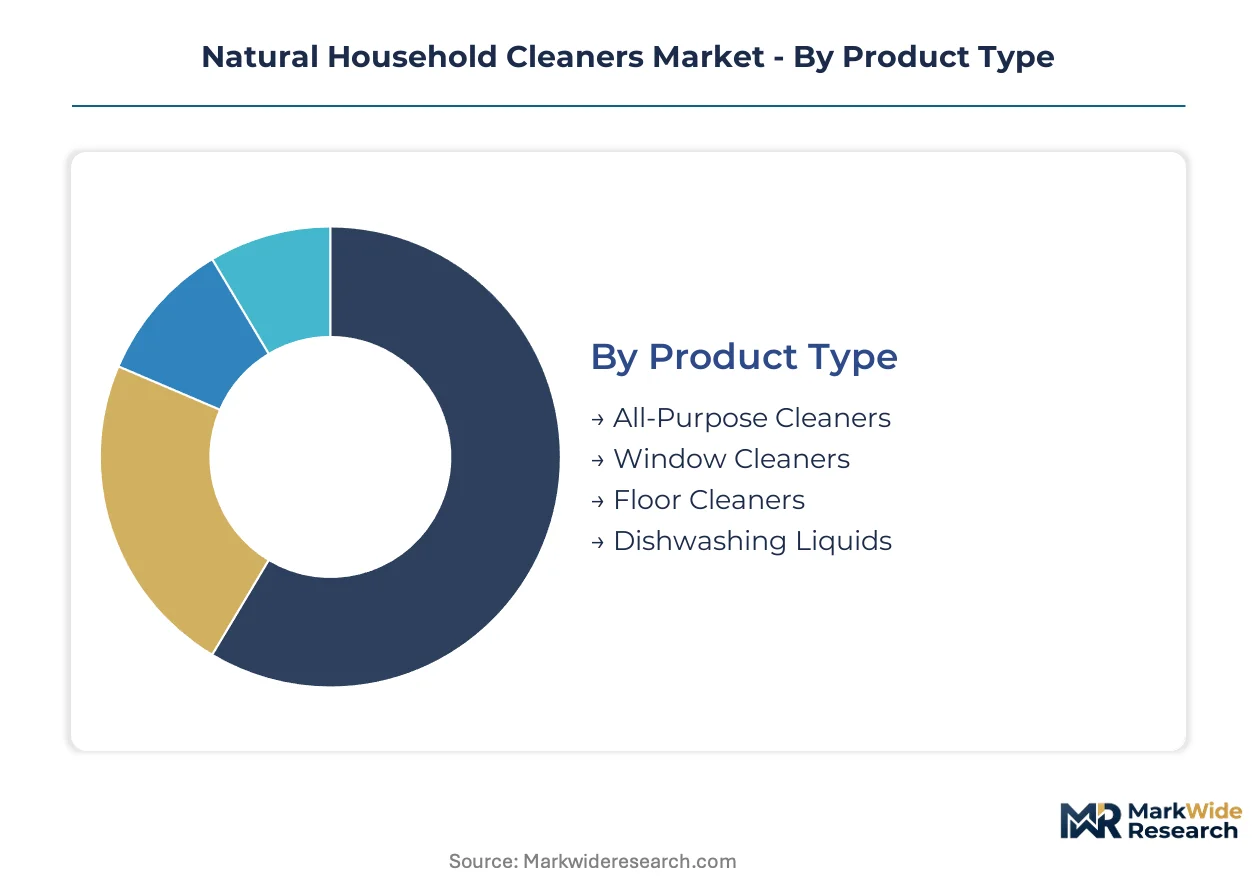
Market segmentation for natural household cleaners clarifies the diverse consumer needs and product functionalities driving industry expansion. Understanding these distinct segments allows manufacturers to tailor product development, marketing strategies, and distribution networks effectively. This granular view reveals where value accrues and where innovation is most impactful across the market.
Product Type:
Product types exhibit varying consumption cycles, from frequently purchased daily essentials to less frequent specialized solutions. Consumers prioritize different attributes based on the cleaning task at hand.
- All-Purpose Cleaners:These versatile formulations address multiple cleaning needs across various surfaces, making them a staple in most households. Demand concentrates in metropolitan areas of the United States and Germany due to their broad utility and consumer focus on chemical safety.
- Dishwashing Liquids:Designed for manual dishwashing, these products require effective grease-cutting properties while remaining gentle on hands. Their high-frequency use drives consistent repurchase cycles.
- Window Cleaners:Formulations specifically for glass and reflective surfaces provide streak-free results.
- Floor Cleaners:Products designed for different flooring materials, from hardwood to tile, offer specialized cleaning.
All-Purpose Cleaners dominate the installed base. Dishwashing Liquids are where expansion concentrates.
Form:
Product form dictates user convenience and application method, influencing purchase decisions based on practical use and environmental considerations.
- Liquid:This traditional form offers ease of application and immediate dissolution for various cleaning tasks. Liquid formulations maintain broad appeal across all consumer demographics.
- Concentrate:These compact formats require dilution before use, significantly reducing packaging waste and shipping weight. Eco-conscious residential consumers in digitally advanced markets like the United States are rapidly adopting these systems.
- Spray:Sprays provide targeted application for surface cleaning and spot treatment.
- Wipe:Pre-moistened wipes offer convenience for quick clean-ups and on-the-go sanitation.
Liquid formats secure the largest volume share. Concentrate forms demonstrate the steepest expansion trajectory.
Ingredient Source:
Ingredient source reflects consumer preference for natural origins and dictates the product's environmental footprint and perceived safety profile.
- Plant-Based:Ingredients derived from botanical sources, such as essential oils and saponified vegetable oils, offer biodegradability and lower toxicity. This segment represents the dominant and fastest-growing choice among consumers seeking eco-friendly options.
- Essential Oils:These concentrated plant extracts provide natural fragrance and often possess inherent antimicrobial properties, appealing to consumers seeking multi-functional benefits. Demand for these premium ingredients is strong in markets with high disposable income.
- Mineral-Based:Formulations utilizing minerals like baking soda or borax provide abrasive or pH-balancing cleaning action.
- Vinegar:Acetic acid-based solutions are valued for their natural disinfecting and deodorizing properties.
Plant-Based ingredients hold the leading position in market value. Essential Oils are capturing a growing share of premium purchases.
Distribution Channel:
Distribution channels define how products reach consumers, impacting brand visibility, pricing strategies, and market accessibility.
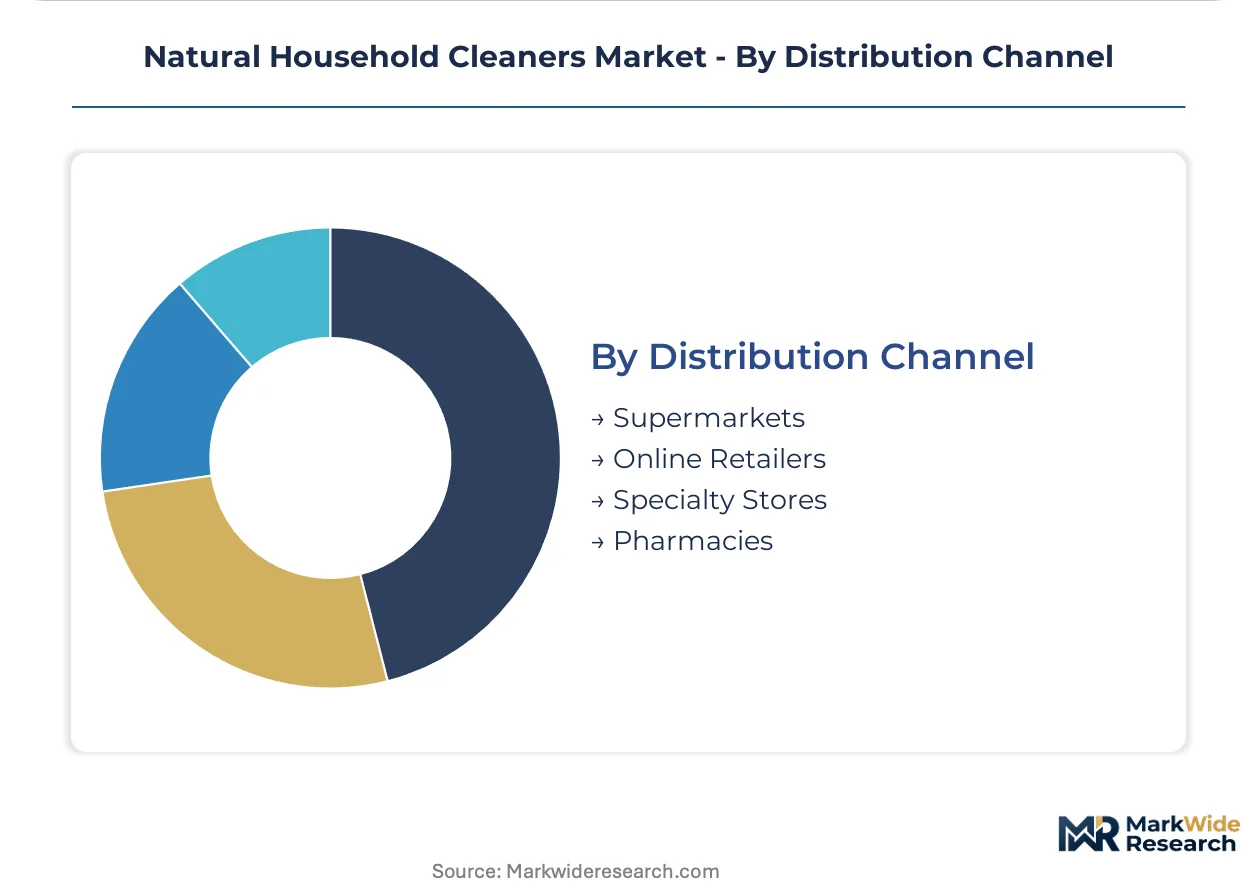
- Supermarkets:These large retail chains offer broad geographic reach and high foot traffic, serving as a primary channel for mass-market natural cleaning products. Supermarkets remain critical for mass market reach.
- Online Retailers:E-commerce platforms provide direct access to consumers, enabling niche brands to compete on transparency and sustainability credentials. Online platforms are redefining direct brand engagement.
- Specialty Stores:These outlets focus on specific product categories, often offering curated selections of premium or unique natural cleaners.
- Pharmacies:Health-focused retail environments provide a trusted point of sale for products emphasizing safety and non-toxic formulations.
Supermarkets account for the largest sales volume. Online Retailers are driving the most significant channel disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust digital infrastructure in developed economies underpins the widespread adoption of natural household cleaners, facilitating direct-to-consumer sales and brand visibility. This market expansion is particularly evident in urban centers where consumer awareness and disposable income are higher. Regulatory frameworks also play a critical role in shaping regional market dynamics.
United States
Heightened consumer consciousness regarding chemical exposure drives demand for natural household cleaners. The EPA's Safer Choice program guides purchasing decisions for health-conscious consumers. Metropolitan areas like New York and Los Angeles exhibit strong adoption, reflecting higher disposable incomes and online retail penetration.
Germany
German consumers prioritize natural formulations due to a strong cultural emphasis on environmental protection and product safety. The EU Ecolabel sets stringent standards for ingredient sourcing and biodegradability. Urban centers like Berlin and Munich demonstrate high consumer awareness and purchasing power for certified natural products.
France
French residential consumers increasingly seek natural cleaners aligned with broader wellness and sustainability trends. ECHA regulations compel manufacturers to disclose sourcing, influencing product reformulation. Paris and other large French cities represent key consumption hubs, favoring transparent and eco-friendly household goods.
Brazil
Untapped demand in Brazil emerges from a growing middle class and increasing environmental awareness in urban areas. ANVISA oversees product safety, contributing to consumer trust in regulated goods. São Paulo and Rio de Janeiro offer substantial growth opportunities for natural household cleaner brands.
South Korea
South Korean consumers demonstrate high engagement with eco-conscious products, propelled by advanced digital adoption and health concerns. The MFDS ensures product safety and compliance for consumer goods. Urban centers such as Seoul and Busan are critical markets, reflecting high disposable incomes and preference for innovative solutions.
Natural Household Cleaners Market Key Industry Players
On the supply side, the industry is dynamic and increasingly fragmented, with established incumbents facing disruption from agile, direct-to-consumer brands. This landscape features three primary strategic archetypes: established global corporations, specialized D2C innovators, and regional market specialists. Established players are expanding their natural product lines to retain market share. Niche brands differentiate through formulation transparency, sustainability credentials, and innovative product systems, such as refillable packaging.
Established players like The Clorox Company respond to market shifts by integrating natural product lines into their extensive portfolios, aiming to maintain broad consumer reach. Conversely, specialized innovators such as The Honest Company, Inc. exemplify brands built on strong identities centered on family safety and ingredient transparency. Blueland, an Inc. company, further represents the segment driving innovation through sustainable product systems, including refillable and waterless formats. These distinct approaches underscore the varied competitive strategies employed across the natural household cleaners market.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| Kao Corporation |
| Henkel AG & Co. KGaA |
| The Honest Company, Inc. |
| Godrej Consumer Products Limited |
| Procter & Gamble |
| The Clorox Company |
| Blueland |
| Unilever |
| Others |
Cost & Logistics Intelligence
Under-capacity in specialized botanical ingredient extraction facilities drives supplier behavior and influences pricing posture for natural household cleaners. This dynamic impacts the cost structure for manufacturers seeking high-quality, certified plant-based inputs.
Pricing Analysis
Volume-discount tiering structures characterize the natural household cleaners market. Price differentiation stems from certification levels, such as EPA Safer Choice, and established brand premium. Pricing pressure stems from the higher procurement cost of plant-based ingredients compared to synthetic alternatives. Price-sensitive consumers deter from natural products, while eco-conscious consumers in high-income demographics exhibit less sensitivity.
Supply Chain Analysis
While specific export-control regimes for plant-based raw materials are not widely imposed, potential future restrictions on sustainably sourced botanicals could limit ingredient flows. The supply chain draws heavily from agricultural regions in Brazil and India for essential oils and saponified vegetable oils. Commodity price volatility due to agricultural yields and seasonality presents a structural risk. Distribution runs through both mass-market supermarkets and direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural household cleaners market presents significant opportunities, but a scarcity of expertise in scaling sustainable botanical ingredient sourcing limits rapid expansion. Companies must address this gap to capitalize on evolving consumer preferences.
For Market Incumbents:
Insulate existing market share by aggressively expanding natural product lines with robust third-party certifications like the EU Ecolabel. Invest in formulation science R&D to counter performance skepticism, a persistent threat from conventional chemical brands. Leverage established distribution channels, particularly supermarkets, to maintain broad consumer reach against agile D2C entrants.
For New Entrants and Emerging Players:
Establish a beachhead in product system innovation by offering concentrated refills and waterless tablets for eco-conscious consumers. Target digitally advanced metropolitan areas in the United States and Germany, where consumer awareness and disposable income are higher. Employ direct-to-consumer online platforms, emphasizing transparent ingredient sourcing and sustainability credentials as a core go-to-market angle.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the plant-based ingredient sourcing sub-segment, driven by demand for verifiable sustainability. The market demonstrates strong long-term viability, supported by evolving consumer wellness and environmental trends. Seek acquisition targets among niche brands with proprietary formulation science or strong direct-to-consumer channels. Growth in certified product sales or investment in sustainable supply chain infrastructure signals inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | Reinforce brand trust by emphasizing verifiable environmental impact reductions. |
| Direct-to-Consumer Launch | Bypass traditional retail gatekeepers, building direct customer relationships and brand loyalty. |
| Premium Tier Introduction | Capture higher-margin consumer segments with advanced plant-based formulations and certifications. |
| Distribution Channel Expansion | Secure broader market access through strategic partnerships with major supermarket chains. |
| Green Manufacturing Transition | Reduce operational footprint, aligning with consumer demand for eco-conscious production practices. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary insights came from brand managers, R&D directors, sustainability officers, and retail buyers. Secondary sources included regulatory filings from the EPA and ECHA, company annual reports, and relevant trade association publications. The study employed both bottom-up and top-down triangulation to ensure data accuracy.
Market size forecasts considered consumer spending patterns, regulatory shifts, and ingredient cost fluctuations. The analytical framework assessed market dynamics over the projection horizon, modeling segmentation dimensions including product type, form, ingredient source, distribution channel, and regional adoption. Compound annual growth rates were derived through regression analysis of historical data and projected market drivers, incorporating disposable income trends in metropolitan areas and certification uptake rates.
Sensitivities concentrate around unforeseen regulatory changes and significant shifts in raw material availability. Forecasts reflect assumptions regarding evolving consumer preferences and technological advancements in natural formulations. Material shifts in environmental policy or consumer behavior would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Screen Cleaner Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Floor Cleaning Device Market