
 Respiratory Virus Vaccines Market | 2026-2036
Respiratory Virus Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Virus Vaccines Market Analytics
Bioprocess engineering talent is rotating from small-molecule manufacturing into vaccine platform development, easing capacity constraints for novel modalities. GSK plc leverages its established adjuvant technology portfolio to sustain leadership in seasonal influenza combinations. Moderna Inc. anchors its pipeline expansion on mRNA respiratory platforms beyond COVID-19. Pfizer Inc. competes through integrated manufacturing scale and distribution reach across multiple respiratory indications.
Respiratory virus vaccines comprise immunological preparations designed to induce adaptive immunity against pathogenic agents affecting the pulmonary system, including influenza viruses, respiratory syncytial virus, and SARS-CoV-2 variants, typically formulated with antigenic components stabilized in buffered saline solutions with proprietary adjuvant systems and administered to prevent infection or attenuate disease severity in susceptible populations. mRNA vaccine platforms command premium positioning due to rapid redesign capabilities for variant strains, while inactivated virus formulations occupy mature, cost-sensitive procurement channels. Intranasal administration routes represent the fastest-growing vector as developers pursue mucosal immunity advantages and improved patient compliance relative to intramuscular delivery.
FDA accelerated approval pathways and EMA adaptive licensing frameworks shape development investment priorities by rewarding platforms with pandemic pivot potential. WHO prequalification standards govern access to procurement by government health agencies in lower-income settings, creating tiered market access conditions. Stakeholders must monitor platform diversification decisions as regulatory expectations for variant-matching speed and manufacturing resilience harden across jurisdictions.
Market Dynamics
FDA's accelerated approval pathways for pandemic preparedness are compressing development timelines from years to months, forcing manufacturers to reconfigure bioprocess engineering workflows around platform agility rather than batch optimization.
Growth Catalysts
- EMA Adaptive Licensing:The European framework rewards respiratory vaccine platforms demonstrating rapid variant-matching capabilities, directing R&D investment toward modular mRNA architectures.
- Federal Stockpiling Mandates:United States government procurement programs are broadening seasonal immunization volumes through multi-year supply agreements with hospital systems.
- Intranasal Delivery Platforms:Mucosal immunity advantages and improved pediatric compliance are pulling formulation investment away from intramuscular administration routes.
Market Restraints
- Cold Chain Infrastructure Gaps:Ultra-low temperature storage requirements for mRNA formulations limit distribution reach into rural health networks lacking specialized logistics capabilities.
- Adjuvant Supply Concentration:Proprietary adjuvant systems rely on concentrated specialty chemical suppliers, creating single-source vulnerability for combination vaccine production.
- WHO Prequalification Barriers:Stringent stability and manufacturing documentation standards exclude smaller developers from procurement by lower-income government health agencies.
Strategic Opportunities
- Combination Respiratory Formulations:Co-formulation of influenza, RSV, and coronavirus antigens into single-dose products addresses patient compliance fatigue and reduces healthcare system administration burden.
- Point-of-Care Manufacturing:Distributed micro-facilities using portable bioreactor systems could bypass centralized production bottlenecks during surge demand periods.
- India's Expanding CDMO Capacity:Contract development organizations in Indian pharmaceutical clusters are building mRNA platform capabilities to capture technology transfer from Western innovators.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Vaccine platform development competes with cell and gene therapy for limited pools of professionals skilled in continuous manufacturing and quality by design.
- Legacy Fill-Finish Equipment Retrofit:Existing aseptic processing lines require substantial capital reconfiguration to handle novel lipid nanoparticle formulations at commercial scale.
- Variant-Matching Clinical Trial Design:Immunological correlates of protection remain unresolved for emerging strains, complicating regulatory submission strategies across FDA and EMA jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Virus Vaccines Market |
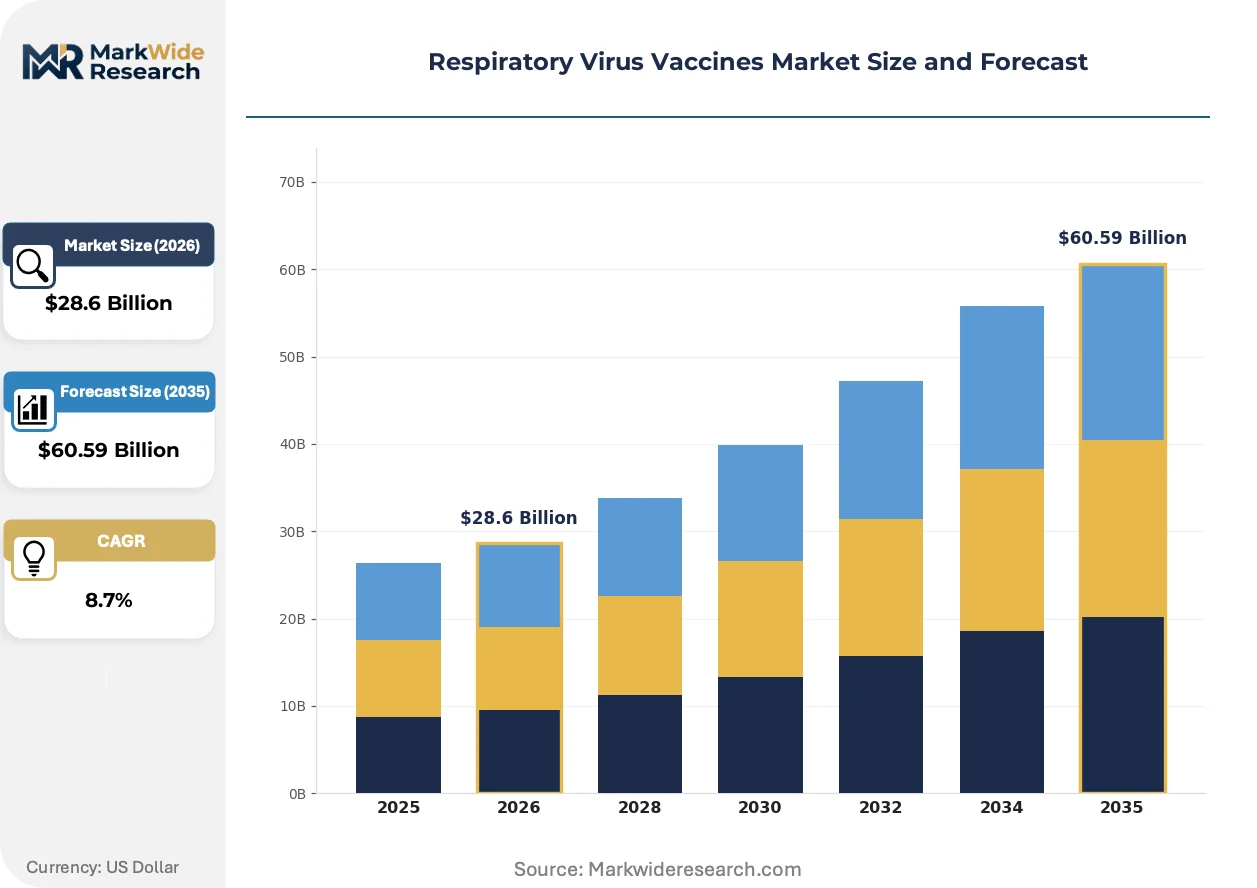
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Virus, Live Attenuated Virus, Subunit Vaccine, mRNA Vaccine Application: Public Health Immunization, Travel Vaccination, Clinical Use, Emergency Preparedness End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Government Health Agencies Administration Route: Intramuscular, Subcutaneous, Intranasal, Oral |
| Companies Covered | GSK plc, Pfizer Inc., Sanofi, Moderna Inc., Merck & Co., Inc., AstraZeneca, Johnson & Johnson Services, Inc., CSL Seqirus, Novavax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Virus Vaccines Market Evolving Landscape
Respiratory vaccine development is pivoting from platform standardization toward modular architectures that enable rapid antigen substitution without full process revalidation.
mRNA lipid nanoparticle formulations are fragmenting the established adjuvanted protein market by enabling seasonal strain updates within weeks rather than months. Hospital pharmacy directors are prioritizing these platforms for formulary inclusion despite premium positioning. The structural consequence is compression of traditional inactivated virus development timelines and consolidation of manufacturing investment around nucleic acid modalities.
REACH registration requirements for novel lipid excipients are extending European market entry timelines for next-generation delivery systems. Manufacturers must submit comprehensive toxicological dossiers for proprietary ionizable lipids before commercial distribution authorization. Small and mid-sized developers are responding by partnering with established chemical suppliers possessing existing regulatory master files.
Hospital procurement committees are consolidating respiratory vaccine purchasing through integrated delivery networks rather than individual facility contracting. Group purchasing organizations are capturing volume aggregation benefits and standardizing administration protocols across member health systems. This behavioral shift is most pronounced in United States metropolitan markets where health system consolidation has concentrated buying power among three to five regional networks.
Respiratory Virus Vaccines Market Segmentation
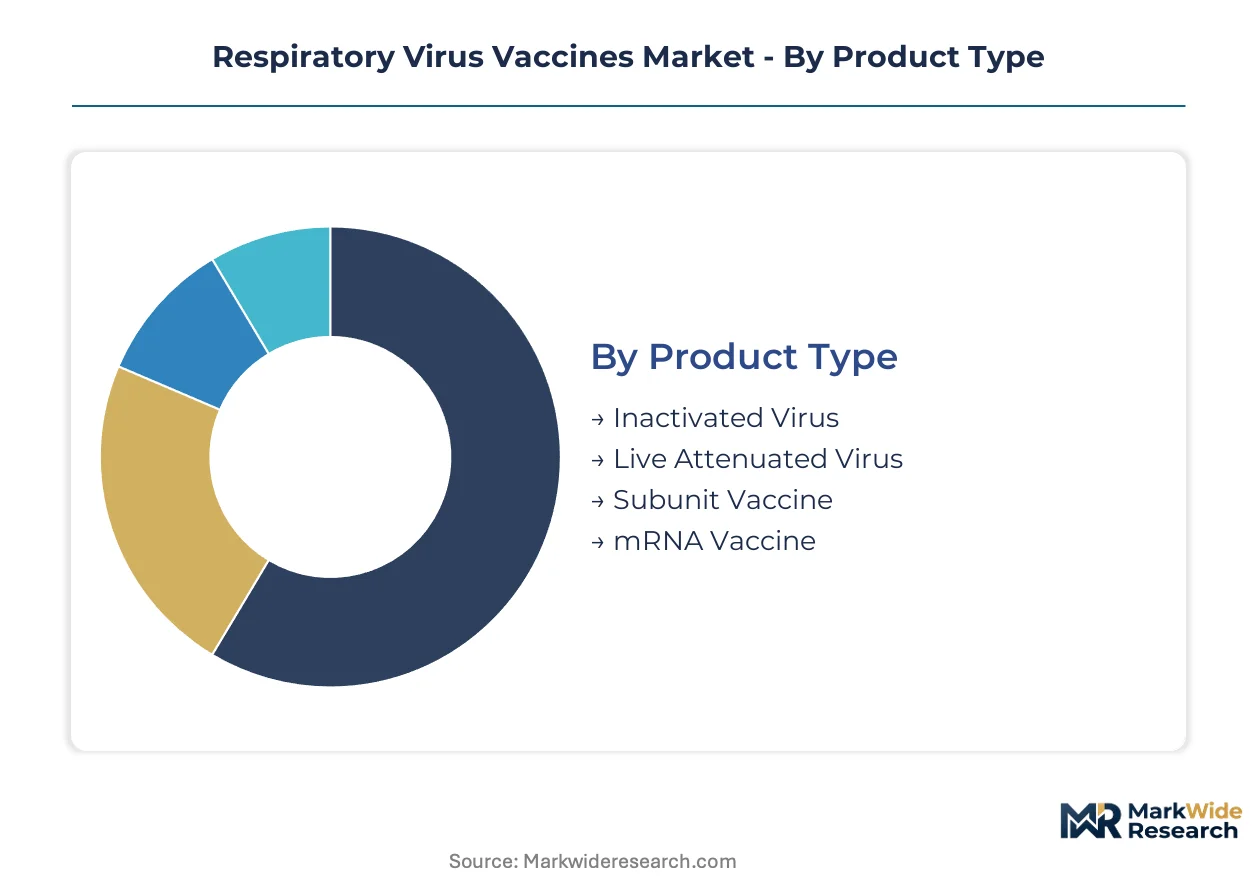
Segmentation in respiratory virus vaccines reveals how platform technology, procurement channel, and delivery mechanism each command distinct margin structures and regulatory requirements. Manufacturers must align R&D investment with the specific compliance and cold-chain demands of their target segments.
Product Type:
Margin pools concentrate in nucleic acid platforms where rapid strain adaptation commands premium pricing from hospital systems and government stockpiles.
- mRNA Vaccine:Lipid nanoparticle-encapsulated nucleic acid sequences enable antigen redesign within weeks of variant emergence. Procurement is concentrating in United States federal stockpiling programs and European hospital networks prioritizing pandemic pivot capacity over per-dose cost.
- Inactivated Virus:Chemically or heat-treated whole virions suspended in buffered saline with alum adjuvants. Demand clusters in cost-sensitive procurement channels across India and Southeast Asia where established cold-chain infrastructure supports traditional formulations.
- Live Attenuated Virus:Temperature-sensitive formulations requiring continuous refrigeration.
- Subunit Vaccine:Purified protein antigens combined with proprietary adjuvant systems.
The dominant share belongs to Inactivated Virus, while mRNA Vaccine is closing the gap fastest.
Application:
Volume concentration tracks government procurement mandates rather than private clinical demand, with multi-year supply agreements locking in manufacturing capacity years ahead of delivery.
- Public Health Immunization:Seasonal campaigns targeting influenza and expanding RSV coverage for pediatric and elderly populations. United States CDC procurement and European national immunization programs are broadening age-eligible cohorts and mandating healthcare worker vaccination.
- Emergency Preparedness:Strategic stockpiles maintained against pandemic surge requirements. BARDA and HHS contracts in the United States plus ECDC joint procurement mechanisms are compressing development-to-delivery timelines through platform pre-qualification.
- Travel Vaccination:Pre-departure immunization for Hajj pilgrimage and tropical deployment.
- Clinical Use:Individual patient administration in hospital and outpatient settings.
Public Health Immunization captures the largest procurement volumes, though Emergency Preparedness is expanding most quickly as sovereign stockpiling accelerates.
End User:
Customer type determines regulatory burden and payment terms, with government agencies imposing the most stringent stability documentation and longest approval cycles.
- Government Health Agencies:National immunization programs and pandemic preparedness authorities in the United States, Germany, and Japan. These buyers demand WHO prequalification and multi-year stability data, excluding smaller developers from tender participation.
- Healthcare Providers:Hospital systems and integrated delivery networks consolidating purchasing through group purchasing organizations. United States metropolitan markets show pronounced concentration among three to five regional networks standardizing formulary protocols.
- Pharmaceutical Companies:Licensees and partners seeking technology transfer for regional manufacturing.
- Research Institutions:Academic medical centers conducting immunogenicity studies and correlates of protection research.
Government Health Agencies dominate procurement value, while Healthcare Providers are gaining share fastest through formulary consolidation.
Administration Route:
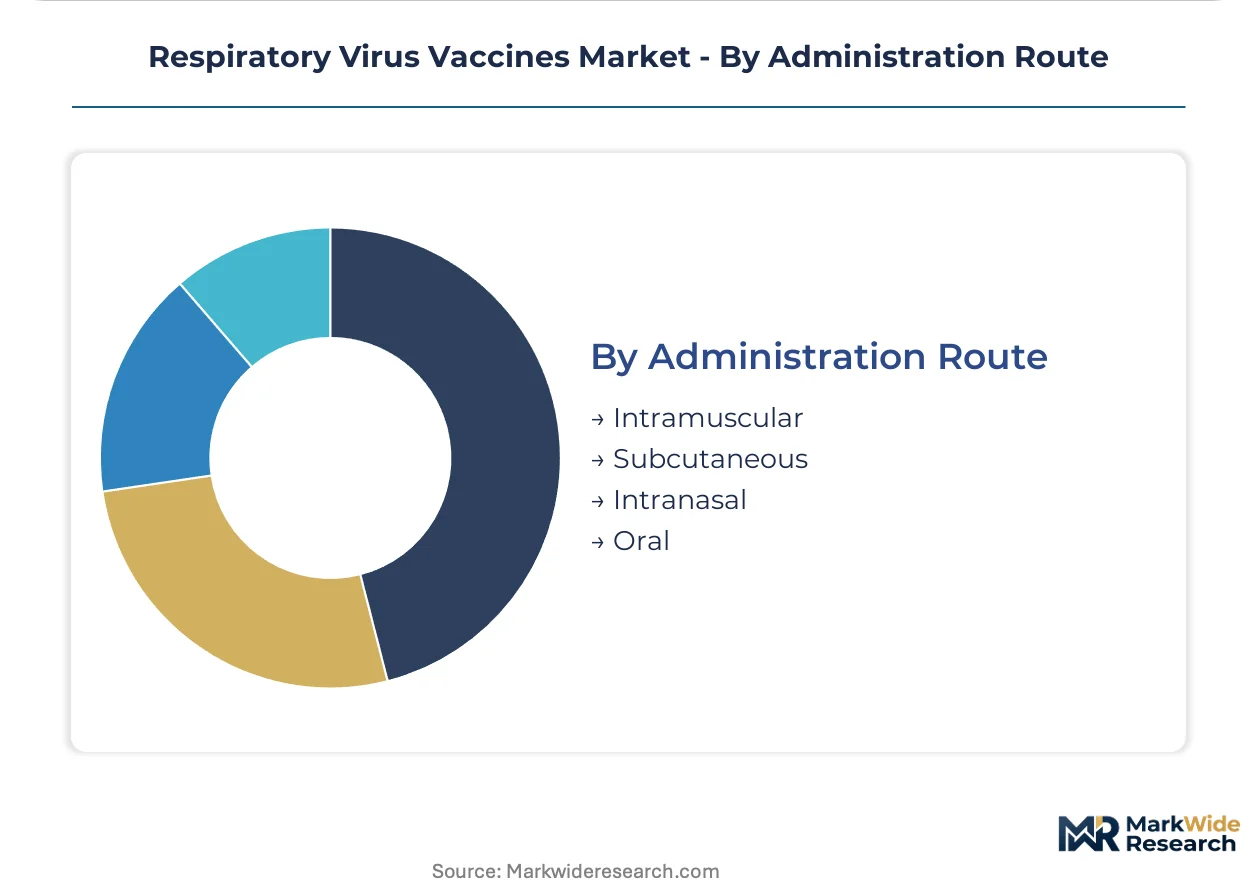
Delivery mechanism selection increasingly reflects pediatric compliance priorities and mucosal immunity hypotheses rather than manufacturing convenience.
- Intranasal:Aerosolized or droplet formulations depositing antigen on nasal mucosa to induce IgA-mediated protection. Development pipelines at Bharat Biotech and Codagenix are targeting improved patient acceptance and potential transmission-blocking effects in United States and Indian trials.
- Intramuscular:Needle-based delivery into deltoid or vastus lateralis muscle. This route retains dominant manufacturing scale and regulatory familiarity, with existing fill-finish lines optimized for standard syringe presentations across Pfizer and Moderna supply chains.
- Subcutaneous:Dermal deposition requiring smaller antigen doses.
- Oral:Enteric-coated formulations for gastrointestinal delivery.
Intramuscular administration holds the established position, yet Intranasal delivery is climbing the fastest as developers pursue differentiated immunological profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor procurement concentration in the United States, while EMA adaptive licensing and WHO prequalification standards shape tiered access across European hospital networks and lower-income settings.
United States
BARDA and HHS contracts compress development-to-delivery timelines through platform pre-qualification, while CDC procurement broadens seasonal immunization volumes. Federal stockpiling mandates lock in multi-year supply agreements with hospital systems. The Greater Boston and San Francisco Bay Area clusters concentrate mRNA platform engineering talent and bioprocess development facilities.
Germany
EMA adaptive licensing rewards respiratory vaccine platforms demonstrating rapid variant-matching capabilities, directing R&D investment toward modular architectures. National immunization programs demand multi-year stability data and WHO prequalification for tender participation. The Rhine-Main and Munich biotech corridors host lipid nanoparticle formulation development and adjuvant research operations.
India
CDSCO regulatory frameworks govern domestic manufacturing authorization while WHO prequalification standards enable access to government procurement in lower-income settings. The country's national pharmaceutical regulator maintains stringent documentation requirements for stability and manufacturing processes. Hyderabad and Pune pharmaceutical clusters are building mRNA platform capabilities through technology transfer from Western innovators.
Japan
PMDA review pathways emphasize manufacturing resilience and quality-by-design documentation for novel delivery systems. METI industrial policy supports domestic vaccine platform development through targeted funding mechanisms. The Kanto region around Tokyo anchors fill-finish operations and cold-chain distribution infrastructure for respiratory immunization programs.
United Kingdom
MHRA recognition procedures post-Brexit maintain alignment with EMA standards while enabling accelerated access pathways for pandemic preparedness. NHS procurement consolidation through integrated care systems standardizes formulary protocols across regional networks. The Oxford-Cambridge arc concentrates viral vector and subunit vaccine research facilities with adjacent bioprocess engineering capacity.
Respiratory Virus Vaccines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding procurement relationships through manufacturing scale and the lower tier competing on platform agility and adjuvant differentiation. The vendor base separates into three strategic archetypes: diversified pharmaceutical conglomerates with respiratory vaccine as one vertical, pure-play mRNA platform developers, and established influenza specialists leveraging adjuvant IP. Competitive moves center on combination formulation development and geographic manufacturing partnerships to bypass centralized production bottlenecks.
Within the integrated pharmaceutical tier, GSK plc and Pfizer Inc. exemplify archetypes built on adjuvant technology portfolios and manufacturing scale respectively. Moderna Inc. anchors the pure-play mRNA platform developer position. These three entities represent the dominant competitive anchors shaping procurement concentration in United States federal programs and European hospital networks.
| Leading Market Players |
|---|
| GSK plc |
| Pfizer Inc. |
| Sanofi |
| Moderna Inc. |
| Merck & Co., Inc. |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| CSL Seqirus |
| Novavax |
| Others |
Value Network & Pricing Analysis
mRNA lipid nanoparticle formulations displacing inactivated virus platforms in United States federal procurement are simultaneously redrawing supply geography toward Massachusetts and North Carolina manufacturing clusters while compressing premium pricing windows for traditional adjuvanted products.
Pricing Analysis
United States hospital networks pay 40-60% premiums over Indian government tenders for identical mRNA platforms. Three-tier pricing structure across pandemic stockpile, seasonal procurement, and private clinical channels reflects FDA emergency use authorization tiers and cold-chain compliance costs. Cost compression in the inactivated virus segment intensifies as Indian and Southeast Asian manufacturers scale alum-adjuvanted output for WHO prequalified procurement. Government health agencies exhibit lowest price sensitivity due to pandemic preparedness mandates, while private outpatient clinics face tightening reimbursement constraints.
Supply Chain Analysis
United States and Germany anchor lipid nanoparticle formulation and fill-finish operations, while India and South Korea build mRNA platform capabilities through technology transfer partnerships. Proprietary ionizable lipids, synthetic nucleosides, and single-use bioreactor assemblies draw from concentrated specialty chemical suppliers in Switzerland and Japan. Single-source vulnerability pervades adjuvant systems, where GSK's AS03 and MF59 portfolios dominate combination vaccine production. Distribution runs through centralized cold-chain hubs in metropolitan hospital networks, with last-mile rural delivery requiring specialized ultra-low temperature logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where FDA platform pre-qualification and multi-year BARDA contracts create switching costs that lock hospital systems into established supplier relationships.
For Market Incumbents: Consolidate manufacturing capacity in United States federal procurement corridors through backward integration into lipid nanoparticle production, neutralizing single-source chemical dependencies. Secure CDC formulary positioning by pre-positioning variant-matched mRNA sequences before seasonal strain selection, raising rival revalidation barriers.
For New Entrants and Emerging Players: Anchor in intranasal delivery platform development where mucosal immunity claims bypass head-to-head efficacy comparisons with intramuscular incumbents. Target Indian CDMO partnerships for WHO prequalification pathways, leveraging technology transfer agreements to access lower-income government procurement tenders closed to Western innovators.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors adjuvant IP holders and nucleic acid delivery specialists over single-product developers. Five-to-ten year viability hinges on combination formulation pipelines spanning influenza, RSV, and coronavirus antigens. Watch FDA correlates of protection guidance resolution as the signal triggering accelerated M&A in clinical-stage platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Combination Respiratory Formulation Development | Co-formulation of influenza, RSV, and SARS-CoV-2 antigens reduces administration burden for CDC immunization programs. |
| mRNA Platform Technology Transfer | Indian CDMO partnerships enable WHO prequalification access for manufacturers lacking established global cold-chain infrastructure. |
| Intranasal Delivery Clinical Advancement | Mucosal immunity positioning differentiates from intramuscular incumbents in pediatric and compliance-sensitive populations. |
| Adjuvant System Backward Integration | In-house ionizable lipid production mitigates single-source supply risk for combination vaccine manufacturing. |
| Point-of-Care Manufacturing Pilot | Distributed micro-facilities using portable bioreactors address surge demand gaps in pandemic response scenarios. |
Research Methodology
Operator-level perspectives from vaccine platform engineers, hospital formulary directors, regulatory affairs leads, and government procurement officers anchored the qualitative base. Primary interview insights triangulated against FDA emergency use authorization filings, EMA adaptive licensing submissions, CDC procurement databases, and WHO prequalification records. Bottom-up manufacturing capacity assessments and top-down epidemiological demand modeling converged on segment-level volume estimates.
Sensitivity analysis tested variant emergence frequency, cold-chain infrastructure investment rates, and adjuvant supply concentration scenarios across the projection horizon. Segmentation dimensions spanned platform technology, procurement channel, administration route, and regional regulatory cluster. CAGRs derived from epidemiological burden projections, immunization policy expansion trajectories, and manufacturing capacity buildout timelines. Correlates of protection establishment and pandemic declaration triggers served as scenario-branching inputs.
Material uncertainties — novel variant immunological escape, lipid excipient regulatory rejection, and sovereign manufacturing nationalism — sit outside the modeled envelope. Forecasts reflect assumptions about sustained platform pre-qualification incentives and stable cold-chain investment commitments. Recalibration cycles align with material shifts in FDA emergency use pathway scope and WHO prequalification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Europe Adenomyosis Drugs Market