
 Global RFID in Pharmaceuticals Market | 2026-2036
Global RFID in Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global RFID in Pharmaceuticals Market Foresight
Cloud-native RFID middleware is reconfiguring how pharmaceutical supply chains integrate real-time tracking with enterprise ERP systems. Zebra Technologies Corp. leverages its printer-encoder hardware portfolio to dominate manufacturing floor deployments. Avery Dennison Corporation anchors the smart label substrate layer with pharmaceutical-grade adhesive formulations. Impinj, Inc. competes through RAIN RFID chip sensitivity optimized for liquid-filled drug containers.
RFID in pharmaceuticals encompasses radio-frequency identification systems using electromagnetic fields to automatically identify and track drug products, typically operating at 860-960 MHz UHF or 13.56 MHz HF bands with anti-collision protocols enabling simultaneous reads of hundreds of tagged items. These systems serve primary industrial purposes of unit-level serialization, temperature excursion logging, and automated dispensing verification across controlled supply chain environments. Passive RFID tags lead unit volume due to sub-cent cost thresholds achievable at pharmaceutical-scale production, while cold chain monitoring represents the fastest-growing application segment as biologics expand and temperature integrity mandates tighten. Ultra High Frequency technology occupies the dominant technology position for pallet and case-level logistics, though High Frequency maintains entrenched position in item-level authentication where near-field precision prevents cross-read contamination.
The FDA's Drug Supply Chain Security Act mandates interoperable electronic tracking systems for pharmaceutical distribution, while the EU Falsified Medicines Directive requires unique identifier verification at point of dispense, and China's NMPA implements layered serialization standards for vaccine and critical medicine traceability. These regulatory frameworks collectively shape demand by mandating infrastructure investment timelines and specifying data granularity requirements that directly determine RFID system architecture choices. Stakeholders must monitor divergence between regional serialization standards to avoid redundant compliance infrastructure.
Market Dynamics
Serialization mandates across major pharmaceutical markets are compressing deployment timelines for track-and-trace infrastructure, forcing manufacturers to integrate RFID layers with existing packaging lines rather than greenfield builds. This retrofit imperative favors modular hardware architectures over proprietary end-to-end systems.
Growth Catalysts
- EU Falsified Medicines Directive:The mandate for unique identifier verification at point of dispense requires RFID-enabled scanning infrastructure across German, French, and Italian hospital pharmacies.
- Biologics cold chain expansion:Temperature-sensitive monoclonal antibodies and cell therapies demand continuous RFID sensor logging from manufacturing through last-mile delivery.
- Cloud-native middleware:Pharmaceutical ERP vendors are embedding native RFID data ingestion modules, reducing integration friction for serialization compliance.
Market Restraints
- Copper and silver ink volatility:Conductive antenna printing for UHF inlays faces input cost swings that compress tag margins at pharmaceutical volume scales.
- Reader hardware concentration:Fixed-position RFID interrogator manufacturing clusters in Shenzhen and Taipei create supply vulnerability for European pharmaceutical packaging lines.
- HF-UHF protocol fragmentation:Divergent frequency standards between item-level authentication and pallet-level logistics force dual-tagging investments.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO's phased serialization rollout for export-bound generics creates first-mover advantage for RFID-integrated packaging suppliers serving Mumbai-Pune manufacturing corridors.
- Blockchain-RFID convergence:Immutable ledger integration with tag data streams enables tamper-evident pedigree records for high-value oncology therapies.
- Direct-to-pharmacy distribution:Hospital purchasing consortiums in São Paulo and Mexico City are bypassing wholesale tiers, requiring RFID-enabled direct shipment verification.
Industry Challenges
- RF engineer scarcity:Pharmaceutical manufacturers lack in-house expertise for antenna tuning in liquid-filled container environments, forcing reliance on system integrator markups.
- Legacy line retrofit complexity:Existing blister packaging and vial-filling equipment requires mechanical modification to accommodate encoder-integrated print stations without throughput degradation.
- Multi-regional serialization reconciliation:Divergent data carrier specifications between FDA DSCSA and EU FMD force redundant tag encoding or region-specific SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RFID in Pharmaceuticals Market |
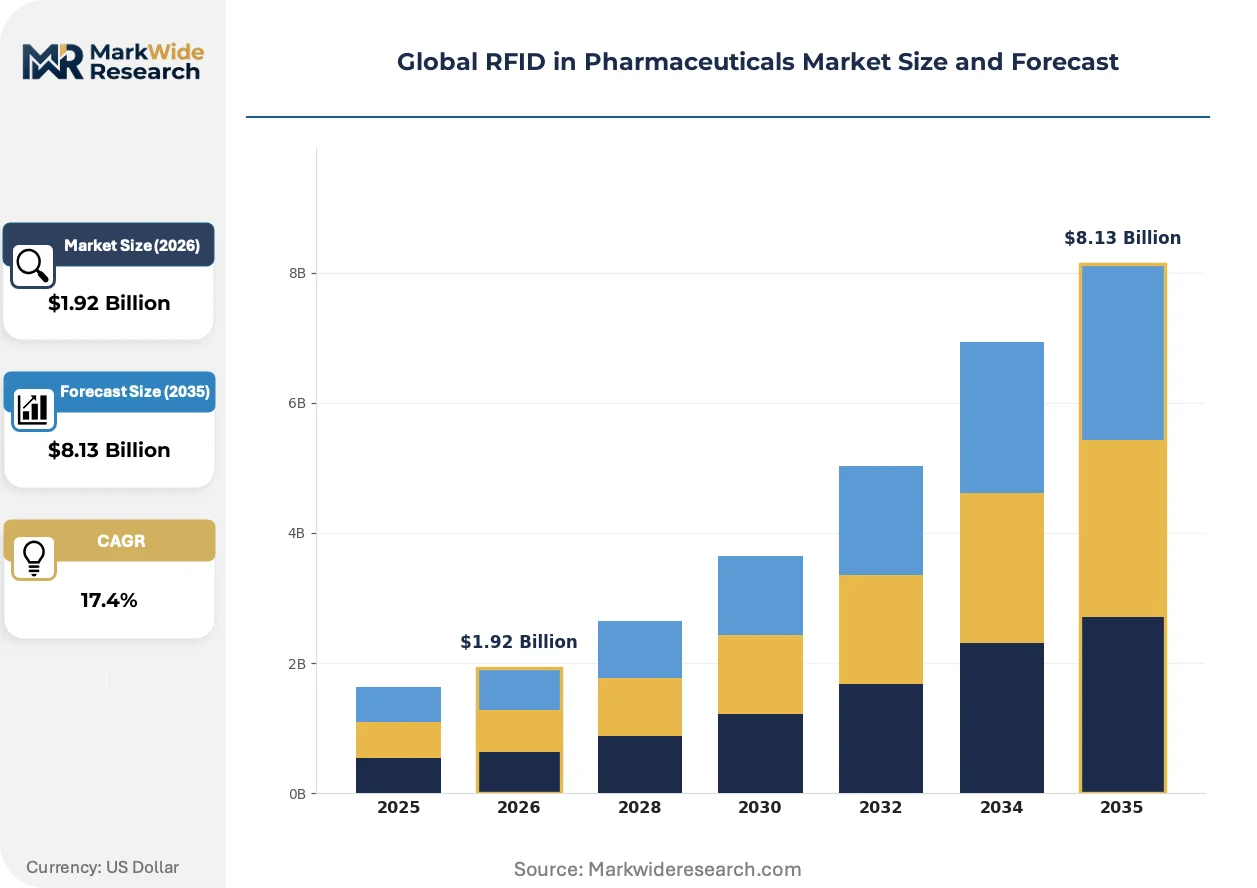
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $8.13 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive RFID Tags, Active RFID Tags, Semi-Passive RFID Tags, NFC Tags Application: Track & Trace, Inventory Management, Counterfeit Detection, Cold Chain Monitoring, Compliance Management End User: Pharmaceutical Manufacturers, Distributors, Retail Pharmacies, Contract Research Organizations, Clinical Trial Companies Technology: Ultra High Frequency, High Frequency, Low Frequency, Microwave Frequency |
| Companies Covered | Zebra Technologies Corp., Avery Dennison Corporation, Impinj, Inc., Honeywell International Inc, Nedap N.V., Alien Technology, LLC, CCL Healthcare, HID Global Corporation, GAO RFID Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RFID in Pharmaceuticals Market Shifts & Advancements
Active sensing capabilities are migrating from specialized cold chain dataloggers into standard passive RFID inlays, collapsing the cost and form-factor gap between simple identification and environmental monitoring. This convergence is redefining minimum viable tag specifications across pharmaceutical tiers.
Sensor-integrated RFID inlays are hybridizing temperature logging with standard EPC Gen2 identification, enabling pharmaceutical 3PLs to eliminate separate datalogger attachments for ambient-sensitive shipments. Contract packagers in the Netherlands and Belgium are piloting these dual-function tags for mRNA vaccine distribution. The technology is hybridizing what were previously discrete hardware categories into unified substrate layers.
China's NMPA has tightened serialization data retention requirements for vaccine traceability, mandating cloud-based verification accessible for seven years post-dispense. This policy compresses on-premise server deployments in favor of API-connected authentication services. Domestic Chinese pharmaceutical firms are responding by adopting RAIN RFID chips with enhanced write-cycle endurance for repeated status updates.
Hospital pharmacy buyers are consolidating RFID tag procurement through group purchasing organizations, displacing brand-specific contracts with performance-specified tenders. This procurement compression forces tag vendors to compete on read-range consistency rather than proprietary software lock-in. The shift is most pronounced in German and Swiss hospital networks where purchasing cooperatives command regional formulary influence.
Global RFID in Pharmaceuticals Market Segmentation
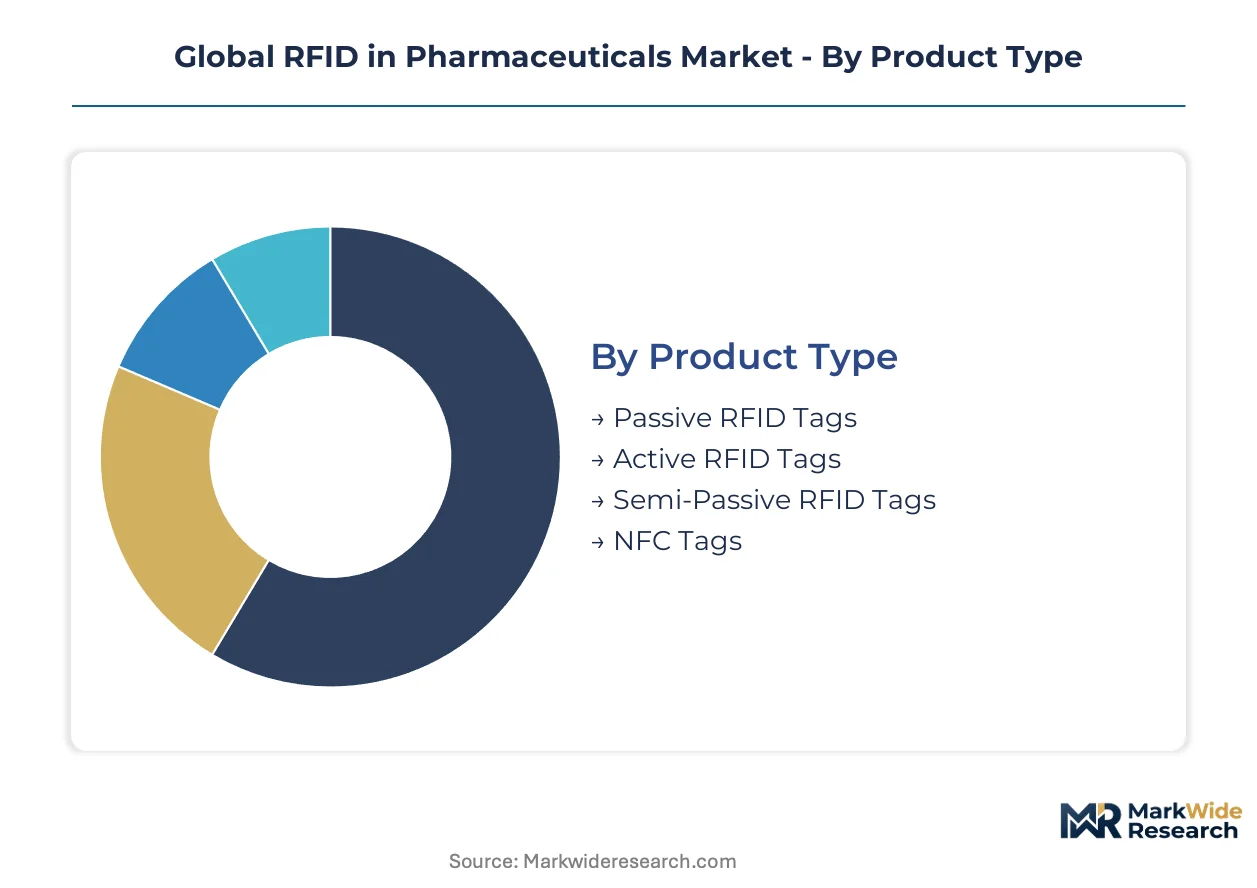
RFID pharmaceutical deployments fragment across power architectures, radio bands, and operational use cases. Each segmentation axis carries distinct procurement patterns and integration complexity that reshape vendor competitive positioning.
Product Type:
Mature passive tag economics dominate pharmaceutical unit volumes while active and sensing-enabled architectures emerge for specialized cold chain applications.
- Passive RFID Tags:Electromagnetic field-powered inlays with no onboard battery, achieving sub-cent unit costs at pharmaceutical production scales. German and Swiss contract packagers deploy these for EU FMD serialization compliance across blister packs and vial labels.
- Active RFID Tags:Battery-powered transponders with continuous beacon transmission and onboard sensor integration. Temperature-sensitive biologics shipments from Belgian 3PLs to hospital pharmacies drive concentrated demand for real-time location and excursion logging.
- Semi-Passive RFID Tags:Battery-assisted backscatter designs extending read range beyond passive limits without full active transmission power. These bridge architectures gain traction in high-value oncology therapy tracking where read reliability outweighs unit cost premiums.
- NFC Tags:13.56 MHz near-field devices enabling smartphone-readable authentication at pharmacy point-of-dispense. Patient-facing verification apps in France and Italy leverage NFC for anti-counterfeiting engagement.
Passive RFID tags retain volume leadership; active RFID tags hold the steepest expansion curve.
Application:
Cost tier stratification separates mandatory regulatory compliance deployments from discretionary efficiency investments.
- Track & Trace:Unit-level serialization enabling pedigree verification from manufacturing through dispense. FDA DSCSA and EU FMD mandates force pharmaceutical manufacturers to embed RFID layers alongside 2D barcode infrastructure.
- Cold Chain Monitoring:Continuous temperature logging for biologics, vaccines, and cell therapies. mRNA vaccine distribution networks in the Netherlands and Belgium pilot sensor-integrated inlays eliminating separate datalogger hardware.
- Inventory Management:Automated stock visibility in hospital pharmacies and wholesale distribution centers. RFID-enabled smart cabinets in German university hospitals reduce controlled-substance counting labor.
- Counterfeit Detection:Authentication layers verifying legitimate product origin at point of dispense. India's CDSCO export serialization requirements drive tag integration for generic shipments to regulated markets.
- Compliance Management:Automated documentation for regulatory audits and quality system records. Electronic batch records with RFID timestamps satisfy FDA 21 CFR Part 11 requirements.
Track & trace commands the largest compliance-driven spend; cold chain monitoring gains share fastest as biologics expand.
End User:
Customer type determines integration complexity, with manufacturers bearing primary serialization infrastructure investment while downstream tiers capture operational benefits.
- Pharmaceutical Manufacturers:Primary serialization obligation holders retrofitting packaging lines with print-encode-verify stations. Mumbai-Pune corridor exporters invest in dual-standard encoding for US and EU market access.
- Distributors:Wholesale verification nodes in three-tier US and two-tier European supply chains. McKesson and AmerisourceBergen equivalents deploy RFID tunnel readers for shipment validation.
- Retail Pharmacies:Hospital and community pharmacy dispense-point scanners for final verification. German hospital purchasing cooperatives consolidate RFID reader procurement across regional networks.
- Contract Research Organizations:Clinical supply chain visibility for investigational drug accountability. Temperature monitoring for IP shipments between depots and investigative sites.
- Clinical Trial Companies:Patient-specific kit identification and automated dispensing compliance. Direct-to-patient trial models require last-mile RFID verification.
Pharmaceutical manufacturers absorb the heaviest capital burden; retail pharmacies represent the fastest-climbing installation base as point-of-dispense mandates spread.
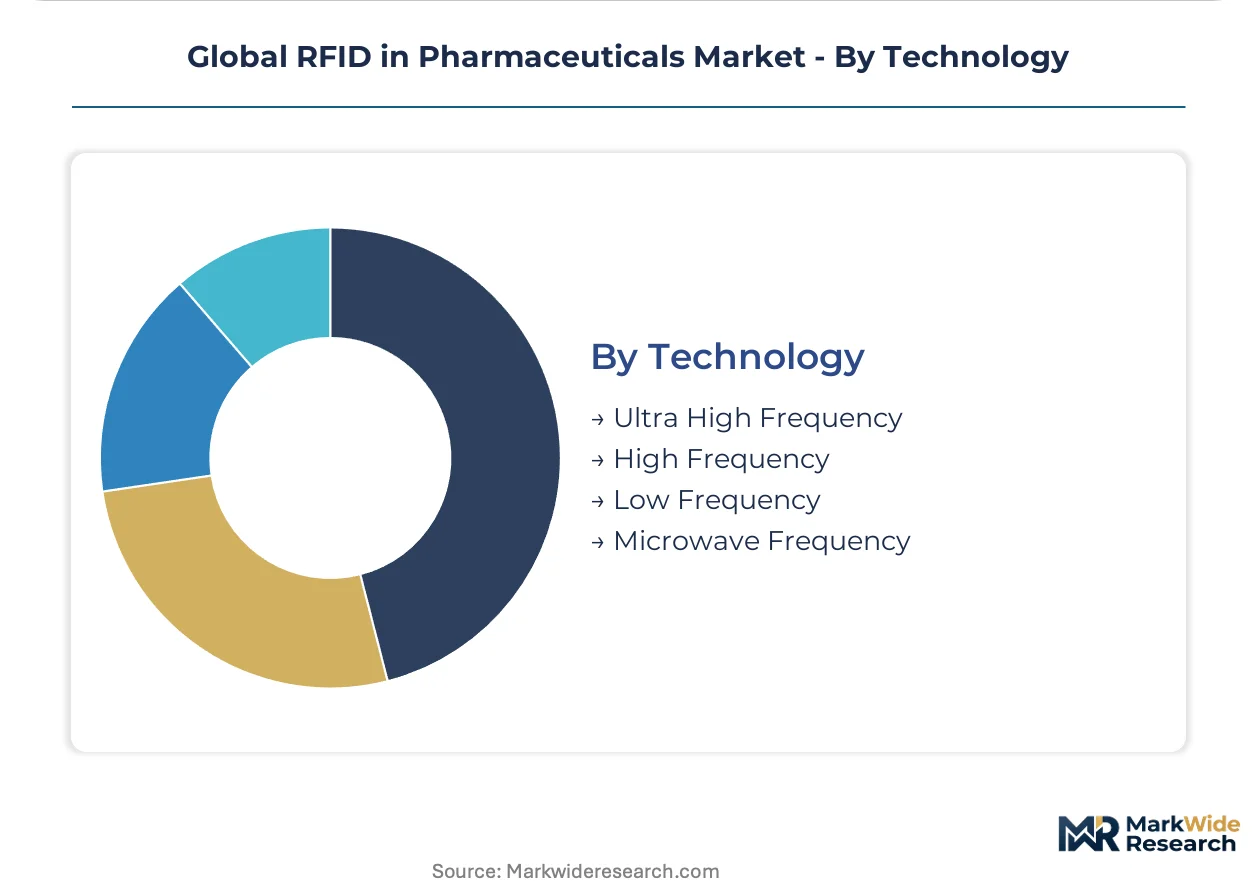
Technology:
Frequency band selection trades read range against precision, with UHF dominating logistics and HF securing item-level authentication.
- Ultra High Frequency:860-960 MHz backscatter systems enabling 10+ meter read ranges for pallet and case-level logistics. RAIN RFID dominates pharmaceutical distribution center automation.
- High Frequency:13.56 MHz near-field precision preventing cross-reads in dense item environments. HF maintains entrenched position in unit-level vial and blister pack authentication.
- Low Frequency:125-134 kHz inductive coupling with minimal RF interference in liquid-filled containers. Specialized applications in implantable device tracking and metal-proximity environments.
- Microwave Frequency:2.45 GHz and 5.8 GHz systems for specialized high-data-rate applications. Limited pharmaceutical penetration due to cost and liquid absorption constraints.
UHF technology leads logistics automation investment; HF secures enduring share in precision authentication use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Germany absorb the heaviest RFID infrastructure investment as EU Falsified Medicines Directive deadlines compress deployment timelines. Hospital purchasing cooperatives in German-speaking Europe consolidate procurement power, shifting vendor selection criteria toward read-range consistency.
Germany
Contract packagers in the Munich-Stuttgart corridor retrofit blister packaging lines with print-encode-verify stations for EU FMD compliance. The country's national pharmaceutical regulator mandates unique identifier verification at hospital pharmacy points of dispense. RFID-enabled smart cabinets in Heidelberg and Freiburg university hospitals reduce controlled-substance counting labor through automated inventory visibility.
United States
Wholesale distributors deploy tunnel readers for shipment validation under FDA Drug Supply Chain Security Act interoperability requirements. The FDA mandates electronic tracking systems for pharmaceutical distribution with phased implementation through 2023. Three-tier supply chain nodes in Memphis and Louisville concentrate RFID reader infrastructure investment for verification at distribution centers.
China
Domestic pharmaceutical firms adopt RAIN RFID chips with enhanced write-cycle endurance for NMPA vaccine traceability mandates. The NMPA tightened serialization data retention requirements mandating cloud-based verification accessible for seven years post-dispense. Yangtze River Delta vaccine manufacturers in Shanghai and Suzhou pilot sensor-integrated inlays for mRNA distribution networks.
India
Mumbai-Pune corridor exporters invest in dual-standard encoding infrastructure for simultaneous US and EU market access. The CDSCO implements phased serialization rollout for export-bound generics creating first-mover positioning for integrated packaging suppliers. Contract manufacturers in Hyderabad and Ahmedabad retrofit vial-filling equipment to accommodate encoder-integrated print stations without throughput degradation.
Netherlands
Belgian and Dutch 3PLs pilot sensor-integrated RFID inlays eliminating separate datalogger hardware for temperature-sensitive biologics. The EMA coordinates with national regulators on serialization standard alignment though implementation timelines vary by member state. Rotterdam distribution hubs serve as RFID infrastructure gateways for mRNA vaccine flows into German and French hospital networks.
Global RFID in Pharmaceuticals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, substrate, and middleware layers. The vendor base organizes around printer-encoder hardware dominance, smart label substrate supply, and RAIN RFID chip sensitivity optimization. Three archetypes anchor competitive positioning: integrated hardware-software platforms, specialized inlay and adhesive substrate suppliers, and semiconductor-focused chip designers. Capacity expansion in Asian manufacturing clusters and strategic partnerships for cloud-native middleware integration represent dominant competitive moves.
Among hardware-integrated platforms, Zebra Technologies Corp. and Honeywell International Inc exemplify the channel-controlling archetype through printer-encoder portfolio breadth. Avery Dennison Corporation anchors the substrate-specialist tier with pharmaceutical-grade adhesive formulations for smart label layers. Impinj, Inc. occupies the semiconductor-design position with RAIN RFID chip architectures optimized for liquid-filled drug container environments. These three company groupings represent the functional segmentation across which competitive rivalry intensifies as serialization mandates compress procurement timelines.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| Avery Dennison Corporation |
| Impinj, Inc. |
| Honeywell International Inc |
| Nedap N.V. |
| Alien Technology, LLC |
| CCL Healthcare |
| HID Global Corporation |
| GAO RFID Inc. |
| Others |
Supply & Pricing Matrix
Copper and silver ink volatility in conductive antenna printing compresses tag margins at pharmaceutical volume scales, forcing pricing tier spreads that widen between premium pharmaceutical-grade substrates and economy inlays while simultaneously reshaping sourcing footprints toward Asian manufacturing clusters.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate long-term tag supply agreements, insulating converters from commodity swings but passing base metal volatility through to pharmaceutical buyers. Pricing stratifies across premium, standard, and economy tiers driven by adhesive certification grade and read-range consistency specifications. Cost compression in economy-tier passive inlays intensifies because Chinese substrate oversupply erodes converter margins. Contract packagers in Germany and Switzerland exhibit lowest price sensitivity due to EU FMD compliance deadlines, while Indian generic exporters face acute budget constraints for dual-standard encoding infrastructure.
Supply Chain Analysis
Single-source vulnerability for fixed-position RFID interrogator manufacturing clusters in Shenzhen and Taipei creates supply risk for European pharmaceutical packaging lines awaiting EU FMD deployment deadlines. Semiconductor fabrication for RAIN RFID chips draws from Taiwan, South Korea, and domestic Chinese foundries, while pharmaceutical-grade adhesive substrates source from German chemical specialists and Malaysian tape converters. Distribution runs through three-tier pharmaceutical wholesale networks in the United States and two-tier European systems anchored by German distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID in pharmaceuticals sits at a platform-economics inflection where cloud-native middleware ecosystems are displacing proprietary hardware-software bundles, rewarding vendors who achieve API-level interoperability with SAP and Oracle ERP systems.
For Market Incumbents: Insulate hardware margins by embedding subscription-based middleware layers that capture recurring revenue from serialization compliance workflows. Deepen backward integration into pharmaceutical-grade adhesive substrate production to defend against Avery Dennison's substrate lock-in. Prioritize RAIN RFID chip write-cycle endurance enhancements for NMPA vaccine traceability mandates in China.
For New Entrants and Emerging Players: Build out sensor-integrated inlay capabilities for mRNA vaccine cold chain monitoring, the fastest-climbing application segment where incumbent tag vendors lack temperature logging expertise. Target Mumbai-Pune corridor contract manufacturers with modular print-encode-verify stations that retrofit existing vial-filling lines without throughput degradation. Pursue hospital purchasing cooperative tenders in German-speaking Europe with performance-specified read-range guarantees rather than proprietary software bundles.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors semiconductor-design specialists with liquid-container antenna tuning IP over hardware-integrated platforms facing margin compression. Long-term viability rests on cloud-native middleware attach rates rather than printer-encoder hardware shipments. Watch for FDA DSCSA-EU FMD data carrier harmonization negotiations as the signal for redundant compliance infrastructure rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Middleware Integration | API connectivity with SAP S/4HANA captures recurring revenue from serialization compliance workflows. |
| Sensor-Integrated Inlay Development | Dual-function temperature logging tags eliminate separate datalogger hardware for Belgian 3PLs. |
| Backward Integration into Substrates | In-house pharmaceutical-grade adhesive production defends margin position against substrate specialists. |
| Modular Print-Encode-Verify Retrofit | Mechanical adaptation kits enable EU FMD compliance on existing blister packaging lines. |
| Hospital Purchasing Cooperative Engagement | Performance-specified tenders in German networks displace brand-specific contract lock-in. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA DSCSA guidance documents, EMA serialization implementation reports, and NMPA vaccine traceability circulars. Primary interviews captured perspectives from pharmaceutical packaging line engineers, hospital pharmacy procurement managers, RFID systems integrators, and contract manufacturing executives. Secondary validation drew from customs trade data for RFID inlay imports, SEC 10-K disclosures from hardware vendors, and EU FMD national implementation databases. Bottom-up tag volume estimates triangulated against top-down pharmaceutical serialization compliance spending projections.
Forecast inputs span product type segmentation across passive, active, and sensing-enabled architectures; application segmentation across track-and-trace, cold chain monitoring, and inventory management; and end-user segmentation distinguishing pharmaceutical manufacturers from retail pharmacies and distributors. CAGRs derive from regulatory mandate timeline analysis, biologics cold chain expansion trajectories, and cloud-native middleware adoption curves across the projection horizon. Industry-specific inputs include EU FMD hospital pharmacy deadline enforcement patterns and NMPA vaccine serialization data retention requirements.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor foundries or cloud hyperscalers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Iodine Deficiency Drug Market