
 Home Respiratory Therapy Market | 2026-2036
Home Respiratory Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Home Respiratory Therapy Market Outlook
North American oxygen concentrator manufacturing is rebalancing after pandemic-era supply surges. ResMed leverages connected care platforms to sustain recurring revenue from sleep apnea patients. Inogen anchors its position through portable oxygen technology leadership. Philips navigates regulatory remediation while competing in the CPAP segment.
Home respiratory therapy encompasses mechanical and gas-exchange support devices designed for non-clinical environments, typically operating at pressure ranges of 4-20 cm H₂O for positive airway systems and oxygen flow rates of 1-5 L/min for concentrator units, serving patients with chronic or acute respiratory insufficiency outside institutional settings. CPAP devices dominate value pools among product types due to sleep apnea prevalence and replacement cycles, while digital health solutions represent the fastest-expanding technology dimension as remote patient monitoring integrates with reimbursement models. Ventilators occupy a premium niche within the product mix, serving high-acuity homecare patients with chronic conditions.
FDA clearance pathways for Class II medical devices shape product development timelines and market entry costs for manufacturers targeting the United States. Medicare competitive bidding programs and HIPAA data requirements simultaneously constrain pricing and mandate connectivity standards for connected respiratory devices. Stakeholders must weigh reimbursement stability against sensor-enabled adherence monitoring when allocating R&D investment across device portfolios.
Market Dynamics
Medicare competitive bidding programs are compressing margins for durable medical equipment suppliers while simultaneously mandating connected device capabilities, forcing manufacturers to absorb connectivity costs without proportional reimbursement relief.
Growth Catalysts
- Hospital-at-home waivers:CMS emergency waivers for acute-level care in residential settings are expanding ventilator and high-flow oxygen eligibility beyond traditional homebound criteria.
- OSA prevalence:Undiagnosed obstructive sleep apnea in the United States creates replacement demand for CPAP devices as screening penetrates primary care networks.
- Remote therapeutic monitoring:CPT codes for respiratory monitoring reimburse providers for digital adherence data, incentivizing sensor-equipped device procurement.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries control critical microcontroller supply for oxygen concentrator flow sensors, creating single-source vulnerability.
- Lithium-ion cost volatility:Portable oxygen concentrator battery packs depend on cathode materials subject to commodity price swings in cobalt and nickel markets.
- CE-MDR transition friction:European Union medical device regulation recertification timelines are delaying product line extensions for legacy oxygen delivery systems.
Strategic Opportunities
- Rural health clinic integration:Federally qualified health centers in Appalachian and Southwestern states lack respiratory therapy capacity, creating white-space for telehealth-integrated device deployment.
- COPD exacerbation prediction:Machine learning models applied to nocturnal oximetry data are converging with pulse-dose delivery algorithms to enable preemptive intervention.
- VA procurement centralization:Department of Veterans Affairs consolidated purchasing for spinal cord injury ventilator patients offers volume contracting advantages for multi-setting device platforms.
Industry Challenges
- Respiratory therapist staffing:Home medical equipment providers face recruitment gaps for credentialed clinicians capable of ventilator setup and patient education in non-institutional environments.
- Firmware validation cycles:FDA software-as-medical-device guidance requires documented verification for over-the-air updates to connected CPAP algorithms, extending release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Respiratory Therapy Market |
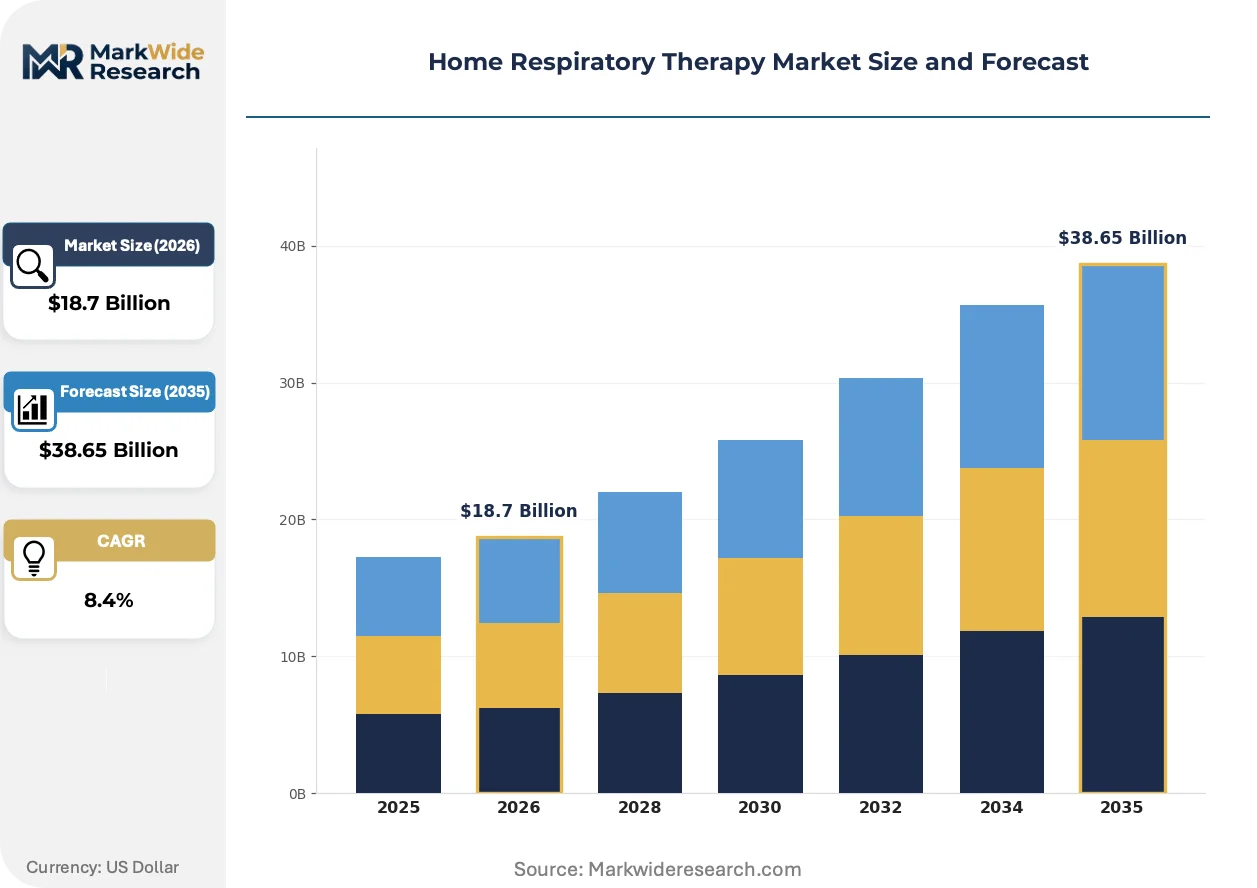
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, CPAP Devices, Nebulizers, Oxygen Concentrators End User: Homecare Patients, Elderly, Pediatric Patients, Individuals with Chronic Conditions Technology: Digital Health Solutions, Sensor Technology, Wireless Monitoring, Smart Devices Application: Chronic Obstructive Pulmonary Disease, Sleep Apnea, Asthma Management, Lung Rehabilitation |
| Companies Covered | Lincare Holdings (Linde plc), Inogen, ResMed, Getinge AB, AdaptHealth, Koninklijke Philips, Apria Healthcare Group (Owens & Minor), Drive Devilbiss International, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Respiratory Therapy Market Strategic Shifts
Device connectivity is transitioning from competitive differentiator to reimbursement prerequisite, while artificial intelligence applications migrate from sleep staging to predictive respiratory event detection.
Multi-parameter sensing is converging with cloud-based adherence analytics to transform CPAP machines into longitudinal respiratory health platforms. Sleep medicine practices are adopting these integrated systems to satisfy payor documentation requirements for continued therapy authorization. The technology is converging with remote patient monitoring infrastructure to compress the gap between device data capture and clinical intervention.
FDA's evolving enforcement discretion for artificial intelligence-enabled diagnostic features is reshaping predicate device selection for 510(k) submissions. Manufacturers must now demonstrate algorithm change control protocols as part of premarket review. High-acuity home ventilator segments are responding by segregating AI-enabled modules into distinct regulatory submissions from base hardware platforms.
Patients are assuming greater cost-sharing responsibility for device accessories and replacement supplies, altering purchasing patterns for tubing and mask interfaces. Durable medical equipment suppliers are responding with subscription-based consumable programs that bundle filtration components with remote monitoring services. This behavioral shift is most visible in Medicare Advantage plans with supplemental benefits for chronic condition management.
Home Respiratory Therapy Market Segmentation
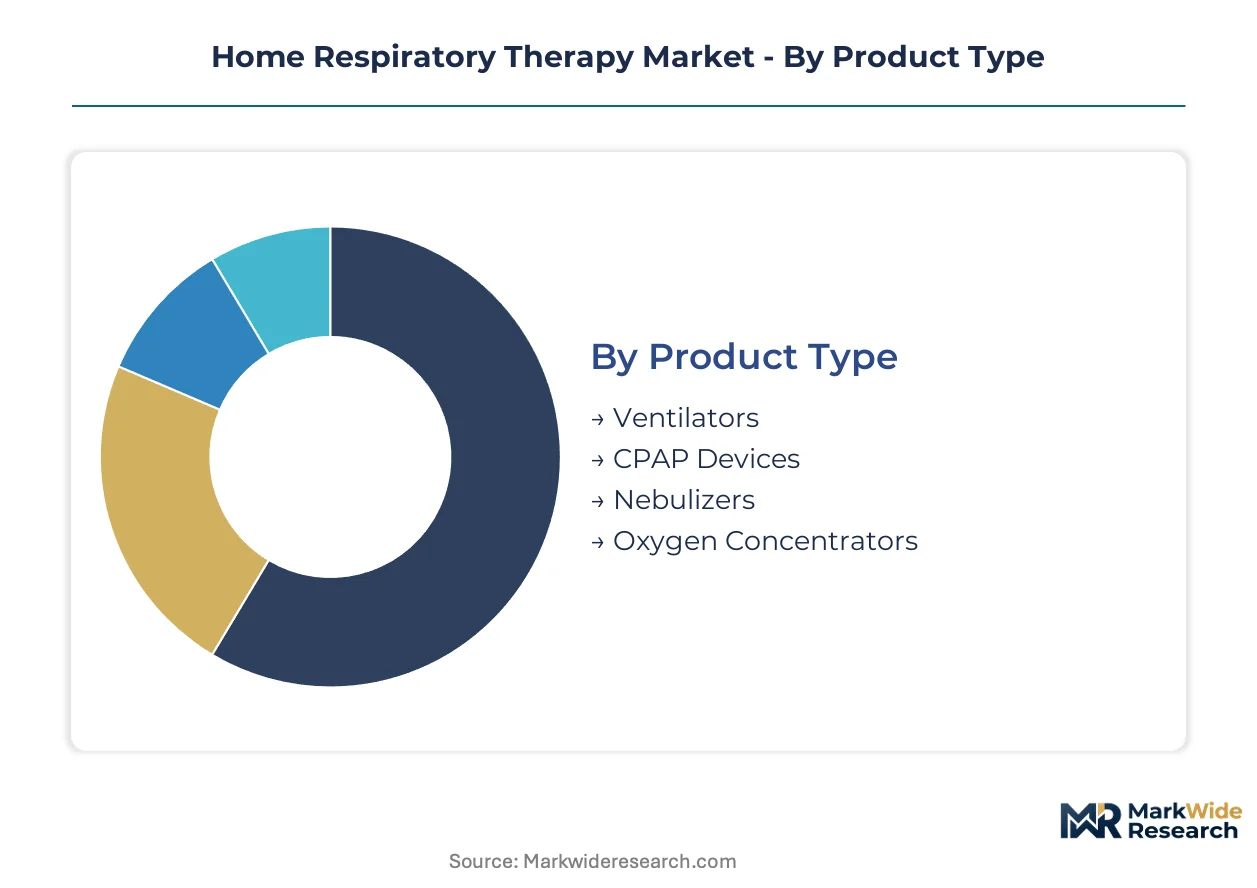
Home respiratory therapy segmentation reveals how regulatory pathways, patient acuity levels, and connectivity requirements fragment procurement decisions across device categories. Manufacturers must align product portfolios with distinct reimbursement codes and clinical workflows that vary sharply by segment.
Product Type:
FDA Class II 510(k) clearance dominates ventilators and CPAP devices, while oxygen concentrators navigate simpler regulatory paths; nebulizers face the lightest certification burden among the four categories.
- Ventilators:High-acuity positive and negative pressure systems delivering mechanical ventilation at 4-40 cm H₂O, incorporating battery backup and alarm systems for life-sustaining homecare. Demand concentrates among spinal cord injury and ALS patients in the United States, where Medicare's hospital-at-home waivers expanded eligibility beyond traditional homebound criteria.
- CPAP Devices:Continuous positive airway pressure systems operating at 4-20 cm H₂O with heated humidification and auto-titrating algorithms for obstructive sleep apnea. Replacement cycles drive volume in the United States as primary care screening penetrates employer wellness programs and Medicare Advantage plans.
- Nebulizers:Jet and mesh aerosol delivery systems converting liquid bronchodilators into respirable particles for acute symptom relief. Pediatric asthma management in Medicaid-enrolled households generates consistent demand.
- Oxygen Concentrators:Pressure swing adsorption units generating 90-96% concentrated oxygen at 1-10 L/min flow rates. Portable variants with lithium-ion batteries serve ambulatory COPD patients; stationary units dominate nighttime prescriptions.
Leading the category by volume: CPAP Devices. Growing fastest: Ventilators.
End User:
Reimbursement complexity and care coordination intensity separate these patient populations, with chronic condition cohorts requiring the most intensive device training and remote monitoring infrastructure.
- Homecare Patients:Individuals discharged from acute care with durable medical equipment prescriptions for post-acute recovery or long-term respiratory support. Hospital-at-home program expansion in the United States is accelerating ventilator and high-flow oxygen deployment to this cohort.
- Elderly:Medicare beneficiaries over 65 with age-related respiratory decline, sleep-disordered breathing, and comorbid cardiovascular conditions. Competitive bidding program constraints compress margins for suppliers serving this price-sensitive population.
- Pediatric Patients:Children with congenital anomalies, premature birth complications, or cystic fibrosis requiring size-appropriate interfaces and family-centered training protocols. Medicaid funding variability across states creates geographic access disparities.
- Individuals with Chronic Conditions:COPD, interstitial lung disease, and neuromuscular disorder patients with predictable long-term device needs. Remote therapeutic monitoring CPT codes incentivize connected device procurement for this adherence-tracked population.
Dominant by prescription volume: Elderly. Expanding most quickly: Homecare Patients.
Technology:
Connectivity infrastructure costs and HIPAA compliance requirements create tiered investment barriers, with full-stack digital platforms commanding premium positioning against component-level sensor suppliers.
- Digital Health Solutions:Cloud-based adherence analytics platforms integrating multi-device data streams for longitudinal respiratory monitoring. Sleep medicine practices adopt these systems to satisfy payor documentation requirements for continued therapy authorization.
- Sensor Technology:Flow, pressure, and oximetry sensors embedded within device air pathways for real-time parameter capture. Taiwan-based foundry concentration for microcontroller supply creates single-source vulnerability for oxygen concentrator flow sensors.
- Wireless Monitoring:Bluetooth and cellular transmission modules enabling over-the-air data upload to clinical dashboards. FDA software-as-medical-device guidance extends firmware validation cycles for manufacturers.
- Smart Devices:AI-enabled CPAP machines with auto-titrating algorithms and predictive respiratory event detection. Algorithm change control protocols are now required as part of 510(k) premarket review.
Highest deployment penetration: Digital Health Solutions. Steepest expansion trajectory: Smart Devices.
Application:
Clinical endpoint heterogeneity shapes device specification requirements, with sleep apnea demanding comfort-optimized interfaces while COPD management prioritizes oxygen conservation and exacerbation prediction.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy and non-invasive ventilation for emphysema and chronic bronchitis patients. Machine learning models applied to nocturnal oximetry data are converging with pulse-dose delivery algorithms to enable preemptive intervention.
- Sleep Apnea:Obstructive and central sleep-disordered breathing management through positive airway pressure. Undiagnosed prevalence in the United States creates replacement demand as screening penetrates primary care networks.
- Asthma Management:Rescue nebulization and controller medication delivery for reactive airway disease. Pediatric Medicaid enrollment drives volume in this segment.
- Lung Rehabilitation:Post-surgical recovery and interstitial lung disease maintenance through ventilatory support and oxygen supplementation. VA consolidated purchasing for spinal cord injury patients offers volume contracting advantages.
Largest installed base: Sleep Apnea. Gaining share fastest: Chronic Obstructive Pulmonary Disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in South America's salt flats and cobalt mining in the Democratic Republic of Congo anchor battery supply chains that power portable oxygen concentrators worldwide. Taiwan-based semiconductor foundries concentrate microcontroller production for flow sensors. German precision engineering clusters manufacture high-acuity ventilator components.
United States
Medicare hospital-at-home waivers and aging demographics drive ventilator deployment to residential settings. FDA Class II 510(k) clearance pathways shape product development timelines for connected CPAP devices. Minnesota's medical device corridor hosts major respiratory equipment manufacturers developing auto-titrating algorithms.
Germany
CE-MDR recertification timelines delay legacy oxygen delivery system extensions while creating compliance bottlenecks. The EU Medical Device Regulation mandates enhanced clinical evidence for high-acuity home ventilators. Baden-Württemberg's precision engineering cluster produces pressure sensors and flow control valves for European device manufacturers.
Japan
Super-aging society demographics expand long-term oxygen therapy prescriptions for COPD management. PMDA regulatory frameworks prioritize software validation for AI-enabled diagnostic features in sleep apnea devices. Osaka-based electronics manufacturers supply pulse oximetry sensors to regional device assemblers.
China
Domestic production of pressure swing adsorption units scales to serve hospital-at-home programs in tier-one cities. NMPA medical device registration requirements extend timelines for imported high-acuity ventilators. Shenzhen's hardware ecosystem manufactures lithium-ion battery packs for portable concentrator exports.
India
Medicaid-enrolled pediatric asthma populations generate consistent nebulizer demand across state-level procurement programs. CDSCO medical device rules classify oxygen concentrators as notified devices requiring import licenses. Gujarat's pharmaceutical manufacturing belt produces bronchodilator formulations paired with mesh nebulizer devices.
Home Respiratory Therapy Market Competitive Environment
Global majors compete with regional champions across reimbursement access and connectivity platform integration. The vendor base clusters around three tiers: diversified healthcare conglomerates with sleep medicine portfolios, pure-play respiratory device specialists, and durable medical equipment distributors with local service networks. Strategic moves concentrate on connected care platform development and vertical integration into sensor manufacturing.
Within the diversified healthcare tier, Koninklijke Philips and Medtronic exemplify conglomerate-scale positioning across multiple respiratory modalities. ResMed represents the connected-care specialist archetype with cloud-based adherence analytics. Inogen occupies a position as the portable oxygen technology pure-play. Lincare Holdings and AdaptHealth exemplify the durable medical equipment distribution model with Medicare contracting scale.
| Leading Market Players |
|---|
| Lincare Holdings (Linde plc) |
| Inogen |
| ResMed |
| Getinge AB |
| AdaptHealth |
| Koninklijke Philips |
| Apria Healthcare Group (Owens & Minor) |
| Drive Devilbiss International |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Medicare competitive bidding programs for durable medical equipment concentrate purchasing power among national suppliers, compressing margins and forcing manufacturers toward subscription-based service bundling for connected CPAP and ventilator platforms.
Pricing Analysis
Warranty and remote monitoring service bundling now separates premium CPAP tiers from economy alternatives, with FDA 510(k) clearance status and cellular connectivity modules driving price differentiation. Cost compression in portable oxygen concentrators intensifies as lithium-ion battery pack expenses fluctuate with cobalt and nickel commodity markets. Hospital-at-home waiver patients exhibit lowest price sensitivity due to Medicare coverage, while cash-pay retail channels serving undiagnosed sleep apnea populations face steepest competitive discounting.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries controlling microcontroller supply for oxygen concentrator flow sensors. Device manufacturing draws from German precision engineering clusters for pressure sensors, Chinese lithium-ion battery pack assembly for portable units, and South Korean display components for patient interfaces. Tariff exposure on Chinese-sourced electronics creates margin risk for US-assembled devices. Distribution runs through durable medical equipment suppliers with Medicare contracting scale and direct-to-patient fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device guidance and HIPAA data requirements erect substantial compliance moats, advantaging established players with documented algorithm change control protocols and cloud infrastructure security certifications.
For Market Incumbents: Extend connected care platform capabilities through backward integration into sensor manufacturing, reducing Taiwan foundry dependency for flow control components. Consolidate respiratory therapist training networks to defend against staffing shortages threatening ventilator setup quality. Prioritize CE-MDR recertification investments to maintain European market access amid regulatory friction. For New Entrants and Emerging Players: Capture rural health clinic integration opportunities in Appalachian and Southwestern states where federally qualified health centers lack respiratory therapy capacity. Target pediatric asthma management segments with Medicaid-aligned nebulizer offerings and family-centered training protocols. Deploy telehealth-integrated device platforms to differentiate against incumbent service models. For Investors and Strategic Acquirers: The window for entry favors digital health platforms with FDA-cleared remote therapeutic monitoring infrastructure and established CPT code reimbursement pathways. Long-term viability hinges on AI-enabled predictive analytics capabilities converging with pulse-dose oxygen delivery algorithms. Watch Medicare Advantage plan supplemental benefit expansions for chronic condition management as inflection signal for connected device procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI-Enabled CPAP | Algorithm change control protocols now required for auto-titrating sleep apnea devices seeking US market entry. |
| CE-MDR Recertification Pathway | Enhanced clinical evidence mandates delay legacy oxygen delivery extensions across European Union markets. |
| Hospital System Partnership | Hospital-at-home waivers from CMS expand ventilator eligibility beyond traditional homebound criteria. |
| Software Companion Development | Cloud-based adherence analytics satisfy payor documentation requirements for continued therapy authorization. |
| Reimbursement Strategy | Remote therapeutic monitoring CPT codes incentivize sensor-equipped device procurement by adherence-tracked populations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and durable medical equipment procurement leads. FDA 510(k) premarket notification databases, CMS Medicare claims data, and European medical device regulatory submissions provided device-specific validation. Bottom-up unit shipment estimates triangulated against top-down reimbursement expenditure models across product categories.
Segment-level modeling operated at technology-deployment configuration, patient acuity tier, and connectivity capability granularity throughout the forecast period. CAGRs derived from fitted trend extrapolation calibrated to Medicare competitive bidding program impact and hospital-at-home waiver expansion trajectories. Forecast inputs incorporated semiconductor supply concentration indices and lithium-ion commodity price band assumptions.
The model holds under stable Medicare reimbursement and FDA enforcement discretion conditions; deviation in CE-MDR implementation timelines or Taiwan semiconductor supply disruptions would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market