
 Automatic Gate and Door Opening System Market | 2026-2036
Automatic Gate and Door Opening System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Gate and Door Opening System Market Intelligence
The European Union's Energy Performance of Buildings Directive (EPBD) is shifting demand towards systems with better thermal insulation and lower standby power consumption. Assa Abloy leverages its extensive portfolio to meet these new standards across commercial and residential sectors. Chamberlain Group specializes in smart home-integrated garage door openers for the North American market. FAAC S.p.A. competes on the durability of its hydraulic operators for high-traffic commercial gates in Europe.
An automatic gate and door opening system is an electromechanical or hydraulic assembly that automates entry points using motors, sensors, and control units. These systems often integrate technologies like infrared sensors or Radio Frequency Identification (RFID) for secure access control. Sliding gate operators and garage door openers represent the largest product segments by volume. Demand from warehousing units and commercial facilities shows significant momentum, driven by logistics sector modernization and the need for efficient building management.
Safety regulations such as UL 325 in the United States and the CE marking framework governed by the Machinery Directive in Europe dictate mandatory features. These standards, focusing on entrapment protection and operational reliability, directly influence product design and market access. Stakeholders must now determine how to best integrate advanced sensor technologies and IoT connectivity to create value beyond basic automation.
Market Dynamics
The market's primary structural force is the convergence of stringent safety regulations with the demand for IoT-enabled smart building integration. This dual pressure compels manufacturers to innovate beyond basic automation, embedding advanced sensing and connectivity into core product designs.
Growth Catalysts
- Logistics Sector Modernization:The expansion of warehousing and distribution centers, particularly in logistics hubs across the United States and Germany, necessitates high-cycle, durable, and automated door systems to improve throughput and operational efficiency.
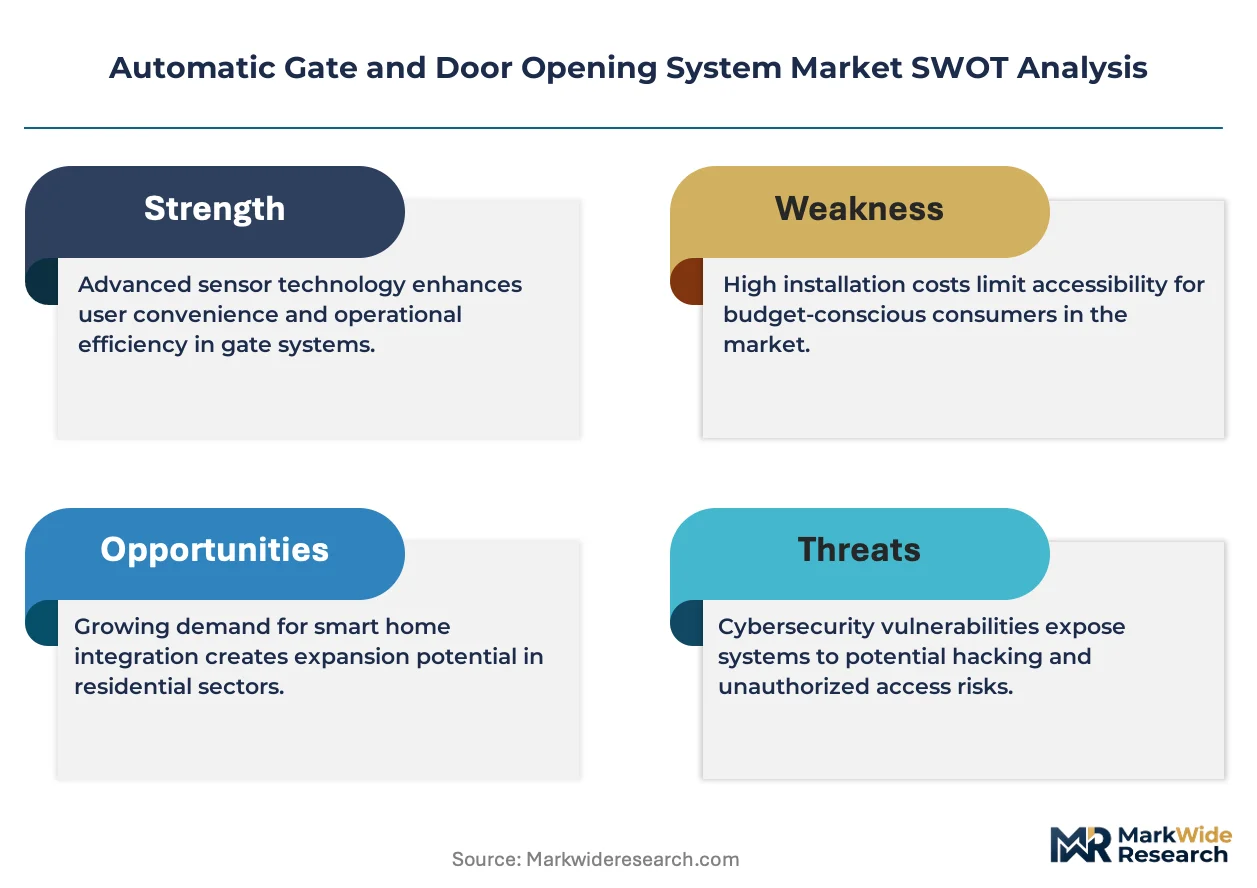
- Regulatory Mandates:The European Union's Machinery Directive and Energy Performance of Buildings Directive (EPBD) are compelling the adoption of systems with enhanced safety features and superior thermal insulation, directly influencing product development priorities.
- Access Control Technology:The integration of Radio Frequency Identification (RFID) and other credential-based technologies provides a significant pull for upgrading systems in commercial and industrial facilities seeking to enhance security and streamline access management.
Market Restraints
- High Installation Costs:The significant upfront investment required for heavy-duty hydraulic operators and the associated civil engineering work for in-ground systems can be a substantial barrier for small to medium-sized commercial enterprises.
- Integration Complexity:Achieving seamless interoperability between new automated gate systems and a facility's existing, often proprietary, building management or security platforms presents a significant technical hurdle and can deter adoption.
- Component Supply Volatility:The reliance on a concentrated global supply chain for critical electronic components, such as microcontrollers and specialized sensors, exposes manufacturers to price fluctuations and potential production delays.
Strategic Opportunities
- Predictive Maintenance Services:Leveraging IoT connectivity to offer data-driven predictive maintenance subscriptions creates a new recurring revenue stream, moving beyond a transactional hardware sales model for manufacturers and service providers.
- Retrofit Market for Energy Efficiency:A substantial opportunity exists in upgrading older commercial and residential buildings with modern, insulated door systems to comply with new energy standards like the EPBD in Europe.
- Smart Home Ecosystem Integration:Developing operators with native support for major smart home platforms in the North American residential market allows for differentiation and appeals to consumer demand for unified home automation experiences.
Industry Challenges
- Skilled Technician Shortage:The industry faces a deficit of installation and service technicians who possess the dual expertise in mechanical systems and the IT networking skills required for configuring modern, connected gate and door openers.
- Compliance and Certification Timelines:Navigating the complex and time-consuming certification processes for standards like UL 325 in the United States and CE marking in Europe can delay product launches and increase development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Gate and Door Opening System Market |
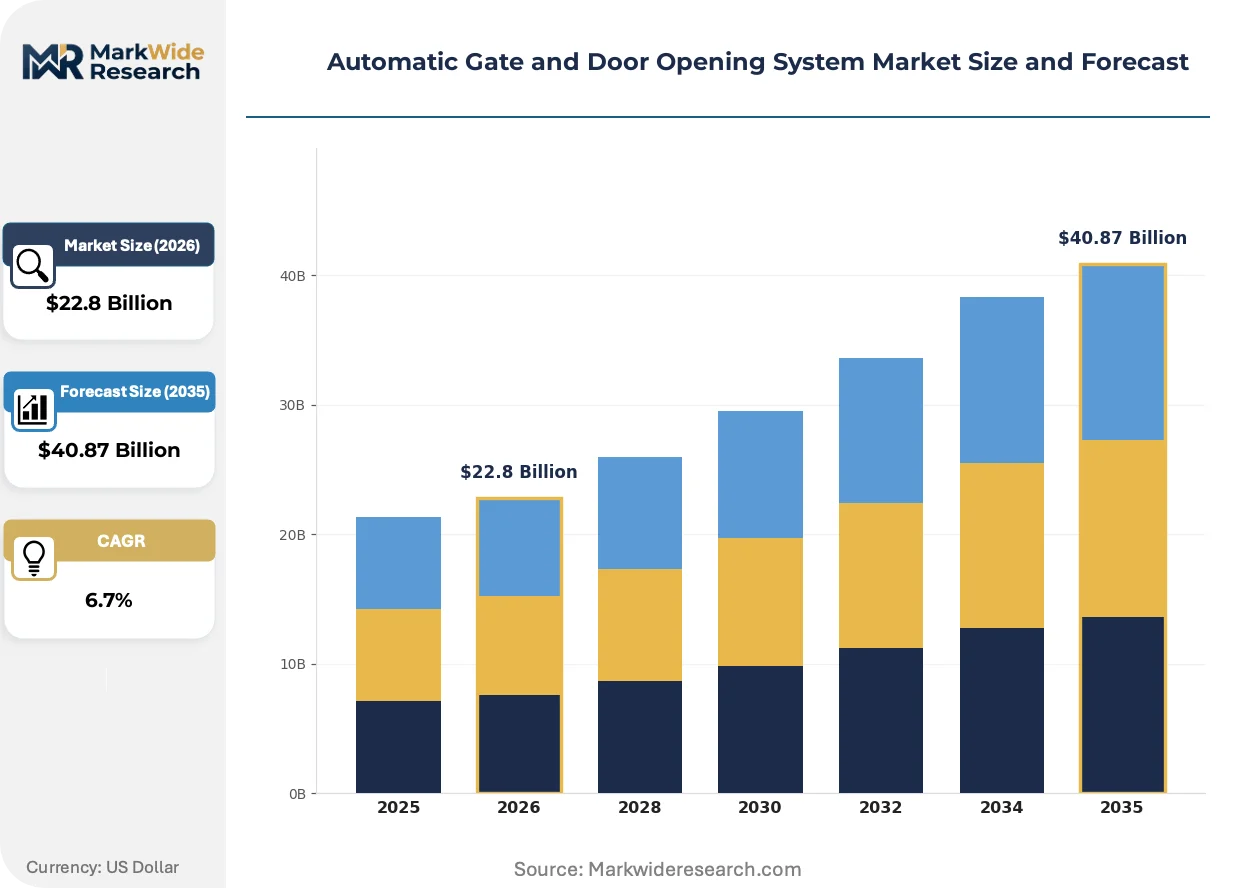
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swing Gate Operators, Sliding Gate Operators, Barrier Gate Operators, Garage Door Openers, Pedestrian Door Operators, Revolving Door Operators Technology: Infrared Sensors, Radio Frequency Identification, Bluetooth, Ultrasonic Sensors, Magnetic Sensors, Motion Detectors Application: Residential Premises, Commercial Facilities, Institutional Buildings, Hospitality Venues, Warehousing Units, Entertainment Complexes End User: Property Management Companies, Security Firms, Logistics Providers, Facility Maintenance Services, Event Management Agencies, Retail Chains |
| Companies Covered | Chamberlain Group, Assa Abloy, FAAC S.p.A., Nice S.p.A., BFT S.p.A., LiftMaster, DoorKing, CAME, Allegion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Gate and Door Opening System Market Strategic Shifts & Innovations
A fundamental shift from standalone automation to interconnected access ecosystems defines the market's trajectory. This evolution prioritizes data, connectivity, and energy performance, moving beyond simple motorized operation to create intelligent, responsive entry points for buildings and facilities.
Advanced sensor fusion, combining technologies like infrared beams with microwave or radar, provides more reliable and nuanced presence detection. High-security sites and industrial facilities are the primary adopters of this technology for enhanced safety and operational accuracy. This sensor fusion capability is expanding into high-traffic commercial and premium residential applications, enabling more sophisticated entrapment protection and false-trigger avoidance.
The European Union's Machinery Directive continues to be a powerful force influencing global product design. This regulation's emphasis on comprehensive risk assessment and documented safety features forces manufacturers to engineer higher levels of operational reliability. Gate and door operators intended for public-access commercial properties are most affected, prompting redesigns that incorporate redundant safety circuits and self-monitoring capabilities.
Demand patterns are evolving from one-time hardware purchases toward service-oriented models, particularly in the commercial real estate sector. This disrupts the traditional channel of selling through installers and distributors, as building managers seek comprehensive access control solutions bundled with maintenance and software updates. This trend is most visible in major metropolitan markets in North America and Western Europe.
Automatic Gate and Door Opening System Market Segmentation
Understanding the automatic gate and door opening system market through segmentation reveals distinct demand drivers and technological preferences across various applications. This analysis highlights how product design, technology integration, and end-user requirements shape competitive strategies and market penetration. Different segments respond uniquely to regulatory pressures and operational efficiency needs.
Product Type:
Product types range from highly standardized residential units to custom-engineered industrial solutions, reflecting diverse operational demands and traffic volumes.
- Sliding Gate Operators:These systems utilize a motor to move a gate horizontally along a track, ideal for properties with limited swing space. Demand concentrates in commercial facilities and warehousing units in Germany, driven by high-cycle requirements.
- Garage Door Openers:Electromechanical devices automate the opening and closing of overhead garage doors, commonly found in residential and light commercial settings. North American residential markets show strong demand, fueled by smart home integration and convenience.
- Swing Gate Operators:Motors actuate gates that pivot on hinges, suitable for properties with ample opening clearance.
- Barrier Gate Operators:These operators control a horizontal arm for vehicle access management, frequently used in parking lots and toll booths.
- Pedestrian Door Operators:Systems automate hinged or sliding doors for foot traffic, enhancing accessibility in public and commercial buildings.
- Revolving Door Operators:These specialized operators manage rotating doors, optimizing energy efficiency and traffic flow in high-rise buildings.
Most installed capacity flows through Garage Door Openers. Expansion is steepest in Sliding Gate Operators.
Technology:
Technology selection is heavily influenced by the application's specific security, convenience, and operational efficiency requirements, from basic presence detection to advanced access control.
- Radio Frequency Identification:RFID technology uses electromagnetic fields to automatically identify and track tags attached to objects or people, enabling hands-free access. Commercial and industrial facilities, particularly in the United States, adopt RFID for secure, high-throughput access management.
- Infrared Sensors:These sensors detect presence or motion using infrared light, providing fundamental safety and activation functions for automatic doors and gates. Public-access commercial properties in Europe depend on infrared for reliable entrapment protection, adhering to the Machinery Directive.
- Bluetooth:Bluetooth connectivity enables short-range wireless control from mobile devices, enhancing user convenience in residential settings.
- Ultrasonic Sensors:Ultrasonic sensors emit sound waves to detect objects, offering an alternative for presence detection in various door systems.
- Magnetic Sensors:These sensors detect the opening or closing state of a door or gate, crucial for system status monitoring and security.
- Motion Detectors:Motion detectors activate door systems upon detecting movement, commonly used for automatic pedestrian doors in retail environments.
Infrared Sensors demonstrate the highest installed base for safety functions. Adoption rates for Radio Frequency Identification are climbing fastest in industrial applications.
Application:
Application segments differentiate by the volume of traffic, security needs, and environmental conditions, dictating the required system durability and feature set.
- Warehousing Units:These facilities require robust, high-cycle gate and door systems to manage constant inbound and outbound logistics traffic. Demand is strong in major logistics hubs across the United States and Germany, driven by e-commerce expansion.
- Commercial Facilities:This segment includes offices, retail stores, and public buildings, demanding systems that balance security, aesthetics, and accessibility. European commercial properties prioritize energy-efficient solutions to comply with the EPBD.
- Residential Premises:Homeowners seek convenience and security from automatic gate and garage door systems, often integrating with smart home platforms.
- Institutional Buildings:Schools, hospitals, and government facilities require reliable, secure access solutions with specific safety and compliance features.
- Hospitality Venues:Hotels and resorts utilize automated doors for guest convenience and aesthetic appeal, often with integrated access control.
- Entertainment Complexes:Theaters, stadiums, and amusement parks employ automated entry systems to manage large crowds efficiently and securely.
Commercial Facilities currently attract significant investment for advanced systems. Warehousing Units show the most rapid expansion in new installations.
End User:
End-user categories reflect distinct purchasing priorities and decision-making influences, from large-scale property portfolio management to specialized security integration.
- Logistics Providers:These companies operate extensive distribution networks, requiring integrated, high-performance automated systems for efficient cargo movement and facility security. Their procurement decisions heavily favor durability and IoT-enabled predictive maintenance features.
- Property Management Companies:These entities manage diverse real estate portfolios, seeking scalable and compliant automatic door solutions for tenant satisfaction and operational efficiency. They prioritize systems with remote management capabilities and long-term service contracts.
- Security Firms:Security firms integrate automatic gate and door systems into broader access control solutions for their clients, emphasizing robust security protocols.
- Facility Maintenance Services:These providers manage the upkeep and repair of automated systems, valuing ease of maintenance and reliable component availability.
- Event Management Agencies:Agencies use temporary or permanent automated access for crowd control and ticketing at various events, focusing on rapid deployment.
- Retail Chains:Retailers deploy automated doors for customer convenience and store security, often seeking energy-efficient and aesthetically pleasing models.
Logistics Providers prioritize total cost of ownership and operational uptime. Property Management Companies seek integrated solutions offering remote oversight and compliance adherence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automatic gate and door opening system market scaled significantly with the advent of industrial automation and the expansion of logistics infrastructure. Early adoption in developed economies established foundational demand for efficient access solutions. This historical trajectory continues to influence regional growth patterns and technological advancements.
United States
The United States experiences strong demand for automated door systems, driven by e-commerce expansion and modern warehousing units. UL 325 safety standards strictly govern product design, ensuring high entrapment protection. Logistics hubs in California are rapidly deploying high-cycle sliding gate operators for increased throughput.
Germany
Germany's market benefits from advanced industrial automation and central European logistics hubs, driving demand for robust systems. The EU Machinery Directive mandates stringent safety features, while EPBD drives energy-efficient solutions. Industrial zones around Munich prioritize durable hydraulic operators for high-traffic commercial gates.
France
France demonstrates consistent demand for automated access systems across commercial facilities and public buildings, emphasizing security and accessibility. CE marking requirements ensure products meet high European safety standards. Urban development projects in the Île-de-France region integrate pedestrian door operators for enhanced traffic flow.
China
China's rapid manufacturing expansion and vast logistics infrastructure fuel significant demand for automated gate and door systems. National GB standards guide system design and deployment, ensuring local compliance and performance. Major manufacturing clusters in the Pearl River Delta adopt advanced sensor fusion for enhanced operational accuracy.
India
India's accelerating infrastructure development and burgeoning e-commerce sector drive automated access solutions for new commercial and warehousing projects. Bureau of Indian Standards (BIS) certifications are increasingly important for product quality and safety. Metropolitan areas like Bengaluru see a rise in smart home-integrated garage door openers for residential premises.
Automatic Gate and Door Opening System Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the automatic gate and door opening system market, creating a tiered competitive structure. The market exhibits consolidation among established manufacturers offering extensive product portfolios, alongside numerous specialized regional players. Strategic archetypes include global integrators, niche technology innovators, and regional service providers. Portfolio diversification and strategic partnerships are dominant competitive moves for market participants.
Within the global integrator archetype, Assa Abloy exemplifies a diversified portfolio approach, serving both commercial and residential sectors with a broad range of access solutions. The Chamberlain Group, a US-based entity, represents specialization in smart home-integrated garage door openers, anchoring its position in the North American residential market. Italy-based FAAC S.p.A. occupies a position as a specialist in durable hydraulic operators, particularly for high-traffic commercial gates in European markets.
| Leading Market Players |
|---|
| Chamberlain Group |
| Assa Abloy |
| FAAC S.p.A. |
| Nice S.p.A. |
| BFT S.p.A. |
| LiftMaster |
| DoorKing |
| CAME |
| Allegion |
| Others |
Cost & Logistics Intelligence
Vertical integration into critical electronic component manufacturing anchors supply positions for larger players, influencing their ability to dictate pricing across specialized system tiers. This strategic control enhances their market stability and competitive advantage.
Pricing Analysis
Value-based pricing dominates for complex industrial and commercial installations, reflecting specialized engineering and compliance with standards like UL 325. Price differentiation stems from certification level and system durability requirements for high-cycle applications. Pricing pressure stems from component supply volatility, pushing system costs upward. Residential buyers for smart home integration exhibit lower price sensitivity compared to small commercial enterprises seeking basic functionality.
Supply Chain Analysis
Single-source vulnerability sits with specialized electronic component manufacturers, particularly for microcontrollers and advanced sensors sourced predominantly from East Asia. The supply chain relies on these critical inputs and precision-engineered mechanical parts from European industrial centers. Component supply volatility represents a significant structural risk. Distribution runs through a network of certified installers and value-added distributors, with an emerging shift towards direct service contracts for commercial real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage exists as differing regulatory burdens, such as the EU's EPBD demanding thermal insulation versus US markets prioritizing UL 325 safety features, create distinct demand profiles. This divergence offers opportunities for targeted market entry and product specialization.
For Market Incumbents: To counter the threat of specialized IoT solution providers, established manufacturers must deepen their vertical integration into advanced sensor development. Consolidating smaller software firms specializing in building management system integration will enhance their connected product portfolios. Investment in CE marking and UL 325 certification processes remains critical for market access.
For New Entrants and Emerging Players: Enter via specialized retrofit solutions targeting energy efficiency compliance in European commercial facilities. The most penetrable segment for new players involves upgrading older systems to meet EPBD standards. A strong go-to-market angle involves offering bundled installation and long-term maintenance contracts for these upgrades.
For Investors and Strategic Acquirers: Roll-up economics work for regional service providers because of the fragmented installation and maintenance market. Long-term viability rests on integrated offerings that combine hardware, software, and recurring service revenue streams. A key signal to watch is the increasing uptake of predictive maintenance subscriptions across commercial portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Advanced Sensor Fusion Systems | These systems enhance safety and operational accuracy in high-traffic commercial and industrial settings. |
| Platform Integration: Smart Home Ecosystems | Native support for major smart home platforms appeals to North American residential consumers. |
| Acquisition of Specialist Firm: IoT Software Developer | Acquiring software expertise accelerates the shift towards interconnected access ecosystems and data services. |
| Geographic Expansion: Emerging Logistics Hubs | Targeting new warehousing units in India and Southeast Asia capitalizes on e-commerce growth. |
| Service Model Innovation: Predictive Maintenance Subscriptions | Shifting towards recurring revenue streams beyond hardware sales enhances customer lifetime value. |
Research Approach
Bottom-up warehousing unit and residential premises modeling reconciled against top-down component manufacturer and system integrator tracking forms the analytical core. Primary interviews with logistics providers, property management companies, and system integrators validated secondary data from industry association reports, national building codes, and company filings. This approach ensured a robust triangulation of market estimates.
An input-output matrix framework projected market evolution across the analysis window, segmenting by product type, technology, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends, projected market penetration, and new installation forecasts. Key forecast inputs included e-commerce expansion rates and smart home technology adoption.
Inputs from industry association reports and regulatory filings were available through the study window; gaps in granular regional adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and stable regulatory environments. Unforeseen supply chain disruptions or significant shifts in building codes could revise these projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Canada Access Control Market