
 North America Bath Remodeling Market | 2026-2036
North America Bath Remodeling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bath Remodeling Market Analysis
Multifamily property renovation is realigning demand patterns across the North America bath remodeling landscape. Kohler leverages its vertically integrated ceramics manufacturing to command premium positioning in specification-grade installations. The Home Depot anchors mass-market accessibility through dense retail distribution and proprietary private-label bath collections. Ferguson competes on contractor channel control, sustaining deep relationships with professional installers across metropolitan building markets.
North America bath remodeling encompasses the design, demolition, and replacement of residential bathroom fixtures, surfaces, plumbing systems, and ventilation elements to improve functionality, water efficiency, and aesthetic value. Typical projects involve moisture-resistant substrate preparation, waterproofing membrane application, and installation of fixtures rated to ASME A112 performance standards for drainage and supply integrity. Showers and vanities lead product-type revenue contribution, with frameless glass enclosures and floating vanity configurations capturing disproportionate margin pools. Acrylic dominates volume in bathtub replacements due to favorable weight-to-durability ratios, while natural stone surfaces concentrate in luxury homeowner segments where material differentiation commands pricing premiums.
The Environmental Protection Agency WaterSense program and Department of Energy appliance efficiency standards constrain fixture flow rates, directly shaping manufacturer R&D priorities and product line rationalization. State-level plumbing codes adopted from International Plumbing Code variants across Texas, Florida, and California create fragmented compliance landscapes that favor regionally adaptive distributors. Builders and contractors must monitor evolving lead-time dynamics for imported ceramic and glass components while positioning installation capacity ahead of seasonal demand surges.
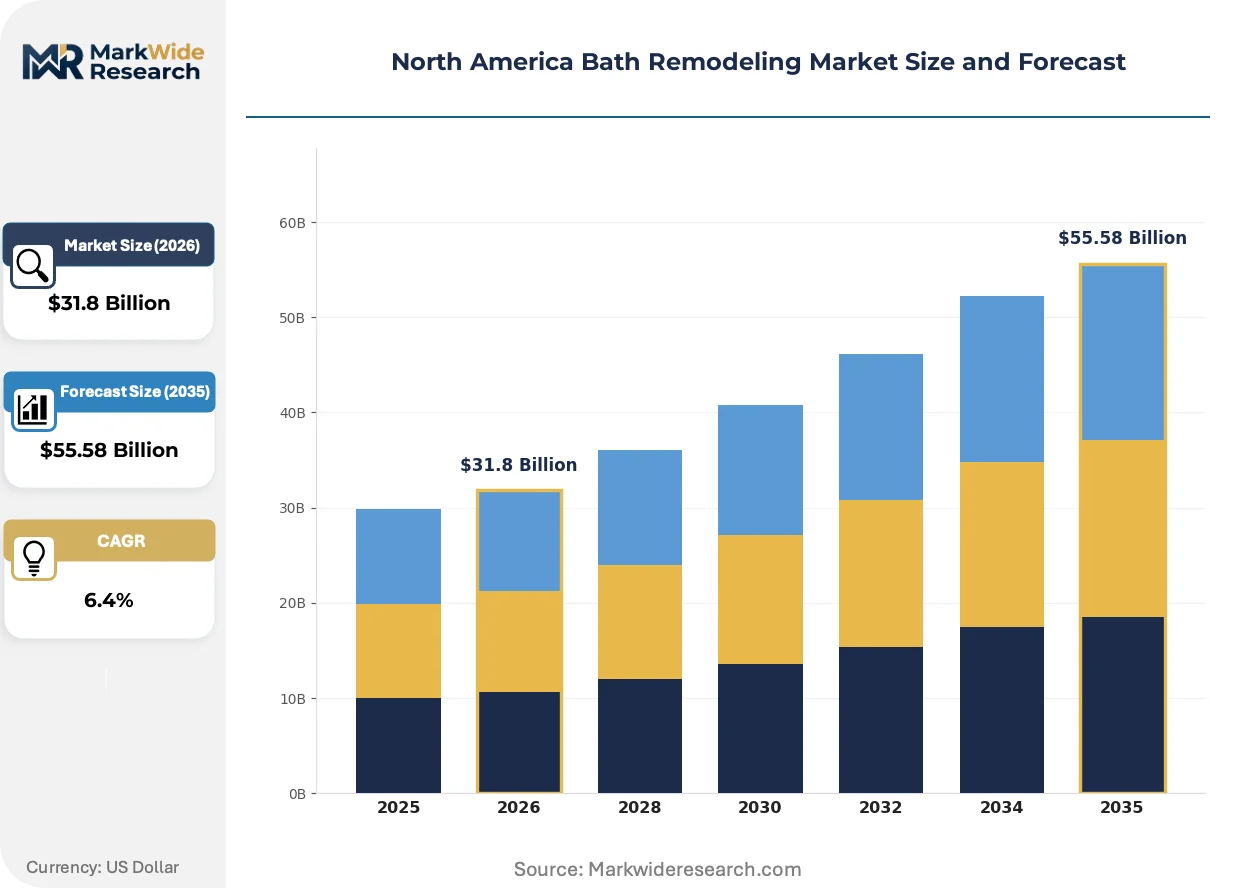
Market Dynamics
The North America bath remodeling market is being fundamentally restructured by the Environmental Protection Agency WaterSense certification mandates, which are forcing manufacturers to redesign entire fixture portfolios while creating compliance-driven segmentation between certified and non-certified product lines.
Growth Catalysts
- WaterSense Certification Mandates:The Environmental Protection Agency's flow-rate restrictions on faucets and showerheads are compelling homeowners to replace older fixtures, generating replacement demand that bypasses new construction cyclicality.
- Aging Housing Stock:The United States inventory of homes exceeding 40 years of age is concentrating renovation spending in wet-area upgrades where moisture damage and outdated plumbing create urgent functional imperatives.
- Sun Belt Migration Patterns:Residential turnover in Florida, Texas, and Arizona is sustaining elevated project volumes as inbound households renovate purchased properties and developers accelerate new multifamily construction.
Market Restraints
- Ceramic Import Concentration:Heavy reliance on overseas ceramic tile and glass component suppliers exposes contractors to volatile ocean freight lead times and tariff uncertainty.
- Skilled Labor Scarcity:The shortage of certified plumbers and waterproofing specialists in metropolitan building markets is elongating project timelines and compressing installer margins.
- Code Fragmentation:State-level adoptions of International Plumbing Code variants across Texas, Florida, and California create compliance complexity that favors large distributors with regional adaptation capabilities.
Strategic Opportunities
- Smart Fixture Convergence:Integration of digital temperature controls with WaterSense-compliant hardware is opening premium price tiers in the United States renovation segment.
- Multifamily Renovation Cycles:Institutional ownership of rental housing in Sun Belt states is creating programmatic refresh demand independent of homeowner discretionary spending.
- Modular Wet-Room Systems:Prefabricated waterproof substrate assemblies are reducing on-site skilled labor requirements and compressing installation schedules for contractor adoption.
Industry Challenges
- Waterproofing Certification Gaps:Inconsistent training standards for membrane application across state licensing boards is elevating callback risk and insurance costs for installation contractors.
- Supply Chain Reconfiguration:Shifting from just-in-time ceramic sourcing to domestic inventory buffers is demanding working capital expansion that strains mid-sized distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bath Remodeling Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanities, Showers, Bathtubs, Faucets Material: Porcelain, Acrylic, Glass, Stone End User: Homeowners, Contractors, Designers, Builders Installation Type: Complete Remodel, Partial Remodel, DIY, Professional |
| Companies Covered | Re-Bath, Lowe’s, Kohler, Ferguson, American Standard Bath, Jacuzzi Bath Remodel, The Home Depot, BathWraps, Bath Fitter, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bath Remodeling Market Emerging Trajectories
Digital control systems and prefabricated assembly methods are compressing traditional installation timelines while regulatory pressure on water efficiency is redefining product specification criteria across residential renovation channels.
Smart thermostatic valve technology is integrating digital temperature management with flow restriction compliance. High-end homeowners in the United States are specifying these systems at accelerating rates. This convergence is integrating hardware and software supply chains that previously operated independently.
The Environmental Protection Agency WaterSense program is tightening certification requirements for showerheads and faucets. Manufacturers must now maintain dual product lines or abandon non-compliant inventory. The luxury segment is responding fastest, using certification as a competitive differentiator in specification-grade projects.
Homeowner purchasing patterns are fragmenting across retail channels. Mass-market buyers are migrating toward big-box private-label collections while premium segments demand direct-to-contractor specification services. This bifurcation is most pronounced in Texas and Florida metropolitan markets where contractor density supports specialized distribution models.
North America Bath Remodeling Market Segmentation
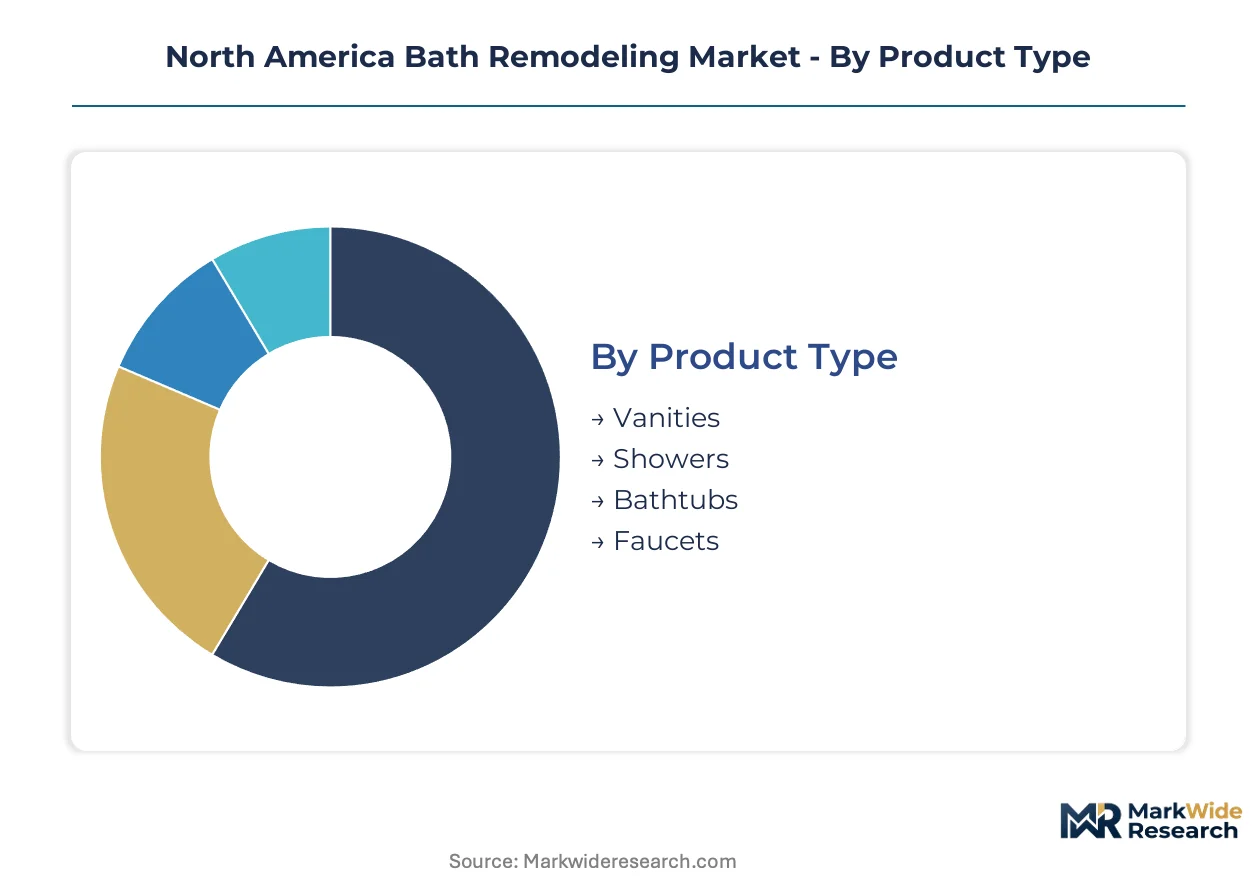
WaterSense certification requirements from the EPA reshape product specifications differently across each segment, creating compliance-driven price tiers that separate certified from non-certified offerings. Understanding where regulatory burden concentrates helps identify which segments command premium positioning and which face margin compression from redesign costs.
Product Type:
EPA WaterSense flow-rate restrictions apply most stringently to showerheads and faucets, while vanities face minimal direct regulatory burden but carry indirect compliance through integrated sink fixtures.
- Showers:Frameless glass enclosures and thermostatic valve systems dominate specification-grade projects. Demand clusters in Sun Belt states where Florida and Texas homeowners prioritize walk-in conversions for aging-in-place functionality. WaterSense showerhead mandates accelerate replacement cycles independent of housing turnover.
- Faucets:Aerator technology and ceramic disc cartridges must integrate sub-1.5 gpm flow compliance without sacrificing user experience. California and Texas plumbing codes enforce the strictest adoption timelines, forcing distributors to maintain dual inventory positions.
- Vanities:Floating configurations capture disproportionate margin pools through moisture-resistant substrate engineering. Integrated sink basins must coordinate with WaterSense faucet specifications.
- Bathtubs:Acrylic formulations dominate volume replacements due to favorable weight-to-durability ratios. Freestanding soaking tubs concentrate in luxury segments where material differentiation overrides efficiency mandates.
Showers sit at the top of the volume ranking, with faucets climbing the fastest as regulatory replacement cycles compress refresh timelines.
Material:
Cost tier stratification separates premium natural surfaces from mass-market synthetics, with certification burden falling heaviest on finished goods rather than raw material categories.
- Acrylic:Thermoformed sheets enable seamless tub and shower surround fabrication with consistent waterproofing performance. Texas and Florida contractors specify acrylic for multifamily renovation cycles where installation speed outweighs material prestige.
- Stone:Granite and marble vanity surfaces command pricing premiums through material differentiation and fabrication complexity. Luxury homeowner segments in Arizona and California sustain demand despite weight and sealing maintenance requirements.
- Porcelain:Vitreous china fixtures carry established ASME A112 certification heritage with minimal reformulation risk from evolving efficiency standards.
- Glass:Tempered and laminated configurations for enclosures require coordination with frameless hardware systems. Import concentration from overseas suppliers exposes lead-time volatility.
Acrylic captures the highest installation volume, while stone gains share fastest in premium renovation channels.
End User:
Customer type determines procurement channel access and specification authority, with professional intermediaries controlling product selection in high-value projects.
- Contractors:Licensed plumbers and general renovation specialists filter homeowner choices through established distributor relationships. Ferguson and specialized supply houses in metropolitan Texas and Florida markets capture specification control.
- Homeowners:Direct purchasers gravitate toward big-box retail accessibility and private-label collections. The Home Depot anchors mass-market volume through dense distribution and financing programs.
- Builders:Production home developers standardize fixture packages across subdivision portfolios, negotiating volume pricing that bypasses retail markup structures.
- Designers:Interior specification professionals source through to-the-trade showrooms for custom residential projects where aesthetic coordination overrides cost minimization.
Contractors command the largest project value flow, with builders expanding most quickly through Sun Belt multifamily construction.
Installation Type:
Project scope and labor sourcing create distinct margin structures, with professional complete remodels capturing full value chain participation while DIY segments sacrifice warranty coverage for cost reduction.
- Professional:Certified installer networks execute complete wet-area gut renovations with permit compliance and waterproofing warranty coverage. Skilled labor scarcity in Arizona and Florida metropolitan markets elongates scheduling backlogs.
- Complete Remodel:Full demolition and substrate replacement projects generate highest per-project revenue through fixture, surface, and labor bundling. Aging housing stock across the United States concentrates demand in homes exceeding 40 years.
- Partial Remodel:Surface-level refresh projects limit disruption and cost exposure while postponing structural plumbing upgrades. Countertop and fixture replacement without waterproofing membrane work dominates this segment.
- DIY:Homeowner self-installation concentrates in accessory replacement and cosmetic upgrades where code compliance and warranty transferability matter less.
Professional installation represents the dominant value capture mode, with complete remodels gaining share fastest as deferred maintenance accumulates in aging housing inventory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit regulatory-arbitrage opportunities by concentrating production in jurisdictions where EPA WaterSense compliance costs align with local enforcement capacity. Canada and Mexico capture spillover demand from U.S. housing stock pressures while offering alternative certification pathways.
United States
Aging housing inventory exceeding 40 years concentrates renovation spending in Sun Belt metros where Florida, Texas, and Arizona contractors face acute skilled labor shortages. EPA WaterSense mandates accelerate fixture replacement cycles independent of discretionary housing turnover. Dallas-Fort Worth and Phoenix anchor the fastest-growing installation clusters as inbound migration sustains multifamily renovation pipelines.
Canada
Cross-border supply chains serve U.S. demand through Ontario-based ceramic and acrylic fabricators benefiting from tariff-advantaged trade flows. Natural Resources Canada efficiency standards create parallel but less stringent compliance frameworks than EPA requirements. Toronto and Vancouver metropolitan areas concentrate specification-grade distribution serving high-end residential segments.
Mexico
Maquiladora operations near the U.S. border produce acrylic tub and shower surround components for American big-box retailers seeking cost-competitive volume supply. Mexican federal environmental standards lack WaterSense-equivalent flow-rate mandates, reducing reformulation burdens for export-focused manufacturers. Monterrey and Tijuana industrial corridors anchor ceramic and glass component assembly for North American distribution.
North America Bath Remodeling Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated fixture producers commanding premium positioning while retail private-label collections capture mass-market volume. The market structures around three tiers: specification-grade specialists with contractor channel control, big-box retailers with dense distribution networks, and regional installation franchises with localized service coverage. Consolidation pressure concentrates among mid-scale fabricators facing working capital demands from inventory buffering. Strategic moves center on backward integration into ceramic production and exclusive distribution partnerships with professional installer networks.
Within the premium-tier vector, Kohler anchors specification-grade positioning through captive ceramics manufacturing. Ferguson occupies a position as the dominant contractor-channel distributor across Sun Belt metropolitan markets. The Home Depot exemplifies mass-market accessibility through proprietary private-label bath collections and consumer financing programs.
| Leading Market Players |
|---|
| Re-Bath |
| Lowe's |
| Kohler |
| Ferguson |
| American Standard Bath |
| Jacuzzi Bath Remodel |
| The Home Depot |
| BathWraps |
| Bath Fitter |
| Others |
Supply Flow & Price Mechanics
Prefabricated wet-room system adoption simultaneously compresses installation labor costs and concentrates procurement power among large-scale fabricators with captive acrylic production. This production-method transition elevates margin capture for vertically integrated specialists while forcing mid-tier distributors to absorb working capital strain from inventory buffering against ceramic import volatility.
Pricing Analysis
Distributor margin layering separates specification-grade showroom channels from big-box retail markups, with WaterSense certification premiums adding tiered pricing separation between compliant and legacy inventory. Price differentiation hinges on certification grade and brand positioning, with cost compression in mass-market acrylic fixtures intensifying due to private-label expansion. Professional contractors exhibit lowest price sensitivity through bundled project economics, while DIY homeowners drive aggressive retail discounting.
Supply Chain Analysis
Direct-to-contractor channels handle professional installer demand through Ferguson and specialized supply houses, while big-box retail serves homeowner self-selection. Manufacturing concentrates in Mexico, China, and domestic Ohio-based ceramics corridors. Raw material dependencies include petroleum-based acrylic resins, imported vitreous china, and tempered glass components. Tariff exposure on ceramic tile and glass imports creates persistent margin risk for distributors without domestic sourcing alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American bath remodeling has matured into a late-cycle quality story where aging-in-place functionality and WaterSense compliance command sustained premium positioning over commodity replacement cycles.
For Market Incumbents: Hedge ceramic import concentration by securing domestic acrylic fabrication partnerships or captive substrate production in Mexico border zones. Defend specification-channel control through exclusive WaterSense-certified product lines that lock contractor loyalty against emerging direct-to-installer digital platforms. For New Entrants and Emerging Players: Direct-to-contractor e-commerce routes offer the most penetrable vector for bypassing established distributor relationships in Texas and Florida metropolitan markets. Target multifamily property management procurement offices with modular wet-room system catalogs and installation scheduling software integration. For Investors and Strategic Acquirers: Valuations sit cheapest among regional installation franchises with localized service density but undifferentiated brand positioning. Long-term viability favors targets with backward integration into waterproofing membrane production or exclusive smart-thermostatic valve distribution rights. Monitor EPA WaterSense enforcement tightening as the signal for accelerated replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Production | Captive resin supply insulates margin from petroleum volatility and Mexico tariff exposure. |
| Smart Fixture Certification Investment | EPA WaterSense compliance opens premium pricing tiers in specification-grade renovation channels. |
| Contractor Channel Exclusive Distribution | Ferguson-style professional installer relationships lock specification authority against retail displacement. |
| Modular Wet-Room System Launch | Prefabricated assemblies reduce skilled labor dependency and compress project timelines for multifamily adoption. |
| Sun Belt Metropolitan Expansion | Florida, Texas, and Arizona migration sustains elevated project volumes independent of national housing cyclicality. |
Methodological Framework
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market through structured interviews with bathroom fixture procurement managers, licensed plumbing contractors, multifamily property developers, and big-box retail category buyers. Secondary validation drew from EPA WaterSense certification databases, customs import records for ceramic and glass components, and building permit filings in Sun Belt metropolitan statistical areas. Bottom-up project volume estimates triangulated against top-down manufacturer shipment data.
Granularity-level modeling disaggregated the market across product type, material formulation, end-user procurement channel, and installation scope dimensions throughout the forecast period. CAGRs derived from regression analysis of housing stock age distributions, regulatory compliance timelines, and regional migration patterns. Industry-specific inputs included WaterSense adoption curve assumptions and skilled labor availability indices in target metropolitan markets.
Ceramic import tariff escalations, EPA enforcement intensity variations, and multifamily construction financing availability are the dominant revision risks to base-case projections. Forecasts reflect documented assumptions regarding housing turnover rates and regulatory compliance cost pass-through. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Residential Construction Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Siding Market
Residential Construction
Europe Manufactured Homes Market