
 Saudi Arabia Vinyl Flooring Market | 2026-2036
Saudi Arabia Vinyl Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Vinyl Flooring Market Analytics
The split between premium and commodity tiers is hardening as luxury vinyl tiles command thicker wear layers and extended warranties while standard vinyl sheets compete on bulk project pricing. Tarkett leverages European manufacturing standards to anchor its position in high-specification hospitality fit-outs. Abdul Rahman Al Shareef Group competes through extensive local distribution networks serving contractor channels across the Kingdom. Mohawk Industries differentiates via rigid core technology leadership that targets moisture-prone installation environments.
Saudi Arabia vinyl flooring comprises synthetic polymer-based surfacing materials, typically constructed from polyvinyl chloride resins combined with plasticizers, stabilizers, and printed decorative layers, manufactured through calendering or extrusion processes to achieve specified thicknesses and wear resistance ratings. The material serves primarily as a cost-effective, water-resistant alternative to natural wood and stone in high-traffic commercial and residential environments. Luxury vinyl tiles now capture the strongest margin pools as specification-grade projects demand realistic embossing and enhanced dimensional stability. Click-lock installation methods are gaining share among residential renovators seeking reduced labor dependency and faster project completion.
SASO mandates product conformity assessments for all imported flooring materials, while the Saudi Building Code enforces fire resistance and indoor air quality standards that filter out lower-grade imports. The Ministry of Municipal and Rural Affairs and Housing oversees material approvals for government-backed construction programs, creating a dual-track compliance environment. Stakeholders must monitor evolving eco-label requirements and local content incentives as the Kingdom advances industrial localization targets.
Market Dynamics
Red Sea coastal hotel construction is compressing project timelines and forcing specification-grade vinyl flooring procurement into accelerated qualification cycles that favor pre-certified suppliers.
Growth Catalysts
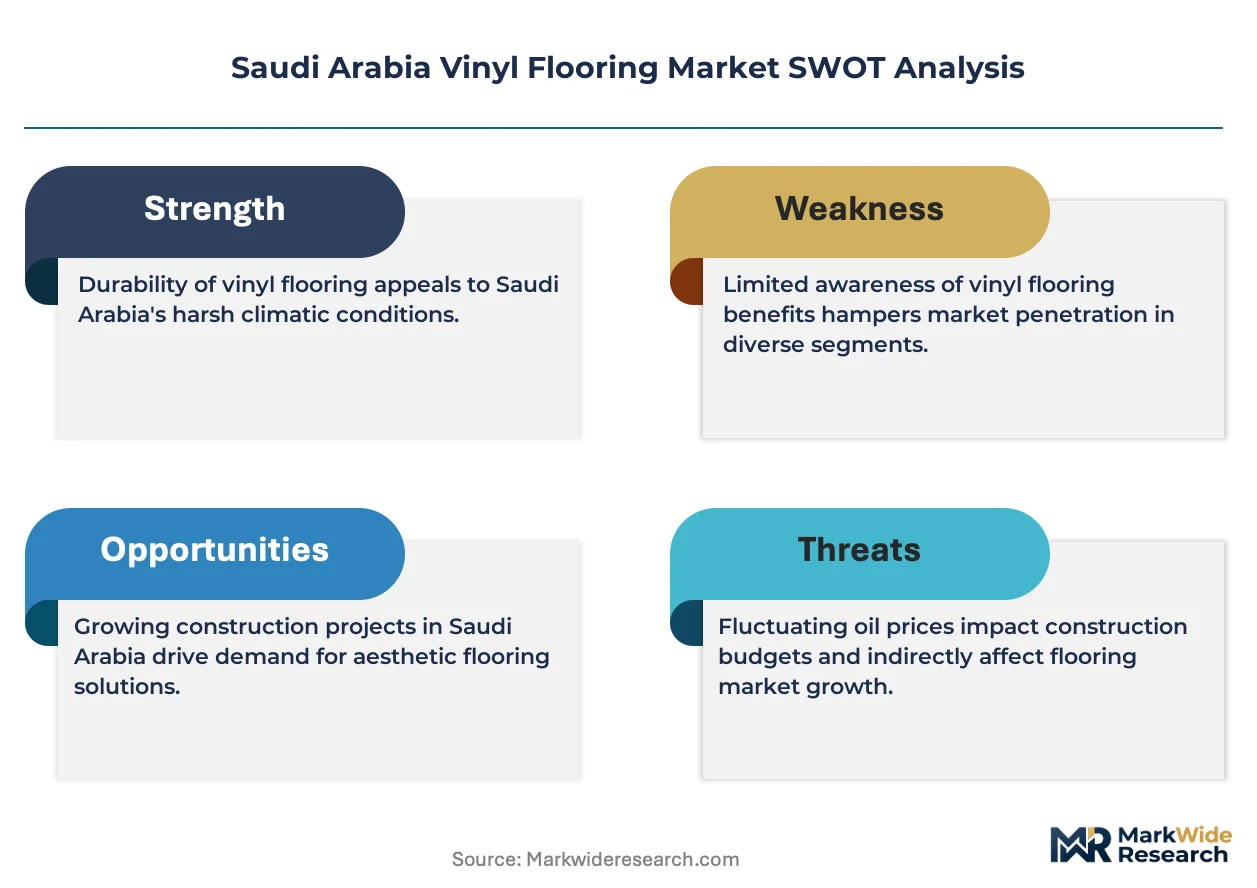
- SFDA Material Conformity Pathway:Streamlined SASO certification processes for pre-approved European manufacturers are reducing time-to-market for hospitality fit-out materials.
- Red Sea Project Pipeline:Giga-project developments including NEOM and Amaala are generating concentrated demand for moisture-resistant rigid core flooring in coastal environments.
- Calendering Process Advances:Thicker wear layer production capabilities at 0.55mm and above are enabling extended warranty offerings that differentiate premium specification tiers.
Market Restraints
- Plasticizer Cost Volatility:Phthalate and bio-based plasticizer input costs fluctuate with petrochemical feedstock pricing, compressing margin stability for domestic compounders.
- Import Concentration Risk:European and East Asian suppliers control 70% plus of high-specification LVT feedstock, exposing projects to shipping lane disruption and currency fluctuation.
- Fire Resistance Technical Ceiling:Current PVC formulations face hard limits in achieving Class A surface burning ratings without mineral filler loading that degrades embossing fidelity.
Strategic Opportunities
- Tabuk Residential Corridor:Northern province housing initiatives remain undersupplied with certified vinyl flooring distributors, creating first-mover positioning for logistics-capable entrants.
- Local Content Incentive Alignment:Ministry of Investment industrial localization credits are creating offset pathways for manufacturers establishing compounding or finishing operations within special economic zones.
- Click-Lock Residential Channel:DIY renovation demand in Jeddah's established neighborhoods is opening specialty retailer partnerships that bypass traditional contractor-dominated distribution.
Industry Challenges
- SASO Certification Timeline Compression:Laboratory testing queues for fire performance and VOC emissions documentation currently extend 14-18 weeks, misaligning with fast-track construction schedules.
- Moisture Barrier Integration Complexity:Rigid core products require substrate moisture testing protocols that many Saudi contractor crews lack training to execute consistently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Vinyl Flooring Market |
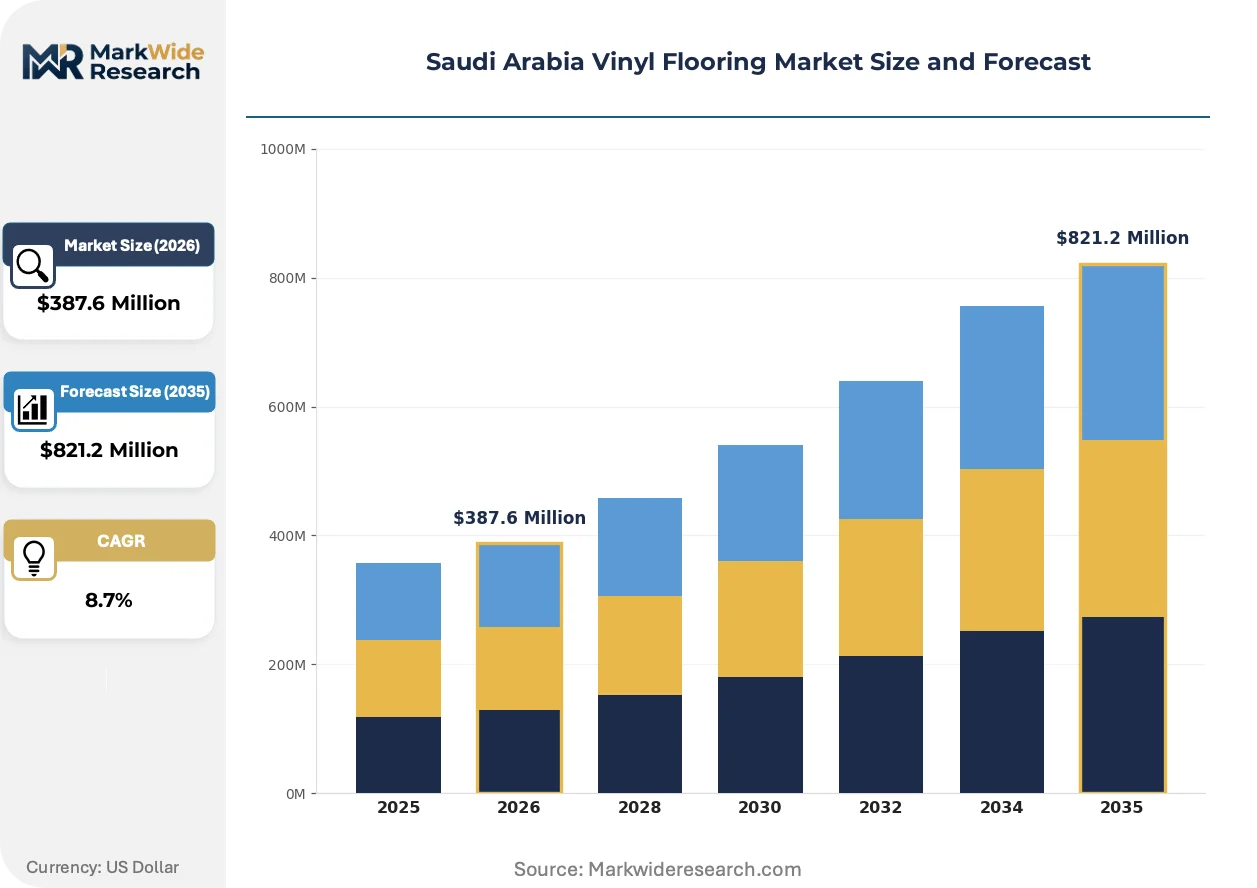
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tiles, Vinyl Sheets, Vinyl Planks, Printed Vinyl End User: Residential, Commercial, Industrial, Hospitality Thickness: 3mm, 4mm, 5mm, 6mm Installation Method: Glue-Down, Floating, Click-Lock, Loose Lay |
| Companies Covered | Shaw Industries, Forbo Flooring Systems, Tarkett, Abdul Rahman Al Shareef Group, Polyflor, Gerflor, Mohawk Industries, Al Souriya, Armstrong Flooring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Vinyl Flooring Market Evolving Landscape
Specification-grade flooring procurement is fragmenting across three parallel vectors: installation labor reduction, regulatory compliance automation, and aesthetic fidelity advancement.
Digital embossing technology is overtaking mechanical cylinder printing in luxury vinyl tile production. Hospitality designers specify registered emboss patterns that align with printed wood grain for realistic tactile feedback. Major Red Sea resort developers now mandate this technology in finish schedules, compressing demand for conventional printed sheet vinyl.
SASO's expanded VOC emission testing protocols under the Saudi Building Code are filtering import portfolios. Manufacturers must submit chamber test documentation for formaldehyde and total volatile organic compound release. Residential distributors report 30% of prior Asian supply sources failing revised thresholds, redirecting procurement toward European-certified production lines.
Contractor channel consolidation in Riyadh's commercial district is compressing project bidding cycles. Large fit-out firms now maintain pre-approved vendor lists with locked pricing tiers, displacing open tender processes. This concentration favors suppliers with dedicated Saudi specification teams and local inventory positioning over export-only competitors.
Saudi Arabia Vinyl Flooring Market Segmentation
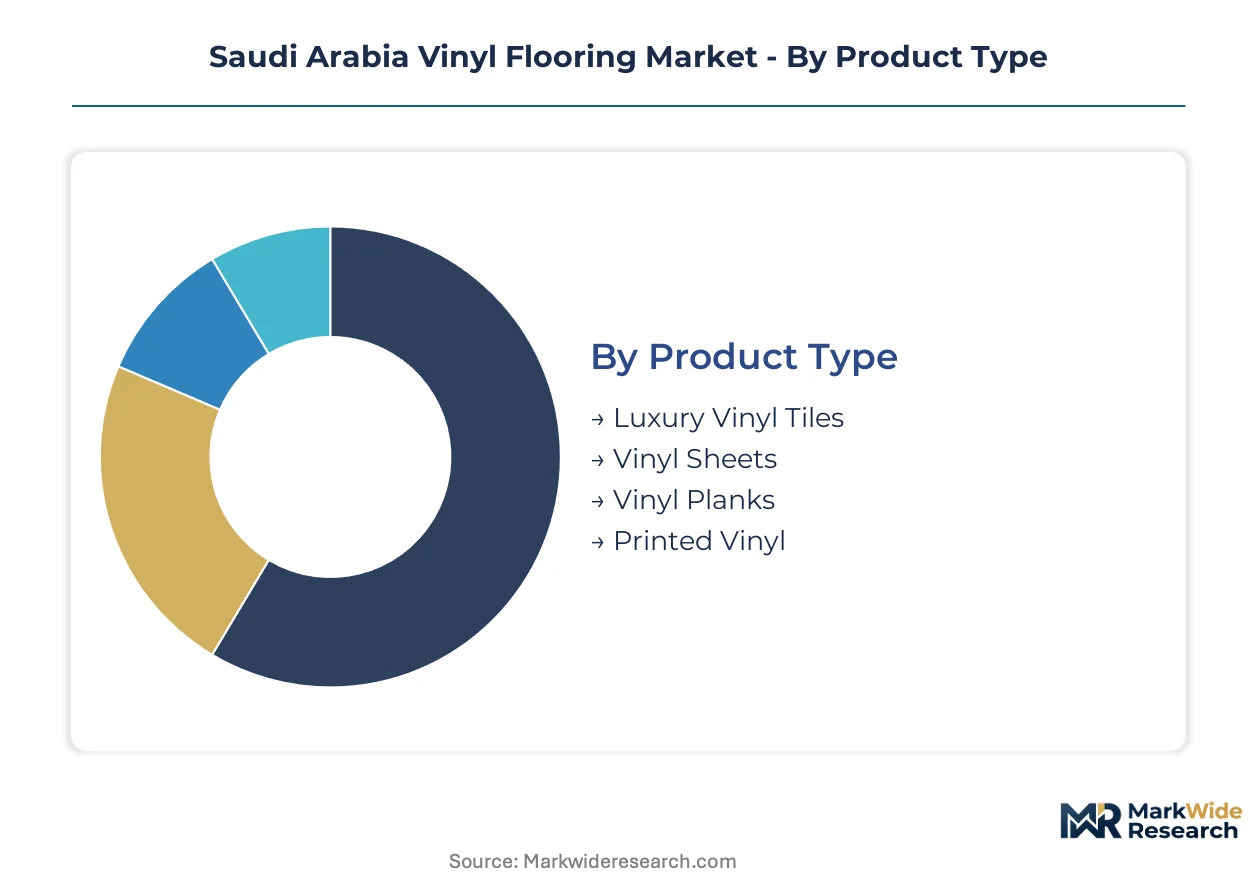
Vinyl flooring procurement in Saudi Arabia fragments across performance tiers, installation complexity, and project scale. Specification-grade buyers prioritize wear layer thickness and SASO certification alignment, while residential renovators weight click-lock convenience against unit economics.
Product Type:
Material construction and surface embossing fidelity separate hospitality specification from bulk contractor procurement.
- Luxury Vinyl Tiles:Multi-layer rigid core construction with registered emboss patterns delivers dimensional stability for Red Sea coastal humidity. NEOM and Amaala resort developers mandate this format for guest room and corridor applications where realistic wood grain replication commands premium positioning.
- Vinyl Sheets:Homogeneous or heterogeneous rolled goods manufactured through calendering processes serve healthcare and education sectors requiring seamless moisture barriers. Jeddah hospital renovation pipelines favor welded sheet installations for infection control compliance.
- Vinyl Planks:Narrow-format strips with beveled edges target residential living spaces seeking hardwood aesthetics at reduced cost.
- Printed Vinyl:Surface-printed economy-grade material competes on bulk project pricing for temporary installations and budget housing.
Volume sits with Vinyl Sheets; growth tilts toward Luxury Vinyl Tiles.
End User:
Project timeline compression and warranty duration requirements distinguish institutional buyers from individual consumers.
- Residential:Individual homeowners and multi-unit developers in Riyadh's northern expansion corridors drive click-lock format adoption. Jeddah's established neighborhoods generate renovation demand where DIY installation reduces labor dependency.
- Commercial:Office fit-outs in Riyadh's King Abdullah Financial District require 0.55mm wear layers for 15-year warranty compliance. Pre-approved vendor lists maintained by large fit-out firms filter supplier access.
- Industrial:Warehouse and logistics facilities prioritize chemical resistance and static control properties over aesthetic specifications.
- Hospitality:Red Sea coastal hotel construction compresses qualification cycles toward pre-certified European suppliers. Tarkett and specification-grade competitors anchor positioning through extended warranty offerings.
Commercial captures current procurement volume; hospitality climbs the fastest as giga-project timelines accelerate.
Thickness:
Structural stability and acoustic performance trade against material cost and freight economics.
- 3mm:Thin-profile glue-down sheets serve renovation overlays where existing substrate height constraints limit installation options.
- 4mm:Entry-level rigid core construction balances dimensional stability with price positioning for mid-market residential applications.
- 5mm:Intermediate thickness dominates hospitality specification where underfoot comfort and sound transmission ratings influence designer selection.
- 6mm:Maximum-profile rigid core targets high-traffic commercial environments requiring superior impact resistance and longest warranty terms.
4mm and 5mm configurations split current volume; 6mm gains specification share fastest as warranty competition intensifies.
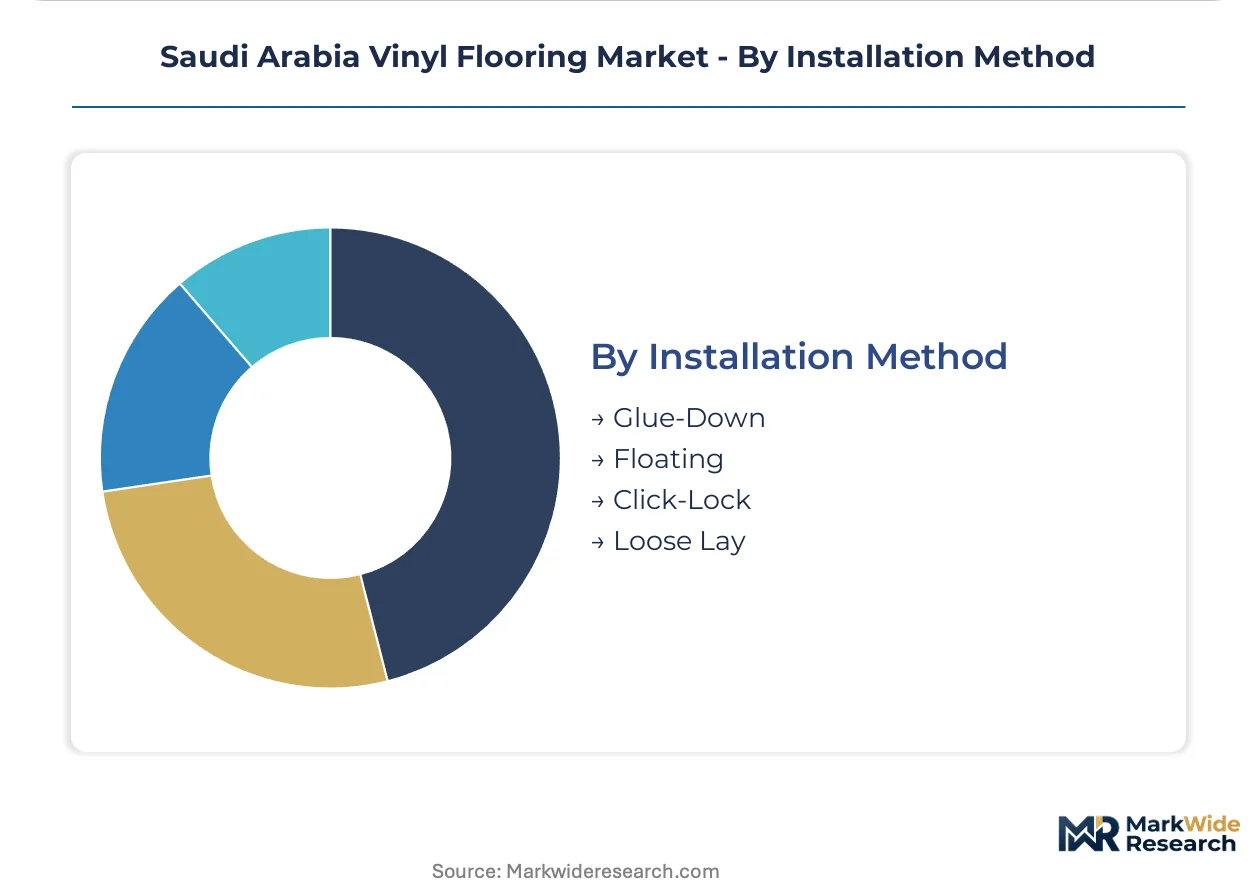
Installation Method:
Labor skill availability and substrate preparation requirements determine contractor format preference.
- Glue-Down:Full-spread adhesive application demands skilled crews and extended curing timelines. Healthcare and education sectors accept this complexity for seamless performance.
- Floating:Interlocking perimeter systems without adhesive accommodate uneven substrates common in Saudi residential construction.
- Click-Lock:Mechanical locking edges enable rapid installation with reduced labor dependency. Riyadh contractor crews increasingly specify this format to compress project schedules.
- Loose Lay:Friction-backed sheets rely on perimeter weighting for stability, serving temporary installations and rapid renovation cycles.
Glue-Down retains institutional volume; Click-Lock expands most quickly through residential channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors Saudi Arabia's vinyl flooring procurement through King Abdullah Financial District office fit-outs and Ministry of Municipal and Rural Affairs housing programs. The capital's contractor networks concentrate specification-grade demand for extended-warranty products.
Riyadh
Commercial district developments and government-backed housing initiatives drive bulk procurement of 5mm-6mm rigid core products. SASO certification requirements filter supplier access through extended laboratory testing timelines. King Abdullah Financial District fit-out firms maintain pre-approved vendor lists that compress bidding cycles toward established distributors.
Eastern Province
Industrial logistics facilities and petrochemical complex expansions generate demand for chemical-resistant sheet vinyl installations. The Ministry of Investment's industrial localization incentives attract compounders considering special economic zone establishment. Dammam's contractor channels serve Jubail industrial city renovation pipelines with homogeneous welded sheet specifications.
Western Region
Jeddah's residential expansion corridors and established neighborhood renovation activity concentrate click-lock format adoption. DIY installation trends open specialty retailer partnerships that bypass traditional contractor-dominated distribution. The city's port infrastructure handles European and East Asian import volumes subject to SFDA material conformity assessments.
NEOM Northwest
Red Sea coastal giga-projects including Amaala and THE LINE generate accelerated qualification cycles for moisture-resistant rigid core flooring. Hospitality developers mandate registered emboss patterns and extended warranties that favor pre-certified European suppliers. Compressed construction timelines force procurement toward distributors with local inventory positioning.
Saudi Arabia Vinyl Flooring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and warranty duration. The vendor base stratifies between European manufacturers anchoring hospitality specification and regional distributors serving contractor bulk procurement. Three archetypes dominate: European specification-grade specialists, Gulf-based logistics-intensive distributors, and global multi-product flooring conglomerates. Competitive moves concentrate on SASO pre-certification investments and local inventory positioning to compress delivery timelines.
Within the European specification tier, Tarkett and Forbo Flooring Systems represent pre-certified manufacturing standards that align with Red Sea resort developer mandates. Abdul Rahman Al Shareef Group occupies a position among Kingdom-based distributors with extensive contractor channel coverage. Mohawk Industries exemplifies technology-focused positioning through rigid core product lines targeting moisture-prone coastal environments.
| Leading Market Players |
|---|
| Shaw Industries |
| Forbo Flooring Systems |
| Tarkett |
| Abdul Rahman Al Shareef Group |
| Polyflor |
| Gerflor |
| Mohawk Industries |
| Al Souriya |
| Armstrong Flooring |
| Others |
Value Network & Pricing Analysis
Captive compounding operations in European manufacturing bases anchor supply positioning for Saudi specification-grade procurement while insulating premium-tier producers from petrochemical feedstock volatility that compresses margin pools for non-integrated compounders. This upstream control translates directly into pricing power over hospitality developers at Red Sea giga-projects who mandate extended warranties and SASO pre-certification.
Pricing Analysis
Warranty-duration anchoring separates premium specification tiers from commodity procurement in Saudi vinyl flooring markets. Three-tier pricing structure across premium, standard, and economy levels reflects wear layer thickness, SASO certification alignment, and embossing fidelity rather than unit volume alone. Cost compression in standard-grade sheet vinyl intensifies as Asian manufacturers compete on bulk project tenders for government housing programs. Contractor channels serving Riyadh commercial fit-outs exhibit lowest price sensitivity due to pre-approved vendor list structures that lock in specification-grade sourcing.
Supply Chain Analysis
Freight economics from Belgian and German port origins to Jeddah anchor total landed cost structures for European specification-grade manufacturers serving Red Sea hospitality developments. Raw material dependencies center on PVC resin feedstocks from German and Dutch petrochemical complexes, phthalate and bio-based plasticizer compounds, and mineral fillers sourced from regional GCC suppliers. Single-source vulnerability concentrates in 0.55mm-plus wear layer production capabilities where calendering equipment investments exceed entry thresholds. Distribution runs through Kingdom-based logistics-intensive distributors with Riyadh and Jeddah inventory positioning that compresses qualification-to-delivery timelines for fast-track construction schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi vinyl flooring market is a vertical-integration race where captive compounding operations and local finishing capacity determine qualification access to giga-project procurement pipelines. Players are pursuing backward integration into PVC resin sourcing and calendering equipment ownership to secure margin pools and SASO certification autonomy.
For Market Incumbents: Lock in specification-grade positioning by acquiring or long-term contracting calendering capacity above 0.55mm wear layer thresholds that NEOM and Amaala developers now mandate. Defend against emerging Asian manufacturers by pre-positioning inventory in Jeddah bonded warehouses to compress delivery timelines below 14-day windows that compressed construction schedules demand. Channel control through Riyadh fit-out firm pre-approved vendor lists remains the critical defensive lever.
For New Entrants and Emerging Players: E-commerce specialty retail partnerships targeting Jeddah's DIY renovation segment bypass contractor-dominated distribution that European incumbents anchor. Tabuk residential corridor logistics gaps create first-mover positioning for distributors with cold-chain and humidity-controlled warehousing capabilities that rigid core products require. White-space penetration should prioritize click-lock format adoption among northern province housing developers underserved by current certification-capable supply bases.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap distributors with SASO pre-certification portfolios and established contractor channel relationships rather than manufacturing assets alone. Long-term viability over the next decade hinges on localization credits alignment with Ministry of Investment industrial zone incentives. The signal to watch is SASO laboratory testing queue compression below 10 weeks, which would eliminate the qualification bottleneck currently protecting incumbent positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Compounding | Captive resin production insulates margin pools from petrochemical feedstock volatility affecting European supply. |
| SASO Pre-Certification Investment | Pre-approved status compresses hospitality qualification cycles from 18 weeks toward 8-week competitive windows. |
| Local Inventory Positioning | Jeddah and Riyadh warehousing enables 72-hour delivery commitments that fast-track Red Sea construction demands. |
| Click-Lock Format Development | Mechanical locking systems reduce Saudi contractor crew skill dependencies and accelerate residential project completion. |
| Registered Emboss Technology Licensing | Digital emboss alignment with printed grain patterns meets NEOM developer mandates for realistic tactile specification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with flooring specification consultants, hospitality procurement directors, SASO certification laboratory managers, and Riyadh commercial fit-out firm project managers provided demand-side validation. Secondary sources included Saudi Building Code documentation, Ministry of Municipal and Rural Affairs housing program specifications, SFDA material conformity assessment records, and European flooring manufacturer technical datasheets. Bottom-up project pipeline enumeration across NEOM, Amaala, and King Abdullah Financial District developments triangulated against top-down construction sector expenditure estimates.
Segment-level modeling addressed product type, end-user sector, thickness configuration, and installation method dimensions across the projection horizon. CAGRs derived from fitted growth curves applied to verified 2026 baseline values, with hospitality sector trajectories weighted against Red Sea giga-project timeline acceleration signals. Industry-specific inputs incorporated SASO certification queue duration trends, calendering capacity expansion announcements, and plasticizer compound pricing indices.
The model holds under sustained giga-project construction velocity and stable SASO regulatory frameworks; deviation in Ministry of Investment localization incentive intensity or Red Sea shipping lane disruption would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and contingency planning for qualification timeline compression or feedstock cost volatility scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Decorative Rugs Market